
 Unit Load Device Market | 2026-2036
Unit Load Device Market Size, Share, and Industry Trends Forecast 2026-2036
Unit Load Device Market Analysis
Composite materials are displacing conventional aluminum in container ULD fabrication and is realigning weight-to-payload economics across long-haul fleets. Unilode Aviation Solutions leverages its pooled fleet model to sustain asset utilization rates above industry norms. TransDigm Group Incorporated anchors its position through captive control of critical latching and restraint mechanisms. DoKaSch GmbH specializes in temperature-controlled solutions that command premium positioning in pharmaceutical lanes.
A unit load device is a pallet or container used to consolidate baggage, mail, and cargo for loading onto wide-body and narrow-body aircraft, typically constructed to IATA-standard dimensions with tare weights ranging from 50 kg for lightweight pallets to over 1,200 kg for refrigerated containers. These devices interface directly with aircraft cargo handling systems and ground support equipment to minimize turnaround times and maximize volumetric efficiency. Container ULDs capture the dominant share of pharmaceutical and express cargo volumes where environmental sealing justifies higher asset costs. Composite material segments are expanding fastest as airlines seek fuel burn reductions through lower tare weights. Aluminum retains volume leadership in pallet ULDs where structural simplicity and repairability dominate procurement criteria.
The FAA mandates fire suppression and smoke detection standards for all ULDs operated on US-registered aircraft, while EASA enforces parallel certification requirements across European Union member states. IATA publishes ULD technical standards that harmonize interoperability between airline fleets and ground handling equipment worldwide. Stakeholders must monitor evolving sustainability mandates from the EU Green Deal and emerging airworthiness directives from China's CAAC as these frameworks will reshape material qualification pathways and fleet renewal cycles.
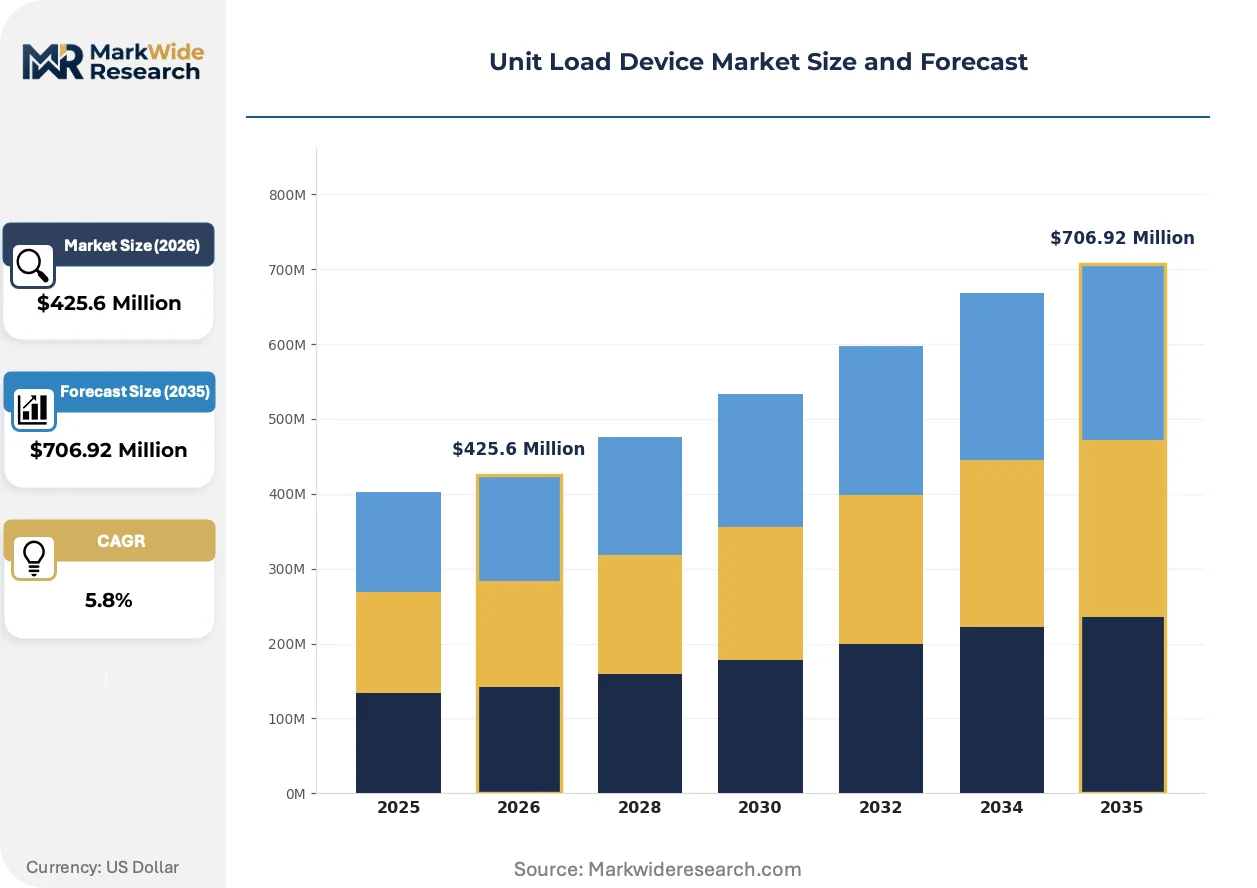
Market Dynamics
Composite material substitution is compressing tare weights across long-haul fleets while FAA and EASA fire-resistance mandates accelerate fleet renewal cycles among cargo operators.
Growth Catalysts
- EU Green Deal sustainability mandates:Airlines in Germany and France face escalating pressure to reduce fuel burn through lighter ULD assets, directly benefiting composite pallet adoption.
- Pharmaceutical cold chain expansion:Temperature-controlled container demand from vaccine and biologics logistics is pulling refrigerated ULD procurement above fleet replacement rates.
- Leipzig cargo hub concentration:DHL's European air freight operations anchor procurement volumes that sustain manufacturer order backlogs through cyclical downturns.
Market Restraints
- Carbon fiber supply concentration:Advanced composite feedstock depends on Japanese and German precursor manufacturers, exposing ULD fabricators to input cost volatility and allocation constraints.
- EASA certification timeline friction:Extended airworthiness validation for novel material formulations delays revenue recognition by 18-24 months for innovative product introductions.
- Aluminum pallet repairability:MRO networks favor dent-and-bend recovery of legacy metal assets over composite replacement, slowing material transition at second-tier airlines.
Strategic Opportunities
- India pharmaceutical export corridors:Temperature-controlled ULD penetration remains below 15% at Mumbai and Hyderabad cargo terminals, creating whitespace for specialized container deployment.
- Blockchain-IoT convergence:Real-time cargo condition monitoring integrated with immutable chain-of-custody records commands premium pricing in high-value pharmaceutical lanes.
- US Inflation Reduction Act clean manufacturing incentives:Domestic composite fabrication facilities qualify for production tax credits that narrow cost gaps with Asian imports.
Industry Challenges
- Composite repair technician scarcity:MRO facilities lack certified personnel for carbon fiber damage assessment and restoration, extending asset downtime.
- Multi-regulatory certification burden:Simultaneous FAA, EASA, and CAAC validation requirements fragment engineering resources and prolong product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unit Load Device Market |
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $706.92 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard ULD, Pallet ULD, Container ULD, AKE ULD Material: Aluminum, Composite, Steel, Plastic End User: Airlines, Ground Handling, Cargo Operators, Freight Forwarders Size: LD-3, LD-6, LD-9, LD-11 |
| Companies Covered | ACL Airshop, Unilode Aviation Solutions, TransDigm Group Incorporated, Palnet GmbH Air Cargo Products, VRR Aviation, Satco Inc., DoKaSch GmbH, CSafe Global, Safran S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unit Load Device Market Emerging Trajectories
Digital tracking integration and material science advances are compressing asset lifecycles while elevating performance specifications across pharmaceutical and express cargo segments.
Thermoplastic composite formulations are converging with automated fiber placement manufacturing to produce unit load devices with 30% lower tare weights than legacy aluminum equivalents. Cargo operators at Frankfurt and Amsterdam Schiphol have accelerated adoption timelines for these assets on Asia-Europe trunk routes. The technology is converging with predictive maintenance platforms that model fatigue life from operational stress data, enabling condition-based retirement rather than calendar-driven replacement.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in temperature-controlled ULDs, forcing manufacturers toward CO2 and hydrocarbon-based cooling systems. This transition compresses engineering development cycles as dual-certificate products must satisfy both legacy and emerging standards during the overlap period. Pharmaceutical logistics providers operating under EMA GDP guidelines face the steepest compliance burden, driving consolidation toward certified fleet operators with dedicated technical resources.
Asset pooling arrangements are displacing dedicated fleet ownership among mid-tier cargo carriers seeking to reduce capital intensity and improve utilization rates. Unilode Aviation Solutions and similar providers now capture maintenance and tracking responsibilities that airlines previously managed in-house. This shift concentrates most visibly among European express operators serving e-commerce volumes with irregular seasonal peaks.
Unit Load Device Market Segmentation
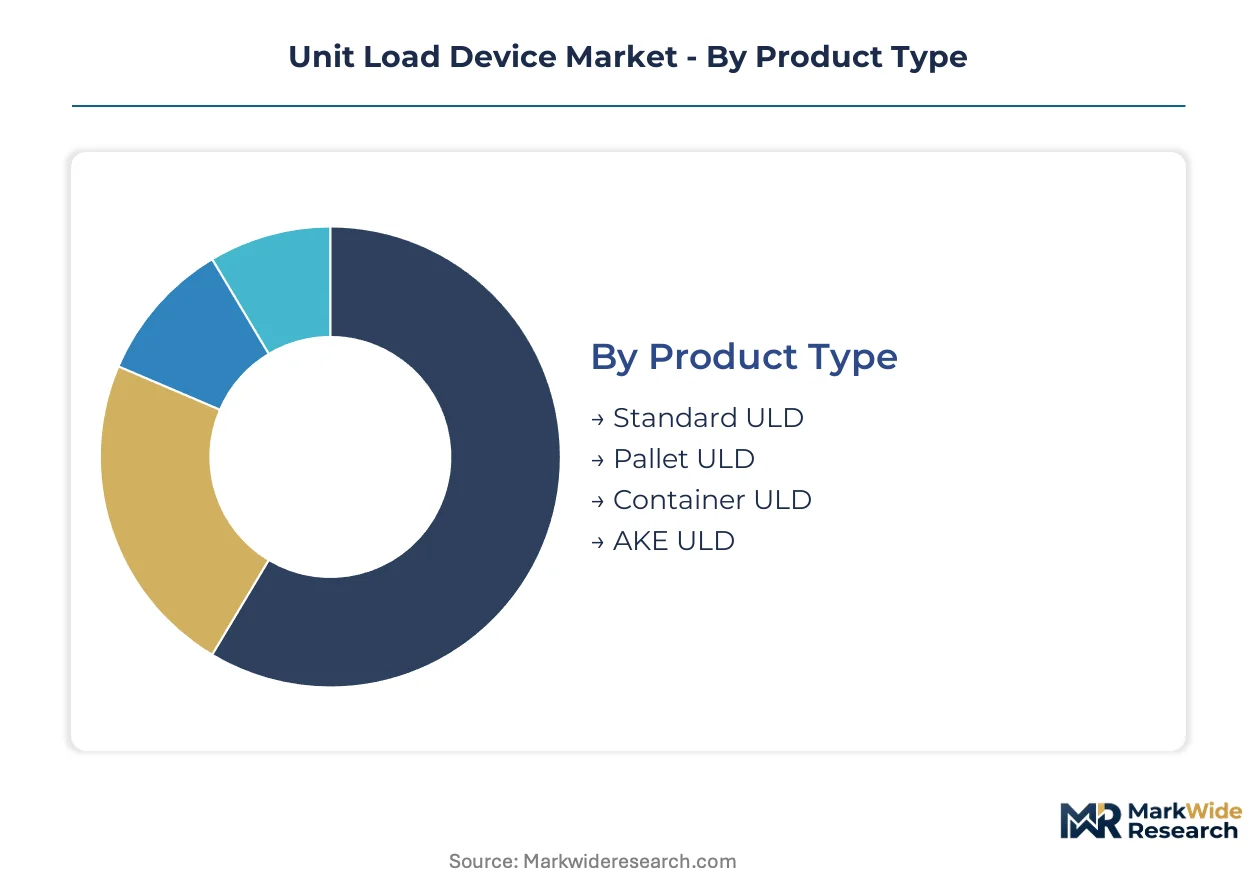
ULD segmentation reveals divergent procurement logic across asset types and operational contexts. Product architecture, material composition, and end-user scale each create distinct performance thresholds and replacement cycles.
Product Type:
Container ULDs operate as standalone environmental systems with integrated sealing and climate control, while pallet ULDs embed directly into aircraft cargo floors as passive load-bearing platforms.
- Container ULD:Fully enclosed structures with rigid walls and doors protect pharmaceutical and express cargo from contamination and temperature excursions. Frankfurt and Leipzig cargo terminals anchor concentrated procurement for temperature-controlled variants serving vaccine distribution lanes.
- Pallet ULD:Flat load-bearing platforms with net restraint systems dominate general cargo and baggage handling where repairability outweighs weight savings. Aluminum construction retains procurement preference among MRO networks favoring dent-and-bend recovery over composite replacement.
- Standard ULD:Generic-purpose assets without specialized climate or containment features serve cost-sensitive operators on short-haul routes.
- AKE ULD:Lower-deck container format optimized for narrow-body aircraft bellies, constrained by dimensional limits of Boeing 737 and Airbus A320 families.
Container ULD leads volumes today; composite-enhanced variants are gaining share fastest.
Material:
Material selection hinges on trade-offs between tare weight reduction, damage tolerance, and regulatory fire-resistance certification timelines.
- Composite:Carbon fiber and thermoplastic formulations achieve 30% weight reduction versus aluminum equivalents. FAA and EASA fire-resistance mandates accelerate fleet renewal among cargo operators seeking fuel burn reductions on Asia-Europe trunk routes.
- Aluminum:Legacy metal alloys dominate pallet fabrication where structural simplicity and field repairability sustain procurement preference. MRO technician scarcity for composite damage assessment reinforces aluminum's position at second-tier airlines.
- Steel:Heavy-duty applications requiring maximum impact resistance, constrained by weight penalties on fuel-sensitive long-haul operations.
- Plastic:Emerging formulations for lightweight, corrosion-resistant niche applications with limited thermal performance.
Aluminum retains installed base dominance; composite segments are expanding most quickly.
End User:
Procurement scale and technical sophistication vary sharply between asset owners and service intermediaries.
- Cargo Operators:Integrated carriers with dedicated freighter fleets drive temperature-controlled ULD specification and volume procurement. DHL's European air freight operations sustain manufacturer order backlogs through cyclical downturns.
- Airlines:Passenger carriers with belly cargo operations prioritize standardization and interchangeability across mixed fleets. Asset pooling arrangements displace dedicated ownership among mid-tier carriers seeking capital intensity reduction.
- Ground Handling:Service providers at major hubs manage ULD positioning and maintenance without direct procurement authority.
- Freight Forwarders:Intermediaries rely on carrier-provided equipment, exerting indirect influence through pharmaceutical lane certification requirements.
Cargo operators anchor premium segment procurement; airlines are consolidating toward pooled fleet models.
Size:
Dimensional standards reflect aircraft type compatibility and volumetric efficiency optimization across fuselage geometries.
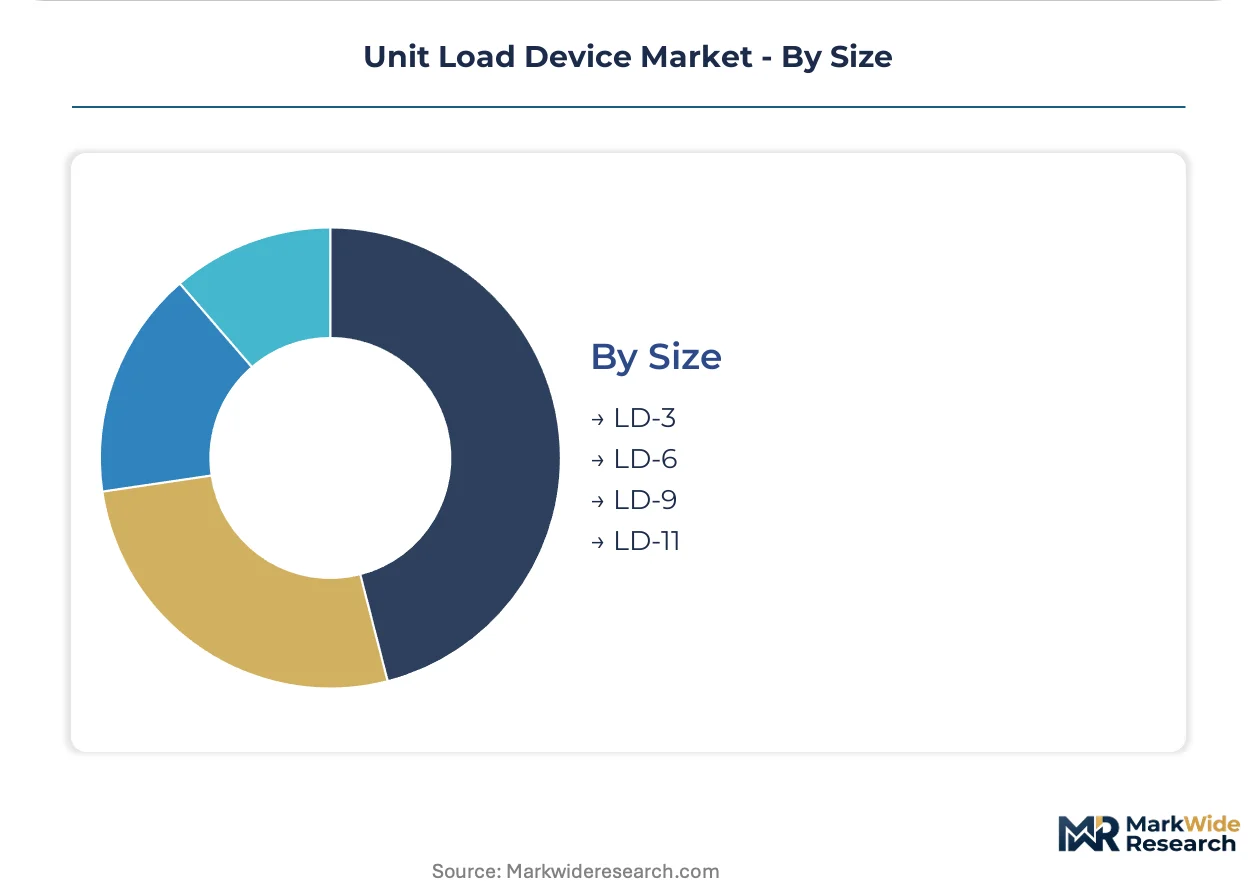
- LD-3:Half-width lower-deck container compatible with wide-body aircraft, the workhorse format for pharmaceutical and express cargo. Frankfurt and Amsterdam Schiphol operations specify LD-3 for maximum interchangeability across Boeing 777 and Airbus A350 fleets.
- LD-6:Full-width lower-deck container doubling LD-3 capacity on main deck positions, constrained by loading system compatibility.
- LD-9:Full-width main deck container for dedicated freighter operations, limited to Boeing 747 and 777F configurations.
- LD-11:Specialized main deck format for specific freighter conversions with restricted fleet penetration.
LD-3 dominates operational deployment; LD-6 is climbing fastest among express carriers maximizing main deck utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt and Leipzig anchor concentrated ULD procurement volumes serving pharmaceutical distribution lanes across Europe. Cargo hub density in Germany drives specification standards that radiate outward to connected markets. Regulatory frameworks from multiple jurisdictions reshape material qualification pathways and fleet renewal cycles.
Germany
DHL's European air freight operations sustain manufacturer order backlogs through cyclical downturns at Leipzig-Halle Airport. The EU Green Deal mandates escalating fuel burn reductions that push Lufthansa Cargo toward composite pallet adoption on Asia-Europe trunk routes. Frankfurt Airport anchors the continent's largest pharmaceutical cargo hub, concentrating temperature-controlled ULD specification authority.
United States
FAA fire suppression and smoke detection standards accelerate fleet renewal among cargo operators serving express e-commerce volumes. The Inflation Reduction Act's clean manufacturing incentives narrow cost gaps for domestic composite fabrication facilities. Memphis and Louisville cargo terminals concentrate procurement scale for overnight delivery networks.
China
CAAC emerging airworthiness directives reshape material qualification pathways for manufacturers supplying domestic airline fleets. Dual carbon goals pressure operators toward lighter tare weight assets on long-haul international routes. Shanghai Pudong and Beijing Capital cargo terminals drive specification for pharmaceutical export corridors.
India
Temperature-controlled ULD penetration remains below 15% at Mumbai and Hyderabad cargo terminals, creating whitespace for specialized container deployment. The PLI scheme incentivizes domestic manufacturing of aerospace components including ULD structural elements. Pharmaceutical export growth from Gujarat and Maharashtra clusters pulls refrigerated asset demand above replacement rates.
Netherlands
Amsterdam Schiphol operations specify LD-3 containers for maximum interchangeability across mixed Boeing and Airbus fleets. EASA certification timelines for novel composite formulations delay revenue recognition for innovative product introductions. The Randstad logistics corridor concentrates European distribution planning for temperature-sensitive biologics.
Unit Load Device Market Vendor Landscape
Global majors compete with regional champions across certification authority and fleet pooling scale. The vendor base organizes around three tiers: integrated aviation conglomerates with captive ULD divisions, specialized container fabricators with pharmaceutical lane expertise, and pooled fleet operators managing asset utilization across multiple carriers. Strategic moves concentrate on composite material partnerships with aerospace suppliers and vertical integration into MRO networks to capture lifecycle value.
Within the pooled fleet operator tier, Unilode Aviation Solutions and ACL Airshop exemplify asset-light models that displace dedicated ownership among mid-tier carriers. Among German-based specialists, DoKaSch GmbH occupies a position in temperature-controlled solutions commanding premium positioning. TransDigm Group Incorporated anchors the component supply vector through captive control of critical latching mechanisms. These three represent distinct competitive archetypes: pooling scale, pharmaceutical specialization, and upstream component dominance.
| Leading Market Players |
|---|
| ACL Airshop |
| Unilode Aviation Solutions |
| TransDigm Group Incorporated |
| Palnet GmbH Air Cargo Products |
| VRR Aviation |
| Satco Inc. |
| DoKaSch GmbH |
| CSafe Global |
| Safran S.A. |
| Others |
Supply Flow & Price Mechanics
Certified composite repair technician pools in Germany and Japan concentrate labor-cost differentials that widen pricing-tier spreads between premium temperature-controlled containers and standard aluminum pallets. MRO networks in Leipzig and Frankfurt command wage premiums that feed into asset leasing rates, while second-tier operators in Eastern Europe and Southeast Asia absorb cost compression through aluminum repairability.
Pricing Analysis
Carbon fiber precursor pass-through from Japanese and German feedstock suppliers compresses margins on composite ULDs faster than aluminum alloy pricing responds to LME movements. Three-tier pricing structure across EASA-certified refrigerated units, fire-resistant composite containers, and standard aluminum pallets reflects certification-grade differentiation and after-sales service bundling. Pricing pressure stems from DHL and Lufthansa Cargo volume consolidation that squeezes mid-tier fabricators on LD-3 container contracts. Express cargo operators show least price sensitivity for pharmaceutical-lane assets; regional baggage handlers face acute cost compression on pallet procurement.
Supply Chain Analysis
EASA and FAA airworthiness qualification gates concentrate supply authority among fabricators with dual-certification engineering teams in Germany and the United States. Carbon fiber prepregs draw from Toray and SGL Carbon facilities in Japan and Germany, while aluminum extrusions source from Hydro and Constellium plants in Norway and the Netherlands. Single-source vulnerability runs through Japanese precursor manufacturers exposed to allocation constraints during aerospace demand surges. Distribution runs through Unilode and ACL Airshop pooled fleet operators that displace direct airline procurement across European and North American hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Unit Load Device Market reads as a late-cycle quality story where pharmaceutical cold chain specifications pull procurement toward EASA-certified refrigerated assets with embedded IoT tracking. Cargo operators at Frankfurt and Leipzig now specify composite-enhanced LD-3 containers as baseline for Asia-Europe trunk routes.
For Market Incumbents: Anchor market position through captive control of MRO networks in Germany and the Netherlands where certified composite technician scarcity creates switching costs. Consolidate latching mechanism supply through backward integration into aerospace-grade hardware fabrication. Defend against pooled fleet operator encroachment by embedding predictive maintenance platforms that extend asset life beyond calendar-based replacement cycles.
For New Entrants and Emerging Players: The EU F-Gas Regulation in Europe opens a window for hydrocarbon-based cooling system specialists to capture refrigerated ULD retrofit demand during the HFC phase-down overlap period. Target India's pharmaceutical export corridors where temperature-controlled penetration at Mumbai and Hyderabad terminals remains below infrastructure investment thresholds. Pursue asset-light pooling partnerships with regional express carriers rather than direct manufacturing scale.
For Investors and Strategic Acquirers: Pooled fleet operators with maintenance and tracking capabilities are the most active acquirer in this space as airlines outsource non-core asset management. Five-to-ten year viability hinges on composite material cost convergence with aluminum and regulatory harmonization across FAA-EASA-CAAC jurisdictions. Watch for CAAC airworthiness directive acceleration as the inflection signal for Chinese domestic fleet renewal cycles and localized supply chain buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Partnership | Toray and SGL Carbon supply agreements secure carbon fiber allocation for EASA-certified container production. |
| MRO Network Acquisition | Certified repair facility purchases in Frankfurt and Amsterdam capture lifecycle value from pooled fleet contracts. |
| IoT-Blockchain Integration | Real-time condition monitoring with immutable custody records commands premium pricing in pharmaceutical lanes. |
| Dual-Certification Engineering Investment | Simultaneous FAA and EASA validation capabilities compress product launch timelines for composite formulations. |
| India Manufacturing Footprint | PLI scheme qualification for aerospace components narrows cost gaps with European fabrication. |
Methodological Framework
Direct dialogue with cargo operations directors at DHL and Lufthansa Cargo, composite fabrication engineers at German ULD manufacturers, MRO facility managers at Frankfurt and Leipzig hubs, and pharmaceutical logistics procurement leads at temperature-controlled freight forwarders grounded qualitative insights. Secondary validation drew from EASA airworthiness directives, FAA certification databases, IATA ULD technical standards, EU F-Gas Regulation implementation timelines, and customs trade data for carbon fiber precursor imports. Bottom-up asset deployment modeling triangulated against top-down pharmaceutical trade flow analysis.
Segment-level volume and value trajectories emerged from product-type splits across container, pallet, and specialized refrigerated formats; material composition tracks for composite, aluminum, and hybrid constructions; and end-user disaggregation between integrated cargo operators, passenger airline belly cargo divisions, and pooled fleet service providers. CAGRs were derived from fleet replacement cycle analysis, fuel burn reduction economics, and regulatory mandate compliance deadlines. Forecast inputs incorporated EASA certification timeline friction, carbon fiber supply allocation constraints, and pharmaceutical lane growth corridors.
Revisions become necessary when CAAC airworthiness directive acceleration, EU Green Deal sustainability mandate tightening, or composite repair technician training pipeline expansion materialize beyond baseline assumptions. A model refresh is warranted upon material change in pharmaceutical export volume trajectories from India and China or pooled fleet operator consolidation patterns across European hubs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Carrier-Agnostic Parcel and Freight Visibility Aggregation Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
China Third-Party Logistics (3PL) Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
Italy Cold Chain Logistics Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Smart Container Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market
Logistics and Shipping
Uruguay Freight and Logistics Market