
 UAE Logistics Market | 2026-2036
UAE Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Logistics Market Intelligence
Modular service bundling is recalibrating how shippers procure logistics in the UAE, with buyers increasingly combining warehousing, customs brokerage, and freight forwarding under single contracts rather than sourcing each separately. DP World leverages its port-to-door infrastructure to anchor integrated offerings across Jebel Ali and Khalifa Port zones. Aramex competes through last-mile density in Gulf Cooperation Council corridors, while Agility Logistics sustains contract logistics specialization for retail and automotive verticals.
UAE logistics encompasses the planning, execution, and control of goods movement across air, sea, road, and rail networks, typically involving cargo handling with temperature-controlled capabilities, bonded warehousing, and customs clearance protocols aligned with Gulf Cooperation Council trade frameworks. Its primary purpose is enabling efficient supply chain continuity for trade-dependent economies where re-export flows dominate. Transportation services lead by volume given Emirates' air hub capacity and DP World's maritime throughput, while AI Systems within the technology segment represent the fastest-expanding category as operators deploy predictive routing and warehouse robotics. E-commerce end users command premium pricing for same-day and next-day delivery commitments, whereas traditional freight forwarding faces margin compression from digital platform entrants.
MOHAP oversees pharmaceutical and food safety standards that dictate cold chain certification requirements for logistics providers handling regulated cargo. The UAE's national logistics strategy and Dubai Customs modernization frameworks mandate single-window clearance and real-time tracking integration, effectively raising technology barriers to market access. Stakeholders must weigh capital deployment between automation infrastructure and compliance upgrades as regulatory timelines compress operational transformation cycles.
Market Dynamics
Integrated last-mile fulfillment networks are compressing procurement cycles as shippers abandon fragmented vendor relationships for bundled port-to-door contracts anchored by free zone infrastructure.
Growth Catalysts
- E-commerce fulfillment velocity:Same-day delivery commitments from Dubai-based retailers are pulling investment into automated sortation and micro-fulfillment nodes across Jebel Ali corridor zones.
- MOHAP cold chain mandates:Pharmaceutical handling certification requirements are expanding temperature-controlled warehouse capacity for vaccine and biologics distribution.
- Khalifa Port multimodal expansion:Rail connectivity to Etihad Rail network is creating integrated sea-land corridors for Saudi-bound cargo consolidation.
Market Restraints
- Labor cost volatility:Warehouse operator wages in Dubai free zones are rising faster than automation amortization schedules permit.
- Air freight slot concentration:Emirates SkyCargo dominance at Al Maktoum International limits third-party cargo handler pricing leverage during peak seasons.
- Customs system fragmentation:Abu Dhabi and Dubai maintain separate single-window platforms, forcing dual compliance investments for national operators.
Strategic Opportunities
- Northern Emirates underpenetration:Ras Al Khaimah and Fujairah lack bonded logistics parks, creating first-mover advantage for port-adjacent distribution center development.
- AI-routing convergence:Predictive analytics layered on Etihad Rail scheduling is enabling dynamic inventory positioning between port and inland container depots.
- Dubai Customs modernization incentives:Real-time tracking integration subsidies are lowering technology barriers for mid-tier freight forwarders.
Industry Challenges
- Warehouse robotics integration:Legacy WMS platforms in older Jebel Ali facilities require costly middleware development to connect with autonomous mobile robot fleets.
- Pharmaceutical qualification timelines:MOHAP good distribution practice certification delays average 14 months, freezing capacity expansion for specialized cold chain operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Logistics Market |
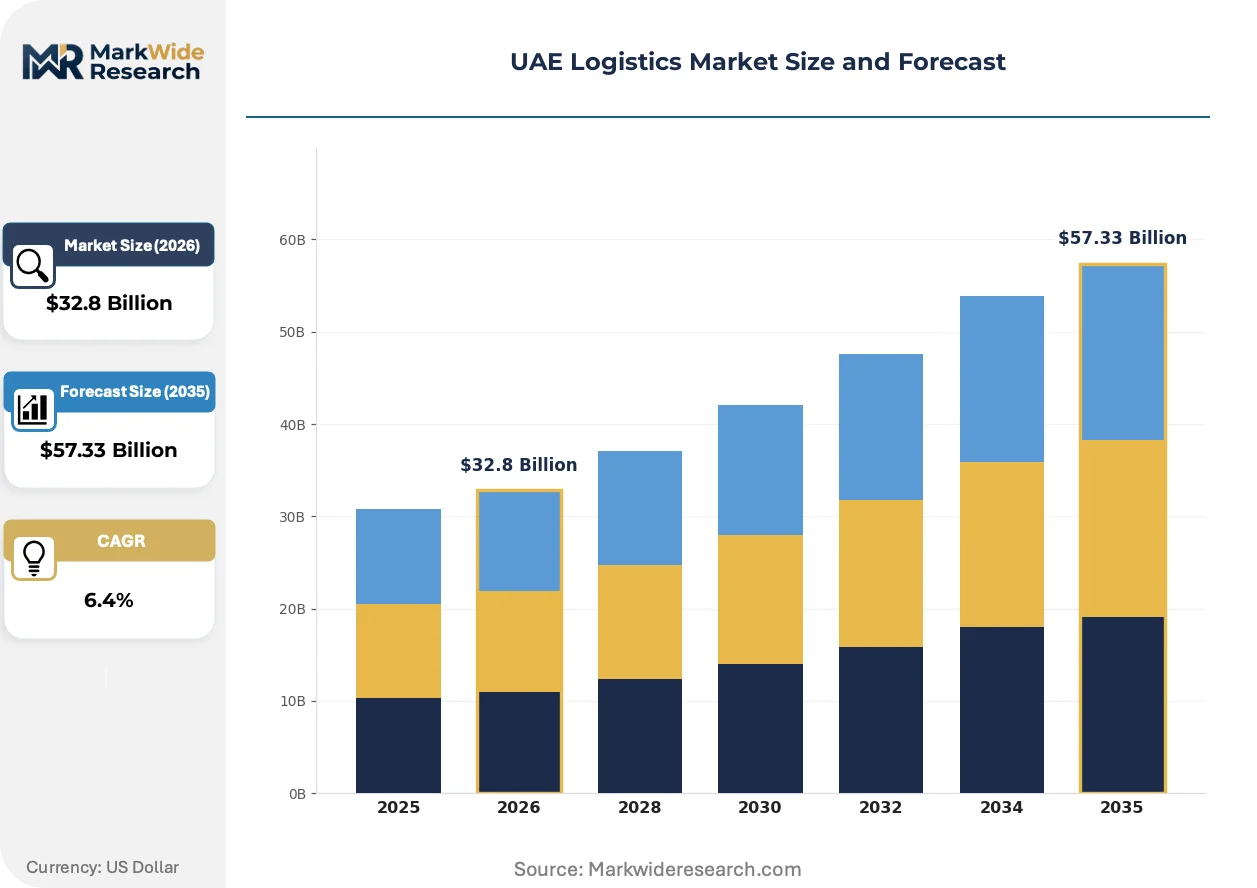
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage End User: E-commerce, Retail, Manufacturing, Automotive Technology: IoT Solutions, AI Systems, Blockchain, Automation Tools Delivery Mode: Air Freight, Sea Freight, Road Transport, Rail Transport |
| Companies Covered | Kuehne + Nagel, Al-Futtaim Logistics, DP World, Emirates Logistics, Agility Logistics, Aramex, FedEx, DB Schenker, DHL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Logistics Market Strategic Shifts & Innovations
Digital freight platforms are collapsing traditional forwarding margins while automated port infrastructure and predictive cargo routing rewrite asset utilization benchmarks across Emirates trade corridors.
Blockchain-enabled documentation systems are decentralizing trust architecture in customs clearance workflows. Dubai Customs and Abu Dhabi Customs pilots now allow shippers to submit verified origin certificates through distributed ledger networks rather than paper-based embassy attestations. This compression is decentralizing brokerage value toward technology-integrated operators who control data verification nodes.
MOHAP's 2024 serialization requirements for pharmaceutical track-and-trace are mandating unit-level barcode integration across cold chain logistics providers. Warehouse operators must now deploy aggregation stations capable of parent-child hierarchy recording for temperature-monitored shipments. Vaccine distributors and biologics importers face the steepest compliance ramps, with certification audits occurring quarterly rather than annually.
Shippers are consolidating vendor panels around integrated service contracts that bundle freight forwarding, customs brokerage, and last-mile delivery under single key performance indicator frameworks. Traditional commission-based forwarding relationships are yielding to outcome-based agreements where providers absorb demurrage and detention exposure. E-commerce verticals in Dubai South free zone are driving this transition fastest, demanding guaranteed delivery windows with penalty clauses.
UAE Logistics Market Segmentation
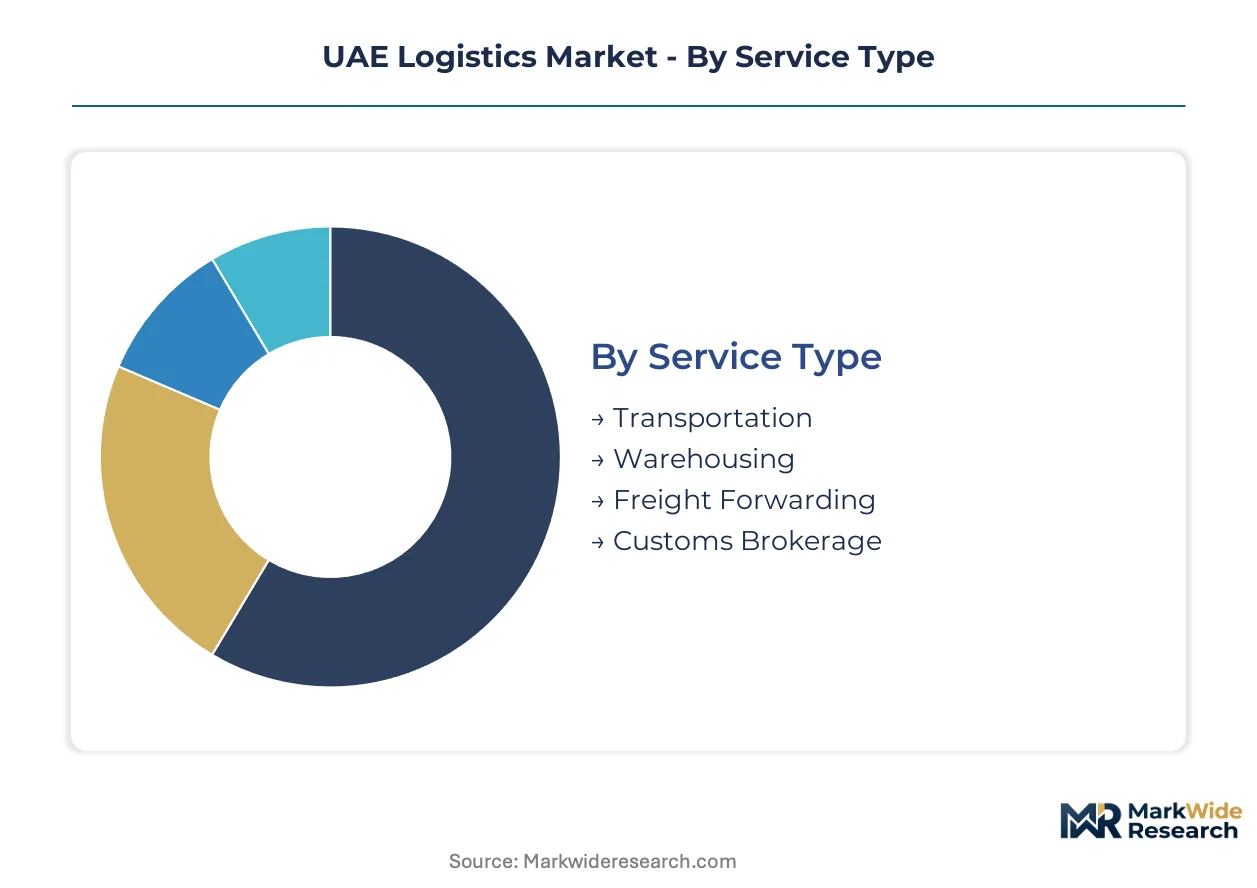
UAE logistics procurement patterns diverge sharply between trade corridor operators seeking bundled port-to-door contracts and vertical specialists demanding certified cold chain or bonded warehousing. Shippers now prioritize service integration over standalone cost optimization, reshaping how providers structure capacity investments across Emirates free zones.
Service Type:
Buyer differentiation hinges on asset ownership depth versus third-party orchestration preference.
- Transportation:Fleet-based operators control Emirates' air hub capacity through dedicated block space agreements with SkyCargo, while road hauliers compete on cross-GCC lane density. Demand concentrates in Dubai's Jebel Ali corridor where port-rail connectivity to Etihad Rail is compressing dwell times for Saudi-bound cargo.
- Warehousing:Bonded facilities within Dubai South and Khalifa Port free zones offer duty-deferred storage with value-added processing capabilities. Temperature-controlled capacity is expanding fastest in Dubai Healthcare City and Abu Dhabi's KIZAD zone under MOHAP certification mandates.
- Freight Forwarding:Commission-based booking agents face margin erosion as digital platforms disintermediate ocean and air cargo procurement. Mid-tier operators in Abu Dhabi and Dubai are consolidating around niche trade lanes where customs complexity sustains advisory fees.
- Customs Brokerage:Licensed specialists navigate dual single-window platforms between Dubai Customs and Abu Dhabi Customs, requiring duplicate compliance investments. Real-time tracking integration subsidies are lowering technology barriers for smaller operators seeking modernization.
Transportation leads volumes today; warehousing is gaining share fastest.
End User:
Vertical requirements range from velocity-driven fulfillment to compliance-heavy regulated cargo handling.
- E-commerce:Same-day delivery commitments from Dubai-based retailers are pulling investment into automated sortation and micro-fulfillment nodes. Penalty clauses for missed delivery windows are shifting risk to logistics providers absorbing demurrage and detention exposure.
- Retail:Omnichannel inventory positioning demands flexible warehousing contracts with seasonal surge clauses. Major retail groups in Dubai Mall and Mall of the Emirates corridors are consolidating vendor panels around integrated service bundles.
- Manufacturing:Just-in-time component flows from Jebel Ali Free Zone to Gulf assembly plants require synchronized multimodal scheduling. Etihad Rail connectivity is enabling inland container depot networks for steel and petrochemical feedstock distribution.
- Automotive:Finished vehicle logistics through Khalifa Port relies on specialized roll-on/roll-off handling with pre-delivery inspection facilities. Agility Logistics maintains contract logistics specialization for this vertical with dedicated yards in Jebel Ali.
E-commerce commands premium pricing; manufacturing offers volume stability through long-term contracts.
Technology:
Deployment maturity separates infrastructure-heavy automation from software-layer analytics.
- IoT Solutions:Sensor networks track container location, temperature, and shock events across Emirates trade corridors. Pharmaceutical and food safety regulators mandate real-time cold chain monitoring with automated alert thresholds.
- AI Systems:Predictive routing algorithms optimize last-mile sequencing in Dubai's dense urban corridors. Warehouse robotics integration faces middleware challenges in legacy Jebel Ali facilities with outdated WMS platforms.
- Blockchain:Distributed ledger pilots with Dubai Customs and Abu Dhabi Customs enable verified origin certificate submission without paper-based embassy attestations. Decentralized trust architecture is compressing brokerage value toward technology-integrated operators.
- Automation Tools:Autonomous mobile robot fleets require costly facility retrofitting in older free zone warehouses. Greenfield developments in Dubai South are specifying robotics-ready infrastructure from construction phase.
IoT Solutions anchor current deployment; AI Systems are expanding most quickly as operators prioritize predictive capabilities.
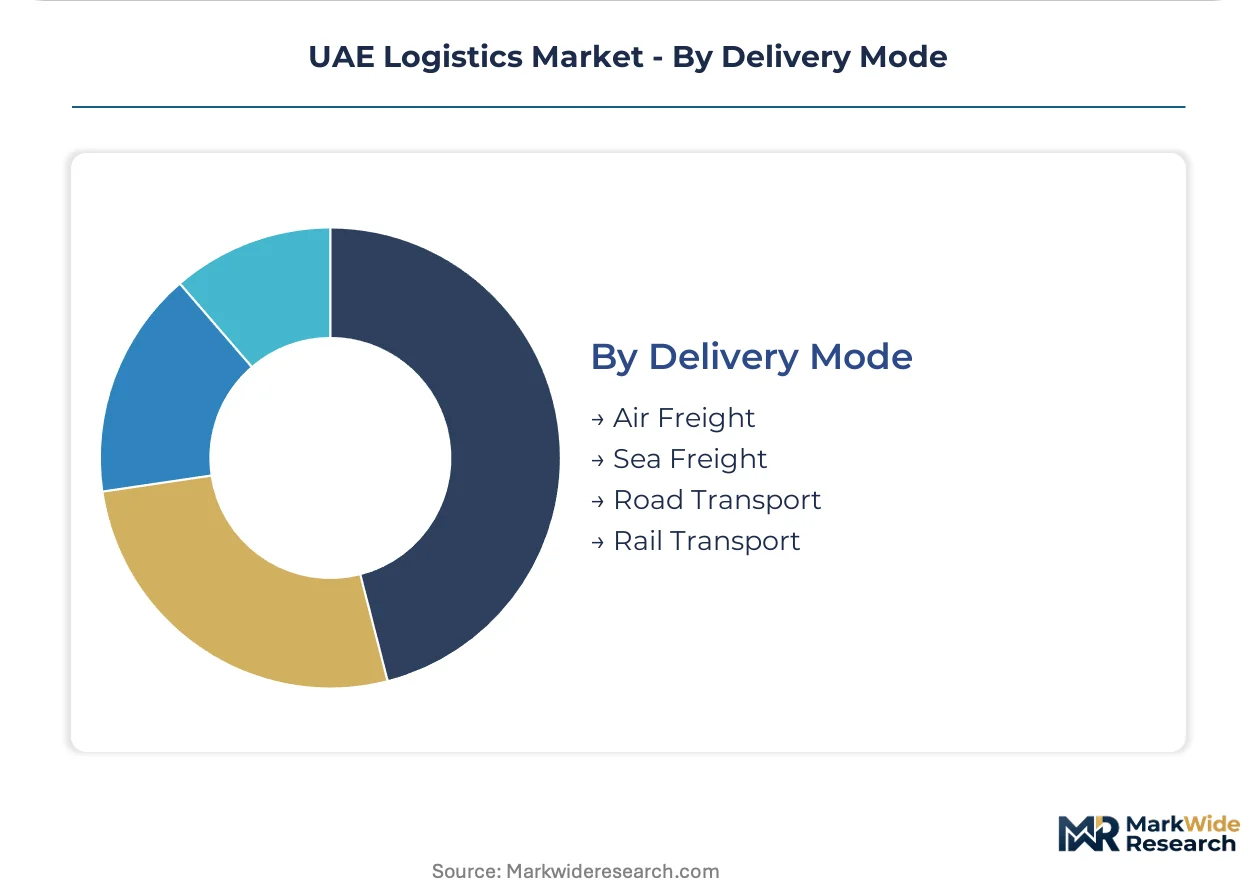
Delivery Mode:
Modal choice reflects cargo value density, time sensitivity, and destination accessibility within GCC networks.
- Air Freight:Emirates SkyCargo dominance at Al Maktoum International limits third-party handler pricing leverage during peak seasons. High-value electronics and pharmaceutical exports concentrate in Dubai's air hub given frequency to European and Asian markets.
- Sea Freight:DP World's Jebel Ali and Khalifa Port terminals handle containerized re-export flows dominating UAE trade volumes. Rail connectivity to Etihad Rail network is creating integrated sea-land corridors for Saudi-bound consolidation.
- Road Transport:Cross-border trucking to Saudi Arabia, Oman, and Bahrain remains essential for GCC corridor distribution. Driver shortage pressures and fuel cost volatility are accelerating interest in rail substitution for long-haul lanes.
- Rail Transport:Etihad Rail's freight network is expanding container terminal connections with scheduled block train services to Ghuweifat and Fujairah. Predictive analytics layered on rail scheduling enables dynamic inventory positioning between port and inland depots.
Sea Freight leads volumes today; Rail Transport is climbing the fastest as network completion unlocks new corridor economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics infrastructure in the UAE traces its modern lineage to Jebel Ali Port's 1979 commissioning, which established Dubai as a transshipment hub before expanding into multimodal networks spanning the seven emirates.
Dubai
Jebel Ali Free Zone and Dubai South anchor the emirate's logistics density, with e-commerce fulfillment driving automated sortation investments. Dubai Customs mandates real-time tracking integration through its single-window platform. The Al Maktoum International corridor concentrates air freight capacity with dedicated cargo terminals serving pharmaceutical and electronics verticals.
Abu Dhabi
Khalifa Port's Etihad Rail connectivity is creating sea-land corridors for Saudi-bound consolidation. KIZAD free zone expansion targets automotive and aerospace logistics under Abu Dhabi Customs jurisdiction. The Musaffah industrial cluster houses temperature-controlled warehouses serving MOHAP-certified pharmaceutical distribution.
Sharjah
Hamriyah Free Zone and Sharjah International Airport support mid-tier freight forwarding operations with lower land costs than Dubai. The emirate's logistics parks specialize in breakbulk cargo and construction materials handling. Sharjah's port network serves as overflow capacity during Jebel Ali peak congestion.
Northern Emirates
Ras Al Khaimah and Fujairah remain underpenetrated for bonded logistics infrastructure despite expanding port capacities. Fujairah's strategic location outside the Strait of Hormuz attracts oil and gas logistics specialists. Ras Al Khaimah's developing free zones offer first-mover incentives for distribution center development.
UAE Logistics Market Key Industry Players
Premium-margin players sit above commodity-margin players across asset ownership depth, with port-anchored integrators commanding bundled contract pricing while digital-forwarding entrants compress traditional brokerage yields. The vendor base clusters around three strategic archetypes: infrastructure-heavy port operators, technology-integrated last-mile specialists, and vertical-focused contract logistics providers. Dominant competitive moves include free zone capacity expansion and predictive analytics licensing for routing optimization.
Within the infrastructure-anchored tier, DP World and Emirates Logistics exemplify port-to-door integrators leveraging Jebel Ali and Khalifa Port assets. Among GCC-specialized last-mile operators, Aramex occupies a position shaped by cross-border density. Kuehne + Nagel represents the global forwarding archetype competing through customs advisory depth.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Al-Futtaim Logistics |
| DP World |
| Emirates Logistics |
| Agility Logistics |
| Aramex |
| FedEx |
| DB Schenker |
| DHL |
| Others |
Cost & Logistics Intelligence
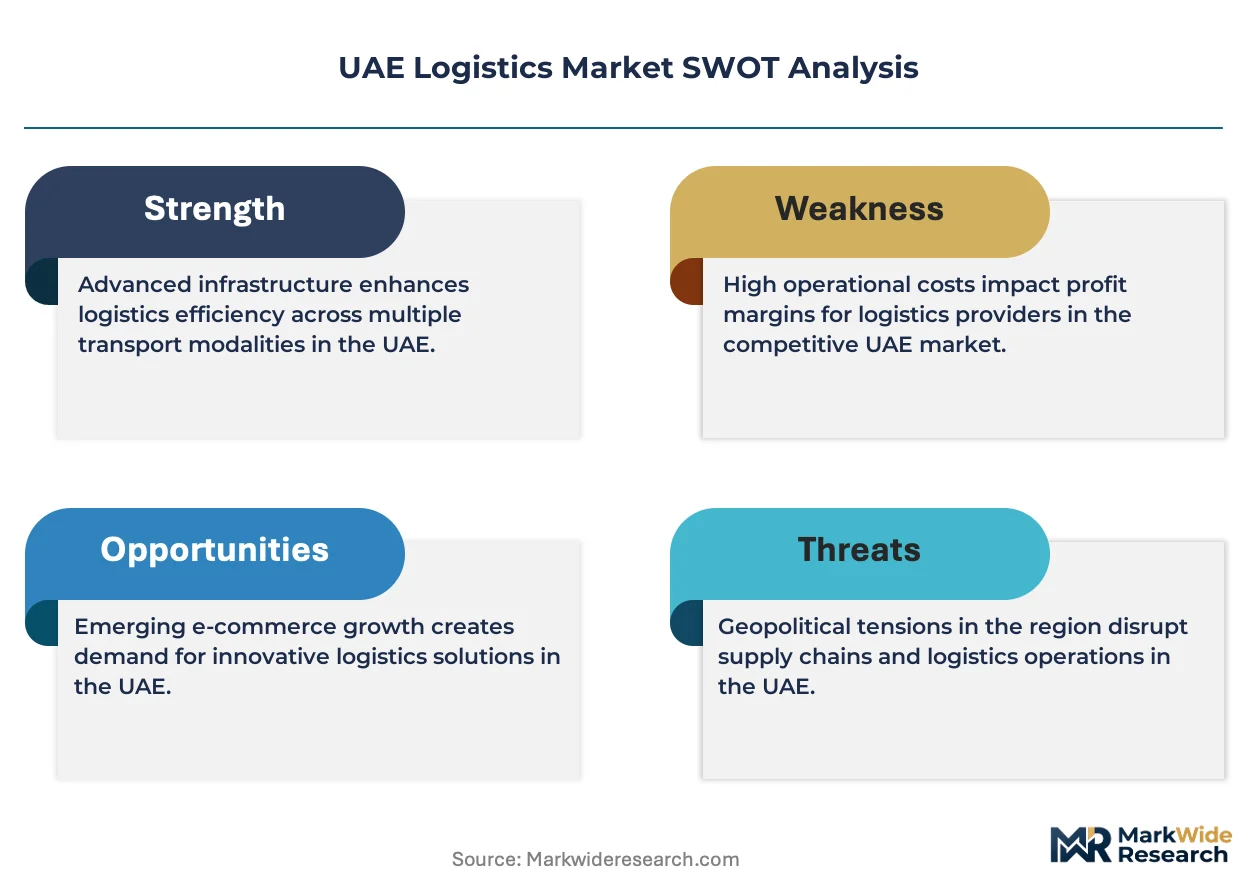
E-commerce fulfillment buyers in Dubai South and Jebel Ali Free Zone anchor the UAE logistics market's dominant pricing model, their same-day delivery demands compressing procurement cycles into bundled port-to-door contracts with penalty clauses for missed windows.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MOHAP-certified cold chain providers from bonded warehouse operators and basic freight forwarders. Price differentiation rests on certification grade and volume scale, with pharmaceutical handlers commanding premiums for serialization compliance. Cost compression in standard-tier forwarding is intensifying because digital platforms disintermediate ocean and air cargo procurement. E-commerce verticals exhibit least price sensitivity for guaranteed delivery windows, while commodity traders in breakbulk segments drive hardest bargain negotiations.
Supply Chain Analysis
Workforce availability in Bangladesh, India, and Pakistan shapes labor supply for UAE warehouse operations, with recruitment pipelines feeding Jebel Ali and Khalifa Port free zones. Raw material dependencies span steel racking systems from China, refrigeration compressors from Germany and Japan, and WMS software licenses from US and European vendors. Single-source vulnerability concentrates in Emirates SkyCargo block space agreements during peak pharmaceutical export seasons. Distribution runs through port-adjacent free zones with last-mile handoffs to Aramex and regional courier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE logistics market functions as a geographic-arbitrage play between Dubai's premium-priced integrated services and Sharjah's lower land-cost overflow capacity, with Dubai Customs real-time tracking mandates widening the compliance cost differential.
For Market Incumbents: Cement control over Jebel Ali and Khalifa Port free zone capacity through automation infrastructure investments that raise technology barriers for digital platform entrants. Lock in e-commerce fulfillment contracts with outcome-based KPI frameworks before mid-tier forwarders secure Dubai Customs modernization subsidies. Priority levers include warehouse robotics integration and MOHAP cold chain certification expansion. For New Entrants and Emerging Players: Northern Emirates pharmaceutical distributors represent an underserved buyer archetype lacking bonded cold chain infrastructure in Ras Al Khaimah and Fujairah. Target first-mover advantage in port-adjacent distribution centers serving oil and gas logistics outside the Strait of Hormuz. Go-to-market angle centers on Etihad Rail connectivity for Saudi-bound cargo consolidation with lower free zone entry costs than Dubai. For Investors and Strategic Acquirers: Port operators with integrated free zone assets are the most active acquirer in this space, seeking technology-layer capabilities to defend margin position. Long-term viability favors infrastructure-heavy players with captive port access over commission-based forwarding models. Acquisition target archetype: mid-tier customs brokers with Dubai Customs real-time tracking integration. Signal to watch: Khalifa Port rail terminal utilization rates as Etihad Rail network completion approaches.| Strategic Initiative | Industry Significance |
|---|---|
| Free Zone Capacity Expansion | Jebel Ali and Khalifa Port zones attract pharmaceutical and e-commerce verticals with duty-deferred storage. |
| Warehouse Robotics Integration | Autonomous mobile robot fleets in Dubai South facilities reduce labor cost volatility in Dubai free zones. |
| MOHAP Certification Investment | Cold chain serialization compliance opens vaccine and biologics distribution to premium-margin handlers. |
| Etihad Rail Connectivity | Sea-land corridors through Khalifa Port compress dwell times for Saudi-bound consolidation cargo. |
| Real-Time Tracking Integration | Dubai Customs subsidies lower technology barriers for mid-tier freight forwarders seeking modernization. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with logistics operators, customs brokerage principals, free zone authority planners, and e-commerce supply chain directors with secondary validation. Sources included UAE customs trade statistics, DP World throughput disclosures, Etihad Rail development updates, and MOHAP pharmaceutical distribution guidelines. Bottom-up segment sizing and top-down macroeconomic triangulation cross-verified volume and value estimates across service type, end user, technology, and delivery mode dimensions.
Historical reference periods anchored the forecast window to pre-pandemic baseline volumes, pandemic disruption peaks, and normalization trajectories across the projection horizon. Segmentation modeling incorporated service type bundling preferences, end-user vertical requirements, technology deployment maturity, and free zone geographic concentration. CAGRs derived from trend extrapolation with elasticity adjustments for e-commerce penetration rates and rail network completion timelines. Industry-specific inputs included pharmaceutical cold chain capacity expansion schedules and Dubai Customs single-window integration milestones.
Underlying measurement precision varies by segment; transportation and warehousing volumes carry tighter precision than emerging AI Systems deployment rates. Forecasts reflect assumptions about regulatory timeline adherence, infrastructure completion schedules, and vertical demand continuity. Material deviation in Etihad Rail freight launch dates, MOHAP certification processing timelines, or Dubai Customs platform integration deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
Japan Logistics Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Europe Courier Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Germany Last Mile Delivery Market