
 Thailand Cold Chain Logistics Market | 2026-2036
Thailand Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Cold Chain Logistics Market Insights
Thailand's Eastern Economic Corridor is reconfiguring national cold chain capacity through industrial zone expansion and port-linked logistics parks. SCG Logistics leverages its cement-and-building-materials parent network to dominate bonded warehouse construction near Laem Chabang. Kerry Logistics sustains cross-border ASEAN connectivity through its Thai-Laos-Vietnam road corridor investments. JWD Group anchors pharmaceutical cold storage with FDA-certified facilities in Pathum Thani.
Cold chain logistics encompasses temperature-controlled storage, handling, and distribution systems maintaining product integrity between 2°C and 8°C for pharmaceuticals or below -18°C for frozen foods through vapor-compression refrigeration, insulated containers, and real-time telemetry monitoring. Its primary commercial purpose is preventing spoilage, maintaining potency, and extending shelf life for perishable goods across extended supply chains. Road transportation mode occupies the dominant share given Thailand's peninsula geography and highway infrastructure density connecting Bangkok to provincial agricultural zones. Active temperature control methods lead pharmaceutical and high-value biotechnology segments where deviation tolerance narrows to ±0.5°C. Storage services command disproportionate margin pools due to land scarcity near urban consumption centers and escalating electricity costs for continuous refrigeration.
Thailand's FDA pharmaceutical storage licensing, ASEAN Good Distribution Practice standards, and Department of Agriculture's cold treatment protocols for fruit exports shape compliance architecture and capital requirements for market entry. The country's Board of Investment incentives for logistics infrastructure partially offset refrigeration equipment import duties, redirecting investment toward automated high-bay cold stores. Stakeholders must monitor whether Thailand's carbon neutrality commitments accelerate ammonia-CO2 cascade refrigeration adoption versus conventional hydrofluorocarbon systems.
Market Dynamics
Thailand's cold chain sector is compressing toward the Eastern Economic Corridor as Laem Chabang port expansion and bonded logistics zones concentrate temperature-controlled capacity within a 100-kilometer coastal strip. This geographic pull is redrawing national distribution networks away from Bangkok-centric models.
Growth Catalysts
- FDA Cold Storage Licensing:Thailand's pharmaceutical regulator tightened import compliance standards for temperature-sensitive biologics, mandating certified facilities that lock in multi-year contracts with logistics providers.
- Fresh Food E-Commerce:Digital grocery platforms are expanding refrigerated last-mile delivery infrastructure across Greater Bangkok, creating dedicated urban cold networks separate from traditional wholesale channels.
- ASEAN Good Distribution Practice:Cross-border harmonization of pharmaceutical handling protocols is enabling Thai cold storage operators to capture regional distribution flows into Laos, Cambodia, and Vietnam.
Market Restraints
- Electricity Cost Volatility:Continuous refrigeration operations face margin pressure from Thailand's industrial electricity tariffs, which fluctuate with natural gas import prices and grid congestion during peak tropical months.
- Land Scarcity Near Consumption Centers:Cold storage construction concentrates in peri-urban zones where industrial land availability is tightening around Bangkok, Pathum Thani, and Samut Prakan provinces.
- Refrigerant Regulatory Transition:Thailand's carbon neutrality commitments are creating uncertainty between ammonia-CO2 cascade systems and conventional hydrofluorocarbon equipment, freezing some capital deployment decisions.
Strategic Opportunities
- Chiang Mai-Ranong Corridor:Northern Thailand's underpenetrated cold chain infrastructure offers first-mover positioning for operators serving Myanmar border trade and highland agricultural exports.
- Automated High-Bay Cold Stores:Board of Investment incentives for logistics infrastructure partially offset refrigeration equipment import duties, redirecting capital toward vertical storage systems that maximize land efficiency.
- Real-Time Telemetry Convergence:Integration of IoT temperature sensors with blockchain traceability is enabling pharmaceutical shippers to command premium service tiers through audit-ready documentation.
Industry Challenges
- Refrigeration Technician Shortage:Specialized ammonia system maintenance skills are scarce in Thailand's labor market, extending equipment downtime and raising service contract costs for facility operators.
- Multi-Temperature Zone Integration:Pharmaceutical clients demand simultaneous 2°C-8°C, 15°C-25°C, and frozen storage within single facilities, complicating HVAC engineering and energy management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Cold Chain Logistics Market |
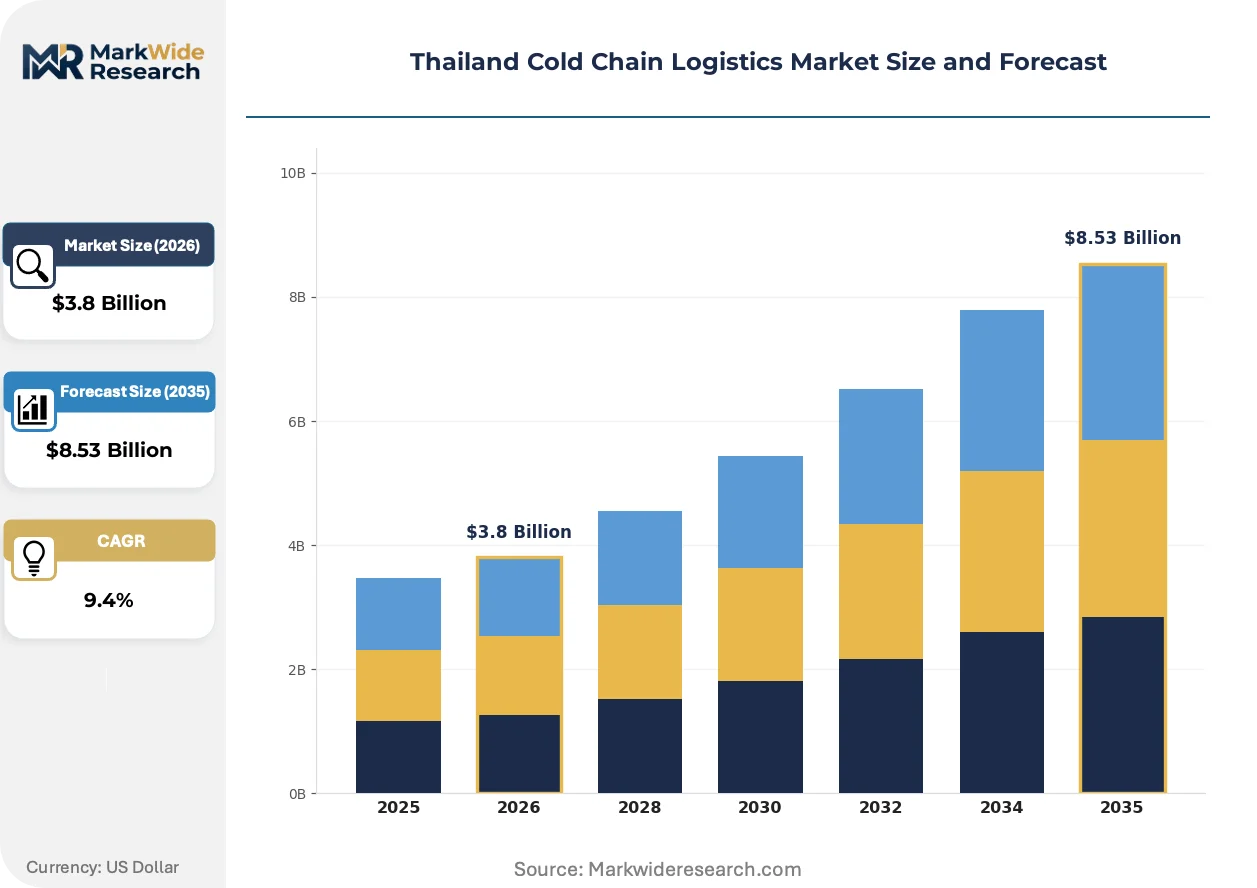
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Temperature Control Method: Active, Passive, Refrigerated, Cryogenic Transportation Mode: Road, Air, Rail, Sea End Use Industry: Pharmaceuticals, Food & Beverage, Chemicals, Electronics Service Type: Storage, Distribution, Packaging, Monitoring |
| Companies Covered | SCG Logistics, Kerry Logistics, Thai Cold Chain Network, DHL Supply Chain, JWD Group, Yusen Logistics, DB Schenker, Nichirei Logistics Group, Agility Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Cold Chain Logistics Market Trends and Innovations
Digital infrastructure is virtualizing physical cold chain operations across Thailand, compressing the information lag between warehouse temperature events and customer notification. This shift is redrawing competitive boundaries between asset-heavy operators and technology-enabled intermediaries.
IoT-enabled temperature monitoring is virtualizing compliance documentation for pharmaceutical shipments. Thai FDA-licensed facilities are deploying sensor networks that stream continuous thermal data to cloud platforms, replacing manual logging and paper certificates. Major hospital procurement departments now require API-accessible temperature histories as a contract precondition, compressing supplier qualification timelines from weeks to days.
Thailand's Board of Investment revised logistics infrastructure incentives to prioritize energy-efficient refrigeration systems, accelerating capital flows toward ammonia-CO2 cascade technology. The policy shift is elevating compliance costs for incumbent operators with aging hydrofluorocarbon equipment while creating certification advantages for greenfield facilities in the Eastern Economic Corridor. Pharmaceutical cold storage applicants face extended licensing timelines if proposed systems fall below specified efficiency thresholds.
Consolidation of fresh produce procurement is displacing fragmented wholesale relationships with direct farm-to-platform contracts. Centralized buying desks at major e-commerce grocery operations now specify cold chain performance standards that exclude traditional market intermediaries lacking temperature verification capability. This pattern is most visible in Greater Bangkok's dragon fruit and durian distribution, where origin-integrated cold treatment protocols have become mandatory for export-grade shipments.
Thailand Cold Chain Logistics Market Segmentation
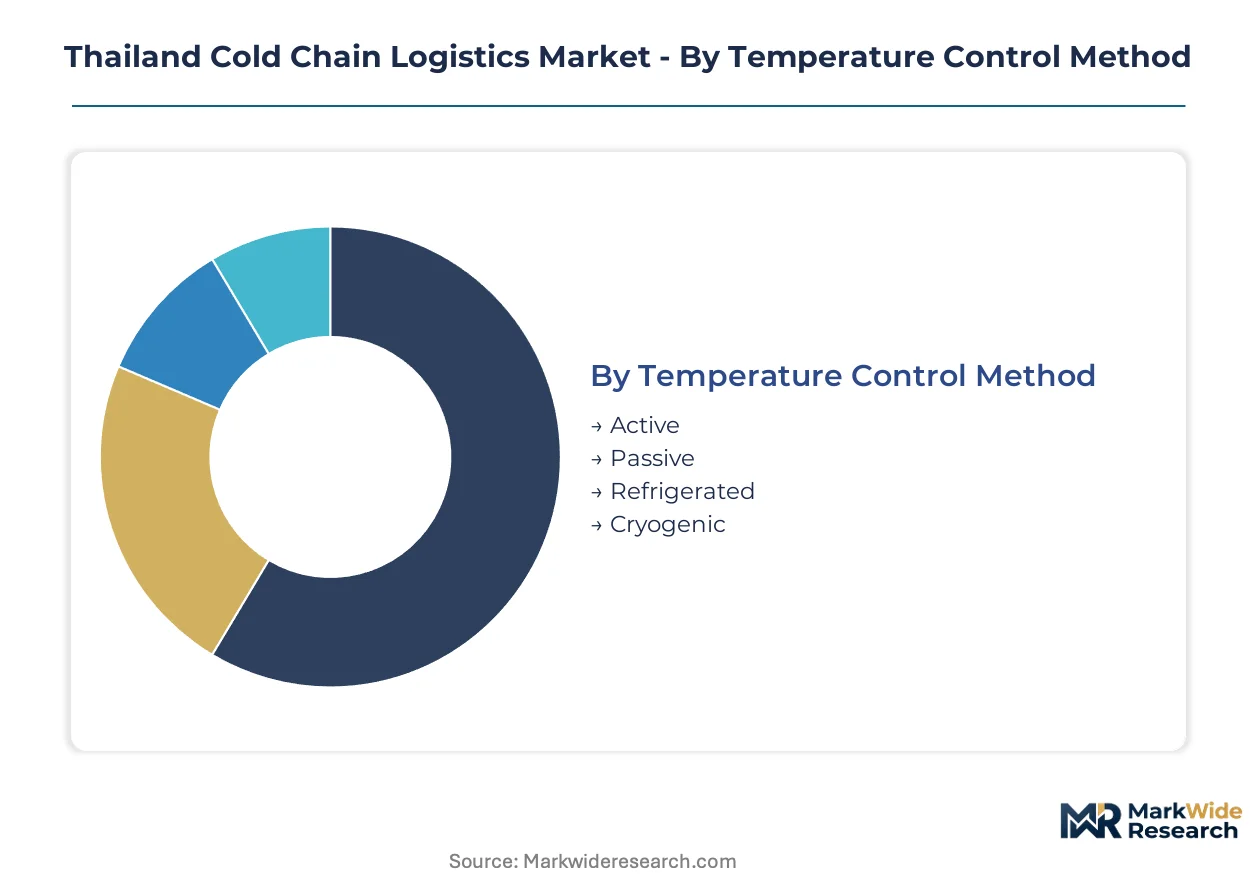
Cold chain logistics operators in Thailand configure service portfolios around temperature sensitivity tiers and regulatory compliance burdens. Segment boundaries determine capital allocation, technician specialization requirements, and contract duration structures across the Eastern Economic Corridor and Greater Bangkok.
Temperature Control Method:
After-sales service intensity peaks with active temperature control systems requiring continuous ammonia-CO2 cascade maintenance and real-time telemetry calibration.
- Active:Vapor-compression refrigeration systems with continuous power supply maintain precise thermal bands through automated compressor cycling and redundant backup units. Pharmaceutical distribution into Laos and Cambodia depends on active-controlled vehicles to satisfy ASEAN Good Distribution Practice documentation requirements. Demand concentrates among FDA-licensed facilities serving biologics importers at Laem Chabang.
- Refrigerated:Engine-driven mechanical cooling dominates Thailand's road transport fleet connecting Bangkok to provincial seafood processing zones. Insulated truck bodies with integrated refrigeration units handle frozen durian and shrimp exports through the Eastern Economic Corridor's bonded logistics parks.
- Passive:Phase-change materials and insulated containers provide temperature stability without active power, suited for short-haul pharmaceutical samples and last-mile e-commerce grocery delivery in Greater Bangkok's congested urban cores.
- Cryogenic:Liquid nitrogen vaporization systems maintain ultra-low temperatures below -150°C for cell therapy logistics and specialized biotechnology shipments into Pathum Thani's hospital clusters.
Refrigerated systems hold the largest share; momentum sits with active control as pharmaceutical compliance standards tighten.
Transportation Mode:
Cost tier differentiation separates capital-intensive air cargo from asset-light road networks serving provincial agricultural collection points.
- Road:Highway density along Thailand's peninsula geography enables refrigerated trucking dominance for dragon fruit and durian exports from Chiang Rai to Laem Chabang. Fleet operators in Samut Prakan specialize in multi-temperature zone trailers serving Central Retail and Lotus's distribution centers.
- Sea:Reefer container throughput at Laem Chabang port anchors temperature-controlled exports to China and Japan. Bonded cold storage integration allows seafood processors in Chonburi to stage frozen shrimp for vessel loading without customs interruption.
- Air:Bangkok Suvarnabhumi's cargo terminals handle high-value pharmaceutical shipments requiring rapid transit to ASEAN markets. Cold chain service contracts here command premium pricing for temperature excursion liability coverage.
- Rail:Limited refrigerated rail capacity connects northeastern agricultural zones to Bangkok processing hubs, constrained by track gauge incompatibility with neighboring networks and sporadic power supply reliability.
Road transportation holds the largest share; air cargo is expanding most quickly for pharmaceutical time-critical deliveries.
End Use Industry:
Application-specific compliance requirements create divergent facility specifications and certification timelines across customer verticals.
- Food & Beverage:Seafood processing clusters in Chonburi and Rayong drive frozen storage demand, while fresh produce e-commerce platforms in Greater Bangkok require urban micro-fulfillment cold rooms. Temperature protocols here span -18°C frozen through 2°C-8°C chilled bands.
- Pharmaceuticals:FDA-licensed facilities in Pathum Thani and Lat Krabang handle vaccine imports and biologics distribution under Thailand's tightened cold storage licensing regime. Deviation tolerance narrows to ±0.5°C for oncology therapeutics.
- Chemicals:Temperature-sensitive industrial adhesives and specialty coatings require controlled storage in Samut Prakan's manufacturing zones, though volume remains fragmented across small-batch distributors.
- Electronics:Semiconductor and battery components need 15°C-25°C humidity-controlled environments, overlapping with pharmaceutical ambient storage infrastructure in mixed-use facilities.
Food & Beverage holds the largest share; pharmaceuticals is climbing the fastest on regulatory compliance premiums.
Service Type:
Margin concentration varies sharply between asset-heavy storage operations and technology-enabled monitoring services.
- Storage:Land scarcity around Bangkok and escalating electricity tariffs compress returns for ambient-to-frozen multi-zone warehouses. Automated high-bay systems in the Eastern Economic Corridor maximize pallet density per square meter.
- Distribution:Cross-border road corridors into Laos and Vietnam generate recurring revenue through customs-bonded temperature-controlled trucking. Kerry Logistics maintains dedicated fleet allocation for this ASEAN connectivity.
- Packaging:Insulated box fabrication and phase-change material preconditioning services support e-commerce grocery expansion, with demand scaling alongside platform order volumes in Greater Bangkok.
- Monitoring:IoT sensor deployment and blockchain-integrated temperature logging command software-margin economics without refrigeration asset ownership. Hospital procurement departments now mandate API-accessible thermal histories.
Storage holds the largest share; monitoring is gaining share fastest on digital infrastructure leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold storage capacity concentrates along Thailand's eastern seaboard where Laem Chabang port expansion and bonded logistics zones are redrawing national distribution networks away from Bangkok-centric models. This geographic compression is accelerating infrastructure investment across five distinct sub-regional markets.
Eastern Economic Corridor
Seafood processing clusters in Chonburi and Rayong drive frozen storage demand for shrimp and fish exports. Thailand's Board of Investment incentives for logistics infrastructure redirect capital toward automated high-bay facilities near Laem Chabang. Bonded cold storage integration allows processors to stage frozen products for vessel loading without customs interruption.
Greater Bangkok
Fresh food e-commerce platforms are expanding refrigerated last-mile delivery infrastructure across metropolitan zones. The country's FDA cold storage licensing requirements tighten compliance standards for pharmaceutical imports handled through Pathum Thani distribution hubs. Urban micro-fulfillment cold rooms now operate as dedicated networks separate from traditional wholesale channels.
Chiang Mai-Ranong Corridor
Northern Thailand's underpenetrated cold chain infrastructure offers positioning for operators serving Myanmar border trade. Highland agricultural exports of dragon fruit and durian require origin-integrated cold treatment protocols. Temperature-controlled road connections to Laem Chabang remain sporadic, constraining export-grade shipment volumes.
Samut Prakan
Multi-temperature zone trailers serve Central Retail and Lotus's distribution centers from this industrial province bordering Bangkok. Fleet operators here specialize in frozen and chilled bands spanning -18°C through 2°C-8°C. Land scarcity is tightening around peri-urban cold storage construction sites.
Pathum Thani
Pharmaceutical cold storage concentrates in FDA-certified facilities handling vaccine imports and biologics distribution. Deviation tolerance narrows to ±0.5°C for oncology therapeutics stored here. Hospital procurement departments in this cluster now mandate API-accessible temperature histories as contract preconditions.
Thailand Cold Chain Logistics Market Competitive Landscape
Diversified conglomerate logistics arms and specialized temperature-control operators split the market between asset-heavy infrastructure ownership and technology-enabled service layers. Three strategic archetypes dominate: construction-materials-backed warehouse developers, cross-border ASEAN network operators, and pharmaceutical compliance specialists. Consolidation is accelerating through bonded zone capacity expansion and multi-temperature facility diversification.
Within the conglomerate-backed tier, SCG Logistics leverages its parent company's cement-and-building-materials network to dominate bonded warehouse construction near Laem Chabang. Kerry Logistics sustains regional connectivity through Thai-Laos-Vietnam road corridor investments. JWD Group anchors pharmaceutical cold storage with FDA-certified facilities in Pathum Thani, representing the compliance-specialist archetype.
| Leading Market Players |
|---|
| SCG Logistics |
| Kerry Logistics |
| Thai Cold Chain Network |
| DHL Supply Chain |
| JWD Group |
| Yusen Logistics |
| DB Schenker |
| Nichirei Logistics Group |
| Agility Logistics |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in FDA-certified pharmaceutical cold storage across Greater Bangkok is compressing pricing power toward certified operators while forcing uncertified facilities into commodity frozen-food segments. This utilization gap simultaneously rewards compliance-heavy investments and penalizes generic capacity, bifurcating supplier strategies between premium certification pursuit and cost-base minimization.
Pricing Analysis
Thailand's FDA cold storage licensing dictates the pricing tier structure across the market, separating certified pharmaceutical facilities from uncertified frozen-food warehouses by a substantial compliance premium. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and temperature precision, with oncology-grade ±0.5°C deviation tolerance commanding the highest rates. Cost compression in economy-tier frozen storage is intensifying because electricity tariff volatility and land scarcity squeeze generic operators. Small-scale seafood processors exhibit the highest price sensitivity, while multinational biologics importers prioritize deviation liability coverage over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now characterize equipment procurement for ammonia-CO2 cascade refrigeration systems, reflecting manufacturer financing support for greenfield Eastern Economic Corridor projects. Geographic supply concentration for compressor units and insulated panel systems draws from Japan, Germany, and China, with Japanese suppliers dominating precision pharmaceutical-grade equipment. Raw material dependencies for facility construction rest on imported polyurethane foam, stainless steel refrigeration coils, and specialized control sensors. Single-source vulnerability runs through Japanese compressor technology for ultra-low-temperature applications. Distribution runs through bonded logistics zones at Laem Chabang for export-oriented seafood staging, while domestic pharmaceutical flows center on Pathum Thani hospital cluster proximity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's cold chain logistics market is cycling through a recovery phase as post-pandemic pharmaceutical import normalization and fresh food e-commerce expansion rebuild utilization rates. Capital deployment timing favors operators positioned at the intersection of tightening FDA compliance and automated high-bay efficiency.
For Market Incumbents: Insulate margin position by accelerating ammonia-CO2 cascade retrofits ahead of carbon neutrality enforcement, locking in Board of Investment incentive eligibility while competitors hesitate on refrigerant technology bets. Consolidate through selective acquisition of peri-urban land parcels in Samut Prakan before industrial zoning restrictions tighten further. Defensive certification investment in multi-temperature zone capability counters the threat of hospital procurement departments mandating API-accessible temperature histories as contract preconditions. For New Entrants and Emerging Players: Build out automated high-bay cold storage capacity in the Chiang Mai-Ranong Corridor, where underpenetrated infrastructure and highland agricultural export growth create first-mover positioning absent entrenched competition. Target pharmaceutical monitoring services as the most penetrable segment, leveraging IoT sensor deployment and blockchain-integrated temperature logging without capital-heavy refrigeration asset ownership. Go-to-market traction requires direct contracting with dragon fruit and durian cooperatives for origin-integrated cold treatment protocols that bypass traditional wholesale intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among FDA-certified pharmaceutical cold storage operators with multi-year biologics distribution contracts, offering visibility through regulatory compliance stickiness. Long-term viability over the next decade rests on facilities achieving carbon-neutral refrigeration certification ahead of policy enforcement curves. Acquisition priority targets mixed-use operators with demonstrated multi-temperature zone engineering capability spanning frozen, chilled, and ambient bands. The critical inflection signal to monitor is Thailand's Board of Investment incentive revision timing, which would accelerate capital flows toward greenfield automated facilities and strand aging hydrofluorocarbon-dependent assets.| Strategic Initiative | Industry Significance |
|---|---|
| Automated High-Bay Cold Store Deployment | Maximizes pallet density per square meter in land-scarce peri-urban zones around Bangkok and Pathum Thani. |
| Ammonia-CO2 Cascade Refrigeration Transition | Secures Board of Investment incentive eligibility ahead of carbon neutrality commitments tightening equipment standards. |
| Real-Time Telemetry Integration | Enables API-accessible temperature histories that hospital procurement departments now mandate as contract preconditions. |
| Multi-Temperature Zone Certification | Captures pharmaceutical clients demanding simultaneous frozen, chilled, and ambient storage within single facilities. |
| Chiang Mai-Ranong Corridor Expansion | Positions for Myanmar border trade and highland agricultural exports with limited incumbent competition. |
Research Methodology
Desk research of customs trade databases, Thailand Board of Investment incentive filings, and FDA licensing registries preceded structured interviews with cold storage facility operators, pharmaceutical supply chain managers, and seafood processing procurement leads. Primary fieldwork encompassed facility tours across the Eastern Economic Corridor and Greater Bangkok, supplemented by secondary validation against ASEAN Good Distribution Practice documentation requirements and electricity tariff regulatory filings. Bottom-up capacity utilization estimates triangulated against top-down market value projections.
Forecast assumptions held Thailand's carbon neutrality policy trajectory and FDA licensing stringency as fixed constraints while varying pharmaceutical import growth rates and fresh food e-commerce penetration scenarios. Segmentation modeling incorporated temperature control method, transportation mode, end-use industry vertical, and service type dimensions alongside regional cluster analysis across five sub-national markets. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and infrastructure investment cycles. Industry-specific inputs included bonded logistics zone throughput data and hospital procurement system integration timelines.
Practitioners should monitor Board of Investment incentive revisions, FDA licensing queue backlogs, and ammonia-CO2 cascade equipment lead times for early signals of capacity expansion acceleration or constraint. Forecast outputs reflect documented assumptions about regulatory enforcement timing and infrastructure investment continuity. Macroeconomic deviation in electricity pricing, regulatory acceleration of refrigerant phase-out schedules, or technological disruption in passive temperature control would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
First and Last Mile Delivery Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
North America Cargo Handling Equipment Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Asia Pacific (APAC) Contract Logistics Market
Logistics and Shipping
Tank Container Shipping Market