
 Warehousing and Distribution Logistics Market | 2026-2036
Warehousing and Distribution Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Warehousing and Distribution Logistics Market Outlook
Software-defined warehouse management is hardening into the core revenue layer for logistics providers, shifting value from physical space to algorithmic orchestration. DHL Supply Chain leverages its proprietary WMS deployments across multi-client campuses to sustain margin premiums in contract logistics. Amazon.com anchors its competitive posture through in-house production of robotics and captive supply of last-mile density. GXO Logistics differentiates via RFID-enabled inventory visibility platforms that extend customer retention in retail verticals.
Warehousing and distribution logistics encompasses the physical storage, inventory management, and movement coordination of goods through facilities operating at throughput velocities measured in pallets per hour and order lines per labor minute. The discipline integrates racking systems, material handling equipment, and information architectures to synchronize inbound receipts with outbound shipments against service-level agreements. Storage solutions and order fulfillment together command the largest share of service revenue, while last-mile delivery represents the fastest-expanding margin pool as labor scarcity forces automation investment. Automated storage and RFID tracking within the technology dimension are attracting capital fastest, though blockchain solutions remain nascent outside pharmaceutical serialization use cases.
OSHA warehouse safety standards, EPA emissions rules for diesel-powered material handling fleets, and the EU Green Deal's F-Gas Regulation for cold-chain refrigerants collectively elevate compliance costs and equipment replacement cycles. China's MIIT and SAMR jointly enforce GB standards on automated facility interoperability, creating market access conditions that favor domestic system integrators. Stakeholders must weigh regulatory divergence against platform standardization bets when allocating capital across multi-country networks.
Market Dynamics
The warehousing and distribution logistics sector is experiencing a structural compression of fulfillment timelines as same-day delivery expectations harden into baseline service levels, forcing capital reallocation from square footage expansion toward automation density and algorithmic throughput optimization.
Growth Catalysts
- MIIT Digital Transformation Mandates:China's Ministry of Industry and Information Technology enforcement of smart logistics infrastructure standards is accelerating automated facility deployment across domestic supply chains.
- E-commerce Fulfillment Velocity:Online retail platforms are expanding micro-fulfillment networks in urban cores to meet delivery windows measured in hours rather than days.
- RFID-Enabled Inventory Visibility:Item-level tracking systems are reducing stockout incidents and shrinkage in high-velocity retail verticals.
Market Restraints
- Labor Scarcity Cost Escalation:Warehouse operator wages and retention investments are compressing margins in labor-intensive picking and packing operations.
- Automated Equipment Lead Times:Concentrated supply of robotic systems from German and Japanese OEMs is extending deployment cycles for North American facilities.
- EU F-Gas Regulation Compliance:Cold-chain operators face accelerated refrigerant system replacement costs under the European Green Deal's phasedown mandates.
Strategic Opportunities
- India PLI Scheme for Logistics:Production-linked incentive structures are attracting foreign warehousing automation vendors to establish domestic manufacturing.
- Blockchain-Pharma Convergence:Pharmaceutical serialization requirements are creating pilot demand for distributed ledger track-and-trace systems.
- Dark Store Micro-Fulfillment:Grocery and quick-commerce platforms are retrofitting urban retail vacancies into automated picking centers.
Industry Challenges
- WMS Integration Complexity:Legacy enterprise resource planning systems resist seamless API connectivity with cloud-native warehouse management platforms.
- Automation Technician Shortage:Maintenance and programming skills for robotic material handling equipment outpace vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Warehousing and Distribution Logistics Market |
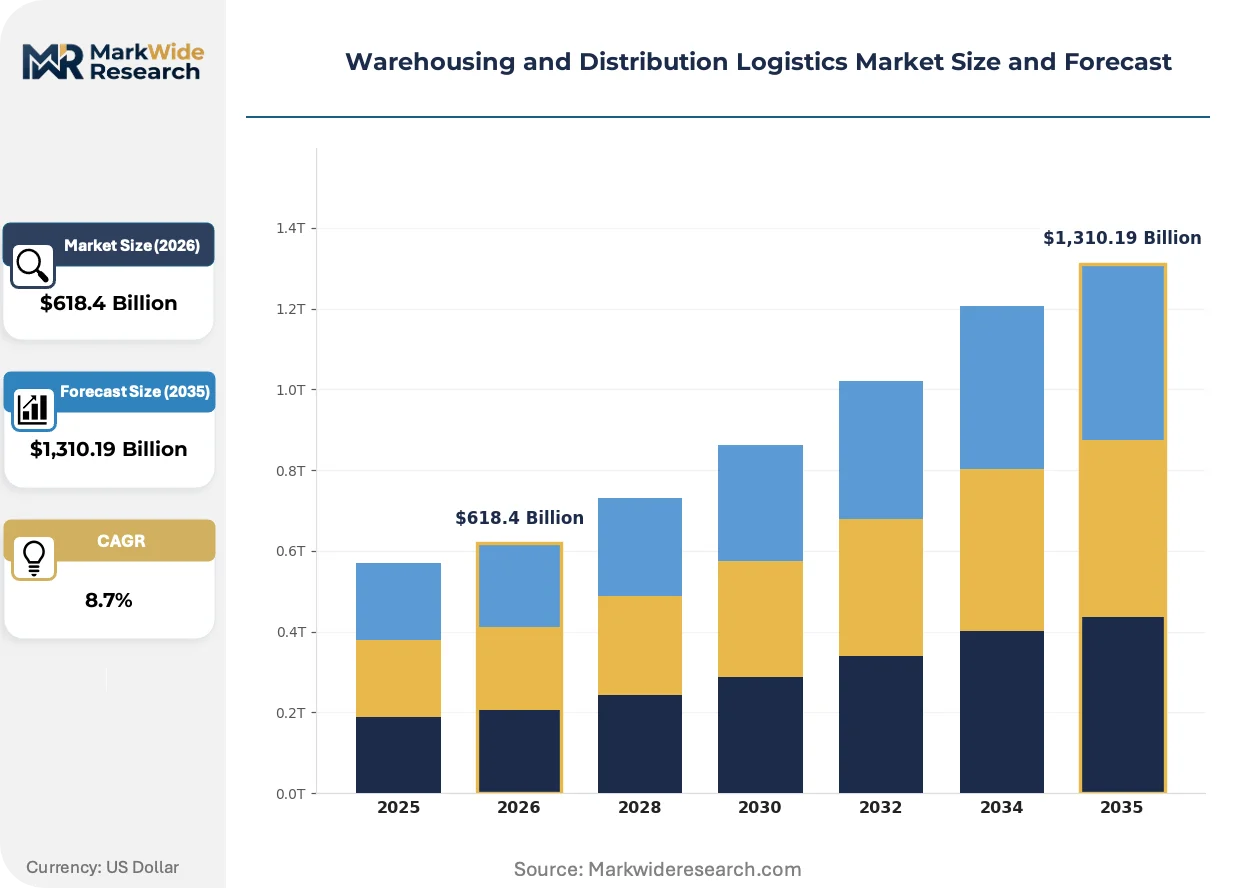
| Market Size in 2026 | $618.4 Billion |
| Market Size in 2035 | $1,310.19 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Storage Solutions, Transportation Services, Order Fulfillment, Last-Mile Delivery Technology: Warehouse Management Systems, Automated Storage, RFID Tracking, Blockchain Solutions End User: E-commerce, Manufacturing, Retail, Pharmaceuticals Distribution Channel: Direct Shipping, Third-Party Logistics, Drop Shipping, Cross-Docking |
| Companies Covered | Kuehne + Nagel, Nippon Express, Amazon.com, DB Schenker, XPO Logistics, DHL Supply Chain, CEVA Logistics, GEODIS, GXO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Warehousing and Distribution Logistics Market Strategic Shifts
Algorithmic orchestration is displacing manual warehouse management as the primary value driver, with capital flowing toward predictive analytics and autonomous mobile robotics rather than physical capacity expansion alone.
Autonomous mobile robots are absorbing intermediate-distance transport tasks previously executed by human-operated pallet jacks and forklifts. Third-party logistics providers in high-labor-cost markets are deploying AMR fleets at facility penetration rates exceeding prior automation waves. This technology compression is enabling smaller-footprint facilities to achieve throughput parity with legacy mega-warehouses.
EPA emissions rules for diesel-powered material handling fleets are forcing accelerated electrification timelines across US distribution networks. Industrial battery and hydrogen fuel cell alternatives are gaining procurement preference in California and Northeast corridor operations. Cold-chain and food distribution verticals face the steepest compliance cost curves under the phased regulatory implementation.
Service-level agreements are compressing from annual contracts toward performance-guaranteed arrangements with penalty clauses tied to order accuracy and delivery windows. Retail and pharmaceutical buyers are unbundling transportation from warehousing to source specialized providers for each leg. This procurement fragmentation is most advanced in German and British markets where buyer concentration supports vendor diversification strategies.
Warehousing and Distribution Logistics Market Segmentation
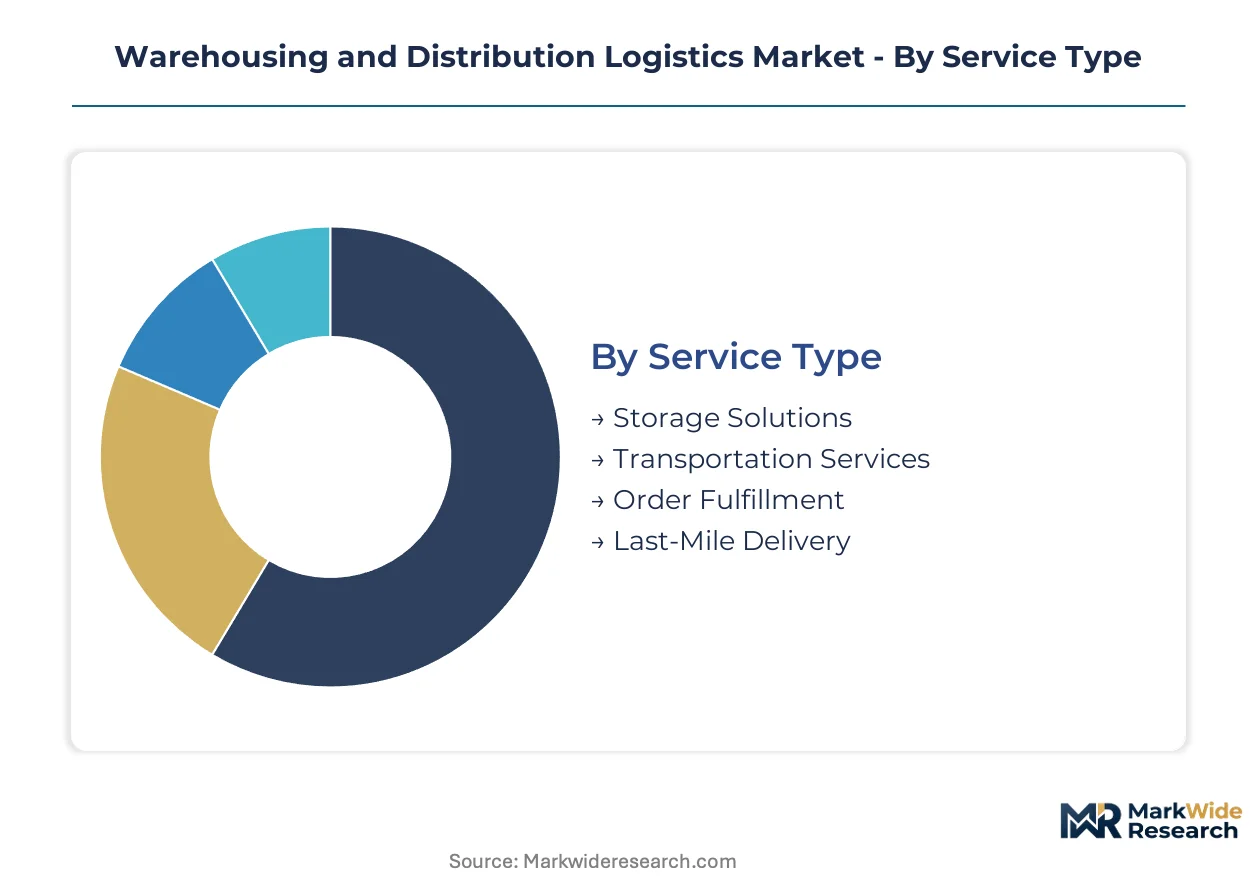
Segmentation in warehousing and distribution logistics reveals how capital allocation priorities diverge across service models, technology stacks, and customer verticals. Procurement patterns vary sharply between e-commerce platforms demanding velocity and pharmaceutical operators prioritizing compliance documentation. Understanding these fault lines enables vendors to align automation investments with margin-rich demand pockets.
Service Type:
Replacement cycles for legacy service infrastructure are shortening as same-day delivery mandates force facility modernization across all four service categories.
- Storage Solutions:Pallet-position optimization and climate-controlled zones for temperature-sensitive inventory dominate facility design specifications. Cold-chain operators in Germany and California are retrofitting ammonia-based refrigeration to meet EPA and EU F-Gas Regulation phasedown timelines.
- Order Fulfillment:Automated picking systems and batch-sortation modules compress order-to-ship intervals from hours to minutes. Micro-fulfillment centers in Shanghai and Mumbai are achieving throughput density previously requiring tenfold larger footprints.
- Transportation Services:Line-haul coordination between distribution nodes remains the largest revenue pool by volume.
- Last-Mile Delivery:Urban density constraints are accelerating locker-network and dark-store deployment.
Storage Solutions sits at the top of the volume ranking, with Last-Mile Delivery climbing the fastest.
Technology:
Cost tier stratification separates proven automation from experimental deployments, with mid-market operators prioritizing payback periods under thirty-six months.
- Warehouse Management Systems:Cloud-native platforms with API-first architectures are displacing on-premise legacy installations. Retail and third-party logistics operators in the US Northeast are selecting vendors based on real-time inventory synchronization capabilities.
- Automated Storage:Shuttle-based dense storage and robotic cube systems maximize vertical cube utilization in land-constrained markets. Japanese automotive parts distributors are deploying these systems to achieve overnight replenishment cycles.
- RFID Tracking:Item-level visibility systems reduce cycle-count labor and shrinkage in high-value verticals.
- Blockchain Solutions:Pharmaceutical serialization pilots are generating limited commercial traction outside regulatory compliance use cases.
Warehouse Management Systems commands the largest installed base, though Automated Storage is expanding most quickly in greenfield facilities.
End User:
Application-specific requirements drive divergent facility specifications, with pharmaceutical and e-commerce representing opposite poles of the complexity spectrum.
- E-commerce:Peak-season surge capacity and returns-processing infrastructure define competitive viability. Amazon and regional platforms in Southeast Asia are commissioning dedicated sortation hubs to manage holiday volume spikes.
- Pharmaceuticals:GDP-compliant temperature monitoring and lot-traceability systems dominate procurement criteria. European wholesalers are consolidating warehousing networks to amortize compliance infrastructure across larger volume bases.
- Retail:Omnichannel inventory pooling and ship-from-store capabilities blur traditional channel boundaries.
- Manufacturing:Just-in-sequence delivery and vendor-managed inventory programs synchronize inbound supply with production schedules.
E-commerce occupies the top volume position, while Pharmaceuticals is gaining share fastest on compliance-driven outsourcing.
Distribution Channel:
Customer type segmentation separates asset-heavy operators from network orchestrators, with margin structures reflecting capital intensity differentials.
- Third-Party Logistics:Multi-client campus models and shared-user automation spread capital costs across revenue streams. DHL Supply Chain and comparable operators in the Netherlands are deploying proprietary WMS layers to sustain contract renewal rates.
- Cross-Docking:Minimal dwell-time requirements and synchronized inbound-outbound scheduling maximize asset turns. Fresh grocery distributors in São Paulo and Mexico City rely on these facilities to maintain product integrity windows.
- Direct Shipping:Manufacturer-controlled transportation prioritizes brand experience and delivery promise reliability.
- Drop Shipping:Inventory-free retail models shift warehousing burden to upstream suppliers.
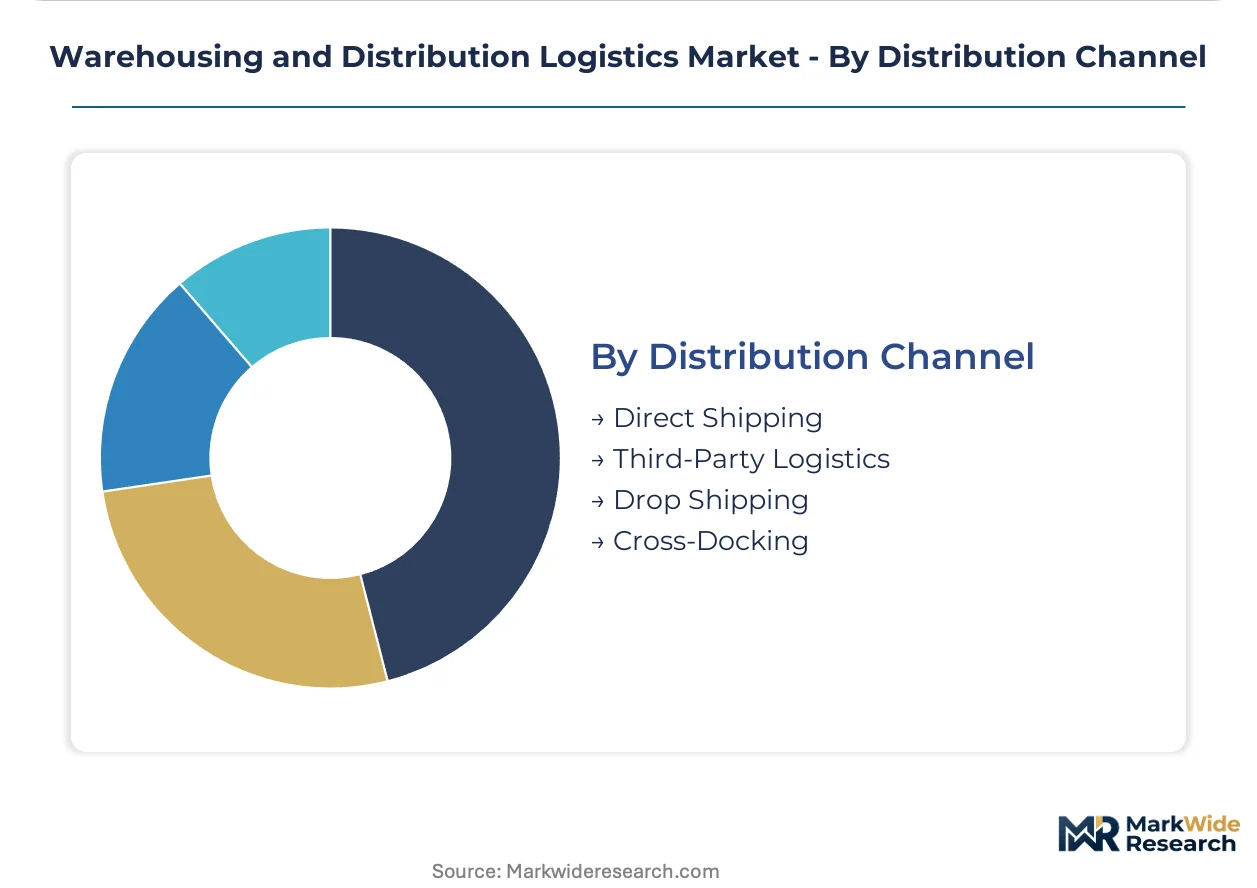
Third-Party Logistics leads by volume, with Cross-Docking showing the steepest expansion trajectory in perishable verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dense logistics corridor contrasts sharply with India's fragmented infrastructure, yet both markets are accelerating automation investment to compress fulfillment timelines. Facility deployment patterns diverge by labor cost strata and regulatory enforcement intensity.
United States
E-commerce platforms are retrofitting urban retail vacancies into micro-fulfillment centers to meet same-day delivery windows. EPA emissions rules for diesel-powered material handling fleets are forcing electrification timelines in California and Northeast corridor operations. The Inland Empire logistics cluster east of Los Angeles is absorbing record automation capital as warehouse density maxes out.
Germany
Third-party logistics operators are consolidating multi-client campuses to amortize WMS infrastructure costs across revenue streams. The EU F-Gas Regulation is accelerating refrigerant system replacement in cold-chain facilities serving pharmaceutical distributors. The Rhine-Ruhr logistics belt is witnessing facility modernization as labor scarcity compresses picking operation margins.
China
Smart logistics infrastructure deployment is concentrating in coastal manufacturing zones to synchronize with export processing timelines. MIIT and SAMR joint enforcement of GB standards on automated facility interoperability is favoring domestic system integrators. The Yangtze River Delta warehouse cluster is achieving throughput density previously requiring tenfold larger footprints through robotic cube systems.
India
Production-linked incentive structures under the PLI scheme are attracting foreign warehousing automation vendors to establish domestic manufacturing. BIS certification requirements for material handling equipment are extending procurement cycles for multinational operators. The Mumbai-Pune logistics corridor is emerging as the primary testing ground for RFID-enabled inventory visibility platforms in retail verticals.
Japan
Automotive parts distributors are deploying shuttle-based dense storage systems to achieve overnight replenishment cycles for just-in-sequence delivery. METI-backed standardization initiatives are accelerating interoperability between robotic material handling systems from competing OEMs. The Chubu region around Nagoya is concentrating automated facility investment to serve Toyota's consolidated supplier networks.
Warehousing and Distribution Logistics Market Competitive Environment
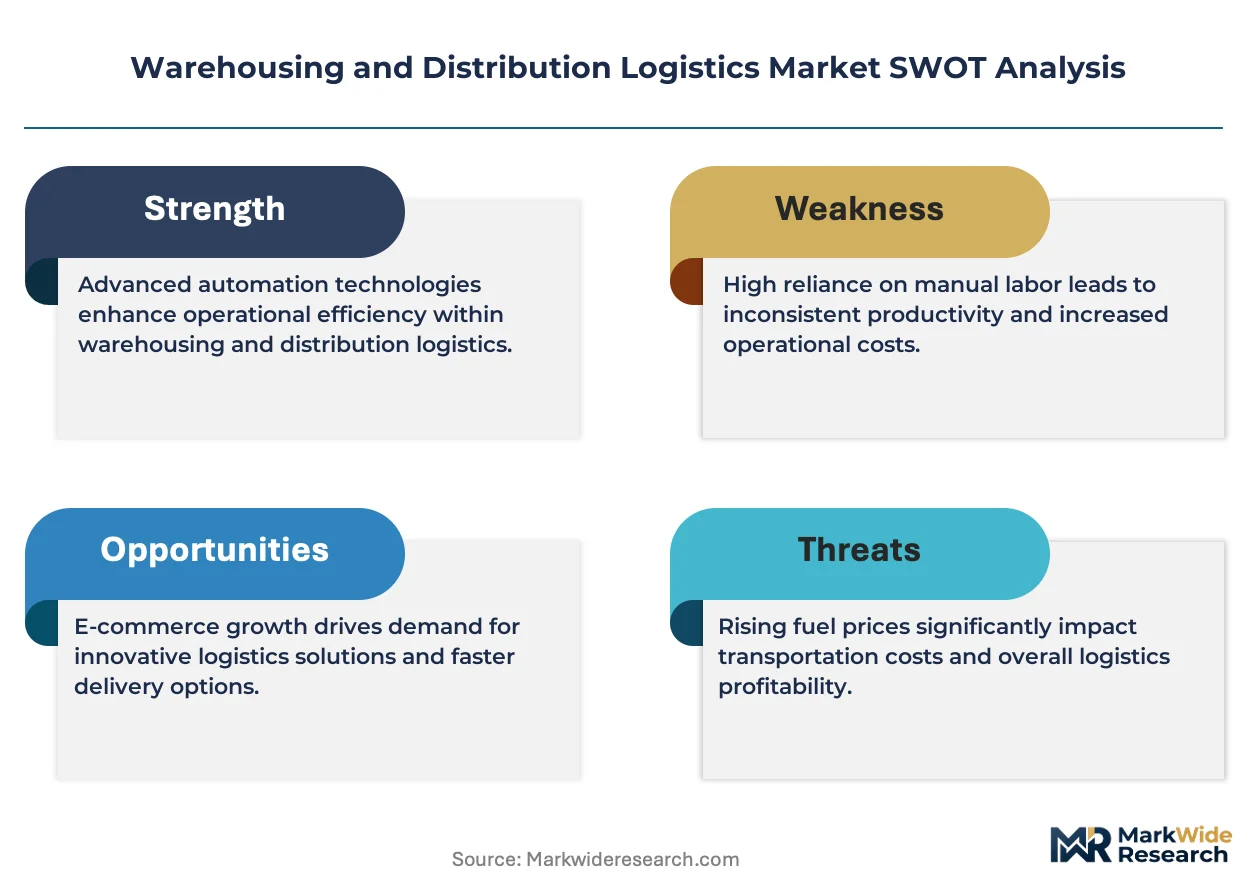
Top-tier vendors anchor contract logistics with proprietary WMS layers, while mid-tier operators compete on regional density and specialized vertical expertise. The market structure tilts toward consolidation as capital requirements for automation density rise. Three archetypes dominate: integrated express-courier networks, asset-light fourth-party logistics orchestrators, and captive e-commerce fulfillment operations. Competitive moves center on M&A to secure last-mile density and strategic partnerships to access robotics technology without captive R&D investment.
Among European-origin integrated logistics networks, Kuehne + Nagel, DB Schenker, and DHL Supply Chain occupy positions defined by multi-client campus models and shared-user automation infrastructure. These operators exemplify the asset-heavy archetype spreading capital costs across revenue streams. Amazon.com represents the captive fulfillment model, anchoring competitive posture through in-house robotics production and controlled last-mile density. GXO Logistics sits within the technology-differentiated tier, with RFID-enabled platforms serving as a reference point for inventory visibility specialization in retail contract logistics.
| Leading Market Players |
|---|
| Kuehne + Nagel |
| Nippon Express |
| Amazon.com |
| DB Schenker |
| XPO Logistics |
| DHL Supply Chain |
| CEVA Logistics |
| GEODIS |
| GXO Logistics |
| Others |
Value Chain & Pricing Dynamics
Captive in-house production of robotics and automated systems anchors Amazon.com's supply position while simultaneously compressing pricing power across third-party logistics tiers. This vertical integration choice forces asset-light operators to compete on software-defined orchestration rather than equipment ownership, widening margin dispersion between technology-leaders and space-providers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for automated storage equipment as domestic system integrators absorb demand previously served by German and Japanese OEMs. Contract logistics pricing stratifies across premium algorithmic-orchestration tiers, standard multi-client campus arrangements, and economy space-only warehousing, with differentiation hinging on WMS sophistication and real-time inventory synchronization capabilities. Pricing pressure stems from labor scarcity cost escalation in North American and European picking operations. E-commerce platforms exhibit the least price sensitivity due to captive fulfillment imperatives, while mid-market retailers face acute margin compression.
Supply Chain Analysis
Returns processing flows and refurbishment networks for robotic material handling equipment are emerging as critical supply chain nodes as AMR fleet penetration deepens. Manufacturing concentration for automated storage systems centers on Germany, Japan, and China, with shuttle-based dense storage hardware drawing from precision steel fabrication, industrial battery cells, and servo motor controllers. Single-source vulnerability persists for semiconductor components governing robotic navigation systems. Distribution runs through OEM-direct channels for large fleet deployments and systems integrator intermediaries for mid-market facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warehousing and distribution logistics functions as a stable compounder anchored by the irreversible shift from physical space arbitrage to algorithmic throughput optimization. E-commerce fulfillment velocity mandates and regulatory automation incentives create durable reinvestment opportunities.
For Market Incumbents: To counter margin compression from labor scarcity and automation capital intensity, DHL Supply Chain and comparable operators should deepen proprietary WMS platform penetration across multi-client campuses to sustain contract renewal premiums. Capacity addition in India's PLI-subsidized manufacturing zones offers cost structure relief for equipment procurement.
For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany and broader European cold-chain markets opens a window for specialized refrigerant system retrofit providers and ammonia-based cooling infrastructure specialists. India's fragmented logistics corridor presents the most penetrable geography for RFID-enabled inventory visibility platforms targeting retail verticals. A direct go-to-market angle through BIS-certified domestic manufacturing partnerships accelerates procurement access.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale third-party logistics operators with underinvested automation infrastructure because buyer consolidation in German and British markets supports vendor diversification strategies that favor multi-client campus models. The acquisition target archetype combines regional density with specialized vertical expertise in pharmaceutical GDP compliance or perishable cold-chain. Monitor MIIT enforcement intensity on GB standards interoperability as the inflection signal for domestic Chinese system integrator valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary WMS Platform Deployment | DHL Supply Chain leverages algorithmic orchestration to sustain margin premiums in contract logistics renewals. |
| AMR Fleet Integration | GXO Logistics absorbs intermediate-distance transport tasks to achieve throughput parity with smaller footprints. |
| Cold-Chain Refrigerant Retrofit | German operators face accelerated EPA and EU F-Gas Regulation compliance timelines for ammonia-based systems. |
| Micro-Fulfillment Center Buildout | Amazon.com retrofits urban retail vacancies to compress same-day delivery windows in dense corridors. |
| RFID-Enabled Inventory Visibility | Retail verticals in India reduce cycle-count labor and shrinkage through item-level tracking platform adoption. |
Study Parameters
Bottom-up e-commerce and pharmaceutical fulfillment modeling reconciled against top-down automated equipment shipment tracking forms the analytical core of this study. Primary interviews with warehouse operations directors, third-party logistics procurement leads, systems integration engineers, and retail supply chain planners combined with secondary validation against customs trade data, SEC 10-K filings, MIIT infrastructure disclosures, and EU F-Gas Regulation implementation reports. Triangulation between demand-side service procurement patterns and supply-side OEM production schedules ensures coherence across volume estimates.
Input-output matrices map facility throughput velocities, automation penetration rates, and labor cost strata across service type, technology stack, and end-user vertical dimensions throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against macroeconomic logistics intensity indicators. Industry-specific forecast inputs include e-commerce gross merchandise value trajectories and pharmaceutical serialization mandate enforcement calendars.
Revisions become necessary when MIIT digital transformation enforcement intensity shifts, EU F-Gas Regulation phasedown timelines accelerate, or autonomous mobile robot OEM supply constraints materially extend. Practitioners should monitor BIS certification processing delays in India and EPA emissions rule implementation in California for early signals of procurement cycle disruption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Japan E-Commerce Logistics Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Tanker Cargo Ship Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
Logistics Visualization System Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
Asia Pacific Finished Vehicle Logistics Market