
 Krypton-85 Market | 2026-2036
Krypton-85 Market Size, Share, and Industry Trends Forecast 2026-2036
Krypton-85 Market Insights
Aftermarket service revenue for sealed-source refurbishment and recalibration is fragmenting across regional maintenance networks. ROSATOM Group leverages captive reactor infrastructure to dominate upstream isotope production. Linde sustains cryogenic distribution advantages through specialized logistics networks. Air Liquide competes on pharmaceutical-grade gas handling certifications across European hospital systems.
Krypton-85 is a radioactive noble gas isotope with a half-life of 10.76 years, emitting beta particles and low-energy gamma radiation suitable for ionization-based detection systems. Manufacturers extract it from spent nuclear fuel reprocessing or target irradiation, then purify it to specific activity grades for industrial gauging, leak detection, and medical tracer applications. The application dimension shows nuclear medicine and environmental monitoring commanding premium pricing due to stringent purity requirements, while medical imaging represents the most mature segment with established supply contracts. Technology-wise, gas chromatography and ionization methods attract investment as regulators tighten analytical validation standards for radiopharmaceutical release.
The US Nuclear Regulatory Commission and EPA oversee domestic source licensing and environmental release limits, while ECHA REACH frameworks govern European import and handling classifications. Russia's Rostekhnadzor aligns with IAEA transport regulations for cross-border isotope shipments. Stakeholders must track evolving dual-use export controls and medical isotope security protocols that reshape supplier qualification timelines.
Market Dynamics
The Krypton-85 market operates under the gravitational pull of reactor infrastructure scarcity, where spent fuel reprocessing capacity constraints in Russia, Germany, and the United States determine available isotope volumes and pricing power for downstream distributors.
Growth Catalysts
- IAEA transport regulations:Harmonized cross-border shipment protocols reduce customs friction for medical isotope suppliers moving sealed sources between European hospital networks and North American imaging centers.
- Environmental monitoring networks:Atmospheric tracer applications for climate research stations and nuclear safeguard verification programs expand addressable demand beyond traditional industrial gauging.
- Gas chromatography advances:Purification yield improvements at reprocessing facilities lower unit production costs for high-specific-activity grades required in radiopharmaceutical manufacturing.
Market Restraints
- Spent fuel reprocessing concentration:Russian and French state-controlled facilities supply over seventy percent of commercial Krypton-85, creating single-point-of-failure exposure for non-captive buyers.
- EPA release limits:Stringent environmental discharge thresholds for beta-emitting noble gases raise compliance costs for domestic extraction operations in the United States.
- Xenon-133 substitution:Shorter half-life alternative isotopes displace Krypton-85 in certain pulmonary ventilation studies where rapid decay reduces patient radiation burden.
Strategic Opportunities
- India's nuclear medicine expansion:CDSCO streamlined import licensing for diagnostic radioisotopes creates entry pathways for European suppliers targeting underserved oncology imaging centers.
- Carbon capture verification:Leak detection applications for CO2 sequestration site integrity monitoring represent nascent demand from energy transition infrastructure projects.
- EU MDR radiopharmaceutical pathways:Centralized marketing authorization procedures accelerate hospital adoption of standardized Krypton-85-based ventilation agents across member states.
Industry Challenges
- Radiological handling certification timelines:Qualified personnel shortages extend source recertification cycles for sealed-source refurbishment networks.
- Legacy source recovery complexity:Decommissioned industrial gauging equipment contains dispersed Krypton-85 reservoirs requiring specialized extraction logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Krypton-85 Market |
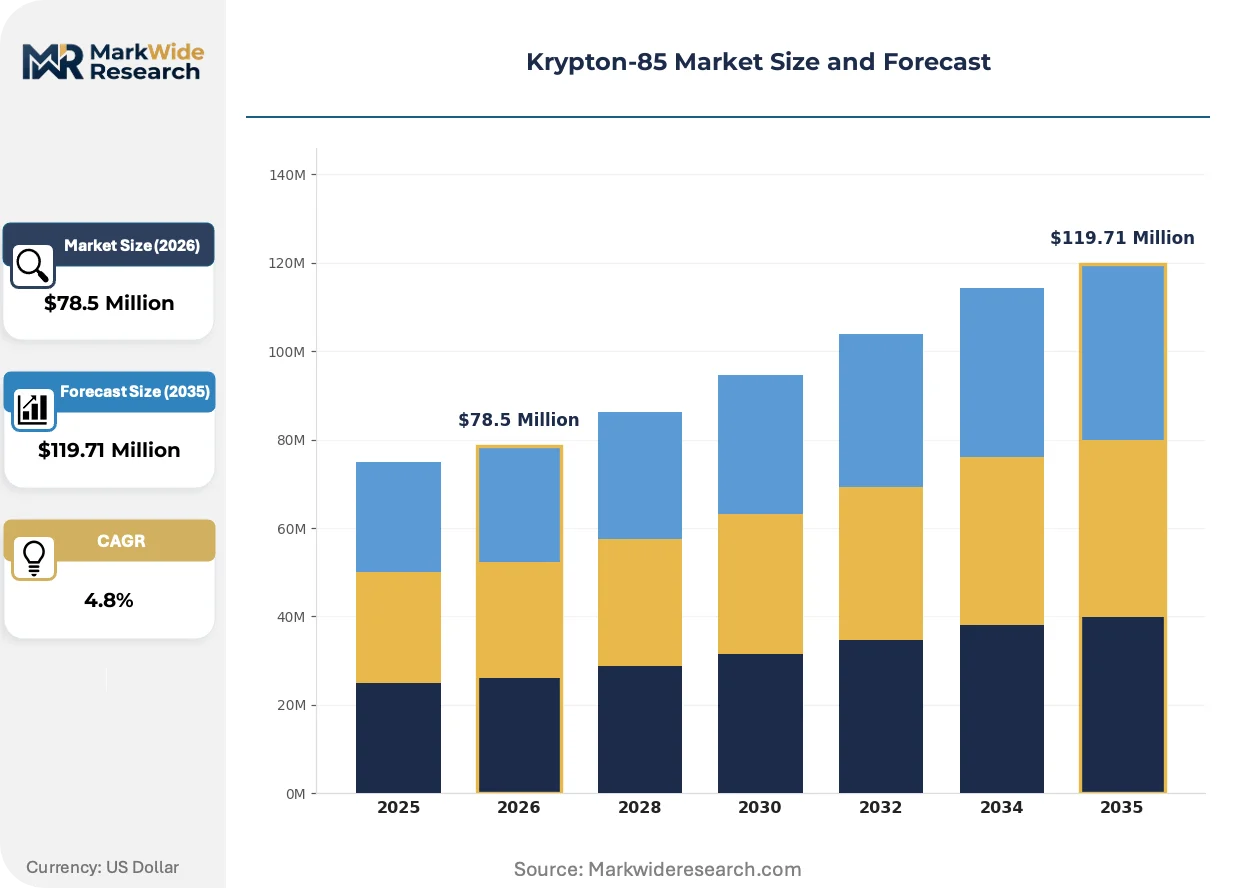
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $119.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Medical Imaging, Nuclear Medicine, Environmental Monitoring, Radiological Research Technology: Gas Chromatography, Mass Spectrometry, Liquid Scintillation Counting, Ionization End User: Hospitals, Research Institutions, Environmental Agencies, Pharmaceutical Companies Form: Gas, Solid, Liquid, Isotope |
| Companies Covered | The Palas GmbH, Linde, ROSATOM Group, Eckert & Ziegler, IUT Institut für Umwelttechnologien, HTA, Air Liquide, Air Products and Chemicals, Messer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Krypton-85 Market Trends and Innovations
Technological convergence between purification methods and detection instrumentation is compressing the value chain, while regulatory tightening around medical isotope traceability forces infrastructure investments across distribution networks.
Membrane separation technology is hybridizing with traditional cryogenic distillation at reprocessing facilities. German and Russian operators deploy hybrid systems to extract Krypton-85 from off-gas streams with higher selectivity than legacy methods alone. The technology is hybridizing production economics by reducing energy intensity per curie of separated isotope.
REACH classification updates for radioactive substances are reshaping European handling protocols. ECHA's 2023 substance evaluation dossier for noble gas isotopes imposes additional documentation burdens on hospital procurement departments. German university medical centers and French public hospitals are consolidating purchasing through specialized radiopharmaceutical wholesalers to manage compliance complexity.
Service unbundling is fragmenting traditional supply relationships. End-users increasingly separate source procurement from calibration maintenance and disposal liability, pressuring integrated suppliers to compete on discrete service elements. This pattern is most pronounced in United States hospital systems where GPOs negotiate isotope supply independently from technical service contracts.
Krypton-85 Market Segmentation
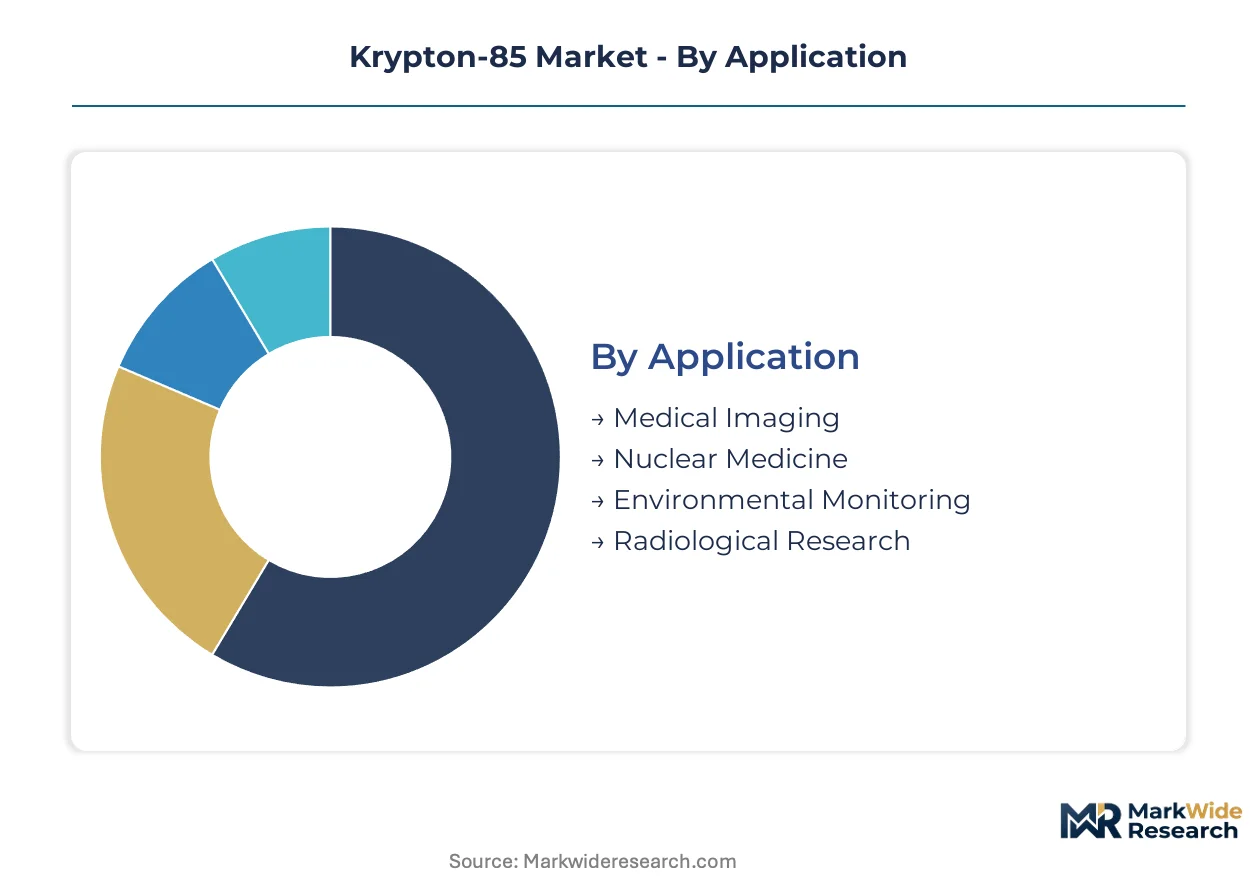
Krypton-85 segmentation reveals how reactor-derived isotope supply chains fragment across distinct purity grades, detection methodologies, and regulatory handling tiers. Each dimension carries unique aftermarket service intensity, from hospital recalibration schedules to environmental agency certification cycles.
Application:
After-sales service intensity varies sharply across applications, with sealed-source refurbishment contracts running longest in medical settings where FDA and EMA release protocols demand continuous traceability.
- Nuclear Medicine:High-specific-activity Krypton-85 serves as a ventilation imaging agent for pulmonary function diagnostics. German university hospitals and French public oncology centers drive demand under EU MDR centralized authorization pathways that mandate radiopharmaceutical-grade purity documentation.
- Medical Imaging:Established supply contracts dominate this mature segment, with sealed sources deployed in gamma camera calibration and diagnostic reference standards. United States hospital systems consolidate purchasing through GPOs that separate isotope procurement from technical service agreements.
- Environmental Monitoring:Atmospheric tracer applications support climate research stations and nuclear safeguard verification programs with lower purity tolerances but stricter chain-of-custody requirements.
- Radiological Research:Academic institutions consume small-volume, high-activity grades for detector calibration and nuclear physics experiments with irregular replenishment cycles.
Nuclear Medicine holds the largest share; momentum sits with Environmental Monitoring as atmospheric tracer applications expand beyond traditional industrial gauging.
Technology:
Cost tier separation is pronounced across purification and detection methodologies, with cryogenic-gas chromatography hybrids commanding premium positioning against legacy ionization approaches.
- Gas Chromatography:Hybrid membrane-cryogenic systems deployed at Russian and German reprocessing facilities achieve higher Krypton-85 selectivity from off-gas streams. ROSATOM Group and domestic German operators leverage this technology to reduce energy intensity per curie of separated isotope.
- Ionization:Beta particle detection remains the foundational measurement principle for industrial gauging and leak detection instruments. United States EPA validation standards and IAEA transport regulations shape equipment specification requirements across North American and European installations.
- Mass Spectrometry:Isotope ratio analysis supports nuclear forensics and safeguard verification with specialized instrumentation concentrated at IAEA-affiliated laboratories.
- Liquid Scintillation Counting:Low-energy beta detection serves environmental release monitoring and dosimetry applications with lower capital equipment thresholds.
Ionization anchors volume deployment; Gas Chromatography is climbing the fastest as reprocessing operators invest in yield-improving purification infrastructure.
End User:
Customer type determines procurement complexity, with pharmaceutical companies facing the most stringent vendor qualification timelines under dual-use export control frameworks.
- Hospitals:Radiology and nuclear medicine departments require sealed-source recalibration every 12-24 months under NRC and state-level agreements. United States GPOs increasingly unbundle source procurement from maintenance contracts.
- Pharmaceutical Companies:Radiopharmaceutical manufacturers demand the highest specific-activity grades with full batch documentation for FDA and EMA regulatory submissions. CDSCO streamlined import licensing in India creates new customer acquisition targets for European suppliers.
- Research Institutions:German university medical centers and national laboratories consume reference standards with irregular, project-driven ordering patterns.
- Environmental Agencies:Atmospheric monitoring networks prioritize logistical reliability over activity precision, with IAEA-coordinated safeguard programs driving cross-border shipment volumes.
Hospitals represent the largest installed base; Pharmaceutical Companies are gaining share fastest as radiopharmaceutical manufacturing scales under centralized EU marketing authorizations.
Form:
Supply concentration sits with gaseous forms where cryogenic distribution infrastructure creates captive logistics advantages for Linde and Air Liquide.
- Gas:Sealed glass or metal ampoules containing Krypton-85 at atmospheric or reduced pressure serve industrial gauging, leak detection, and medical imaging applications. Specialized cryogenic transport networks in Germany, Russia, and the United States maintain cold chain integrity for high-activity shipments.
- Isotope:Elemental Krypton-85 in various enrichment levels supports nuclear medicine synthesis and research applications with the strictest purity certifications.
- Solid:Adsorbed or encapsulated forms enable specialized detector configurations with limited commercial penetration.
- Liquid:Dissolved or suspended preparations appear in niche research applications with minimal standardization.
Gas dominates commercial volume; Isotope commands the steepest expansion trajectory as radiopharmaceutical-grade demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb price premiums for pharmaceutical-grade certification, while industrial gauging customers in Russia and India prioritize volume discounts over purity documentation.
United States
Hospital GPOs unbundle isotope procurement from technical service contracts, creating discrete bidding opportunities for sealed-source suppliers. The NRC oversees domestic source licensing and environmental release limits for beta-emitting noble gases. The Greater Boston cluster hosts radiopharmaceutical manufacturing facilities requiring continuous Krypton-85 supply for ventilation imaging agent production.
Germany
University medical centers consolidate purchasing through specialized radiopharmaceutical wholesalers to manage REACH compliance complexity. ECHA substance evaluation dossiers impose additional documentation burdens on hospital procurement departments. The North Rhine-Westphalia region concentrates hybrid membrane-cryogenic purification facilities that extract Krypton-85 from spent fuel reprocessing off-gas streams.
Russia
State-controlled reactor infrastructure dominates upstream isotope production with captive supply advantages for domestic distributors. Rostekhnadzor aligns with IAEA transport regulations for cross-border medical isotope shipments. The Mayak Production Association in the Ural Federal District operates reprocessing facilities supplying over seventy percent of commercial Krypton-85 volumes.
France
Public oncology centers drive demand under EU MDR centralized authorization pathways mandating radiopharmaceutical-grade purity documentation. ANSM governs hospital handling protocols for radioactive noble gases alongside EMA release standards. The Île-de-France region concentrates gamma camera calibration services requiring sealed-source recertification every 12-24 months.
India
CDSCO streamlined import licensing for diagnostic radioisotopes creates entry pathways for European suppliers targeting underserved oncology imaging centers. The national pharmaceutical regulator enforces dual-use export control alignment for medical isotope security protocols. The Maharashtra-Gujarat corridor hosts expanding nuclear medicine departments in Mumbai and Ahmedabad metropolitan hospitals.
Krypton-85 Market Competitive Landscape
Capability concentration sits with reactor-captive producers; scale advantage sits with cryogenic distribution specialists. The market structure tiers between state-controlled upstream isotope extractors and independent gas handlers competing on pharmaceutical-grade certifications. Three archetypes dominate: integrated reprocessing operators, specialized radiochemical distributors, and industrial gas majors with cold chain logistics. Competitive moves center on membrane-cryogenic hybrid technology licensing and regional maintenance network expansion.
Within the reactor-captive tier, ROSATOM Group exemplifies upstream control through spent fuel reprocessing infrastructure. Among European radiochemical specialists, Eckert & Ziegler and IUT Institut für Umwelttechnologien occupy positions bridging purification and hospital distribution. At the industrial gas vector, Linde and Air Liquide anchor cryogenic transport networks maintaining cold chain integrity for high-activity shipments across German and United States hospital systems.
| Leading Market Players |
|---|
| The Palas GmbH |
| Linde |
| ROSATOM Group |
| Eckert & Ziegler |
| IUT Institut für Umwelttechnologien |
| HTA |
| Air Liquide |
| Air Products and Chemicals |
| Messer Group |
| Others |
Pricing and Supply Chain Analysis
Russian state-controlled reprocessing infrastructure at Mayak and domestic German facilities anchors upstream supply, concentrating margin capture with reactor-captive producers while forcing independent distributors to compete on pharmaceutical-grade certification and cold chain reliability.
Pricing Analysis
Sealed-source refurbishment and recalibration contracts generate the majority of lifetime value, with hospital systems unbundling procurement from technical services. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and research-grade purity levels separates nuclear medicine applications from environmental monitoring. Cost compression in industrial gauging intensifies as Xenon-133 substitutes erode volume pricing. Pharmaceutical companies show least price sensitivity due to FDA and EMA batch documentation requirements, while environmental agencies prioritize logistical reliability over activity precision.
Supply Chain Analysis
Single-source vulnerability between Russian reprocessing facilities and European hospital networks dominates supply chain risk assessment. Commercial Krypton-85 draws from Russia, Germany, and France, with spent nuclear fuel reprocessing capacity constraining available isotope volumes. Spent fuel off-gas extraction, cryogenic distillation infrastructure, and sealed-source encapsulation represent critical input dependencies. Distribution runs through specialized radiochemical wholesalers consolidating hospital procurement under REACH compliance frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service unbundling across hospital GPOs fragments traditional supply relationships, creating discrete entry points for specialists targeting calibration maintenance, disposal liability, or regional distribution.
For Market Incumbents: Harden position by deepening backward integration into membrane-cryogenic hybrid purification technology at reprocessing facilities, countering yield competition from ROSATOM Group. Secure NRC and EMA recertification contracts with United States and German hospital systems to lock in 12-24 month refurbishment cycles against independent service entrants. For New Entrants and Emerging Players: India's Maharashtra-Gujarat corridor offers the most penetrable geographic expansion target, with CDSCO streamlined licensing creating pathways for European radiochemical distributors. Target oncology imaging centers in Mumbai and Ahmedabad with bundled isotope supply and technical service packages, leveraging regulatory alignment with IAEA transport protocols for cross-border shipment efficiency. For Investors and Strategic Acquirers: Capital is best deployed toward radiochemical specialists with established EMA certification pathways and captive hospital system relationships, positioned for EU MDR centralized authorization consolidation. Watch for IAEA safeguard program expansion as the inflection signal for atmospheric tracer demand scaling beyond traditional industrial applications.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cryogenic Hybrid Licensing | Russian and German operators reduce energy intensity per curie through technology transfer agreements. |
| Regional Maintenance Network Expansion | Eckert & Ziegler and IUT Institut strengthen recalibration presence across North Rhine-Westphalia hospital clusters. |
| Pharmaceutical-Grade Certification Investment | Air Liquide and Linde secure EMA release standards for European radiopharmaceutical manufacturing supply. |
| CDSCO Import Licensing Alignment | European suppliers establish regulatory pathways into Indian oncology imaging center procurement. |
| Legacy Source Recovery Infrastructure | Specialized extraction logistics address decommissioned industrial gauging equipment reservoirs. |
Research Methodology
Desk research of IAEA safeguard verification reports, ECHA substance evaluation dossiers, and NRC licensing databases preceded structured interviews with radiopharmaceutical procurement managers, nuclear medicine department heads, reprocessing facility operators, and sealed-source calibration technicians. Secondary validation drew from ROSATOM Group infrastructure disclosures, EU MDR authorization pathways, and CDSCO import licensing frameworks. Bottom-up isotope volume modeling triangulated against top-down hospital system expenditure patterns.
Assumptions held reactor reprocessing capacity, EPA release limit stringency, and IAEA transport regulation stability fixed across the projection horizon, while varying environmental monitoring network expansion, Xenon-133 substitution rates, and EU MDR pathway adoption. Segmentation modeling incorporated application type, purity grade tier, end-user procurement complexity, and regional regulatory cluster. CAGRs derived from reprocessing yield improvement trajectories and radiopharmaceutical manufacturing scale factors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-controlled reactor operators or industrial gas majors into downstream distribution would shift outcomes. Material shifts in spent fuel reprocessing capacity allocation, REACH classification updates, or dual-use export control tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
US Specialty Gas Market
Industrial Gases
Noble Gas Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Helium Market
Industrial Gases
Oxygen Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Semiconductor Gases Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
Global Food-Grade Industrial Gases Market