
 Portable Buffet and Drop-In Ranges Market | 2026-2036
Portable Buffet and Drop-In Ranges Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Buffet and Drop-In Ranges Market Analytics
Equipment leasing and managed-service finance models is narrowing the capital barrier for mid-sized restaurant groups and independent hotels seeking commercial-grade range installations. Electrolux leverages its European manufacturing footprint to sustain cost-competitive positioning in electric and induction portfolios. Hatco Corporation anchors its presence through specialized drop-in warming and cooking solutions for buffet-centric operations. Bosch competes on integrated kitchen ecosystems that bundle ranges with ventilation and refrigeration controls.
Portable buffet and drop-in ranges comprise self-contained or counter-integrated cooking appliances engineered for commercial foodservice environments, typically constructed from stainless steel with outputs ranging from 15,000 to 150,000 BTU depending on fuel type and burner configuration; these units serve front-of-house display cooking, banquet service lines, and modular kitchen layouts where fixed infrastructure proves impractical. Induction ranges command premium positioning due to precise temperature control and reduced ambient heat load, while gas ranges retain volume leadership in legacy installations and outdoor catering deployments. The freestanding installation category captures mobile catering and temporary event demand, whereas built-in and drop-in formats dominate hotel buffet renovations where spatial integration drives specification decisions.
The US Department of Energy enforces minimum efficiency standards for commercial cooking equipment, compelling manufacturers to redesign burner systems and insulation packages. NSF International certification governs food-contact surfaces and sanitation design, creating a compliance threshold that filters out lower-tier imports. The Environmental Protection Agency's emissions guidelines for commercial kitchens in urban air-quality districts further steer specification toward induction and sealed-burner gas technologies. Stakeholders must monitor evolving municipal decarbonization mandates that increasingly prohibit natural gas hookups in new commercial construction, as this regulatory trajectory will reshape fuel-type demand across installation categories.
Market Dynamics
Electrification mandates in commercial construction are forcing equipment specification toward induction platforms, compressing gas range refresh cycles and redrawing manufacturer R&D priorities across fuel-type portfolios.
Growth Catalysts
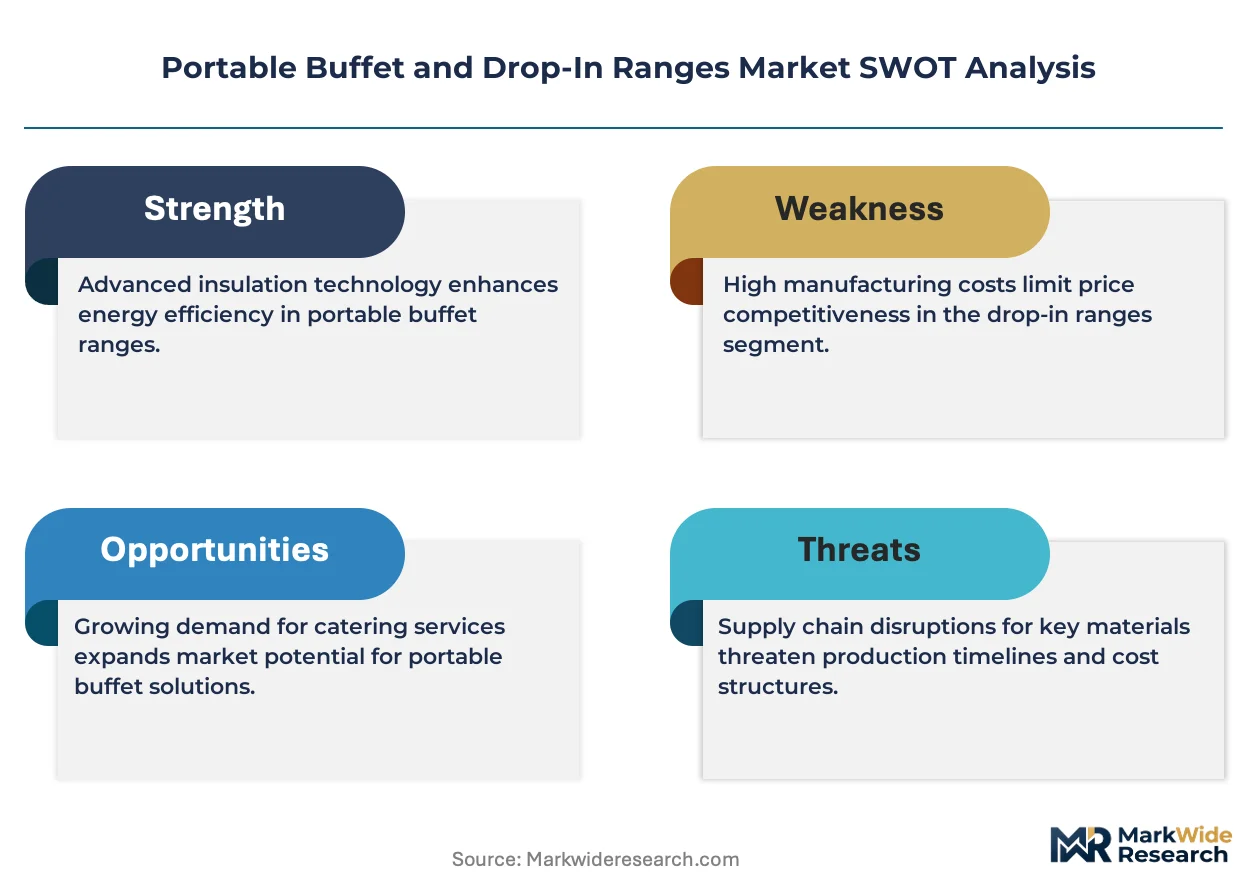
- Commercial Kitchen Efficiency Standards:The US Department of Energy's efficiency thresholds compel burner system redesigns and insulation upgrades, pulling replacement demand forward in full-service restaurant chains.
- Hospitality Construction Activity:Elevated hotel renovation pipelines in the United States concentrate specification volume for built-in buffet formats where spatial integration governs procurement decisions.
- Induction Technology Maturation:Precise temperature control and reduced ambient heat loads position induction ranges as the preferred platform for front-of-house display cooking installations.
Market Restraints
- Copper and Stainless Steel Input Volatility:Commodity price swings for 304-grade stainless and copper winding materials compress margin visibility for electric range manufacturers.
- Legacy Gas Infrastructure Lock-In:Existing natural gas hookups in established commercial kitchens create sunk-cost resistance against fuel-type conversion.
- NSF Certification Timeline Friction:Food-contact surface and sanitation design approval cycles filter out lower-tier import competition but extend time-to-market for new entrants.
Strategic Opportunities
- Equipment-as-a-Service Models:Leasing and managed-service finance structures narrow capital barriers for mid-sized restaurant groups seeking commercial-grade induction installations.
- Municipal Decarbonization Mandates:Urban air-quality districts prohibiting natural gas hookups in new commercial construction accelerate specification shifts toward all-electric portfolios.
- Outdoor Catering Expansion:Freestanding portable range demand from mobile event operators represents an underpenetrated channel for sealed-burner gas configurations.
Industry Challenges
- Field Service Technician Shortage:Specialized induction repair expertise lags equipment deployment, lengthening mean-time-to-repair for high-output buffet installations.
- Integration Complexity with Building Management Systems:Smart kitchen ecosystems require protocol harmonization between range controls and ventilation or refrigeration subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Buffet and Drop-In Ranges Market |
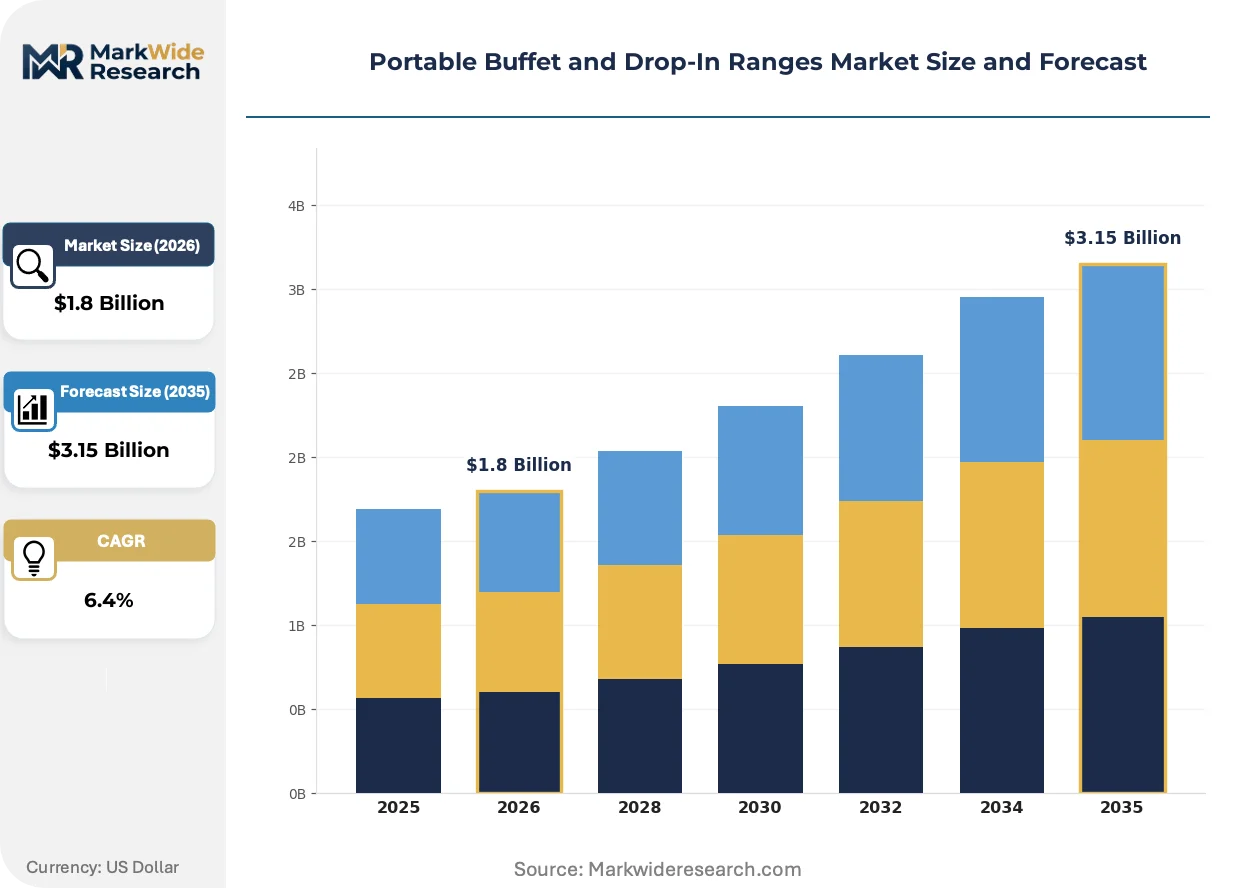
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Ranges, Induction Ranges, Gas Ranges, Charcoal Ranges End User: Hotels, Catering Services, Restaurants, Home Users Installation: Built-In, Freestanding, Drop-In, Modular Power Source: Electricity, Natural Gas, Propane, Biomass |
| Companies Covered | GE Appliances, LG Electronics, Bosch, Café, Thor Kitchen, Frigidaire, Hatco Corporation, SKS Ranges, Electrolux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Buffet and Drop-In Ranges Market Evolving Landscape
Active specification is migrating from standalone equipment procurement toward integrated kitchen ecosystems, compressing vendor count and elevating system-level performance guarantees as procurement criteria.
Induction coil technology is migrating from standard copper-wound configurations toward advanced ferrite-core designs that reduce energy loss and extend duty cycles. High-volume hotel buffet operators are specifying these platforms for continuous-service breakfast lines. The technology shift is migrating from premium tier positioning toward mid-market penetration, compressing price premiums that previously separated induction from gas alternatives.
The Environmental Protection Agency's emissions guidelines for commercial kitchens in urban air-quality districts are tightening venting requirements for open-flame equipment. Manufacturers are responding with sealed-burner gas systems and accelerated induction platform development. Full-service restaurant chains in California and New York metropolitan areas face the steepest compliance curves, driving specification toward electric alternatives ahead of national adoption curves.
Buyer procurement patterns are consolidating vendor relationships around single-source kitchen ecosystem providers. Independent hotels and mid-sized restaurant groups are abandoning multi-vendor equipment sourcing in favor of bundled range-ventilation-refrigeration packages. This concentration is most visible in United States hospitality construction, where general contractors prioritize single-point accountability for kitchen subsystem performance.
Portable Buffet and Drop-In Ranges Market Segmentation
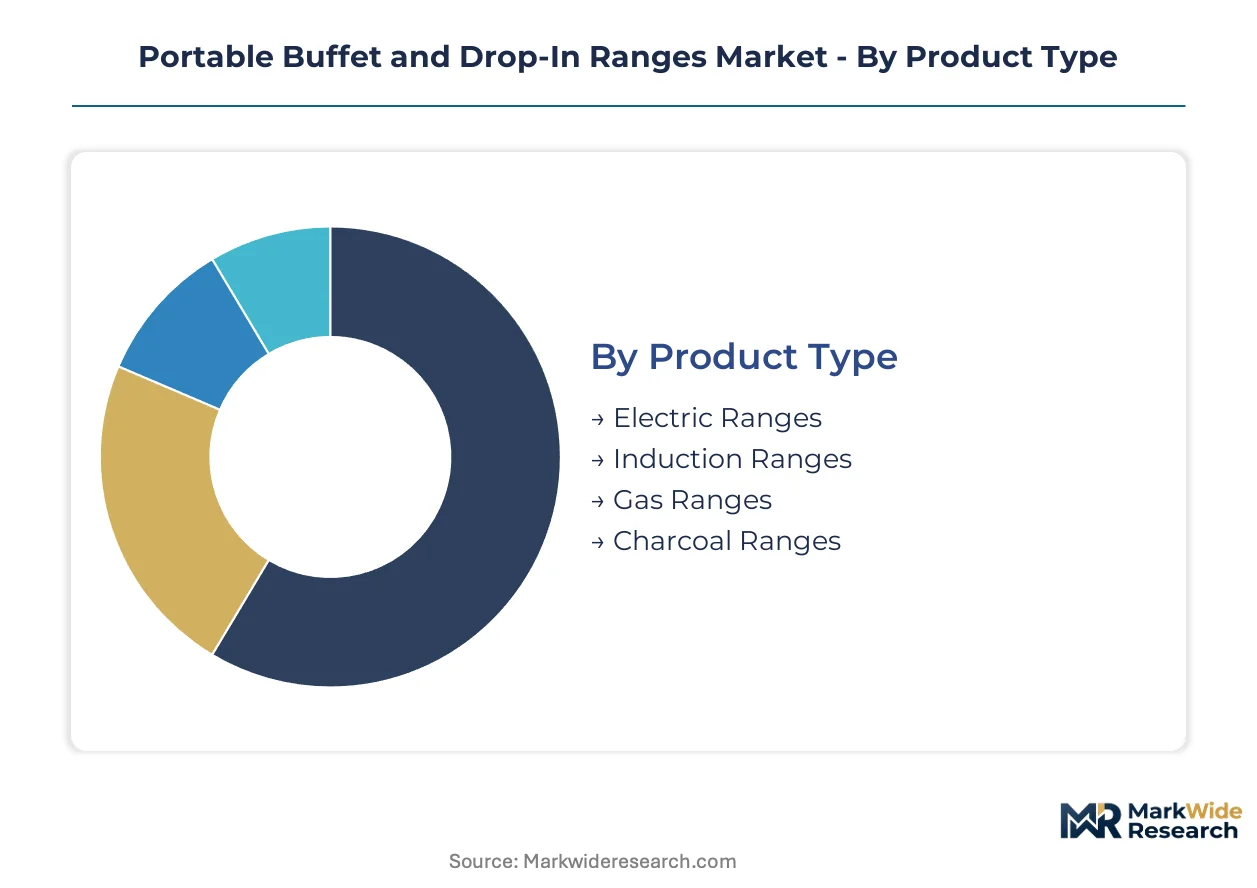
Segmentation in the portable buffet and drop-in ranges market reveals distinct procurement patterns across fuel technologies, installation formats, and operational environments. Equipment specification diverges sharply between front-of-house display applications demanding precise thermal control and back-of-house production lines prioritizing output volume. Understanding these segment boundaries enables manufacturers to align R&D investment with the highest-velocity demand corridors.
Product Type:
The use-case spectrum spans legacy gas infrastructure in established commercial kitchens through emerging induction platforms engineered for energy compliance and ambient heat reduction.
- Induction Ranges:Ferrite-core coil designs reduce energy loss while enabling precise temperature modulation for front-of-house display cooking. Hotel buffet operators in California and New York metropolitan areas specify these platforms ahead of municipal decarbonization mandates prohibiting natural gas hookups.
- Gas Ranges:Open-flame and sealed-burner configurations deliver 15,000 to 150,000 BTU outputs for high-volume production environments. Full-service restaurant chains retain these installations where existing natural gas infrastructure creates sunk-cost resistance against fuel-type conversion.
- Electric Ranges:Resistance-element platforms occupy mid-market positioning between induction precision and gas output intensity.
- Charcoal Ranges:Specialized units serve outdoor catering and exhibition cooking applications requiring distinct flavor profiles.
The dominant share belongs to Gas Ranges, while Induction Ranges is closing the gap fastest.
End User:
Procurement authority concentrates in hospitality construction pipelines and renovation cycles, with specification criteria diverging between capital-intensive hotel chains and event-driven mobile operators.
- Hotels:Built-in and drop-in formats dominate renovation specifications where spatial integration governs procurement decisions. United States hospitality construction activity concentrates demand for buffet-centric warming and cooking solutions with ventilation subsystem compatibility.
- Restaurants:Full-service chains drive equipment refresh cycles through efficiency standard compliance and front-of-house display cooking investments.
- Catering Services:Freestanding portable configurations serve mobile event operators with temporary power and venting requirements.
- Home Users:Residential applications represent marginal volume concentrated in premium outdoor kitchen installations.
Hotels command the largest procurement volume, though Catering Services is expanding most quickly as outdoor event formats proliferate.
Installation:
Physical integration requirements shape margin structures, with permanent infrastructure demanding certified technician deployment and modular formats enabling field reconfiguration.
- Built-In:Counter-integrated appliances require coordinated specification with general contractors during hospitality construction. These installations carry extended performance guarantees and single-point accountability clauses favoring bundled kitchen ecosystem providers.
- Drop-In:Self-contained units designed for existing counter cutouts serve hotel buffet renovations where spatial constraints limit infrastructure modification.
- Freestanding:Mobile configurations with integrated fuel storage and ventilation support temporary event deployment without fixed infrastructure.
- Modular:Reconfigurable platforms enable kitchen layout adaptation across banquet service lines and seasonal menu transitions.
Built-In installations retain the highest average transaction value, while Modular formats are gaining share fastest among mid-sized restaurant groups seeking operational flexibility.
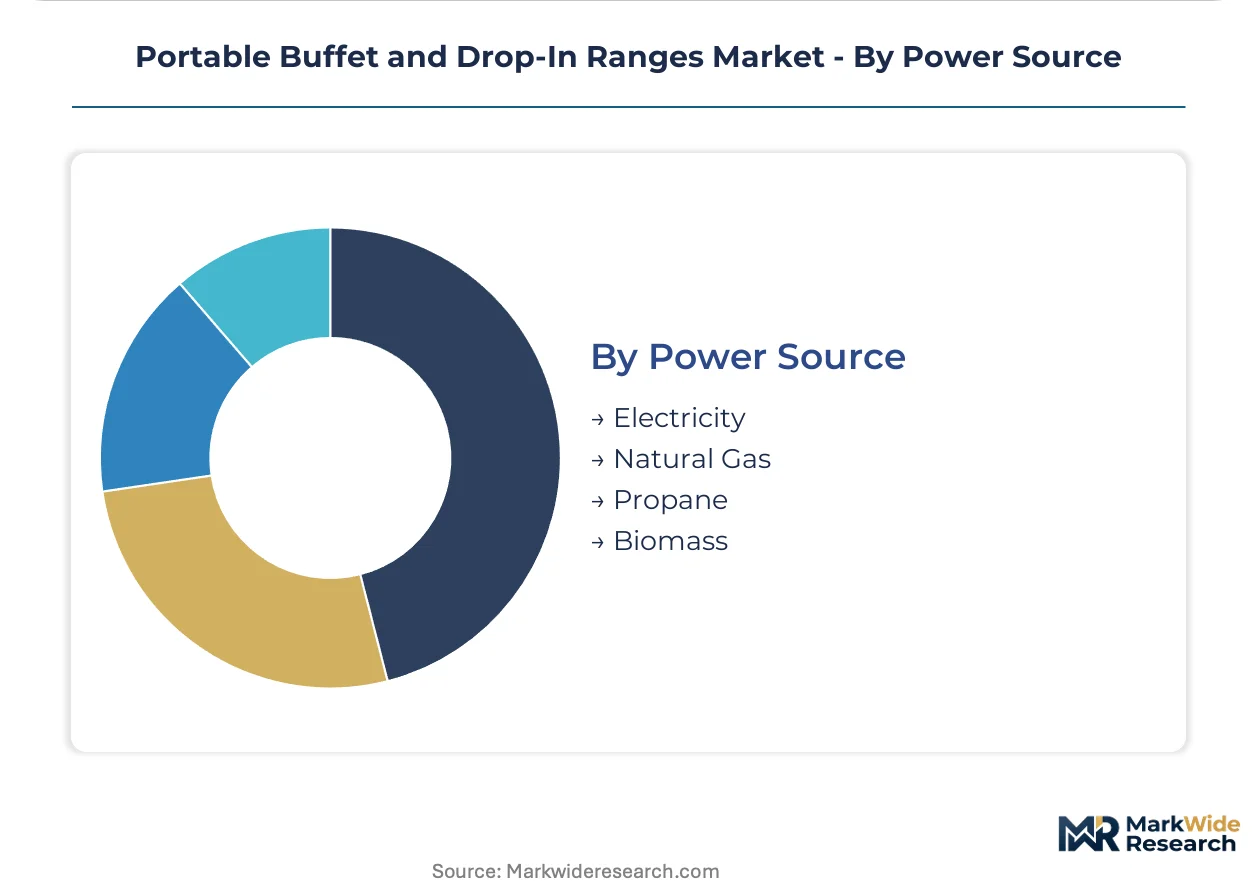
Power Source:
Regulatory trajectory across urban air-quality districts is compressing fossil fuel specification timelines and accelerating electrification investment in new commercial construction.
- Electricity:Grid-connected induction and resistance platforms align with EPA emissions guidelines and municipal decarbonization mandates. The US Department of Energy's commercial kitchen efficiency standards pull replacement demand toward these configurations.
- Natural Gas:Legacy hookups in established commercial kitchens create infrastructure lock-in despite tightening venting requirements for open-flame equipment.
- Propane:Portable cylinder configurations serve outdoor catering and remote event locations without grid access.
- Biomass:Pellet and wood-fired units occupy niche positioning in exhibition cooking and sustainability-marketed hospitality concepts.
Electricity dominates new specification, while Propane retains resilient demand in mobile catering channels beyond grid infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in commercial cooking equipment tilt toward net-import dependence in developed hospitality markets while manufacturing concentration sustains surplus capacity in select Asian production bases. Equipment flows track renovation cycles and regulatory compliance timelines rather than pure cost arbitrage.
United States
Hotel construction pipelines in Florida and Texas concentrate specification volume for built-in buffet formats. The US Department of Energy's commercial kitchen efficiency standards compel burner system redesigns and accelerate replacement demand in full-service restaurant chains. California's municipal decarbonization mandates prohibiting natural gas hookups in new commercial construction steer specification toward induction platforms ahead of national adoption curves.
Germany
Electrolux leverages its European manufacturing footprint to sustain cost-competitive positioning in electric and induction portfolios. The EU Green Deal's building renovation targets compress refresh cycles for commercial kitchen infrastructure. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia anchor component fabrication for sealed-burner gas systems and advanced insulation packages.
China
Domestic hospitality construction in tier-one cities concentrates demand for modular buffet configurations. The country's national energy efficiency standards for commercial appliances pull manufacturing investment toward induction coil production. Yangtze River Delta fabrication centers supply ferrite-core designs for export markets while serving domestic hotel renovation pipelines.
Japan
METI's commercial equipment efficiency guidelines align specification toward precision temperature control platforms. Kanto region hotel operators specify drop-in formats for spatially constrained buffet renovations. Osaka-based industrial clusters specialize in compact induction modules for front-of-house display cooking installations.
United Kingdom
London hospitality construction drives demand for integrated kitchen ecosystems bundling ranges with ventilation controls. The country's national building regulations tightening emissions requirements for commercial kitchens accelerate specification shifts. Midlands manufacturing bases supply resistance-element platforms for mid-market restaurant groups seeking cost-efficient compliance pathways.
Portable Buffet and Drop-In Ranges Market Competitive Landscape
On the supply side, the industry is consolidating around bundled kitchen ecosystem providers while specialized component fabricators retain niche positioning in warming and display cooking subsystems. Tiered competitive structure separates premium integrated-platform vendors from mid-market equipment specialists and regional assembly operations. Strategic archetypes include full-kitchen-system integrators, buffet-centric warming specialists, and scale-driven appliance manufacturers. Dominant competitive moves encompass portfolio diversification into ventilation-refrigeration bundling and geographic expansion through European manufacturing footprints.
Within the integrated-system tier, Bosch and Electrolux exemplify full-kitchen-ecosystem positioning, while Hatco Corporation occupies a specialized anchor position in buffet-centric warming and cooking solutions. These three entities represent distinct strategic vectors: German-engineered building-system integration, Swedish-European cost-competitive electric portfolios, and US-based drop-in specialization for hospitality renovation channels. Their collective presence illustrates how vendor consolidation around single-source accountability is compressing multi-vendor procurement patterns in United States hospitality construction.
| Leading Market Players |
|---|
| GE Appliances |
| LG Electronics |
| Bosch |
| Café |
| Thor Kitchen |
| Frigidaire |
| Hatco Corporation |
| SKS Ranges |
| Electrolux |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese induction coil fabrication centers compresses supplier pricing power and accelerates payment-term concessions to secure volume commitments from Western OEM buyers. This utilization dynamic feeds directly into procurement leverage for full-service restaurant chains negotiating bundled kitchen ecosystem contracts.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the portable buffet and drop-in ranges market. Price differentiation hinges on NSF certification grade and volume scale, with certified induction platforms commanding substantial premiums over non-certified gas alternatives. Cost compression in mid-market electric ranges is intensifying because ferrite-core coil imports from Yangtze River Delta suppliers erode legacy copper-wound manufacturing margins. Independent hotels exhibit the highest price sensitivity due to capital constraint, while major hospitality construction general contractors prioritize single-point accountability over unit cost minimization.
Supply Chain Analysis
Extended payment terms from Yangtze River Delta fabricators to European component suppliers illustrate working-capital stress propagating upstream through the induction coil value chain. Geographic supply concentration centers on China, Germany, and the United States for finished assembly, with 304-grade stainless steel and copper winding materials drawing from South Korean and Indonesian metal processing. Single-source vulnerability in ferrite-core substrate supply creates exposure for manufacturers dependent on tier-one city production clusters. Distribution runs through specialized foodservice equipment distributors and direct general contractor relationships in hospitality construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as electrification mandates splinter procurement authority between energy-compliance officers and traditional kitchen equipment specifiers, creating niche entry points for specialized vendors.
For Market Incumbents: Harden ecosystem bundling through captive ventilation-refrigeration integration to lock out modular competitors targeting mid-sized restaurant groups. Prioritize certification investment in EPA-compliant sealed-burner gas systems to defend installed base against municipal decarbonization mandates prohibiting natural gas hookups in California and New York metropolitan construction pipelines. For New Entrants and Emerging Players: Outdoor catering operators in secondary US metropolitan areas represent the most penetrable entry point for freestanding propane configurations underserved by integrated-system incumbents. Mobile event deployment channels favor simplified field-service architectures over smart-kitchen ecosystem complexity. A rental-first go-to-market model narrows capital barriers and accelerates trial adoption among temporary event operators. For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with ferrite-core induction coil expertise and established NSF certification pathways. Long-term viability across the analysis window rests on regulatory alignment with municipal decarbonization trajectories rather than gas infrastructure legacy exposure. The signal to watch is acceleration in all-electric building code adoption across Sun Belt hospitality construction markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrite-Core Coil Production | Captive supply of advanced induction components insulates margin from commodity copper volatility and Yangtze River Delta price pressure. |
| NSF Certification Acceleration Program | Compressed approval timelines filter import competition and secure specification lock-in for hotel buffet renovation pipelines. |
| Equipment-as-a-Service Platform Launch | Leasing structures convert capital expenditure barriers into recurring revenue streams among mid-sized independent restaurant groups. |
| Sealed-Burner Gas R&D Investment | EPA-compliant open-flame alternatives extend gas portfolio relevance in urban air-quality districts with tightening venting requirements. |
| Smart Kitchen Ecosystem Partnership | Protocol harmonization with building management systems elevates specification probability in bundled general contractor procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of US Department of Energy efficiency filings, EPA emissions guideline updates, and hospitality construction permit databases. Primary interviews engaged foodservice equipment procurement directors, commercial kitchen design consultants, NSF International certification specialists, and general contractor kitchen subsystem specifiers. Secondary validation drew from trade customs data, SEC 10-K disclosures of listed appliance manufacturers, and municipal building code adoption records. Bottom-up equipment shipment analysis triangulates against top-down hospitality construction expenditure modeling.
Forecast inputs include fuel-type specification trajectories, installation format preferences across renovation versus new construction, and power source adoption curves shaped by municipal decarbonization mandates. Segmentation dimensions span product type, end user category, installation format, and power source across the projection horizon. CAGRs derive from regression analysis against historical efficiency standard compliance cycles and regulatory announcement impacts. Industry-specific inputs incorporate US Department of Energy rulemaking timelines and California Air Resources Board commercial kitchen emissions pathways.
Practitioners should monitor municipal gas prohibition ordinance adoption rates and ferrite-core coil import tariff developments for early signals of specification shift velocity. Forecasts reflect assumptions regarding continued electrification mandate expansion and stable hospitality construction permitting activity. Macroeconomic contraction in commercial real estate development, regulatory delay in federal efficiency standard implementation, or breakthrough solid-state cooking technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
North America Online Food Delivery Market
Food Service
South America Free from Food Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Workplace Service Market
Food Service
Global Digital Grocery Market
Food Service
Europe Barbeque Grill Market
Food Service
Bottled Water Cooler Market
Food Service
Egypt Food Service Market
Food Service
Pizza Foodservice Market
Food Service
Indonesia Foodservice Market
Food Service
Food and Grocery Retail Market
Food Service
Asia Pacific Airline Catering Services Market
Food Service
UK Smokeless Indoor Grills Market
Food Service
Haute Cuisine Market
Food Service
Vietnam Food Service Market
Food Service
Beverage Napkins Market