
 Russia Foodservice Market | 2026-2036
Russia Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Foodservice Market Analytics
Plant-based protein formulations are repositioning menu economics across Russian foodservice chains. Vkusno & Tochka JSC leverages its refurbished McDonald's infrastructure to sustain cost advantages in quick-service operations. Teremok-Russian Pancakes LLC anchors its supply chain through captive blini production facilities in the Moscow region. Stars Coffee LLC differentiates via premium bean sourcing and controlled roasting operations.
Russia foodservice encompasses commercial meal preparation and delivery through institutional, quick-service, and full-service channels operating under strict thermal safety and traceability protocols. The sector serves urban consumers, corporate canteens, and transit hubs with standardized portion control and HACCP-aligned preparation workflows. Fast food and delivery service types capture the dominant margin pools as operator investments shift toward aggregator-integrated digital infrastructure. Casual dining occupies a maturing position with compressed expansion timelines outside tier-one cities.
Rospotrebnadzor enforces sanitary-epidemiological standards that dictate kitchen layout specifications and ingredient documentation across all licensed establishments. Federal Law No. 52-FZ on sanitary-epidemiological welfare mandates supplier certification that shapes procurement options for imported inputs. Stakeholders must monitor evolving EAEU technical regulations on food labeling and traceability that will determine cross-border ingredient sourcing feasibility.
Market Dynamics
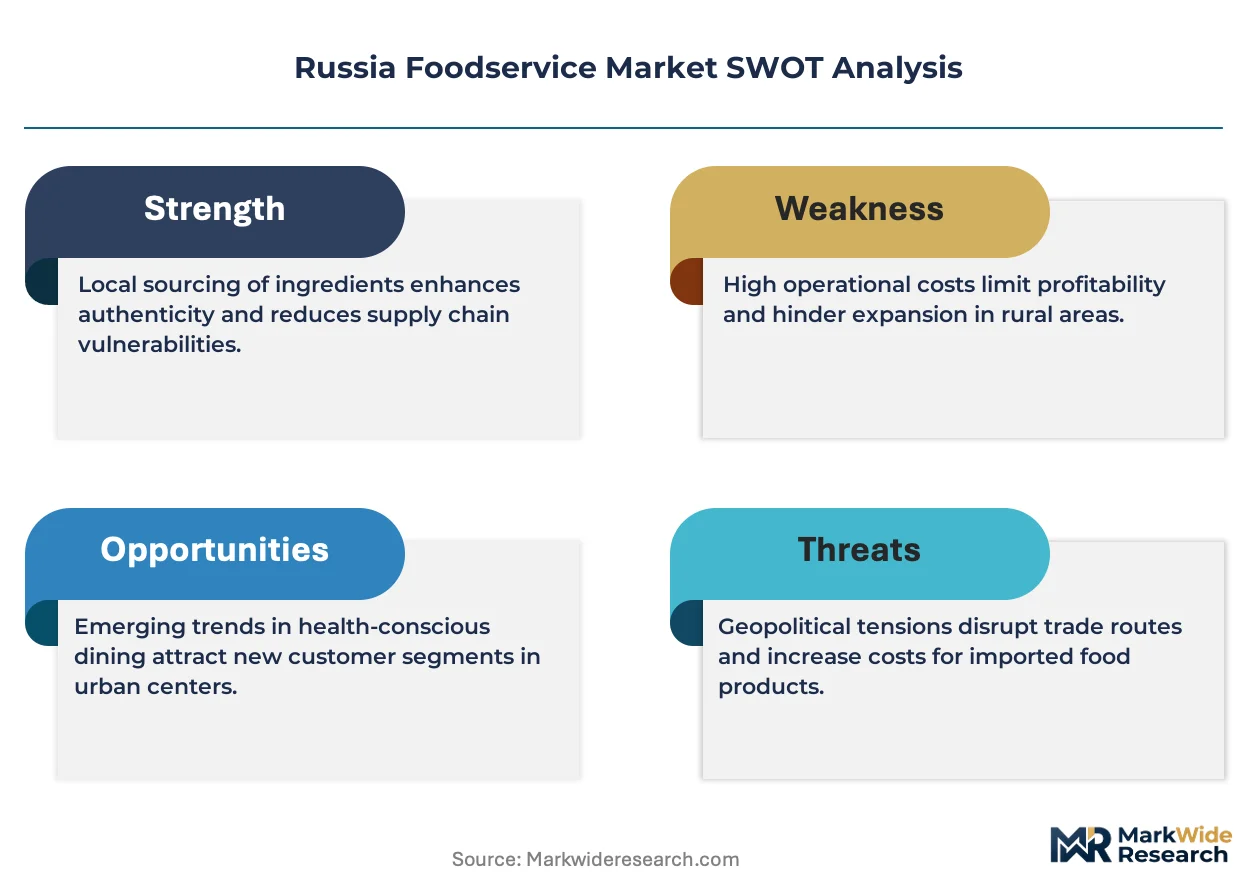
Federal Law No. 52-FZ mandates domestic ingredient traceability that forces operators to rebuild procurement networks around certified Russian suppliers. This regulatory pressure concentrates purchasing power among large chains with compliance infrastructure, squeezing independent operators into aggregator-dependent delivery models.
Growth Catalysts
- EAEU Technical Regulations:Harmonized food labeling standards across member states reduce cross-border sourcing friction for Russian operators expanding into Belarus and Kazakhstan.
- Aggregator-Integrated Digital Infrastructure:Delivery platforms embed POS and inventory systems that lower entry barriers for cloud kitchen operators in secondary cities.
- Regional Hub Investment:Kazan and Yekaterinburg draw quick-service expansion as Moscow and Saint Petersburg saturate with competing formats.
Market Restraints
- Import Substitution Cost Volatility:Domestic dairy and meat inputs fluctuate with regional harvest cycles, compressing margin predictability for operators locked into fixed-price menu strategies.
- Rospotrebnadzor Certification Friction:Sanitary-epidemiological documentation requirements extend supplier onboarding timelines by 40-60 days, freezing menu innovation cycles.
- Single-Source Equipment Dependency:Commercial kitchen fabricators cluster in the Moscow region, creating geographic concentration risk for operators in the Far Eastern Federal District.
Strategic Opportunities
- Siberian and Far Eastern Underpenetration:Novosibirsk and Vladivostok lack full-service casual dining density relative to per-capita income growth, creating white space for mid-market entrants.
- Plant-Based Protein Convergence:Pea and soy isolate formulations meet federal nutritional labeling incentives while differentiating menus against traditional meat-heavy competitors.
- Corporate Canteen Outsourcing:State enterprise privatization mandates open institutional meal contracts to competitive bidding, redirecting volume toward commercial operators with HACCP certification.
Industry Challenges
- Specialized Cold Chain Talent Scarcity:Thermal safety protocol training lags operator expansion into regions without established hospitality education infrastructure.
- Legacy POS Integration Complexity:Aggregator platforms require API connections to decade-old proprietary systems that lack standardized data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Foodservice Market |
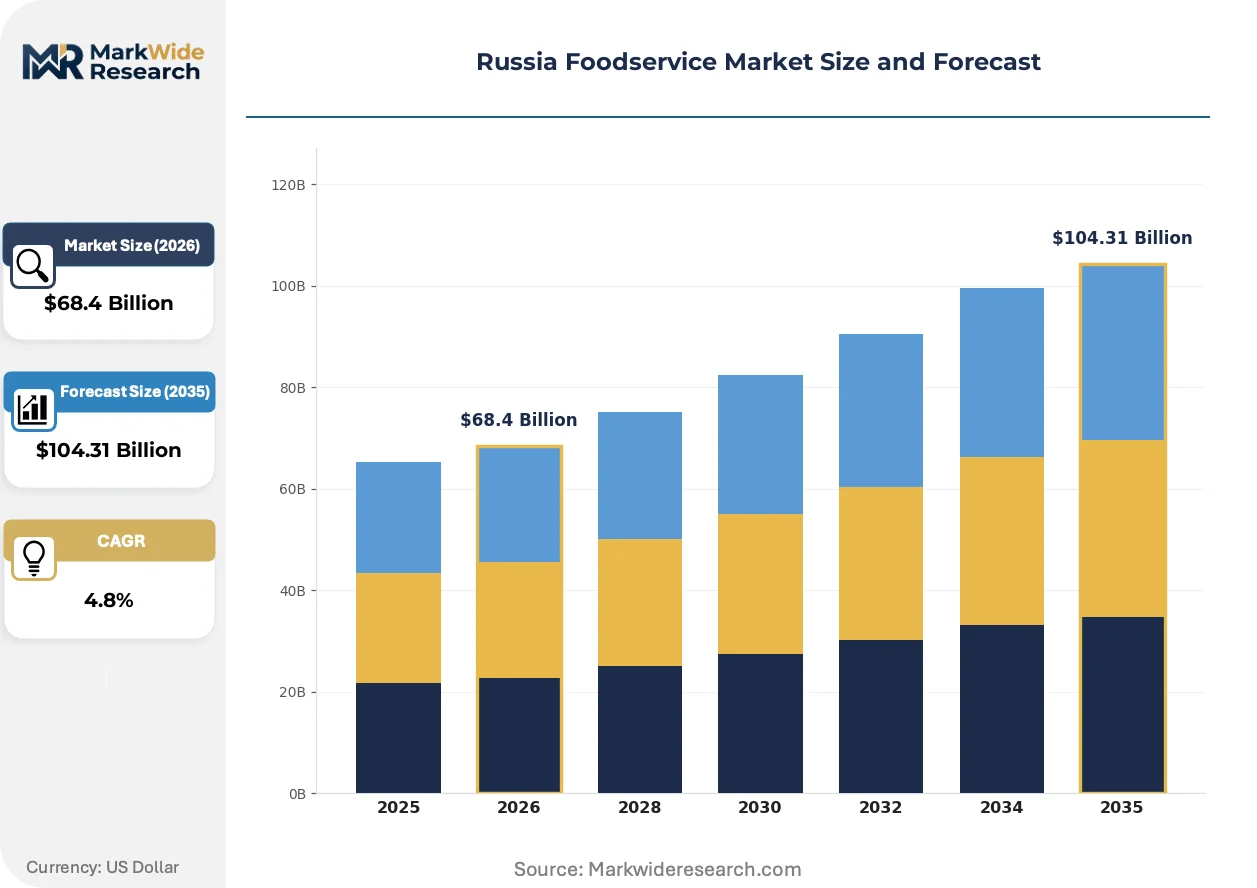
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
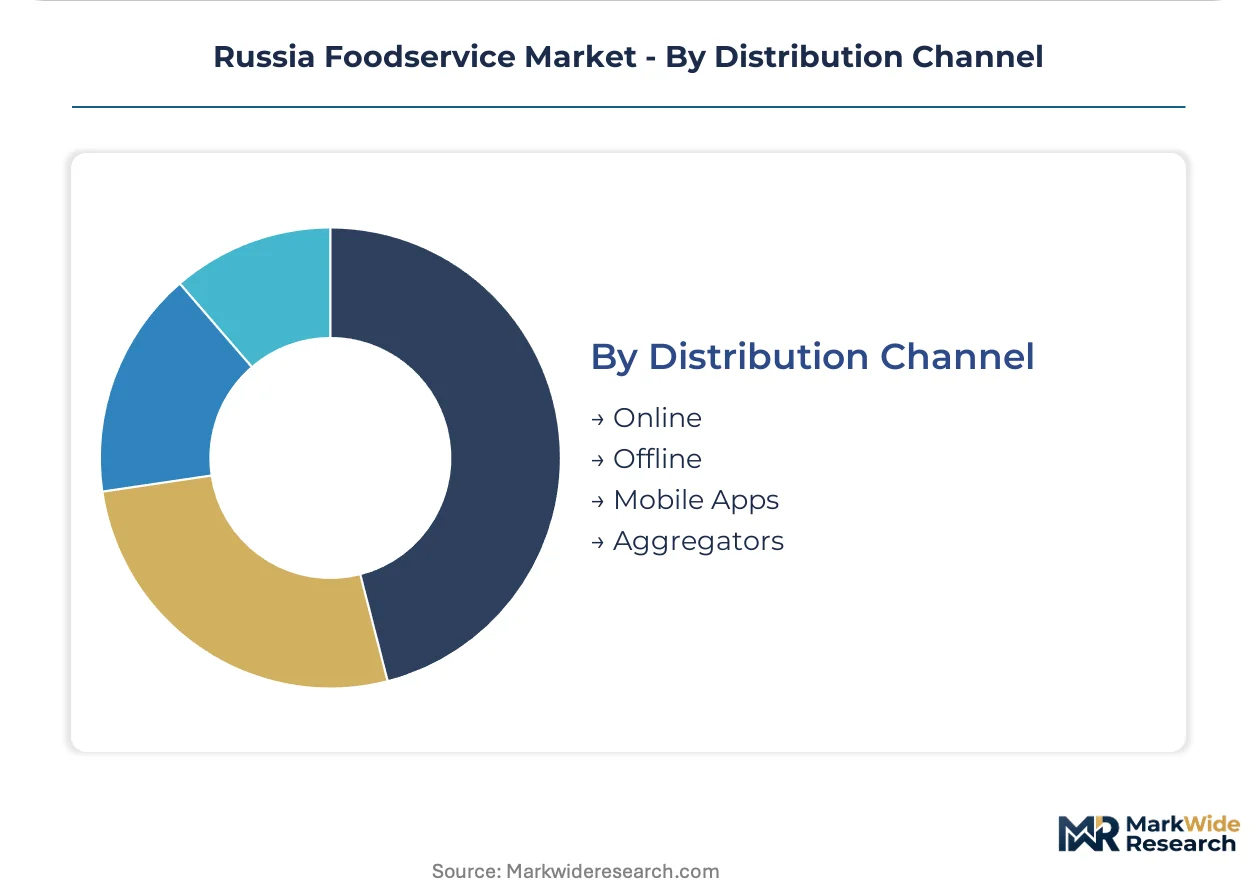
| Segmentation | Product Type: Fast Food, Casual Dining, Cafés, Fine Dining Service Type: Dine-in, Take-out, Delivery, Catering Customer Type: Families, Millennials, Business Travelers, Tourists Distribution Channel: Online, Offline, Mobile Apps, Aggregators |
| Companies Covered | Rosinter Restaurants Holding PJSC, Domino's Pizza Inc., Vkusno & Tochka JSC, Papa John's International Inc., The Wendy's Company, Restaurant Brands International Inc., Stars Coffee LLC, Teremok-Russian Pancakes LLC, Yum! Brands Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Foodservice Market Evolving Landscape
Digital ordering infrastructure is compressing the traditional dine-in service model while reshaping kitchen layout specifications. Operators now optimize for throughput velocity rather than table turnover, with capital allocation shifting toward dispatch logistics and temperature-controlled packaging.
Automated production lines for standardized menu items is converging with cloud kitchen real estate strategies. Quick-service chains deploy robotic patty-forming and fry stations in 80-120 square meter ghost kitchens. This technology convergence enables same-hour delivery promises while reducing labor dependency in tight regional labor markets.
Rospotrebnadzor's 2024 amendments to sanitary-epidemiological regulations mandate real-time temperature logging for all prepared food in transit. Full-service restaurants must retrofit vehicle fleets with IoT sensors or forfeit delivery licensing. Moscow-based operators bear the steepest compliance costs due to fleet scale, accelerating consolidation toward aggregator-owned logistics networks.
Corporate procurement departments now unbundle meal subsidies from single-caterer contracts, forcing operators to compete for individual employee orders through platform interfaces. This demand fragmentation rewards chains with dynamic pricing algorithms and penalizes fixed-menu institutional specialists. Saint Petersburg exhibits the sharpest contract dissolution pace as tech sector employers lead the shift.
Russia Foodservice Market Segmentation
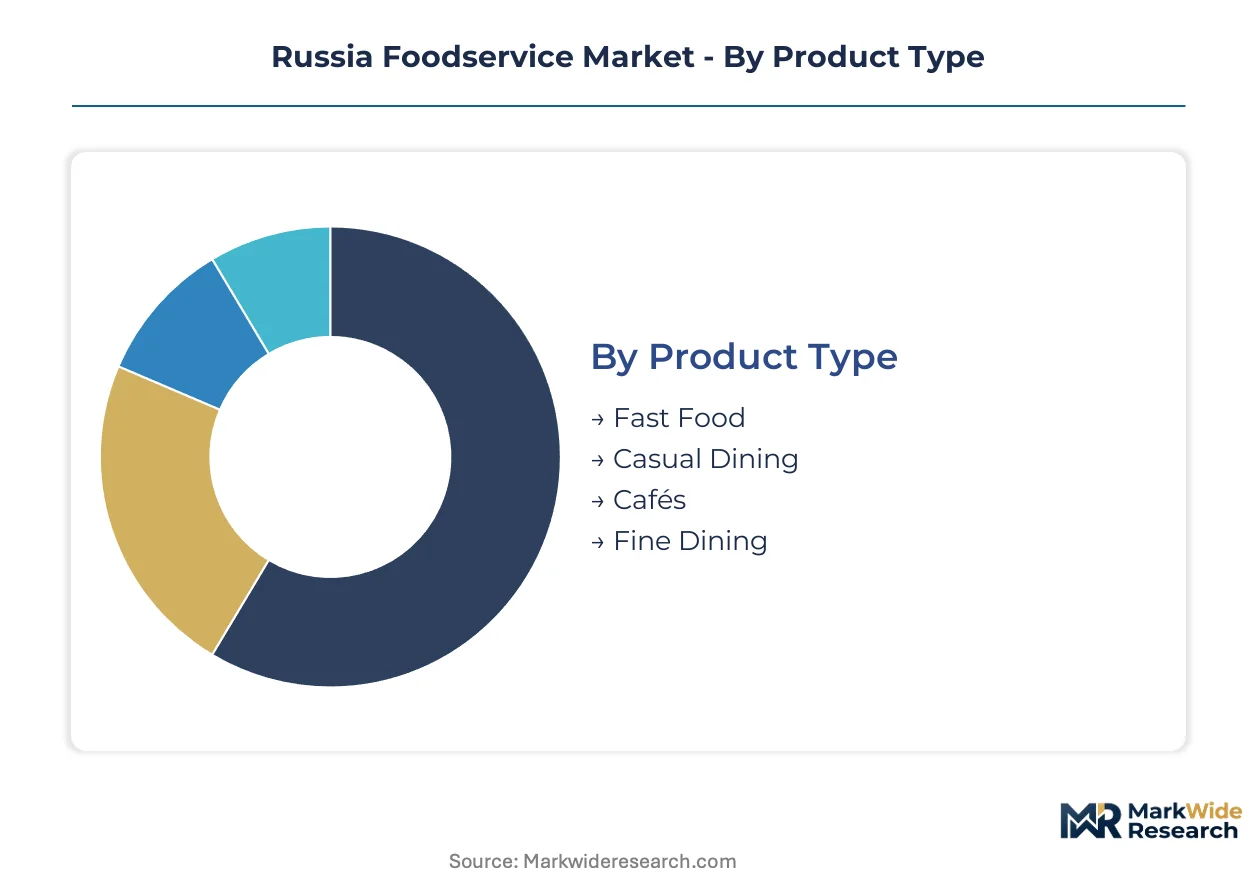
Segmentation reveals how Rospotrebnadzor compliance costs and aggregator platform economics split operator strategies across format types and customer profiles. Understanding these divides exposes where capital concentrates versus where margin compression forces consolidation.
Product Type:
Volume throughput separates quick-turn formats from experience-driven dining, with fixed-cost absorption dictating viable geographies.
- Fast Food:Standardized menu engineering and robotic production lines enable 80-120 square meter ghost kitchen formats. Demand concentrates in Kazan and Yekaterinburg as Moscow saturation pushes chains toward secondary city expansion with lower rent burdens.
- Casual Dining:Full-service table turnover models require larger footprints and trained floor staff, compressing expansion timelines outside tier-one cities where labor pools and supplier density support operational complexity.
- Cafés:Beverage-forward economics with limited hot kitchen infrastructure suit transit hub locations and corporate campus adjacencies.
- Fine Dining:Ingredient traceability documentation and chef certification requirements limit viable supplier networks to Moscow-region specialty distributors.
Mature deployment sits with Fast Food. Newer deployment is concentrated in Casual Dining as regional income growth supports mid-market experimentation.
Service Type:
Customer control over timing and location is reshaping kitchen design specifications and real estate priorities.
- Dine-in:Traditional table service models face declining share as urban real estate costs rise and consumer preference shifts toward convenience.
- Take-out:Counter-service formats with dedicated pickup infrastructure capture lunch-hour office demand in dense business districts.
- Delivery:Aggregator-integrated dispatch logistics and temperature-controlled packaging investments dominate capital allocation for emerging chains.
- Catering:Institutional volume contracts for state enterprise canteens require HACCP certification and specialized cold chain capabilities that filter out smaller operators.
Established infrastructure supports Dine-in. Investment flows are concentrating in Delivery as platform economics rewrite unit economics.
Customer Type:
Meal occasion and price sensitivity segment procurement behavior and platform engagement patterns.
- Families:Value-driven menu bundles and child-friendly facility specifications drive suburban location strategy for quick-service chains.
- Millennials:Digital-native ordering behavior and plant-based protein preference reshape menu development priorities for urban-focused operators.
- Business Travelers:Speed of service and consistent quality standards concentrate demand near transport terminals and central business district hotels.
- Tourists:Seasonal demand volatility and foreign payment method acceptance requirements create operational complexity for historic district operators.
Longstanding targeting focuses on Families. Platform data analytics are unlocking Millennial segmentation with steepest expansion trajectory.
Distribution Channel:
Digital integration depth separates aggregator-dependent operators from proprietary channel builders.
- Online:Direct website ordering with owned customer data supports loyalty program economics and dynamic pricing capabilities.
- Offline:Walk-in and telephone orders persist in regions with limited smartphone penetration or established elderly customer bases.
- Mobile Apps:Proprietary application development requires sustained technology investment that only large chains can amortize across multi-city footprints.
- Aggregators:Yandex.Eda and Delivery Club control last-mile logistics and customer relationships, extracting commission rates that compress operator margins.
Legacy strength remains with Offline. Capability building is accelerating in Mobile Apps as chains seek to reclaim customer ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Moscow and Saint Petersburg concentrate foodservice investment through preferential leasing terms and streamlined Rospotrebnadzor licensing. Federal tax incentives for regional development redirect capital toward secondary city expansion. Operator footprints now stretch across eleven time zones with varying compliance infrastructure maturity.
Moscow
Corporate canteen outsourcing contracts and premium casual dining demand dominate volume. Federal Law No. 52-FZ enforcement is strictest here, with real-time temperature logging mandates for delivery fleets. The Moscow region hosts captive production facilities for blini and plant-based protein formulations serving nationwide chains.
Saint Petersburg
Tech sector employers dissolve single-caterer contracts fastest, fragmenting institutional demand through aggregator platforms. EAEU technical regulations on harmonized labeling reduce friction for Belarusian and Kazakh ingredient imports. Historic district operators struggle with seasonal tourist volatility and foreign payment acceptance requirements.
Kazan
Quick-service chains exploit lower rent burdens as Moscow saturation pushes expansion eastward. Regional harvest cycle volatility in domestic dairy and meat inputs compresses margin predictability. The Tatarstan capital anchors Volga Federal District logistics networks for aggregator-integrated cloud kitchens.
Yekaterinburg
Mid-market income growth supports casual dining experimentation absent in smaller Ural cities. Rospotrebnadzor certification friction extends supplier onboarding timelines, freezing menu innovation. The city draws robotic production line deployments for 80-120 square meter ghost kitchen formats.
Vladivostok
Far Eastern Federal District underpenetration creates white space for full-service entrants relative to per-capita income trajectories. Single-source commercial kitchen fabricator dependency in Moscow creates equipment procurement delays. Port city logistics advantage supports fresh seafood supply chains for premium positioning.
Russia Foodservice Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with quick-service chains consolidating procurement power through compliance infrastructure while independents retreat into aggregator-dependent delivery models. The vendor base organizes around three strategic archetypes: refurbished infrastructure operators leveraging inherited real estate, captive supply chain owners controlling upstream production, and premium positioning specialists differentiating through controlled sourcing. M&A activity concentrates among regional hub acquirers seeking Moscow-grade operational templates. Vertical integration into ingredient production accelerates as domestic sourcing mandates harden.
Within the refurbished infrastructure tier, Vkusno & Tochka JSC occupies a position sustained by inherited McDonald's real estate and equipment networks. Teremok-Russian Pancakes LLC exemplifies captive supply chain ownership through its Moscow-region blini production facilities. Stars Coffee LLC anchors the premium positioning vector via controlled bean sourcing and roasting operations. These three structures represent the dominant competitive responses to federal traceability mandates and regional expansion imperatives.
| Leading Market Players |
|---|
| Rosinter Restaurants Holding PJSC |
| Domino's Pizza Inc. |
| Vkusno & Tochka JSC |
| Papa John's International Inc. |
| The Wendy's Company |
| Restaurant Brands International Inc. |
| Stars Coffee LLC |
| Teremok-Russian Pancakes LLC |
| Yum! Brands Inc. |
| Others |
Value Network & Pricing Analysis
Domestic dairy and meat input costs oscillate with regional harvest cycles, flowing through quick-service chains as compressed margin predictability and forcing operators toward dynamic menu pricing or captive production investments. Federal traceability mandates under Law No. 52-FZ concentrate procurement power among large chains with compliance infrastructure, while independents absorb aggregator commission premiums that reshape viable pricing tiers.
Pricing Analysis
Lead-time premiums reward operators with certified supplier relationships and real-time inventory visibility, while spot-market sourcing attracts discount-seeking independents willing to accept documentation gaps. Pricing stratifies across premium, standard, and economy tiers based on HACCP certification level and geographic delivery radius from Moscow-region production hubs. Cost compression in the economy tier is intensifying because aggregator commission structures extract fixed percentages regardless of order value. Quick-service chains exhibit lowest price sensitivity due to volume-scale procurement power, while independent casual dining operators face acute margin pressure from compliance overhead.
Supply Chain Analysis
Federal domestic-content mandates under Law No. 52-FZ and EAEU technical regulations are reshaping sourcing patterns toward certified Russian suppliers and harmonized cross-border labeling for Belarusian and Kazakh inputs. Geographic supply concentration centers on the Moscow region for commercial kitchen fabrication and captive blini production, with secondary hubs emerging in Kazan and Yekaterinburg for regional distribution. Raw material dependencies rest on domestic dairy, meat, and pea-soy protein isolates subject to harvest volatility. Single-source equipment vulnerability from Moscow-region fabricators creates procurement delays for Far Eastern operators. Distribution runs through aggregator-integrated logistics networks controlling last-mile customer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Federal Law No. 52-FZ erects a barrier-to-entry moat that rewards operators with pre-existing certification infrastructure and squeezes marginal players into dependency on aggregator platforms.
For Market Incumbents: Extend compliance infrastructure advantages by acquiring regional hub operators in Kazan and Yekaterinburg to replicate Moscow-grade operational templates. Invest in captive production facilities for high-documentation inputs like plant-based proteins and blini formulations to insulate margins from harvest cycle volatility. The threat of aggregator commission extraction demands channel control through proprietary mobile app development and direct customer data ownership. For New Entrants and Emerging Players: Enter via cloud kitchen formats in underpenetrated Siberian and Far Eastern markets where per-capita income growth outpaces full-service dining density. Target Novosibirsk and Vladivostok with 80-120 square meter ghost kitchens deploying robotic production lines for standardized menu items. The most penetrable segment is corporate canteen outsourcing, where state enterprise privatization mandates open institutional contracts to competitive bidders with HACCP certification. For Investors and Strategic Acquirers: Rospotrebnadzor's 2024 real-time temperature logging mandate for delivery fleets is the leading indicator that consolidation toward aggregator-owned logistics networks will accelerate, favoring operators with fleet scale or aggregator partnership depth. Long-term viability over the analysis window hinges on backward integration into ingredient production and compliance infrastructure amortization across multi-city footprints. Acquisition targets should exhibit captive supply chain ownership or premium positioning through controlled sourcing. The signal to watch is corporate procurement contract dissolution rates in Saint Petersburg's tech sector, which lead national contract fragmentation trends.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Production Facility Development | In-house blini and plant-protein production insulates Vkusno & Tochka and Teremok from harvest-driven input volatility. |
| Aggregator Platform Integration | API connections to Yandex.Eda and Delivery Club embed POS and inventory systems that lower cloud kitchen entry barriers. |
| Robotic Production Line Deployment | Automated patty-forming and fry stations in ghost kitchens enable same-hour delivery promises with reduced labor dependency. |
| Proprietary Mobile Application Launch | Direct customer data ownership supports loyalty program economics and dynamic pricing capabilities outside aggregator commission structures. |
| Corporate Canteen Contract Bidding | HACCP-certified operators capture institutional volume as state enterprise privatization mandates open meal contracts to competitive bidding. |
Research Methodology
Document review covered Rospotrebnadzor regulatory filings, EAEU technical regulation amendments, and federal food safety mandate documentation, complemented by interviews with quick-service chain procurement directors, cloud kitchen operators, aggregator platform strategy leads, and regional hospitality association representatives. Secondary validation drew from customs and trade data on food ingredient imports, commercial real estate leasing databases for Moscow and secondary cities, and hospitality sector employment statistics. Bottom-up unit economics modeling triangulated against top-down market sizing from operator revenue disclosures and platform transaction volume estimates.
Value projections across the analysis window emerged from segment-level modeling of quick-service, casual dining, and institutional channels, with growth trajectories calibrated to regional income indicators, urbanization rates, and regulatory enforcement intensity. CAGRs derived from historical operator expansion patterns and platform penetration curves in comparable emerging markets. Key forecast inputs included Rospotrebnadzor certification timeline assumptions and aggregator commission rate stability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EAEU regulatory harmonization or sustained import substitution cost volatility. Projections reflect assumptions about federal enforcement consistency and aggregator platform market structure stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Airport Quick Service Restaurants Market
Food Service
Beverage Coaster Market
Food Service
Clear Ice Maker Market
Food Service
Chinese Takeout Market
Food Service
Hospital Food Services Market
Food Service
Onboard Rail Catering Market
Food Service
Instant Grocery Market
Food Service
Food Trays Market
Food Service
Air Fryer Market
Food Service
Cambodia Foodservice Market
Food Service
Qatar Food Service Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Indonesia Foodservice Market
Food Service
Commercial Grills Market
Food Service
United States Online Food Delivery Market
Food Service
Beverage Vending Machine Market