
 GCC Biodegradable Food Service Disposables Market | 2026-2036
GCC Biodegradable Food Service Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Biodegradable Food Service Disposables Market Intelligence
Multi-source procurement of biopolymer resins is consolidating around a smaller set of certified suppliers with Gulf logistics capabilities. BASF SE anchors the region's PLA supply chain through its polymer distribution network, while Novamont S.p.A. leverages its Mater-Bi compostable resin platform to serve food packaging converters in Jeddah and Riyadh. NatureWorks LLC dominates inbound Ingeo PLA volumes, though local toll compounding partnerships help it navigate customs complexity.
GCC biodegradable food service disposables are single-use items engineered from plant-derived polymers or processed agricultural fibers, designed to decompose under industrial composting conditions within 90 to 180 days per ASTM D6400 and EN 13432 protocols. Their primary commercial purpose is to replace petroleum-based plastics in food contact applications across the Gulf's hospitality and foodservice sectors. PLA and bagasse material segments lead current volume, with CPLA gaining share in hot-fill applications due to its elevated heat-deflection temperature. The restaurant end-user segment occupies the deepest margin pool, driven by bulk procurement contracts from Saudi and Emirati quick-service chains.
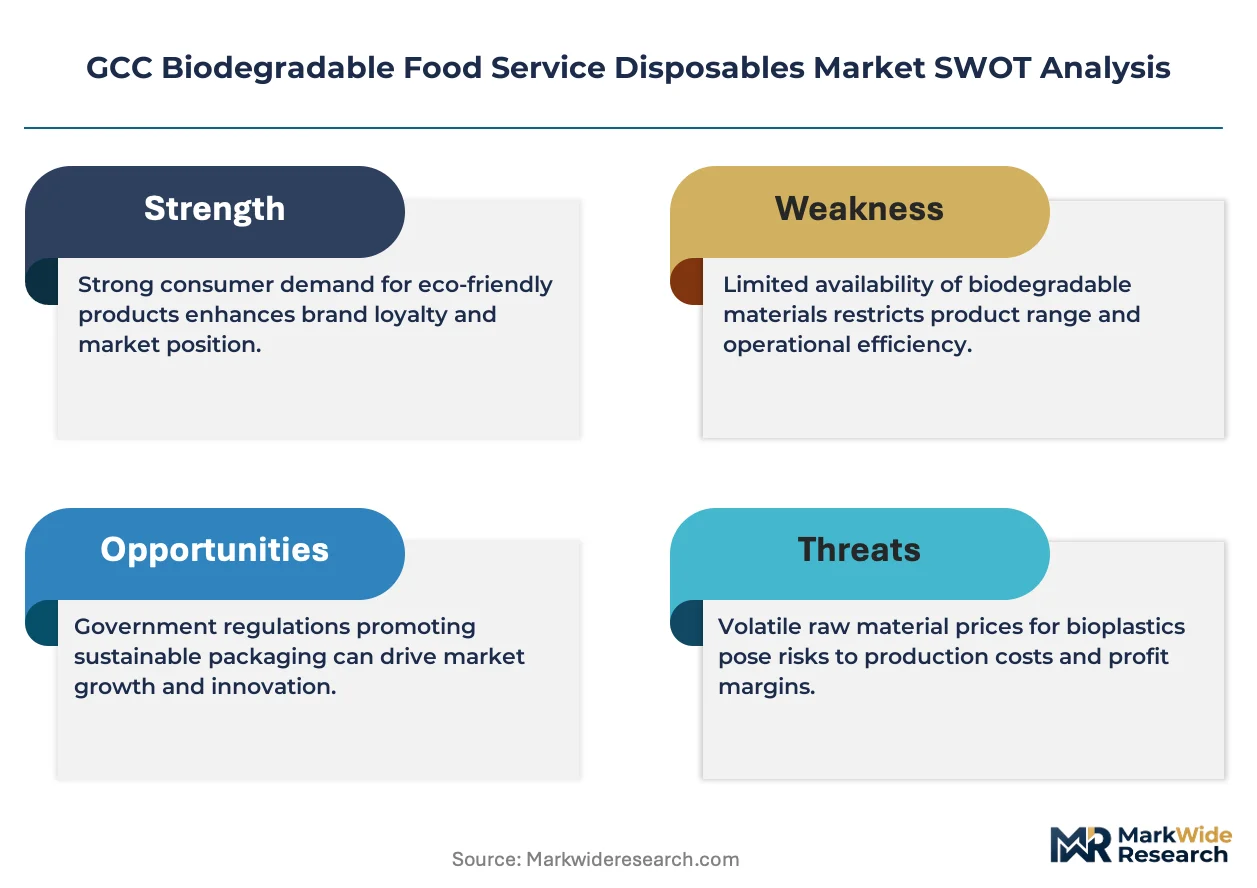
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE Ministry of Climate Change and Environment plastic reduction directives are tightening compliance requirements for disposable foodservice items across the six Gulf states. Dubai Municipality's mandatory sustainable procurement guidelines for government-linked catering contracts directly shape product certification demand. Stakeholders must monitor evolving composting infrastructure timelines and polymer import tariff adjustments to align capacity commitments with actual waste-treatment pathways.
Market Dynamics
Dubai Municipality's mandatory sustainable procurement guidelines for government-linked catering contracts are compressing supplier qualification timelines and forcing rapid certification upgrades across the GCC biodegradable tableware value chain.
Growth Catalysts
- SASO Technical Regulations:Saudi Standards, Metrology and Quality Organization mandates are eliminating non-certified petroleum-based alternatives from foodservice channels, creating immediate replacement demand for ASTM D6400-compliant bagasse and PLA products.
- Quick-Service Restaurant Procurement:Saudi and Emirati QSR chains are executing bulk conversion contracts, locking in multi-year supply agreements with certified biodegradable converters to meet internal sustainability targets.
- Industrial Composting Infrastructure:Planned waste-to-energy and composting facilities in Abu Dhabi and Jeddah are extending viable end-of-life pathways for certified disposables, reducing performance risk for buyers.
Market Restraints
- PLA Resin Import Concentration:Ingeo PLA volumes depend on toll compounding partnerships through Jebel Ali, exposing converters to customs processing delays and polymer tariff volatility.
- Heat-Deflection Limitations:Standard PLA formulations deform above 55°C, restricting penetration in hot-fill beverage applications where CPLA carries 40-60% cost premiums.
- Bagasse Supply Seasonality:Sugarcane fiber availability concentrates around harvest windows in Indian and Pakistani processing hubs, creating raw material scheduling constraints for Gulf molders.
Strategic Opportunities
- Kuwait and Bahrain Hospitality:Hotel construction pipelines in Manama and Kuwait City lack established biodegradable supplier relationships, creating first-mover positioning for certified entrants with Gulf logistics capabilities.
- CPLA Hot-Fill Applications:Crystallized PLA's elevated temperature resistance is opening premium positioning in coffee-to-go and soup container segments where conventional PLA fails.
- Dubai Government Contracting:Mandatory sustainable procurement guidelines for municipality-linked catering create guaranteed offtake volumes for EN 13432-certified suppliers meeting technical specifications.
Industry Challenges
- Composting Certification Alignment:ASTM D6400 and EN 13432 testing timelines stretch 90-120 days, delaying product launches and locking working capital in pre-certified inventory.
- Customs Documentation Complexity:Biopolymer resin imports require polymer classification expertise and origin certificates that Gulf toll compounders struggle to standardize across Saudi and UAE port authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Biodegradable Food Service Disposables Market |
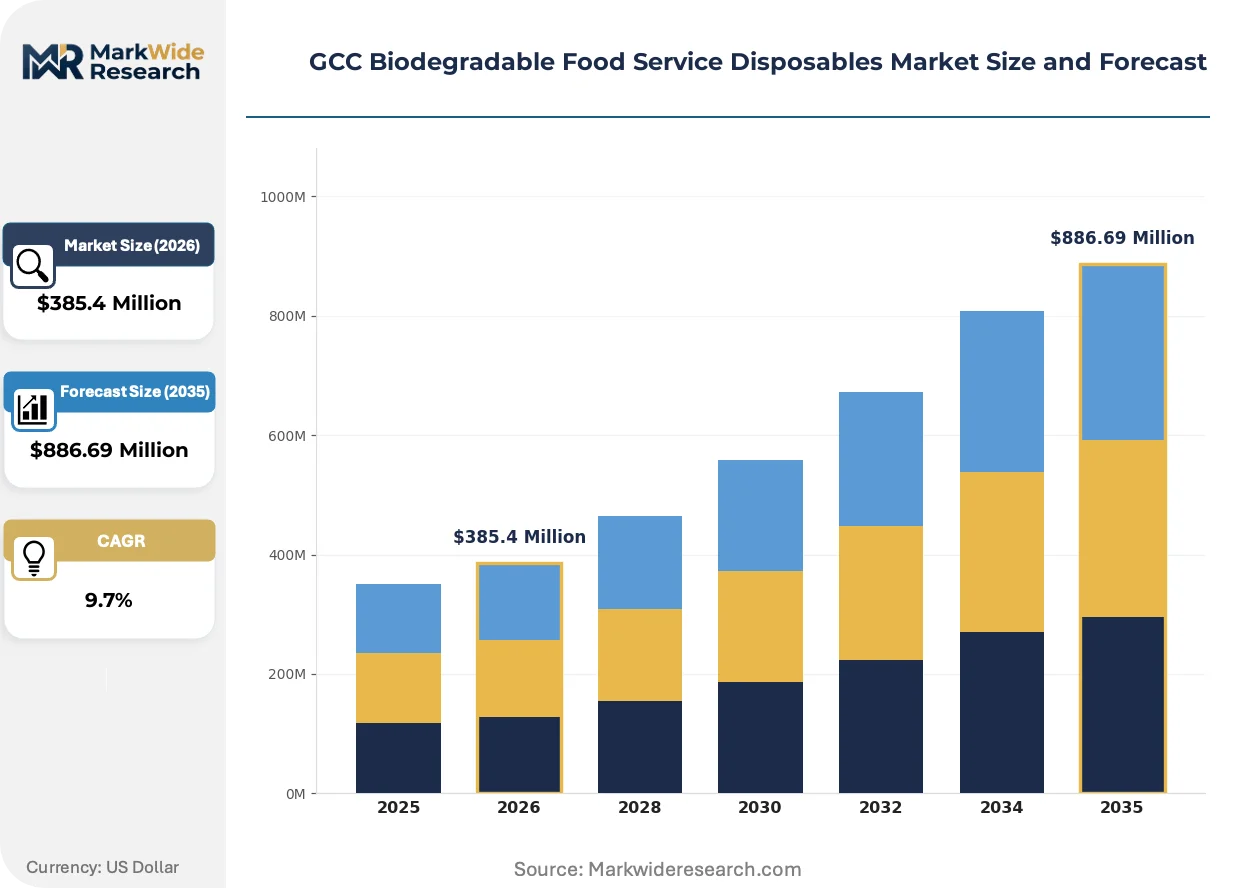
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Cutlery, Straws Material: PLA, CPLA, Bagasse, Bamboo End User: Restaurants, Cafés, Catering Services, Food Trucks Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Mondi plc, BASF SE, Georgia-Pacific, NatureWorks LLC, Novamont S.p.A., WestRock Company, Stora Enso Oyj, Pactiv LLC, Smurfit Kappa Group, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Biodegradable Food Service Disposables Market Strategic Shifts & Innovations
Material science advances and procurement protocol tightening are converging to redefine performance benchmarks and supplier qualification criteria across Gulf foodservice channels.
Crystallized PLA (CPLA) is electrifying hot-fill disposable categories by extending heat resistance to 85°C without petroleum-based additives. Dubai hotel chains and airport concessionaires are adopting CPLA lids and containers for coffee and prepared food applications where standard PLA deforms. This thermal performance leap is compressing the addressable market for conventional polystyrene in premium hospitality segments.
UAE Ministry of Climate Change and Environment plastic reduction directives are mandating disclosure of disposable material composition in foodservice contracts. Catering operators must now certify compostability pathways or face exclusion from government-linked events and facilities. The restaurant end-use segment is responding by consolidating supplier bases around converters with dual ASTM D6400 and EN 13432 certification.
Quick-service chains are compressing supplier evaluation cycles from annual to quarterly reviews, prioritizing converters with demonstrated Gulf logistics reliability and batch-level traceability. This behavioral shift favors regional toll compounders with Jeddah and Dubai warehousing over direct-import models. Saudi QSR procurement teams are most visibly driving this acceleration, linking sustainability scorecards to contract renewal terms.
GCC Biodegradable Food Service Disposables Market Segmentation
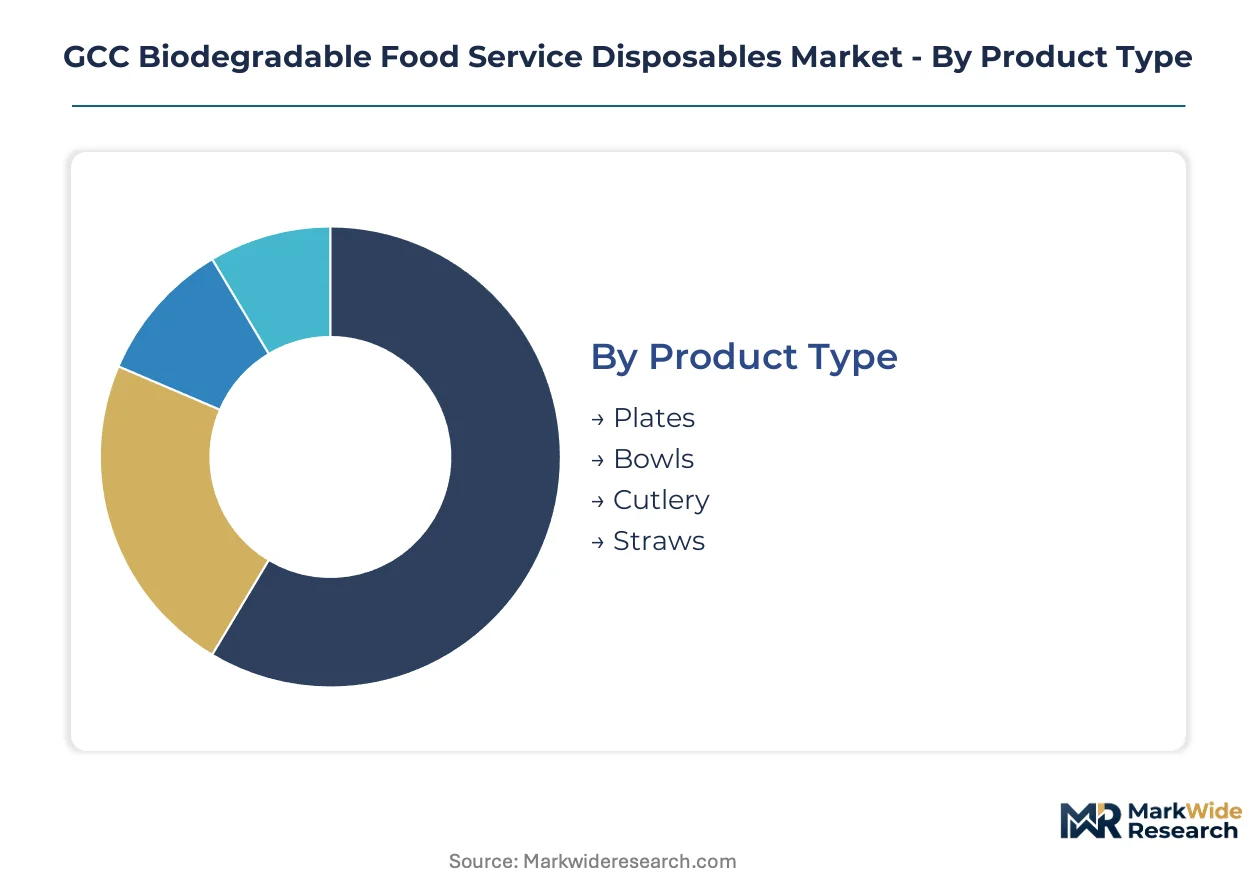
Segmentation in GCC biodegradable foodservice disposables reveals distinct procurement patterns across material performance tiers and channel structures. Product specifications vary sharply between hot-fill and ambient applications, while distribution pathways diverge between institutional bulk contracts and hospitality spot purchasing.
Product Type:
Plates function as standalone serving systems, whereas cutlery and straws typically embed within bundled meal kits or beverage programs.
- Plates:Flatware engineered from bagasse fiber or CPLA resin serves full-meal presentations across Saudi QSR chains and Dubai hotel banquet operations. Heat-deflection requirements above 70°C favor CPLA formulations in hot-food applications, while bagasse dominates ambient catering.
- Cutlery:Spoons, forks, and knives demand higher flexural strength than plate applications, pushing converters toward reinforced PLA blends or bamboo fiber composites. Abu Dhabi airport concessionaires and Jeddah food courts specify certified compostable cutlery in bundled procurement tenders.
- Bowls:Deep-drawn containers for soups and grain bowls require liquid-barrier coatings; CPLA and bagasse-laminated grades capture premium positioning in UAE healthcare catering.
- Straws:Straight and bent formats compete with paper alternatives; PLA straws face heat-limitation constraints in hot-beverage service, restricting penetration to cold-drink segments in Saudi and Emirati cafés.
Volume placements concentrate in Plates; the faster expansion belongs to Cutlery as bundled sustainability mandates spread across Gulf foodservice contracts.
Material:
Cost tiers separate commodity agricultural fibers from engineered biopolymers, with performance premiums widening in high-temperature applications.
- PLA:Standard polylactic acid resin delivers transparency and thermoformability for cold-food packaging. Dubai Municipality procurement guidelines specify PLA for government-linked catering where industrial composting infrastructure exists.
- CPLA:Crystallized PLA extends heat resistance to 85°C through thermal annealing, commanding 40-60% price premiums over standard grades. Coffee-to-go chains in Riyadh and Abu Dhabi specify CPLA lids and containers for hot-fill beverage programs.
- Bagasse:Processed sugarcane fiber offers natural aesthetics and microwave compatibility. Saudi and Pakistani harvest cycles create raw material scheduling constraints for Gulf molders.
- Bamboo:Rapid-renewable grass fiber provides structural rigidity for cutlery and stirrers. Chinese processing hubs supply GCC converters through Jebel Ali consolidation points.
Bagasse captures the deepest volume in ambient foodservice; CPLA climbs the fastest as hot-fill specifications tighten across premium hospitality segments.
End User:
Customer scale determines contract structure, from enterprise procurement teams to owner-operator spot purchasing.
- Restaurants:Saudi and Emirati quick-service chains execute multi-year supply agreements with certified converters, linking sustainability scorecards to contract renewal terms. Bulk procurement concentrates demand among three to five approved suppliers per chain.
- Catering Services:Event and institutional caterers in Dubai and Riyadh face mandatory sustainable procurement guidelines for government-linked contracts. Dual ASTM D6400 and EN 13432 certification gates supplier qualification.
- Cafés:Independent coffee shops and bakery chains in Kuwait City and Manama purchase through wholesale distributors, prioritizing aesthetic differentiation over volume pricing.
- Food Trucks:Mobile operators in Saudi urban corridors favor lightweight bagasse formats for operational efficiency and disposal compliance.
Restaurants anchor current procurement volume; Catering Services gain share fastest as municipal mandates expand across the six Gulf states.
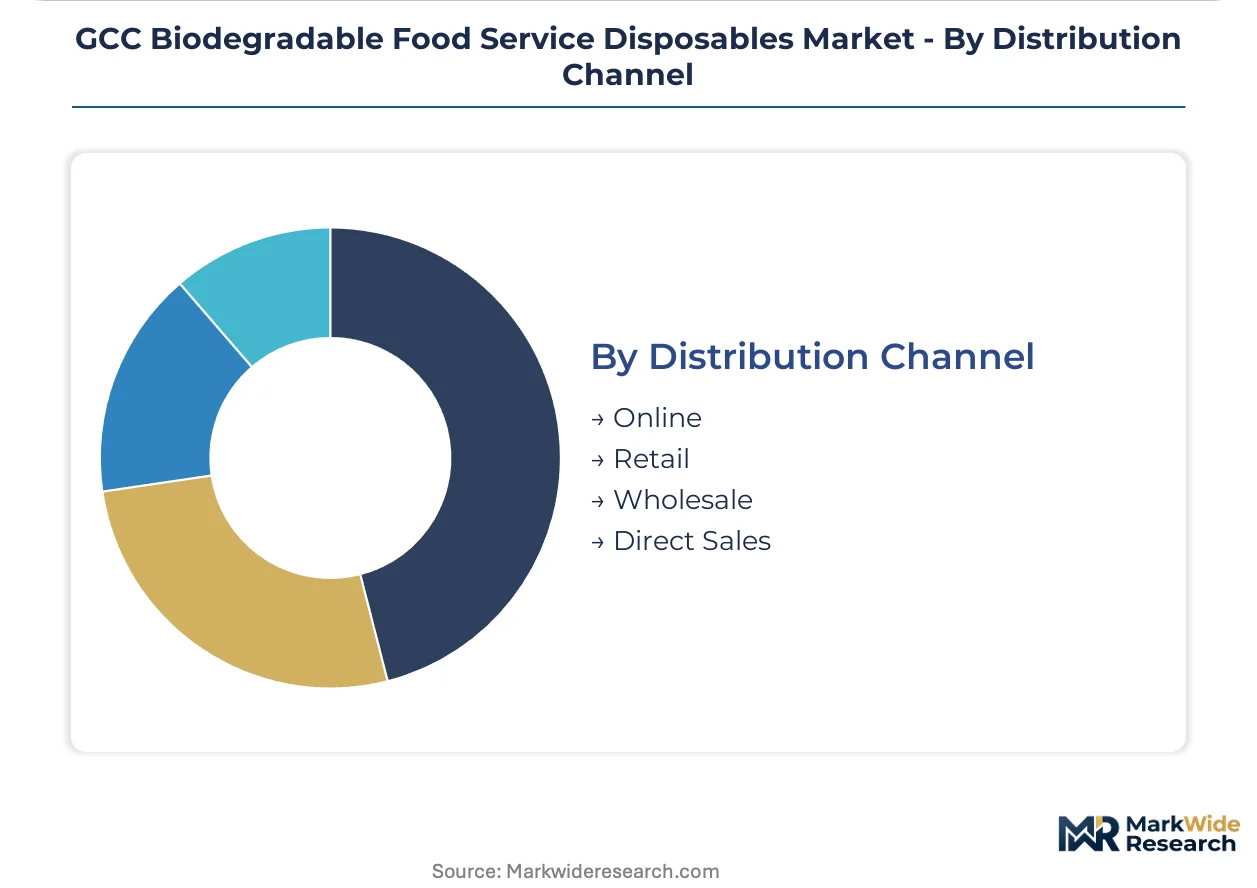
Distribution Channel:
Channel selection reflects buyer sophistication and order scale, with direct relationships consolidating at the top of the market.
- Wholesale:Distributors with Jeddah and Dubai warehousing aggregate demand from mid-size hospitality operators, offering batch-level traceability and Gulf logistics reliability.
- Direct Sales:Certified converters maintain dedicated account teams for Saudi QSR procurement departments and UAE hotel chain sustainability officers.
- Online:E-commerce platforms serve small-format cafés and independent food trucks with minimum-order quantities below wholesale thresholds.
- Retail:Consumer-packaged formats for home entertaining and small events move through hypermarket chains in Abu Dhabi and Doha.
Wholesale channels dominate transaction volume; Direct Sales expand most quickly as enterprise procurement centralizes supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugarcane fiber processing clusters in Pakistan and India anchor raw material flows into GCC biodegradable tableware manufacturing, with Jebel Ali and Jeddah serving as consolidation points for biopolymer resin distribution across the six Gulf states.
Saudi Arabia
Quick-service restaurant chains in Riyadh and Jeddah are executing multi-year supply agreements with certified biodegradable converters. SASO technical regulations mandate ASTM D6400 compliance for foodservice disposables, eliminating petroleum-based alternatives from institutional channels. The Western Region around Jeddah hosts the kingdom's deepest concentration of toll compounding partnerships for PLA resin processing.
United Arab Emirates
Dubai's hospitality corridor generates premium demand for CPLA hot-fill containers and bagasse banquet ware. Dubai Municipality's mandatory sustainable procurement guidelines for government-linked catering contracts enforce EN 13432 certification gates. Abu Dhabi's planned industrial composting facilities are extending viable end-of-life pathways for certified disposables across the emirate's hotel and airport concession networks.
Kuwait
Hotel construction pipelines in Kuwait City lack established biodegradable supplier relationships, creating positioning opportunities for certified entrants with Gulf logistics capabilities. The country's national environmental regulator has issued plastic reduction directives for foodservice operations in government facilities. Wholesale distributors are aggregating demand from mid-size hospitality operators in the capital's emerging dining districts.
Qatar
Catering operators serving Doha's event and hospitality sectors face procurement mandates linked to national sustainability frameworks. The country's waste management authority is developing composting infrastructure timelines that will shape certification requirements for disposable foodservice items. Industrial zones around Doha are attracting regional converters seeking proximity to high-value hospitality contracts.
Bahrain
Manama's foodservice market exhibits underpenetrated demand for certified biodegradable tableware relative to Saudi and Emirati benchmarks. The country's municipal procurement guidelines for government catering are tightening material disclosure requirements. Bahrain's position as a logistics hub offers toll compounders access to cross-Gulf distribution networks serving smaller-format operators.
GCC Biodegradable Food Service Disposables Market Key Industry Players
Global majors compete with regional champions across resin supply and conversion capabilities in the GCC biodegradable foodservice disposables market. BASF SE and NatureWorks LLC anchor polymer supply chains through distribution networks and toll compounding partnerships, while regional converters specialize in molded fiber and thermoformed product categories. Three archetypes dominate: multinational resin suppliers with Gulf logistics infrastructure, regional toll compounders with Jeddah and Dubai warehousing, and specialized converters focused on bagasse and CPLA finished goods. Competitive moves concentrate on strategic partnerships with QSR procurement departments and capacity expansion into underpenetrated Kuwaiti and Bahraini markets.
Within the multinational resin supplier tier, BASF SE and Novamont S.p.A. exemplify positioning through polymer distribution networks and compostable resin platforms. NatureWorks LLC occupies a distinct position as the dominant inbound source for PLA volumes, relying on local toll compounding partnerships to navigate customs complexity. These three companies represent the upstream concentration that shapes converter procurement economics and certification alignment across the Gulf.
| Leading Market Players |
|---|
| Mondi plc |
| BASF SE |
| Georgia-Pacific |
| NatureWorks LLC |
| Novamont S.p.A. |
| WestRock Company |
| Stora Enso Oyj |
| Pactiv LLC |
| Smurfit Kappa Group |
| Others |
Cost & Logistics Intelligence
Dubai Municipality's mandatory sustainable procurement guidelines for government-linked catering contracts are compressing supplier qualification timelines and forcing rapid certification upgrades across the GCC biodegradable tableware value chain.
Pricing Analysis
Certification bundling separates quoted rates from unbundled alternatives lacking ASTM D6400 or EN 13432 documentation. Three-tier pricing structure across premium CPLA hot-fill grades, standard PLA cold-food formats, and economy bagasse fiber tiers captures performance differentiation. Cost compression in standard PLA segments intensifies as Saudi QSR procurement teams consolidate approved supplier lists around three to five converters per chain. Mid-size hospitality operators exhibit highest price sensitivity, while Dubai hotel chains and airport concessionaires absorb premiums for CPLA thermal performance.
Supply Chain Analysis
Biopolymer resin supply rests on NatureWorks LLC's Ingeo PLA volumes entering through Jebel Ali toll compounding partnerships, BASF SE's regional distribution network, and Novamont S.p.A.'s Mater-Bi compostable resin platform serving Jeddah and Riyadh converters. Bagasse fiber feeds from Indian and Pakistani sugarcane processing clusters, with bamboo composites sourcing through Chinese consolidation points. Single-source vulnerability concentrates in PLA resin customs processing delays and polymer tariff volatility at Saudi and UAE port authorities. Distribution runs through Jeddah and Dubai warehousing nodes serving wholesale distributors with batch-level traceability capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into biopolymer resin supply and captive composting facility partnerships represents the dominant vertical-integration race, as converters seek to decouple from NatureWorks LLC's import concentration and Jebel Ali customs exposure.
For Market Incumbents: Hedge against PLA resin import volatility by securing multi-year toll compounding contracts with Jeddah-based processors and diversifying raw material exposure into bagasse fiber partnerships with Pakistani sugar mills. Certification investment in dual ASTM D6400 and EN 13432 testing capabilities locks in Dubai Municipality contract eligibility as qualification timelines compress. For New Entrants and Emerging Players: SASO technical regulations in Saudi Arabia open a window for ASTM D6400-certified converters to capture replacement demand from petroleum-based alternatives eliminated from institutional channels. Kuwait City and Manama hospitality construction pipelines lack established supplier relationships, offering first-mover positioning for certified entrants with Gulf logistics capabilities. Direct sales to Saudi QSR procurement departments with demonstrated batch-level traceability bypasses wholesale distributor margin capture. For Investors and Strategic Acquirers: The window for entry favors regional toll compounders with Jeddah and Dubai warehousing infrastructure and established customs documentation expertise. Long-term viability hinges on composting infrastructure buildout timelines across Abu Dhabi and Jeddah extending viable end-of-life pathways. Watch industrial composting facility commissioning schedules as the inflection indicator for certification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive PLA toll compounding partnerships reduce NatureWorks LLC import dependency and Jebel Ali customs exposure. |
| Dual Certification Investment | ASTM D6400 and EN 13432 testing capabilities gate Dubai Municipality and SASO contract eligibility. |
| Geographic Expansion into Kuwait and Bahrain | Hotel construction pipelines in Kuwait City and Manama lack established biodegradable supplier relationships. |
| Long-term Supply Agreements with QSR Chains | Saudi and Emirati quick-service chains lock in multi-year contracts linking sustainability scorecards to renewal terms. |
| Composting Infrastructure Partnerships | Abu Dhabi and Jeddah waste-to-energy facility collaborations extend viable end-of-life pathways for certified disposables. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across procurement directors at Saudi and Emirati QSR chains, sustainability officers at Dubai hotel groups, technical directors at regional toll compounders, and distribution managers at Jeddah and Dubai warehousing operators. SASO technical regulations, Dubai Municipality procurement guidelines, UAE Ministry of Climate Change and Environment directives, and ASTM D6400 certification databases provided regulatory validation. Bottom-up volume modeling and top-down value triangulation reconciled segment outputs.
Data-stream reconciliation across material type, product format, end-use channel, and distribution pathway dimensions shaped the analytical framework across the projection horizon. CAGRs derived from segment-level growth trajectories weighted by procurement contract visibility and composting infrastructure development timelines. Industrial composting facility commissioning schedules and polymer import tariff adjustments served as key forecast sensitivity inputs.
Caveats apply where SASO regulatory enforcement intensity, Dubai Municipality procurement guideline revisions, or Jebel Ali customs processing disruptions could materially shift the outlook. Forecasts reflect assumptions around certification testing timelines and toll compounding partnership stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food Service Market
Food Service
Latin America Inflight Catering Market
Food Service
United Arab Emirates Full Service Restaurants Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Asia-Pacific Online Grocery Delivery Market
Food Service
US Food Trucks Services Market
Food Service
Online Food Delivery Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
GCC Food Service Market
Food Service
Electric Tiffin Market
Food Service
United States Food Truck Market
Food Service
Air Fryer Market
Food Service
Netherlands Food Service Market
Food Service
Pasteurized Eggs Market
Food Service
India Foodservice Market
Food Service
Aquarium Protein Skimmers Market