
 Healthcare Clinical Analytics Market | 2026-2036
Healthcare Clinical Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Clinical Analytics Market Outlook
Multi-source analytics procurement is recalibrating how health systems evaluate vendor ecosystems, shifting from single-platform dependencies toward modular best-of-breed architectures. Cerner Corporation anchors its position through deep electronic health record integration that sustains recurring enterprise contracts. IQVIA Holdings leverages its real-world evidence repository to differentiate in pharmaceutical analytics services. SAS Institute competes through advanced statistical computing capabilities that dominate academic medical center deployments.
Healthcare clinical analytics encompasses the systematic computational analysis of patient data, clinical workflows, and operational metrics to generate actionable intelligence for care delivery optimization, typically processing structured and unstructured data through machine learning pipelines with sub-second latency requirements for critical care alerts. Its primary purpose is reducing clinical variation, predicting adverse events, and optimizing resource allocation across care continuums. Predictive analytics commands the largest revenue share as health systems prioritize readmission risk stratification and sepsis early warning systems, while prescriptive analytics represents the fastest-expanding margin pool as value-based contracting intensifies. Cloud-based deployment is displacing on-premises infrastructure fastest among mid-size hospital networks seeking elastic compute for population health initiatives.
FDA interoperability mandates under the 21st Century Cures Act and ONC certification requirements are forcing vendors to standardize application programming interfaces and patient data formats, reshaping product roadmaps toward open architecture compliance. HIPAA security rule enforcement and state-level privacy statutes create layered compliance burdens that favor established vendors with dedicated governance infrastructure. Stakeholders must monitor how CMS innovation center payment models redirect analytics investment from retrospective reporting toward prospective risk adjustment and automated care gap closure.
Market Dynamics
FDA interoperability mandates under the 21st Century Cures Act are restructuring vendor roadmaps toward open architecture compliance, forcing health systems to replace siloed data warehouses with standardized application programming interfaces.
Growth Catalysts
- ONC Certification Requirements:Federal mandates for standardized patient data formats accelerate infrastructure replacement cycles across integrated delivery networks.
- Cloud Elasticity:Mid-size hospital networks deploy cloud-native platforms to support population health initiatives without fixed-capital data center investments.
- Sepsis Early Warning Systems:Critical care units prioritize predictive alerting capabilities that reduce mortality events and liability exposure.
Market Restraints
- HIPAA Security Rule Enforcement:Layered state-level privacy statutes create compliance burdens that favor established vendors with dedicated governance infrastructure.
- Legacy System Integration Costs:Proprietary electronic health record architectures require expensive middleware development for analytics platform connectivity.
- Specialized Talent Scarcity:Health informatics professionals with clinical workflow expertise command premium compensation that constrains mid-tier health system budgets.
Strategic Opportunities
- Automated Care Gap Closure:CMS innovation center payment models redirect investment toward prospective risk adjustment workflows.
- Federated Learning Architectures:Privacy-preserving machine learning enables multi-institutional model training without centralized data pooling.
- Rural Health Network Expansion:Critical access hospitals represent underpenetrated demand for cloud-based analytics with subscription pricing.
Industry Challenges
- Interoperability Implementation Timelines:Health information exchange standardization delays stall real-time analytics deployment.
- Clinical Workflow Disruption:Alert fatigue from poorly calibrated predictive models erodes physician trust and platform utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Clinical Analytics Market |
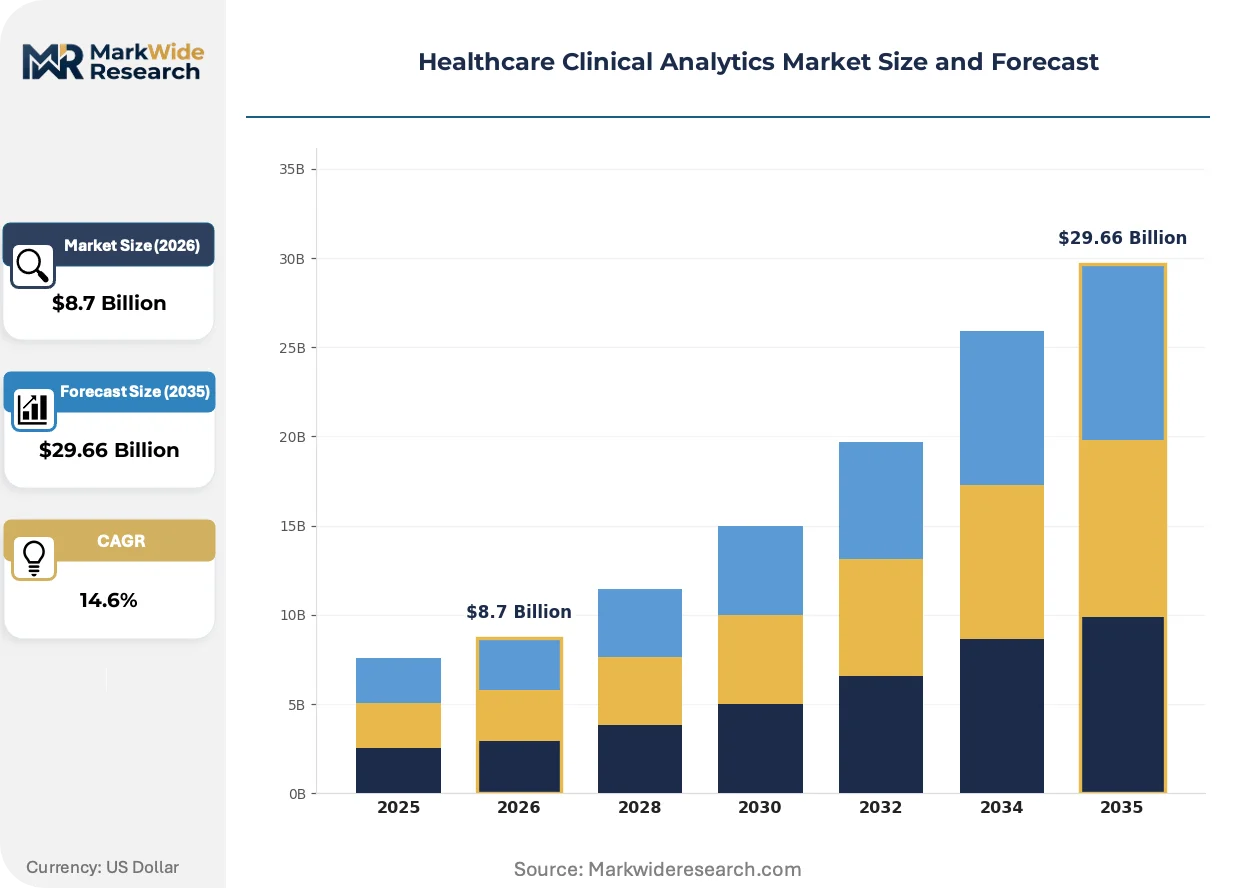
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Real-time Analytics End User: Hospitals, Clinics, Research Organizations, Pharmaceuticals Deployment: On-premises, Cloud-based, Hybrid, Edge Computing Application: Patient Management, Financial Management, Operational Efficiency, Research & Development |
| Companies Covered | IBM Corporation, Oracle Corporation, Cerner Corporation, McKesson Corporation, Allscripts Healthcare Solutions, Inc., IQVIA Holdings, Inc., Optum, Inc., Health Catalyst, Inc., SAS Institute, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Clinical Analytics Market Strategic Shifts
Machine learning pipelines are embedding directly into point-of-care workflows, compressing the latency between data generation and clinical decision support.
Natural language processing engines extract structured insights from unstructured clinical notes, enabling automated coding and quality measure abstraction. Academic medical centers deploy these tools for research cohort identification at scale. This capability is converging with real-world evidence platforms to accelerate pharmaceutical protocol design.
The FDA's 21st Century Cures Act mandates standardized application programming interfaces for patient data access. Vendors must rearchitect proprietary systems toward open architecture compliance. Pharmaceutical sponsors and health systems both face compressed timelines for interoperability certification.
Integrated delivery networks consolidate analytics procurement under centralized chief data officer functions. Single-platform dependencies dissolve as modular best-of-breed architectures gain preference. United States health systems lead this transition, with procurement committees evaluating vendor ecosystems on API maturity rather than feature breadth alone.
Healthcare Clinical Analytics Market Segmentation
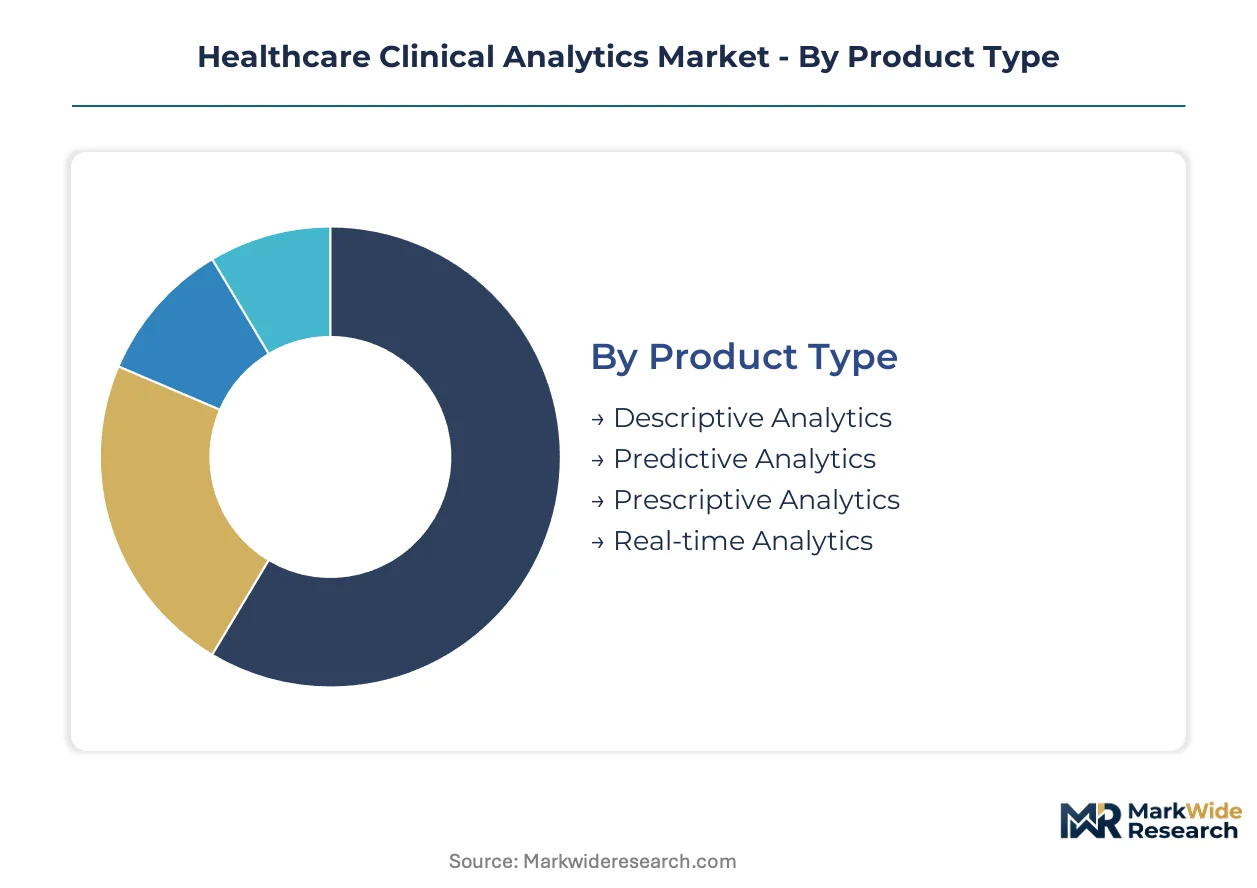
Healthcare clinical analytics vendors configure certification pathways differently across product architectures. Deployment modes trigger distinct HIPAA security rule obligations. End-user scale determines whether cloud elasticity or on-premises governance dominates procurement.
Product Type:
FDA 21st Century Cures Act interoperability mandates apply uniformly across all product types, though real-time alerting systems face additional FDA software-as-medical-device scrutiny for sepsis and deterioration warnings.
- Predictive Analytics:Machine learning models stratify readmission risk and flag sepsis onset using EHR-derived vital signs and laboratory values. Hospital systems in the United States prioritize these capabilities for CMS penalty avoidance and liability reduction.
- Prescriptive Analytics:Optimization engines recommend specific interventions—antibiotic selection, discharge timing, staffing adjustments—based on comparative effectiveness models. Value-based contracting accelerates demand as risk-bearing entities seek automated care pathway adherence.
- Descriptive Analytics:Retrospective dashboards aggregate historical performance against quality benchmarks and regulatory reporting requirements.
- Real-time Analytics:Sub-second latency pipelines process streaming physiologic data for critical care alerting, requiring FDA validation for clinical decision support.
Predictive analytics sits at the top of the volume ranking, with prescriptive analytics climbing the fastest.
End User:
Procurement scale and integration complexity separate institutional buyers, with integrated delivery networks consolidating vendor relationships under centralized data governance functions.
- Hospitals:Enterprise-wide deployments span inpatient, emergency, and ambulatory settings with 24/7 operational requirements. Academic medical centers layer research cohort identification atop clinical workflows.
- Pharmaceuticals:Real-world evidence platforms aggregate de-identified patient trajectories across health systems to accelerate trial design and regulatory submission. IQVIA and similar vendors dominate this segment with proprietary data networks.
- Clinics:Federally qualified health centers and specialty practices adopt cloud-native solutions with subscription pricing to avoid capital expenditure.
- Research Organizations:Federated learning architectures enable multi-site model training without centralized data pooling, preserving institutional firewalls.
Hospitals command the dominant procurement volume, though pharmaceuticals is expanding most quickly as FDA emphasizes real-world evidence in approval pathways.
Deployment:
HIPAA security rule enforcement and state-level privacy statutes create layered compliance burdens that favor established vendors with dedicated governance infrastructure across deployment modes.
- Cloud-based:Elastic compute supports population health initiatives without fixed-capital data center investments. Mid-size hospital networks in the United States lead migration as procurement committees prioritize API maturity over feature breadth.
- Hybrid:Sensitive identifiers remain on-premises while analytics workloads burst to cloud infrastructure. This architecture satisfies risk-averse compliance officers at integrated delivery networks.
- On-premises:Legacy health systems with substantial sunk infrastructure costs maintain captive data centers for latency-critical applications.
- Edge Computing:Distributed processing at bedside devices and local servers enables sub-second alerting without network dependency for critical care units.
Cloud-based deployment leads current installations, with edge computing gaining share fastest as IoT device density increases in surgical suites and intensive care units.
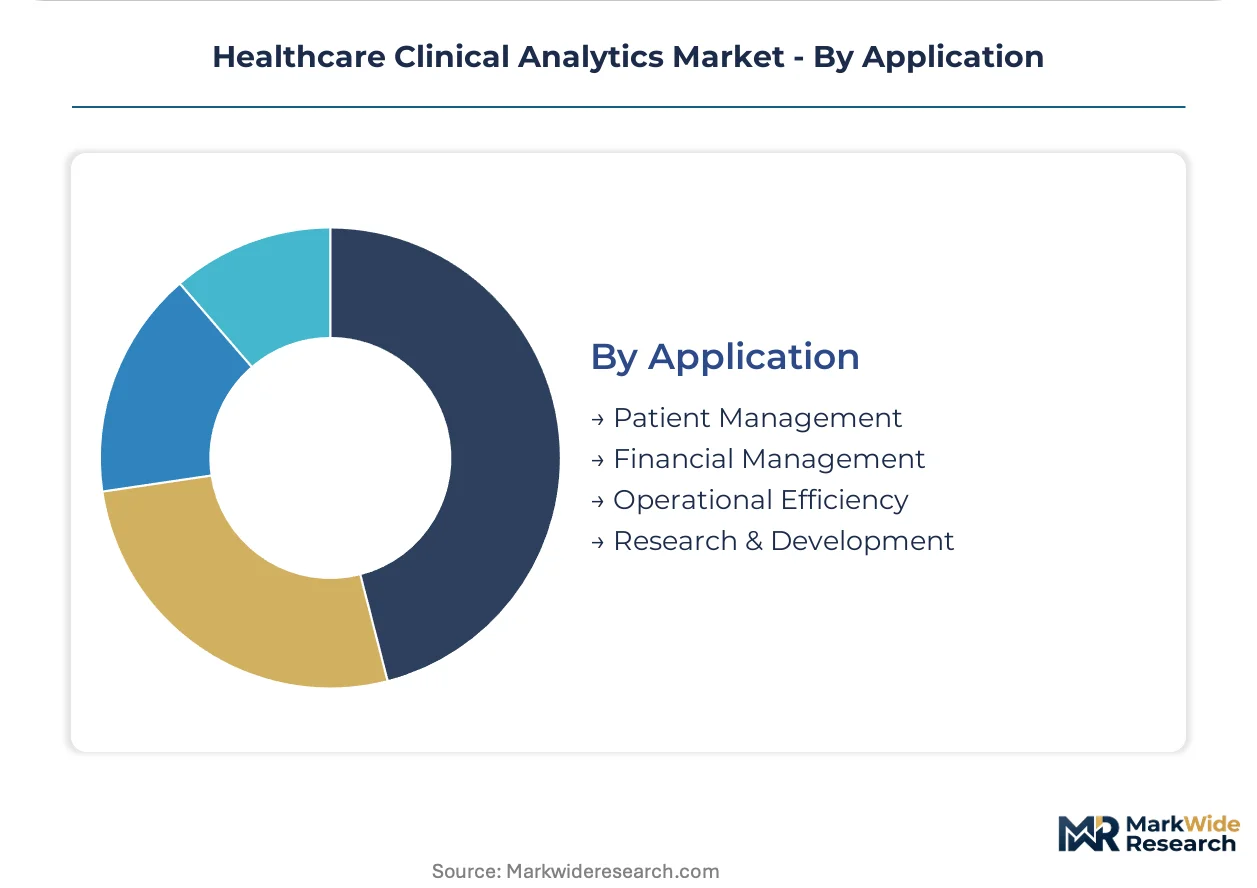
Application:
CMS innovation center payment models redirect analytics investment from retrospective reporting toward prospective risk adjustment and automated care gap closure across application areas.
- Patient Management:Care coordination platforms track chronic disease trajectories, medication adherence, and social determinants across transitions. United States integrated delivery networks deploy these tools for Medicare Advantage risk score optimization.
- Operational Efficiency:OR scheduling algorithms and bed management systems reduce throughput bottlenecks. Labor cost pressures drive adoption as nursing shortages persist.
- Financial Management:Revenue cycle analytics identify documentation gaps and coding optimization opportunities for charge capture improvement.
- Research & Development:Natural language processing engines extract structured insights from unstructured clinical notes for automated cohort identification and protocol feasibility assessment.
Patient management holds the largest installed base, with operational efficiency showing the steepest expansion trajectory as labor cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate the highest procurement volume for clinical analytics platforms. Hospital systems across Germany and Japan accelerate infrastructure modernization under national digitization mandates. Cloud-native vendors penetrate mid-tier hospitals in India and Brazil through subscription pricing models.
United States
Medicare Advantage risk adjustment workflows and CMS innovation center payment models drive enterprise analytics procurement. The FDA's 21st Century Cures Act mandates standardized APIs that force infrastructure replacement cycles. The Boston-Cambridge corridor anchors academic medical center deployments where natural language processing engines extract research cohorts from unstructured clinical notes.
Germany
University hospital networks consolidate vendor relationships under centralized data governance functions. The EU AI Act and MDR frameworks impose validation requirements on clinical decision support algorithms. The Rhine-Ruhr metropolitan region hosts pharmaceutical analytics deployments where real-world evidence platforms aggregate de-identified patient trajectories.
Japan
Super-aging demographics intensify demand for predictive readmission risk stratification across chronic disease management. METI's Society 5.0 initiative funds interoperability infrastructure for hospital information exchange standardization. The Kanto region around Tokyo concentrates deployments of edge computing architectures for sub-second latency in critical care alerting.
India
Corporate hospital chains and health insurance aggregators deploy cloud-native platforms to avoid fixed-capital data center investments. The Digital India mission and CDSCO software-as-medical-device guidelines shape regulatory compliance pathways. Hyderabad and Bengaluru emerge as hubs where mid-tier hospitals adopt subscription-based operational efficiency analytics.
Brazil
Supplementary health insurers and large hospital groups invest in revenue cycle analytics for charge capture optimization. ANVISA's software regulation framework and LGPD privacy statutes create layered compliance obligations. São Paulo's private hospital networks lead adoption of automated care gap closure tools for risk-bearing provider contracts.
Healthcare Clinical Analytics Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue federated learning architectures and edge-native deployments. The vendor ecosystem consolidates around three maturity tiers: legacy electronic health record integrators, cloud-native population health platforms, and pharmaceutical real-world evidence specialists. Strategic archetypes include deep EHR embedders, API-first modular vendors, and academic statistical computing providers. Dominant competitive moves encompass strategic partnerships for interoperability certification and vertical integration into proprietary data networks.
Within the legacy integration tier, Cerner Corporation and McKesson Corporation exemplify established vendors with recurring enterprise contracts anchored to hospital system infrastructure. IQVIA Holdings occupies a distinct position representing pharmaceutical-focused analytics through real-world evidence repository differentiation. These three entities illustrate how geographic origin and corporate structure—Kansas-based Cerner, Texas-based McKesson, and North Carolina-based IQVIA—correlate with archetype specialization rather than direct feature competition.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| Cerner Corporation |
| McKesson Corporation |
| Allscripts Healthcare Solutions, Inc. |
| IQVIA Holdings, Inc. |
| Optum, Inc. |
| Health Catalyst, Inc. |
| SAS Institute, Inc. |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States concentrate procurement volume under centralized chief data officer functions, anchoring a subscription-based SaaS pricing model that scales with patient volume and API call throughput. This buyer concentration creates tiered pricing power where multi-hospital contracts command 30-40% discounts against single-facility deployments.
Pricing Analysis
Cloud infrastructure costs from AWS, Azure, and Google Cloud Platform pass through directly to end-user pricing, with compute-intensive machine learning workloads carrying premium surcharges. Pricing stratifies across enterprise, professional, and essential tiers differentiated by interoperability certification level and dedicated support availability. Cost compression in the mid-market segment is intensifying because Cerner and Epic are bundling analytics modules with core EHR renewals at marginal cost. Federally qualified health centers exhibit the highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize feature breadth over unit cost.
Supply Chain Analysis
GPU and specialized AI accelerator supply rests on NVIDIA's foundry partnerships with TSMC in Taiwan and Samsung in South Korea, creating concentrated dependency for model training infrastructure. Cloud compute provisioning draws from hyperscaler data centers concentrated in Virginia, Oregon, and Dublin, while edge hardware for real-time alerting sources from Intel and AMD fabrication in the United States and Malaysia. Single-source vulnerability in NVIDIA's H100 and A100 chip allocation creates procurement bottlenecks for training-intensive predictive models. Distribution runs through direct enterprise sales teams with professional services bundling, supplemented by channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare clinical analytics functions as a geographic-arbitrage play where cloud-native vendors can deliver US-equivalent capabilities to Indian and Brazilian hospital networks at one-third the infrastructure cost by leveraging Mumbai and São Paulo data center zones outside HIPAA jurisdiction.
For Market Incumbents: Lock in recurring revenue through multi-year EHR-embedded contracts that raise switching costs for hospital systems facing FDA interoperability deadlines. Deepen API certification investment to maintain ONC compliance leadership against modular best-of-breed challengers. Prioritize backward integration into proprietary real-world evidence data networks to differentiate from pure-play software vendors. For New Entrants and Emerging Players: Critical access hospitals in rural United States markets represent the most penetrable buyer archetype, with subscription cloud analytics replacing aging on-premises infrastructure at 60% lower total cost of ownership. Federated learning architectures for research organizations enable penetration without centralized data pooling that triggers HIPAA complexity. A channel partnership strategy with regional GPOs accelerates procurement committee access without direct enterprise sales investment. For Investors and Strategic Acquirers: Pharmaceutical real-world evidence platforms are the most active acquirer in this space, with IQVIA-style data network assets commanding premium multiples over pure software capabilities. Long-term viability centers on regulatory moat sustainability through FDA 21st Century Cures Act certification rather than feature velocity alone. The signal to watch is CMS innovation center payment model expansion into automated care gap closure, which would revalue prospective analytics vendors against retrospective reporting incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software-as-Medical-Device Pathway | Sepsis early warning systems require FDA validation for clinical deployment in US hospitals. |
| ONC Certification Compliance Investment | Standardized API mandates force infrastructure replacement cycles across integrated delivery networks. |
| Hospital System Partnership Expansion | Cerner and Epic embedded analytics sustain recurring enterprise contracts through EHR integration depth. |
| Federated Learning Platform Development | Privacy-preserving multi-site training enables pharmaceutical R&D without centralized HIPAA data pooling. |
| Reimbursement Strategy Alignment | CMS value-based contracting redirects procurement toward prospective risk adjustment capabilities. |
Study Parameters
Direct dialogue with chief data officers, hospital procurement committee chairs, biomedical informaticists, and pharmaceutical real-world evidence directors grounded qualitative findings in operational workflow realities. Secondary validation drew from FDA 510(k) device filings, CMS Medicare cost report data, hospital GPO contract databases, and ONC interoperability certification registries. Bottom-up sizing of vendor-reported deployments triangulated against top-down health system IT budget allocation surveys.
Segment-level revenue estimates across the projection horizon reflect modeled adoption curves for predictive, prescriptive, descriptive, and real-time analytics product types, cross-referenced with deployment mode elasticity and end-user scale parameters. CAGRs were derived from logistic diffusion modeling of cloud migration patterns and value-based contracting penetration rates. Forecast inputs incorporated HIPAA enforcement intensity indices and FDA software-as-medical-device approval velocity assumptions.
Underlying measurement precision varies by segment; cloud-based deployment and pharmaceutical end-use carry tighter precision than edge computing and research organization applications due to disclosed vendor reporting concentration. Forecasts reflect documented assumptions regarding interoperability implementation timelines and CMS payment model evolution. Regulatory enforcement intensity, health system consolidation velocity, and GPU supply availability constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
High Acuity Information Systems Market
Health Informatics
Healthcare Automatic Identification and Data Capture (AIDC) Market
Health Informatics
Global Radiology Information Systems Market
Health Informatics
Cat Allergy in Humans Market
Health Informatics
North America Laboratory Information System Market
Health Informatics
Healthcare BI Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
Global Non Clinical Information System Market