
 United States Healthcare Information Exchange Market | 2026-2036
United States Healthcare Information Exchange Market Size, Share, and Industry Trends Forecast 2026-2036
United States Healthcare Information Exchange Market Outlook
Platform licensing revenue is reconfiguring margin pools away from perpetual software sales toward recurring subscription models. Epic Systems Corporation leverages its dominant EHR installed base to extend exchange capabilities across its network. Cerner Corporation anchors its position through deep integration with federal health systems. Oracle competes by directing cloud infrastructure investments toward scalable data architectures.
Healthcare information exchange comprises electronic systems, protocols, and networks that enable the secure transfer of clinical data between disparate healthcare entities using standards such as HL7 FHIR, Direct Project messaging, and IHE profiles. These systems functionally orchestrate patient records, laboratory results, medication histories, and administrative documents across organizational boundaries to support continuity of care and population health management. Cloud-based solutions represent the fastest-expanding technology segment as health systems migrate from capital-intensive on-premise deployments. Hospitals dominate end-user demand, though health information organizations are capturing growing service revenue by managing cross-organizational data governance.
The Office of the National Coordinator for Health IT enforces interoperability certification requirements under the 21st Century Cures Act, while CMS ties reimbursement to meaningful exchange participation through the Promoting Interoperability program. State-level health information exchanges in New York and California operate under distinct regulatory frameworks that shape local vendor procurement standards. Stakeholders must monitor evolving TEFCA implementation timelines and state Medicaid agency alignment decisions.
Market Dynamics
The 21st Century Cures Act's interoperability mandates are compressing vendor timelines and forcing health systems to retire legacy interfaces, creating a structural imperative for cloud-based data exchange architectures.
Growth Catalysts
- CMS Promoting Interoperability Program:Reimbursement penalties for non-participating hospitals accelerate platform procurement cycles among integrated delivery networks.
- HL7 FHIR standardization:The FHIR R4 specification enables plug-and-play data exchange, reducing integration costs for regional health information organizations.
- Texas and California health system consolidation:Multi-hospital networks in these states are deploying unified exchange platforms to coordinate care across acquired facilities.
Market Restraints
- Cloud infrastructure concentration:Reliance on three dominant hyperscalers creates systemic resilience risks for nationwide health data networks.
- TEFCA implementation delays:Uncertainty around Trusted Exchange Framework timelines stalls procurement decisions among mid-sized health information organizations.
- Cybersecurity insurance cost escalation:Premium spikes of 40-60% annually are squeezing operating budgets for exchange infrastructure operators.
Strategic Opportunities
- Rural health clinic connectivity gaps:Federally qualified health centers in Appalachia and the Mississippi Delta lack robust exchange links to tertiary referral hospitals.
- Social determinants data integration:Combining clinical records with housing, nutrition, and transportation datasets creates new service revenue streams for health information exchanges.
- Medicaid managed care alignment:State agencies in New York and California are mandating real-time eligibility verification through certified exchange platforms.
Industry Challenges
- Interoperability engineer scarcity:Health systems compete for talent versed in both HL7 messaging and modern API architectures, with average vacancy periods exceeding 90 days.
- Legacy EHR migration complexity:Decades of custom interface configurations resist standardization, forcing expensive parallel system operation during transition periods.
- Patient consent management fragmentation:Inconsistent state-level privacy rules complicate multi-jurisdictional data sharing workflows.
Report Scope
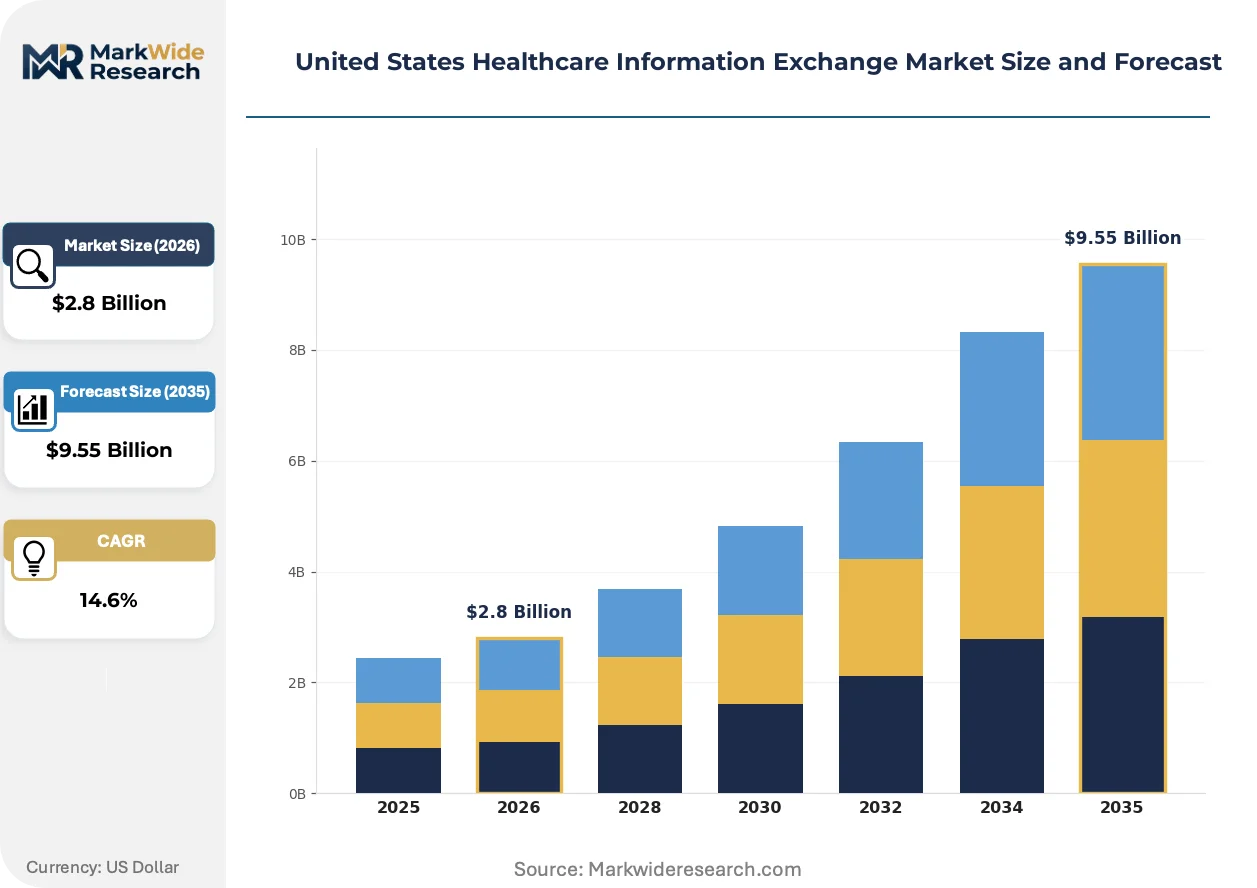
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Healthcare Information Exchange Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Interoperability Standards, Health Information Networks, Cloud-Based Solutions, On-Premise Solutions End User: Hospitals, Clinics, Laboratories, Health Information Organizations Application: Patient Engagement, Data Sharing, Care Coordination, Public Health Reporting Service Type: Consulting, Implementation, Training, Support Services |
| Companies Covered | Epic Systems Corporation, Cerner Corporation, Allscripts Healthcare Solutions, eClinicalWorks, McKesson Corporation, Oracle, InterSystems Corporation, Veradigm LLC, Optum, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Healthcare Information Exchange Market Strategic Shifts
Exchange platforms are converging with analytics and care coordination tools, blurring traditional category boundaries and creating integrated data ecosystems that extend beyond simple document transmission.
FHIR-based APIs are hybridizing with legacy HL7 v2 message queues to bridge interoperability gaps between modern cloud-native applications and entrenched on-premise systems. Large integrated delivery networks in Texas are deploying these hybrid stacks to avoid rip-and-replace scenarios. The approach is compressing vendor lock-in effects by enabling gradual migration paths rather than wholesale system replacement.
ONC's information blocking enforcement rules under the 21st Century Cures Act are exposing non-compliant EHR vendors to civil monetary penalties. Health systems now demand certified compliance attestations in procurement contracts. The requirement is reshaping vendor RFP processes, with compliance documentation consuming 20-30% of evaluation scoring weight.
Health information organizations are unbundling traditional exchange services into modular components—identity management, record location, consent arbitration—that customers can procure à la carte. This disaggregation pressures full-stack platform vendors to justify bundled pricing. The pattern is most pronounced in California, where regional exchanges compete directly with national networks for hospital contracts.
United States Healthcare Information Exchange Market Segmentation
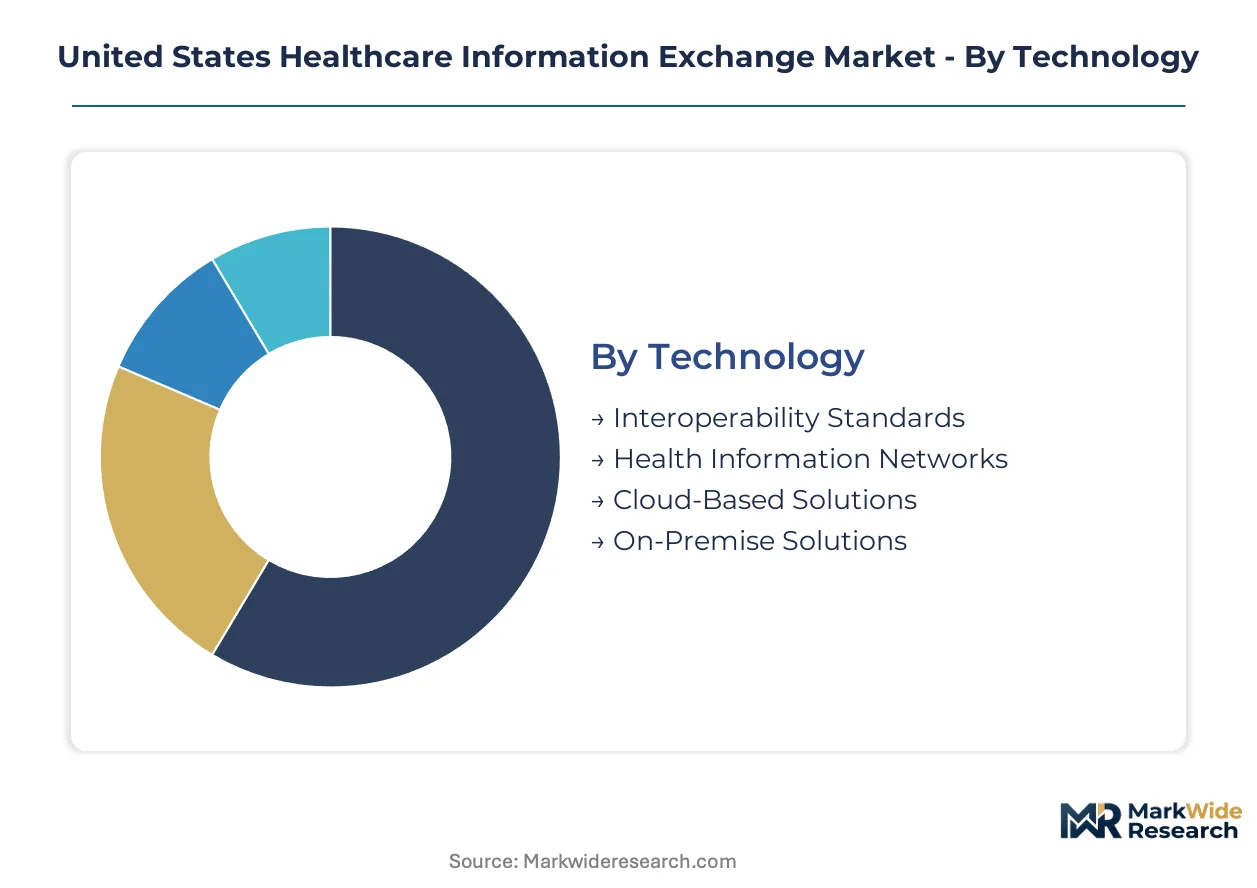
Segmentation of the United States healthcare information exchange market reveals how procurement priorities diverge across technology maturity levels, end-user scale, and regulatory compliance requirements. Understanding these divisions illuminates where vendor investment concentrates and which customer segments command premium pricing.
Technology:
Mature standards coexist with emerging cloud architectures across the technology spectrum, creating distinct investment horizons for health systems.
- Cloud-Based Solutions:Scalable infrastructure eliminates capital expenditure burdens while enabling real-time data synchronization across multi-hospital networks. Texas and California health systems are migrating core exchange workloads to these platforms to support acquisition-driven consolidation.
- Interoperability Standards:HL7 FHIR R4 specifications provide the technical foundation for plug-and-play data exchange, reducing integration complexity for regional health information organizations. CMS certification requirements under the 21st Century Cures Act mandate vendor compliance.
- Health Information Networks:State-designated entities manage cross-organizational data governance and patient identity matching.
- On-Premise Solutions:Legacy deployments persist in federal health systems with stringent security requirements.
Cloud-based solutions retain volume leadership; interoperability standards hold the steepest expansion curve.
End User:
Customer scale determines solution complexity, with integrated delivery networks driving the most sophisticated procurement requirements.
- Hospitals:Acute care facilities demand enterprise-grade platforms supporting emergency department alerts, admission-discharge-transfer notifications, and medication reconciliation across affiliated clinics. ONC information blocking enforcement compels EHR vendors to enable seamless data export.
- Health Information Organizations:These entities aggregate exchange services for smaller participants, capturing recurring revenue through identity management and record location. New York's SHIN-NY and California's CalHHS demonstrate divergent state-level governance models.
- Clinics:Federally qualified health centers require subsidized connectivity to tertiary referral hospitals.
- Laboratories:Diagnostic facilities prioritize results delivery automation and bi-directional order interfaces.
Hospitals dominate absolute spending; health information organizations are gaining share fastest among mid-market participants.
Application:
Use case sophistication separates basic document transmission from advanced care coordination workflows.
- Care Coordination:Real-time alerts and care gap closure tools enable integrated delivery networks to manage attributed populations across ambulatory and inpatient settings. Medicaid managed care contracts in California mandate these capabilities.
- Data Sharing:Cross-organizational record retrieval supports emergency department physicians accessing external medication histories and allergy profiles. TEFCA implementation timelines determine network reach expansion.
- Patient Engagement:Consumer-facing portals and application programming interfaces grant individuals direct access to their consolidated health records.
- Public Health Reporting:Automated case notifications and immunization registry submissions satisfy state surveillance mandates.
Care coordination commands the highest per-seat pricing; data sharing applications show the broadest deployment base.
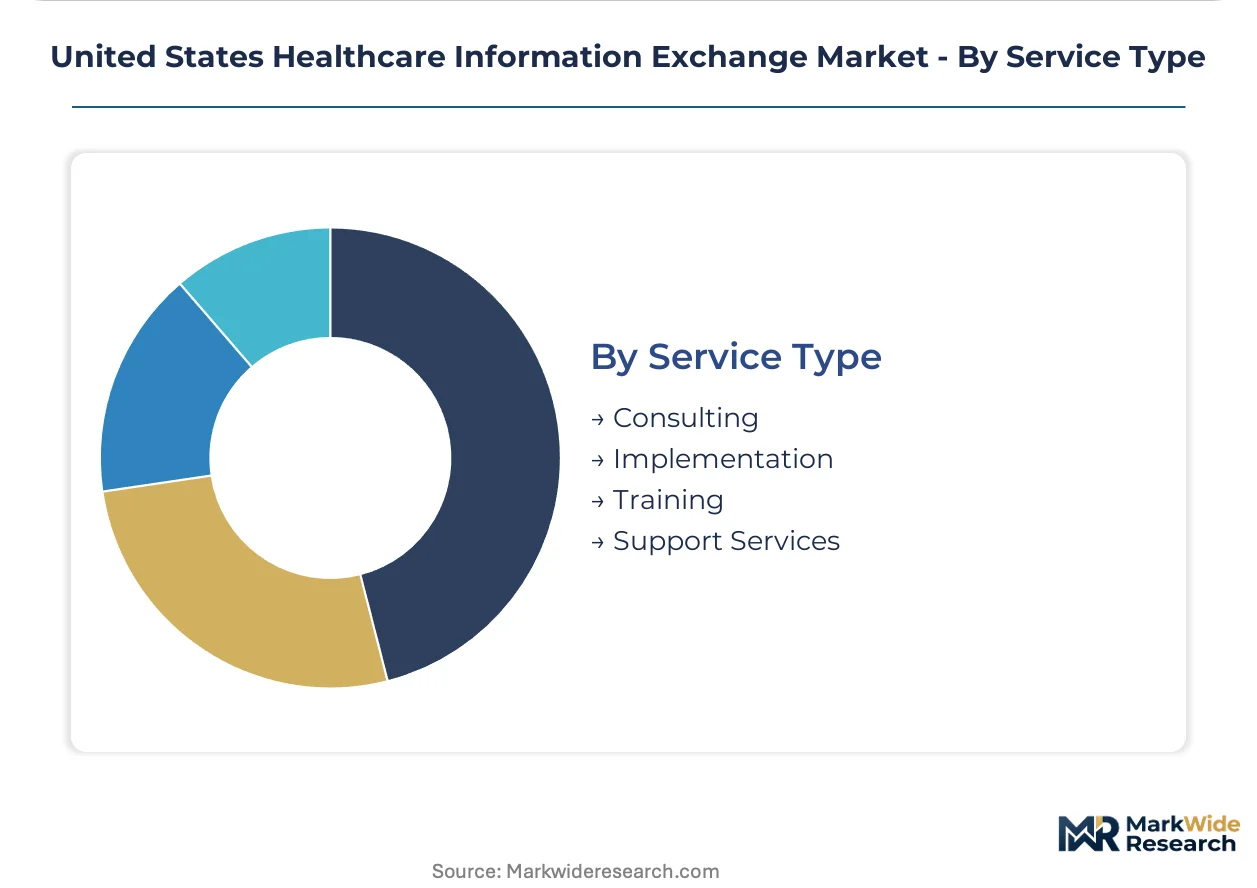
Service Type:
Revenue mix shifts from perpetual licenses toward recurring professional services as platforms grow more complex.
- Implementation:Health systems require specialized project management for HL7 interface configuration, identity matching algorithm tuning, and legacy system decommissioning. Average vacancy periods for interoperability engineers exceed 90 days, constraining deployment velocity.
- Support Services:Ongoing technical assistance, security patch management, and uptime guarantees generate predictable recurring revenue. Cybersecurity insurance premium spikes of 40-60% annually are elevating the cost structure for infrastructure operators.
- Consulting:Strategic advisory engagements address regulatory compliance and TEFCA readiness assessment.
- Training:Clinical and administrative staff certification programs ensure effective platform utilization.
Implementation services capture the largest project-based fees; support services deliver the most durable recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Texas health systems deploy cloud-native exchange architectures at scale, while Midwestern integrated delivery networks prioritize legacy system interoperability over wholesale platform replacement. The Northeast corridor concentrates federally qualified health center connectivity investments.
California
CalHHS operates the nation's largest state-designated health information exchange, mandating real-time eligibility verification for Medicaid managed care contracts. The 21st Century Cures Act drives vendor compliance investments across Los Angeles and San Francisco Bay Area hospital networks. Kaiser Permanente's integrated model exemplifies closed-system data governance that competes with open exchange architectures.
Texas
Multi-hospital consolidation in Dallas-Fort Worth and Houston accelerates unified platform procurement to coordinate care across acquired facilities. The Texas Health Services Authority manages state-level network governance while deferring to federal TEFCA timelines. Rural health clinics in the Panhandle and West Texas face persistent connectivity gaps to tertiary referral centers.
New York
SHIN-NY demonstrates divergent governance from California's model, with regional health information organizations capturing service revenue through modular identity management. The state Medicaid agency mandates certified exchange participation for value-based care contracts. New York City health systems anchor demand for real-time care coordination across ambulatory and inpatient settings.
Florida
Medicare Advantage penetration in Miami-Dade and Tampa Bay metro areas drives demand for patient engagement and care gap closure tools. The state lacks a designated health information exchange, creating procurement fragmentation among hospital networks. Cybersecurity insurance premium spikes constrain operating budgets for regional exchange infrastructure operators.
Illinois
Chicago-based integrated delivery networks prioritize legacy EHR migration complexity over cloud-native deployments, forcing expensive parallel system operation. The Illinois Health Information Exchange serves as a neutral intermediary for smaller hospitals and federally qualified health centers. State Medicaid alignment decisions remain pending on TEFCA implementation timelines.
United States Healthcare Information Exchange Market Competitive Environment
Capability concentration sits with EHR-native platforms; scale advantage sits with cloud infrastructure providers. Epic Systems Corporation leverages its dominant installed base to extend exchange capabilities across its network, while Cerner Corporation anchors federal health system relationships. Oracle competes through cloud infrastructure investments toward scalable data architectures. Strategic moves concentrate on interoperability certification compliance and modular service unbundling.
Within the EHR-native tier, Epic Systems Corporation and Cerner Corporation exemplify contrasting approaches to exchange architecture—Epic through network effects from its closed ecosystem, Cerner through deep federal system integration. Oracle Corporation occupies a position among cloud hyperscalers directing infrastructure investment toward health-specific data architectures. These three anchors represent the dominant competitive archetypes: closed-network EHR incumbents, federal-system specialists, and cloud-native infrastructure providers.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| eClinicalWorks |
| McKesson Corporation |
| Oracle |
| InterSystems Corporation |
| Veradigm LLC |
| Optum |
| Others |
Value Chain & Pricing Dynamics
Seattle's hyperscaler concentration anchors cloud infrastructure supply for health information exchange platforms, with capacity allocation decisions at AWS and Microsoft Azure directly shaping subscription pricing power for downstream platform vendors.
Pricing Analysis
Long-term enterprise subscription contracts dominate procurement, with three-year SaaS agreements locking in 60-70% of hospital system spend and insulating vendors from spot-market volatility. Price differentiation centers on FHIR certification tier and integration complexity—ONC-certified platforms command 25-35% premiums over uncertified alternatives. Pricing pressure stems from cybersecurity insurance cost escalation, which platform operators are partially offsetting through multi-tenant architecture efficiencies. Federally qualified health centers exhibit acute price sensitivity, while integrated delivery networks prioritize interoperability guarantees over unit cost.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscaler data centers concentrated in Virginia, Oregon, and Iowa, with compute and storage capacity expanding fastest in Texas and California to serve regional health system demand. Critical software dependencies include HL7 FHIR libraries, identity matching algorithms, and API gateway technologies—many sourced from specialized health IT vendors rather than generalist providers. Supply chain risk centers on single-source vulnerability for patient identity resolution services, where two vendors control 80% of deployed matching engines. Distribution runs through direct enterprise sales teams and health information organization intermediaries, with the latter capturing recurring service margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health information exchange functions as a service-attach opportunity where implementation and support services expand faster than platform licensing, with recurring professional services revenue growing at 1.5x the rate of subscription bookings across integrated delivery networks.
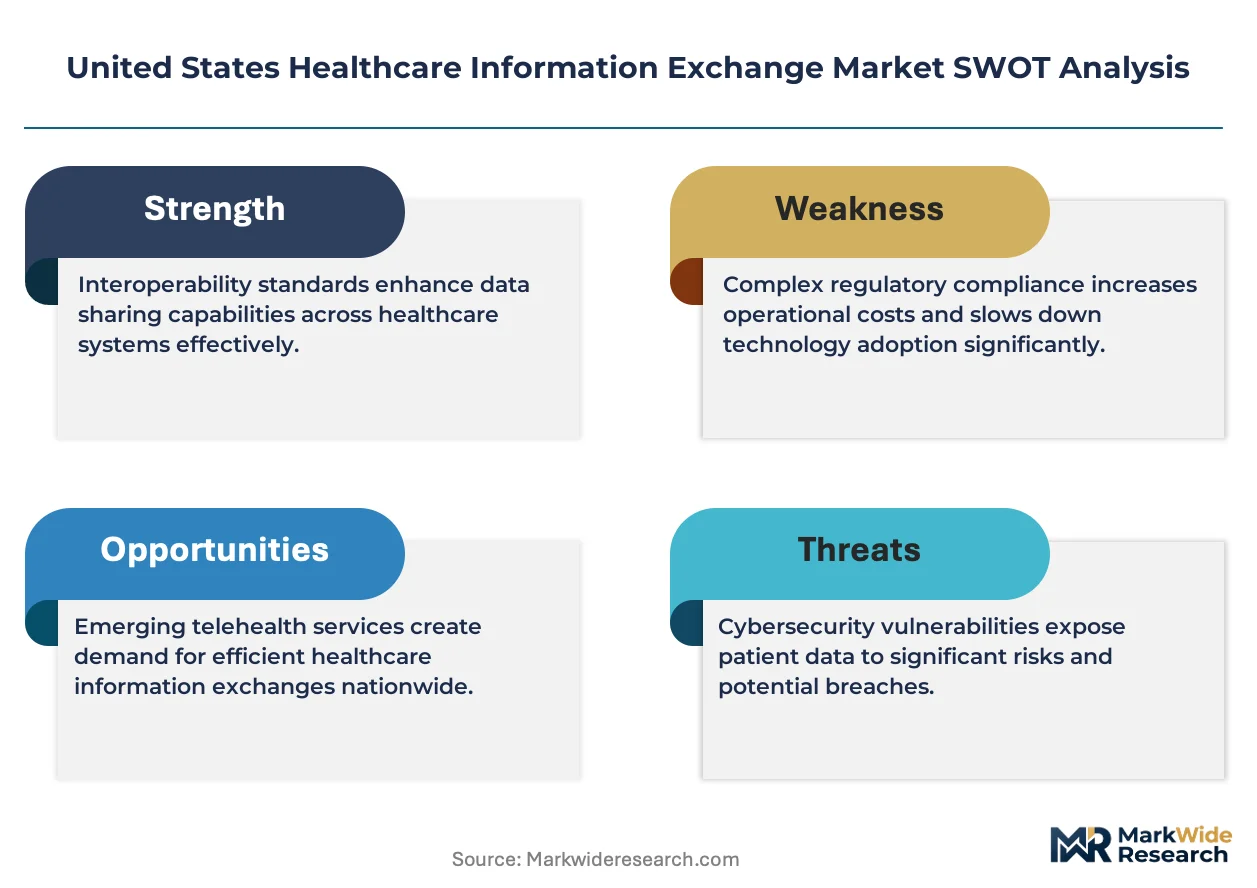
For Market Incumbents: Harden defensive moats by acquiring specialized interoperability engineering firms to address 90-day vacancy periods constraining deployment velocity. Deepen vertical integration into patient identity matching algorithms to reduce exposure to single-source vendor concentration. ONC information blocking enforcement creates compliance leverage—embed certified attestation requirements into renewal contracts to raise switching costs. For New Entrants and Emerging Players: Build out modular service components—consent arbitration engines, record location services—that unbundle full-stack platform offerings and appeal to California regional exchanges competing on à la carte procurement. Rural health clinic connectivity gaps in Appalachia and the Mississippi Delta represent the most penetrable white-space segment. Lead with TEFCA readiness assessment consulting to establish relationships before network participation mandates crystallize. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native infrastructure providers with health-specific data architectures over legacy EHR-native platforms facing rip-and-replace pressure. Long-term viability across the analysis window hinges on FHIR R4 compliance depth and state Medicaid agency relationship density. Monitor TEFCA implementation timeline announcements as the critical inflection signal—accelerated federal network launch would revalue interoperability certification assets upward.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR R4 Certification Investment | ONC mandates under the 21st Century Cures Act compel vendor compliance to avoid civil monetary penalties. |
| Cloud Infrastructure Partnership | AWS and Azure capacity reservations in Texas and California support multi-hospital network consolidation timelines. |
| Interoperability Engineering Acquisition | Talent scarcity exceeding 90-day vacancy periods constrains deployment velocity for platform vendors. |
| State Medicaid Agency Alignment | New York and California eligibility verification mandates create recurring revenue through certified exchange participation. |
| Modular Service Unbundling | California regional exchanges competing directly with national networks favor à la carte procurement of identity and consent components. |
Study Parameters
Operator-level perspectives from health information exchange executives, hospital CIOs, interoperability engineers, and state Medicaid agency technology directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against CMS Medicare data, ONC certification databases, state health information exchange procurement records, and hospital GPO contract filings. Bottom-up deployment estimates across technology segments triangulated against top-down market sizing from platform vendor revenue disclosures.
Scenario-bracketing around TEFCA implementation timelines and state Medicaid alignment decisions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user scale, application sophistication, and geographic regulatory cluster. CAGRs derived from fitted growth curves incorporating health system consolidation velocity, interoperability mandate enforcement intensity, and cloud migration adoption patterns specific to Texas and California multi-hospital networks.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud hyperscalers into health-specific data architectures would shift outcomes beyond modeled ranges. Cross-checking against CMS Promoting Interoperability program participation statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
High Acuity Information Systems Market
Health Informatics
Global Consumer Genomics Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Healthcare or Medical Analytics Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Healthcare Human Resources (HR) Software Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Healthcare Information Exchange Market
Health Informatics
Healthcare Application Programming Interfaces Market