
 Healthcare Payer Services Market | 2026-2036
Healthcare Payer Services Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Payer Services Market Intelligence
The integration of AI-driven analytics as a managed service is restructuring how payers procure and utilize claims management solutions. UnitedHealth Group leverages its vast data assets to develop proprietary risk and compliance management tools for its health plans. Cigna specializes in member enrollment and targeted customer support services for large, national employer clients. Centene Corporation focuses on navigating the complex requirements of serving government-sponsored healthcare programs.
Healthcare payer services encompass the administrative, financial, and clinical support functions outsourced by health insurance providers and other risk-bearing entities. These services rely on data integration platforms to manage complex, high-volume workflows like member enrollment, premium billing, and claims adjudication. Within service types, Claims Management remains the largest category due to its direct impact on operational costs and medical loss ratios. AI-driven analytics represents the fastest-growing technology segment as payers seek to identify fraud and optimize utilization review.
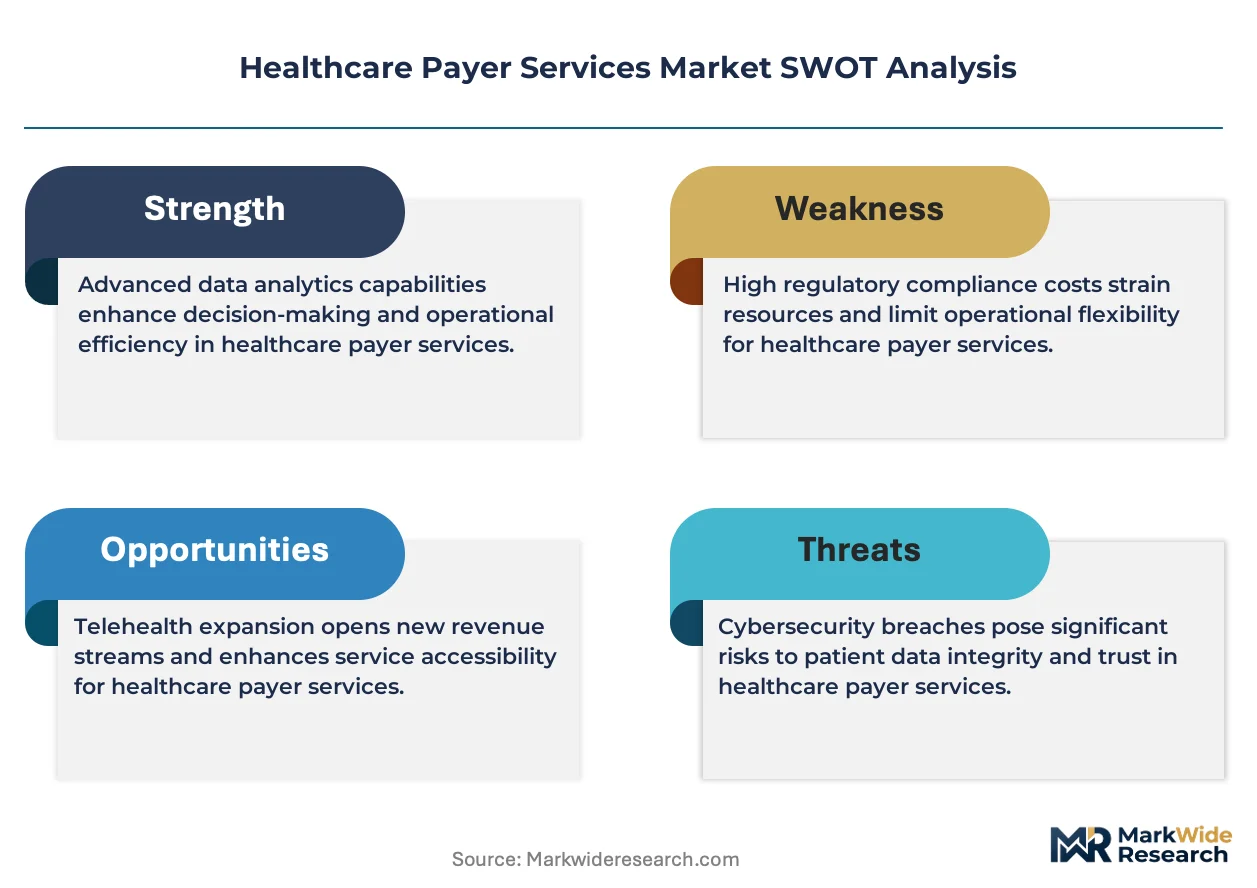
Regulatory frameworks such as the Health Insurance Portability and Accountability Act (HIPAA) in the United States and the General Data Protection Regulation (GDPR) in Europe impose strict data security and privacy requirements. Adherence to these standards, alongside national interoperability rules, is a prerequisite for market access. Payer organizations must now decide whether to build these complex compliance and analytics capabilities in-house or partner with specialized service vendors.
Market Dynamics
The imperative for healthcare cost containment among large employers and governments is the central force shaping the payer services market. This pressure compels payers to adopt advanced data analytics and outsourced administrative solutions to improve operational efficiency and manage medical loss ratios under tightening regulatory scrutiny.
Growth Catalysts
- AI-Driven Analytics Adoption:Payers are implementing AI-powered platforms to automate claims processing, detect fraud, and optimize utilization management, driven by the need to reduce operational expenditures and improve decision-making accuracy.
- Demand from Self-Insured Employers:Large corporations in the United States increasingly rely on specialized third-party administrators to manage employee health benefits, seeking greater control over healthcare spending and access to sophisticated cost-containment tools.
- Government Program Outsourcing:Government agencies in European countries are outsourcing the administration of public health programs to specialized vendors capable of navigating complex regulatory requirements and managing large, diverse populations.
Market Restraints
- Legacy System Integration:The high cost and technical complexity of integrating modern service platforms with payers' existing, often outdated, core administrative systems create significant barriers to adoption and prolong implementation timelines.
- Data Privacy and Security Regulations:Stringent regulations like HIPAA in the United States and GDPR in Europe impose substantial compliance burdens and financial penalties for data breaches, increasing operational risk for service vendors.
- Lack of Interoperability:The absence of universal data standards across the healthcare ecosystem hinders the seamless exchange of information between payers, providers, and service vendors, limiting the effectiveness of analytics and care coordination services.
Strategic Opportunities
- Value-Based Care Enablement:There is a significant opportunity for services that help payers transition from fee-for-service to value-based reimbursement models by providing analytics for measuring provider performance and patient outcomes.
- Expansion in Asia-Pacific:Growing middle-class populations and increasing private health insurance penetration in countries like India and Indonesia present an underpenetrated market for outsourced payer administrative and clinical support services.
- Blockchain for Claims Management:The convergence of AI with blockchain technology offers a pathway to develop highly secure, transparent, and automated platforms for claims adjudication and payment integrity, reducing disputes and administrative friction.
Industry Challenges
- Talent Scarcity:A persistent shortage of professionals with dual expertise in healthcare data analytics and information security complicates vendor efforts to scale operations and develop innovative new services.
- Data Aggregation Complexity:Integrating and normalizing vast, unstructured datasets from diverse sources such as electronic health records, pharmacy benefit managers, and patient-reported outcomes remains a major technical hurdle.
- Navigating Interoperability Mandates:Adhering to evolving national and regional data exchange rules requires continuous investment in technology and compliance resources, posing a challenge for smaller service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Payer Services Market |
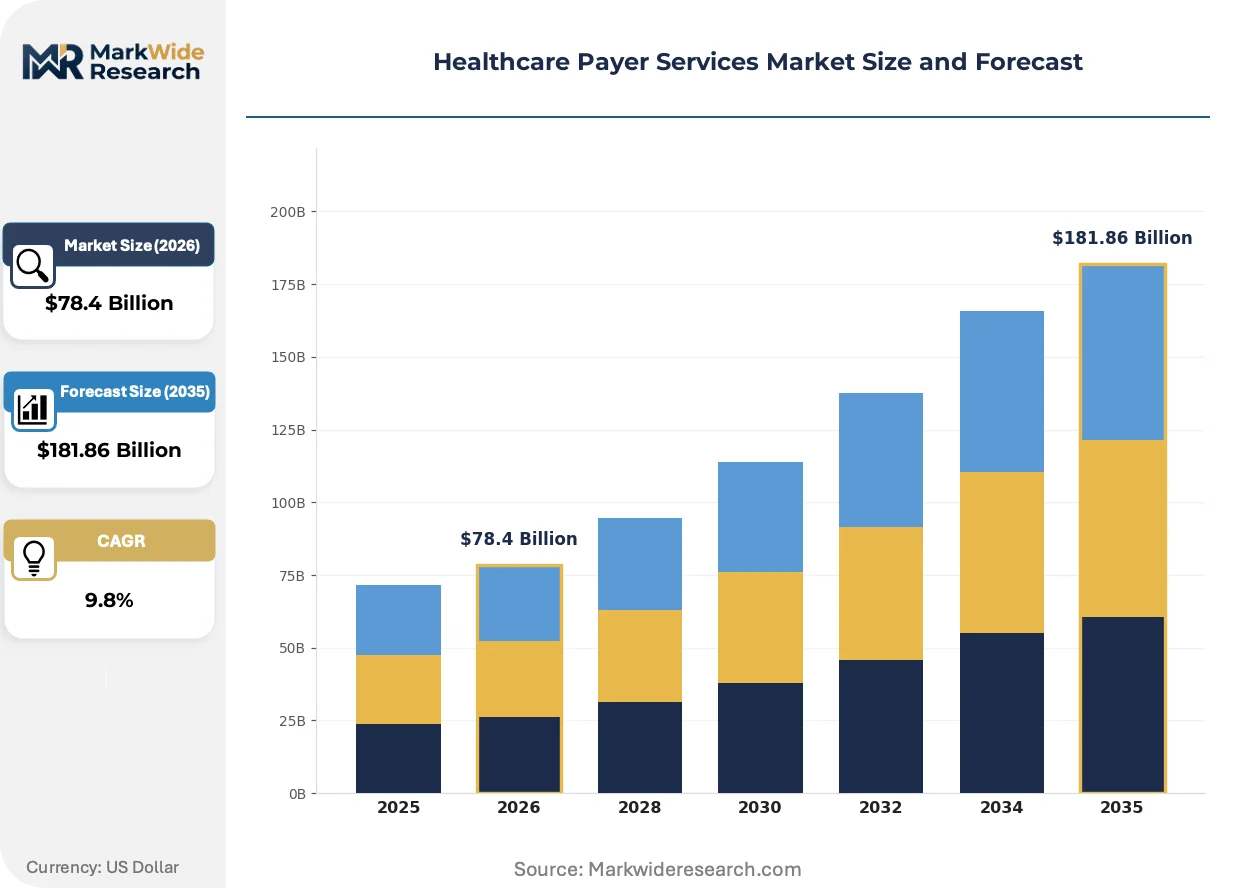
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $181.86 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Claims Management, Member Enrollment, Billing & Collections, Risk & Compliance Management, Customer Support, Utilization Review Technology: Cloud-based Solutions, AI-driven Analytics, Blockchain, Robotic Process Automation, Natural Language Processing, Data Integration Platforms End User: Health Plans, Third-Party Administrators, Self-insured Employers, Government Agencies, Managed Care Organizations, Brokerage Firms Deployment Model: On-premise, Software as a Service, Hybrid Cloud, Hosted Infrastructure, Platform as a Service, Virtual Private Cloud |
| Companies Covered | Centene Corporation, Kaiser Permanente, UnitedHealth Group, Molina Healthcare, HCSC Group, CVS Health, Humana, Cigna, Elevance Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Payer Services Market Strategic Shifts & Innovations
The market's evolution is defined by a strategic shift towards leveraging technology not just for efficiency, but as a core competitive differentiator. AI-driven automation and platform-based service delivery are becoming standard as payers seek integrated solutions to manage cost, compliance, and member engagement simultaneously.
Generative AI is being embedded within payer service platforms to automate complex tasks like prior authorization review and creating personalized member communications. Large health plans and third-party administrators are leading the adoption to handle rising transaction volumes without scaling their workforce. This technology is rewriting the cost structure of claims and member management by automating cognitive labor and improving service consistency.
New regulations governing artificial intelligence, such as the EU AI Act, are establishing risk-based frameworks for algorithmic systems. This is forcing vendors of AI-based payer tools to build in transparency and explainability, especially for functions like utilization review or risk scoring. The analytics segment is most affected, now investing heavily in algorithmic audits and compliance documentation to maintain access to European markets.
A fundamental change in purchasing behavior is visible as payers move from procuring single-point services to subscribing to integrated service platforms. This trend disrupts the business model for niche vendors specializing only in enrollment or billing, creating an advantage for larger providers offering a bundled suite of administrative tools. This shift is most apparent among large national employers in the United States seeking a unified vendor relationship to simplify administration.
Healthcare Payer Services Market Segmentation
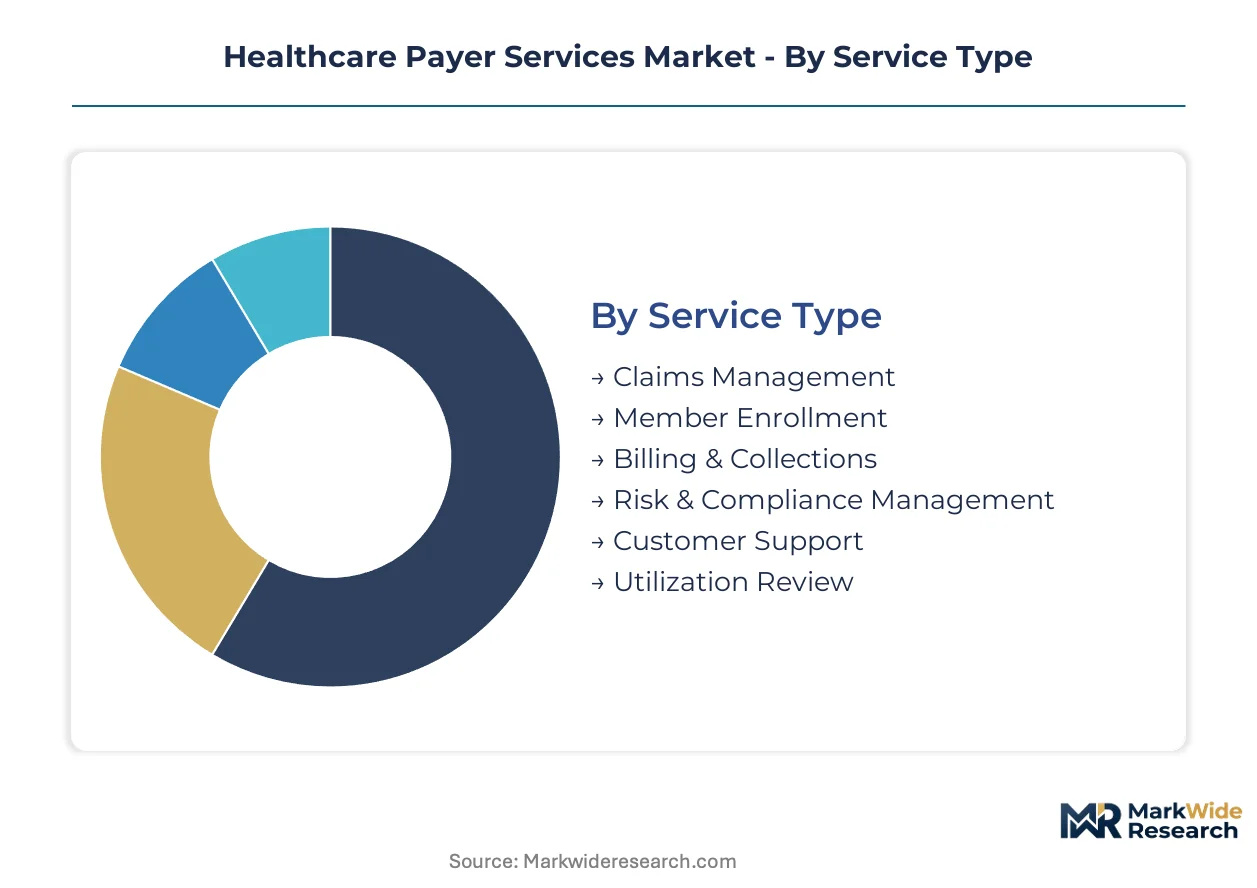
The Healthcare Payer Services Market segments define the specialized offerings and operational models supporting health insurance providers. Understanding these distinctions helps stakeholders identify areas of high demand and pinpoint optimal service delivery methods for diverse client bases. Segmentation reveals how technology and deployment choices align with specific end-user requirements and regulatory environments.
Service Type:
Supply concentration for payer services often aligns with core administrative functions that directly impact financial performance and regulatory compliance. These services streamline the complex interactions between payers, providers, and members.
- Claims Management:This service involves the processing, adjudication, and payment of medical claims submitted by healthcare providers. It directly influences operational costs and medical loss ratios for payers, making it a critical outsourced function.
- Utilization Review:This service assesses the medical necessity and appropriateness of healthcare services, aiming to control costs and ensure quality care. AI-driven analytics are increasingly integrated to optimize decision-making and reduce manual effort.
- Member Enrollment:This involves the administrative tasks associated with onboarding new members and managing existing member data.
- Billing & Collections:These services manage premium invoicing, payment processing, and overdue account recovery for health plans.
- Risk & Compliance Management:This segment provides expertise and tools to navigate complex regulatory frameworks like HIPAA in the United States and GDPR in Europe.
- Customer Support:This includes call center operations and digital platforms for member inquiries, benefits explanations, and issue resolution.
Today's leader: Claims Management. Tomorrow's challenger: Utilization Review.
Technology:
The application of advanced technologies is fundamentally reshaping how payer services are delivered and consumed, enabling greater efficiency and analytical depth. These technologies address operational bottlenecks and enhance data-driven decision-making.
- AI-driven Analytics:These platforms utilize artificial intelligence and machine learning to automate fraud detection, optimize utilization review processes, and personalize member engagement. Payers in the United States and Europe are rapidly adopting these tools for cost containment.
- Data Integration Platforms:These systems consolidate and normalize disparate datasets from various sources, enabling comprehensive insights for claims processing and member management. They are essential for managing high-volume workflows.
- Cloud-based Solutions:These offer scalable and flexible infrastructure for hosting payer applications and data, reducing the need for extensive on-premise IT investments.
- Blockchain:This distributed ledger technology provides secure, transparent, and immutable records, offering potential for streamlined claims adjudication and payment integrity.
- Robotic Process Automation:RPA automates repetitive, rule-based administrative tasks, such as data entry and verification, improving accuracy and speed.
- Natural Language Processing:NLP tools analyze unstructured text data from clinical notes or member communications, extracting valuable insights for risk assessment and care coordination.
AI-driven Analytics is expanding most quickly due to its direct impact on operational efficiency. Data Integration Platforms maintain their essential role in enabling complex workflows.
End User:
Customer type significantly influences the specific service configurations and regulatory expertise required from payer service vendors. Each end-user segment presents unique demands for administrative and clinical support.
- Health Plans:These large insurance carriers outsource a range of administrative, financial, and clinical support functions to manage their vast member bases and operational complexities. UnitedHealth Group and Cigna leverage these services to enhance their offerings.
- Self-insured Employers:Large corporations in the United States directly bear the financial risk of their employees' healthcare costs, requiring specialized third-party administrators for benefits management and cost containment strategies. This group seeks greater control over healthcare spending.
- Government Agencies:Public health programs in Europe and other regions outsource administration to vendors capable of navigating complex national regulations and managing large, diverse populations. Centene Corporation focuses on these programs.
- Third-Party Administrators:TPAs manage various aspects of employee benefits plans for self-insured companies, acting as intermediaries between employers and healthcare providers.
- Managed Care Organizations:MCOs contract with healthcare providers and facilities to provide comprehensive healthcare services to members, often requiring robust administrative support.
- Brokerage Firms:These firms assist employers and individuals in selecting and managing health insurance plans, sometimes leveraging payer services for enrollment or customer support.
Health Plans exert the most influence over service innovation due to their scale. Self-insured Employers are gaining market power through their direct purchasing decisions.
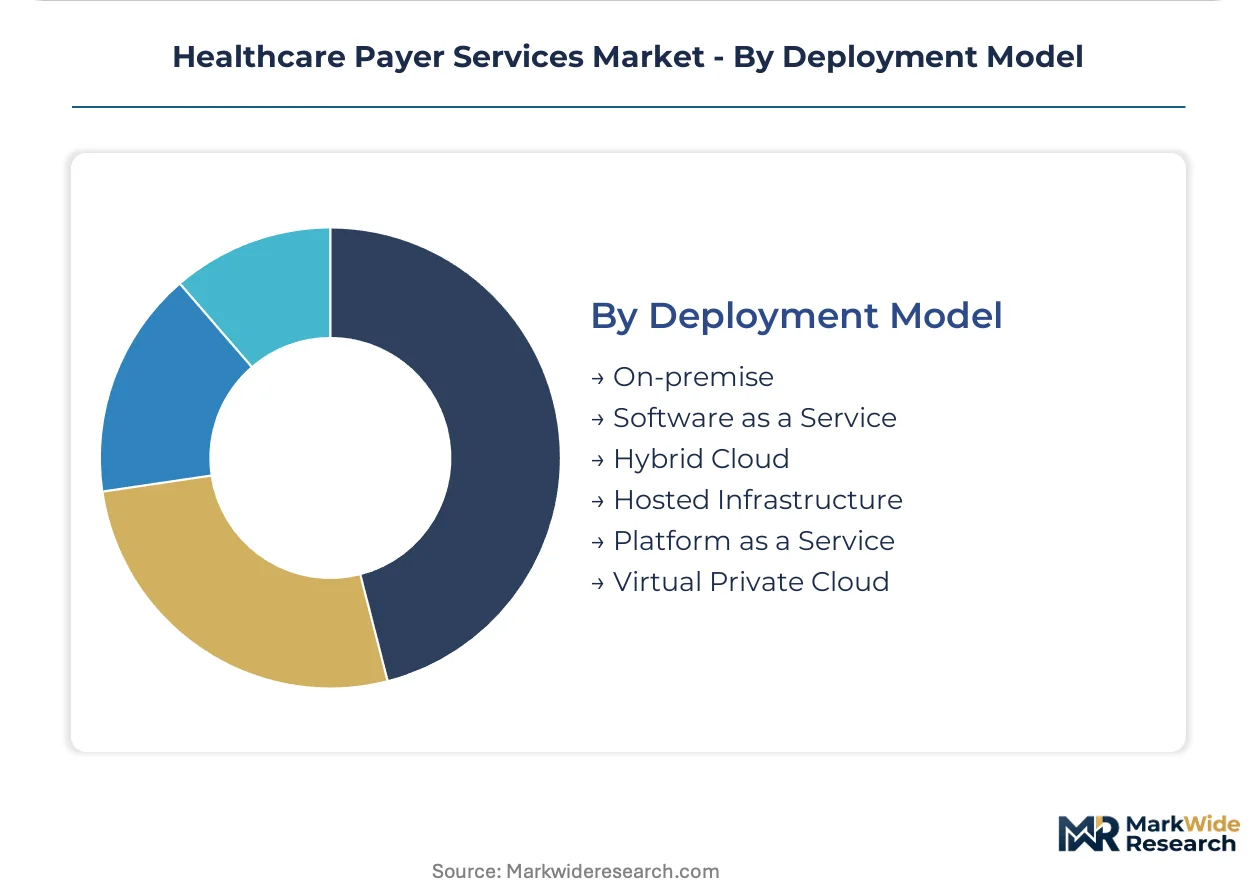
Deployment Model:
The deployment model dictates how payer service solutions are hosted and accessed, impacting scalability, security, and integration with existing IT infrastructure. Organizations choose models based on their specific security needs and legacy system constraints.
- Software as a Service:SaaS models deliver software applications over the internet on a subscription basis, offering scalability and reduced IT overhead for payers. This model is widely adopted by smaller and mid-sized health plans.
- Hybrid Cloud:This model combines on-premise infrastructure with public or private cloud services, allowing payers to maintain sensitive data locally while leveraging cloud flexibility for other applications. It addresses legacy system integration challenges for large enterprises.
- On-premise:Solutions are installed and run on the payer's own servers and infrastructure, providing maximum control over data and security. This is common for organizations with stringent data governance requirements.
- Hosted Infrastructure:Third-party providers host and manage the payer's applications and data in their data centers, offering a balance between control and outsourced management.
- Platform as a Service:PaaS provides a cloud-based environment for developing, running, and managing applications without the complexity of building and maintaining infrastructure.
- Virtual Private Cloud:VPC offers a logically isolated section of a public cloud, providing a private, secure cloud computing environment for payer operations.
Software as a Service shows the broadest adoption across market participants. Hybrid Cloud deployment is demonstrating increasing traction among larger healthcare organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States leads in the adoption of advanced payer services due to its complex insurance landscape, while European nations prioritize cost containment within public health systems. This market demonstrates varied regional drivers shaped by distinct healthcare financing models and regulatory environments. Demand for outsourced administrative and analytical capabilities continues to grow across mature and emerging economies.
United States
Large self-insured employers in the United States demand sophisticated third-party administration for employee health benefits and advanced cost-containment tools. HIPAA imposes stringent data security and privacy requirements on all healthcare entities, influencing service provider offerings. Major technology hubs like San Francisco and Boston are developing innovative AI-driven analytics solutions for the payer services market.
Germany
German government agencies are increasingly outsourcing public health program administration to specialized vendors capable of navigating complex national regulations. GDPR imposes strict data privacy rules, while the EU AI Act influences the development of algorithmic systems in healthcare. Cities such as Munich and Berlin host a growing number of health tech startups focusing on AI-driven analytics for payers.
United Kingdom
The National Health Service (NHS) and private health insurers in the United Kingdom seek advanced claims management and utilization review services to improve operational efficiency. GDPR remains a critical regulatory framework for data handling, alongside national interoperability rules guiding information exchange. London's vibrant financial and technology sectors support the development of sophisticated health insurance platforms.
India
India's growing middle-class population and increasing private health insurance penetration create significant demand for scalable administrative and clinical support services. The country's national data protection laws are evolving, impacting how payer services handle sensitive health information. Bangalore and Hyderabad are emerging as key centers for IT and business process outsourcing services supporting global healthcare payers.
France
French public health programs and private insurers require robust compliance solutions and efficient administrative support to manage national healthcare expenditures. The CNIL enforces GDPR within France, and national health data policies significantly shape service delivery models. Paris is a hub for digital health innovation, attracting companies focused on leveraging AI in healthcare administration.
Healthcare Payer Services Market Key Industry Players
Top-tier vendors anchor the market through integrated service platforms, while specialized niche players focus on specific administrative functions. The market exhibits a tiered structure with large incumbents offering comprehensive solutions and agile technology providers innovating in specific areas. Strategic archetypes include comprehensive service providers, technology-driven specialists, and regional administrators, with dominant competitive moves involving strategic partnerships for technology integration and portfolio diversification into AI-driven analytics.
Among the comprehensive service providers, UnitedHealth Group represents a major force, leveraging vast data assets for proprietary risk management tools and extensive health plan operations. Cigna exemplifies a specialist in member enrollment and targeted customer support services, particularly for large national employer clients seeking streamlined benefits administration. Centene Corporation occupies a distinct position by focusing on navigating the complex requirements of government-sponsored healthcare programs, demanding specialized expertise in regulatory compliance and diverse population management. These entities collectively demonstrate the varied approaches to market leadership within the payer services domain.
| Leading Market Players |
|---|
| Centene Corporation |
| Kaiser Permanente |
| UnitedHealth Group |
| Molina Healthcare |
| HCSC Group |
| CVS Health |
| Humana |
| Cigna |
| Elevance Health |
Cost & Logistics Intelligence
Large self-insured employers in the United States increasingly influence pricing models, favoring subscription-based platforms for cost containment and transparent value delivery. This concentration of purchasing power drives service providers toward outcome-based contracts.
Pricing Analysis
Capacity additions in technology hubs like San Francisco and Berlin are reshaping price floors for AI-driven analytics. The dominant pricing model for payer services is a hybrid of subscription-based platforms and value-based contracts, reflecting service complexity. Price differentiation stems from specialized compliance expertise, such as GDPR adherence, and the depth of AI integration. Pricing softness emerges from the imperative for healthcare cost containment among large employers, making government agencies and self-insured employers highly price sensitive.
Supply Chain Analysis
Adherence to stringent regulatory certifications like HIPAA in the United States and GDPR in Europe gates market access for payer service providers. Geographic supply concentration for technology development centers around the United States and Germany, with India emerging for business process outsourcing. The supply chain relies on specialized AI algorithms, robust data integration platforms, and secure cloud infrastructure. Talent scarcity for healthcare data analytics represents a structural risk. Distribution runs primarily through direct sales to health plans and large self-insured employers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Healthcare Payer Services Market presents a significant margin-expansion story, primarily driven by the integration of AI-driven automation. This technology dramatically reduces operational costs for claims management and utilization review.
For Market Incumbents: Extend integrated service platforms to offer comprehensive solutions across the payer value chain. Consolidate market share by acquiring niche AI analytics firms, countering the threat from agile technology providers. Deepen vertical integration into AI-driven analytics R&D to maintain a competitive edge. Focus on enhancing compliance capabilities for evolving regulations like the EU AI Act.
For New Entrants and Emerging Players: Launch via cloud-based SaaS models, targeting underpenetrated markets like Asia-Pacific for outsourced administrative services. Focus on value-based care enablement analytics as a white-space opportunity. The most penetrable segment involves mid-sized self-insured employers seeking specialized AI-driven utilization review tools. A key go-to-market angle involves offering transparent, explainable AI solutions to address EU AI Act compliance requirements.
For Investors and Strategic Acquirers: Large health plans and technology conglomerates are the most active acquirers in this space, seeking to enhance their digital capabilities. The market demonstrates strong long-term viability over the next 5-10 years, driven by the ongoing need for cost containment and regulatory compliance. Acquisition targets should be AI-driven analytics specialists and data integration platform providers. The signal to watch is the increasing investment in blockchain technology for claims management.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-driven Automation Integration | Enhances claims processing efficiency and fraud detection accuracy for payers. |
| Value-Based Care Platform Development | Supports health plans in transitioning to outcome-focused reimbursement models. |
| Global Compliance Solution Rollout | Addresses diverse regulatory demands like HIPAA and GDPR across multiple regions. |
| Strategic Partnership with Tech Vendors | Accelerates the adoption of advanced analytics and cloud infrastructure. |
| Expansion into Asia-Pacific Markets | Captures demand from growing private health insurance sectors. |
Research Approach
Multiple input streams — financial reports, regulatory documents, and industry publications — were reconciled to build a comprehensive market view. Primary interviews with health plan executives, third-party administrators, and AI solution architects provided qualitative insights. Secondary validation included analysis of SEC filings and government health reports. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
Integrating primary and secondary data streams established the quantitative modeling framework across the analysis window. Segmentation dimensions modeled included service type, technology, end user, deployment model, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected AI adoption rates. Healthcare expenditure trends and evolving regulatory mandates served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological disruption or major regulatory shifts. All forecasts reflect underlying assumptions regarding AI integration and healthcare policy stability. Deviation in national interoperability mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Insurance
US Healthcare Discount Plan Market
Health Insurance
Healthcare Insurance Market
Health Insurance
UAE Health and Medical Insurance Market
Health Insurance
UAE Health Insurance Third Party Administrators (TPA) Market
Health Insurance
Health Insurance Market
Health Insurance
Healthcare Reimbursement Market
Health Insurance
Germany Health Insurance Market
Health Insurance
Healthcare Payer Solution Market
Health Insurance
North America Group Health Insurance Market
Health Insurance
Indonesia Health and Medical Insurance Market
Health Insurance
UAE Health Insurance Market
Health Insurance
US Group Health Insurance Market
Health Insurance
United States Health and Medical Insurance Market