
 Asia Pacific Geographic Information System (GIS) Market | 2026-2036
Asia Pacific Geographic Information System (GIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Geographic Information System (GIS) Market Insights
ISO 19115 geospatial metadata certification is collapsing the vendor qualification cycle, forcing smaller platform providers to accelerate compliance investments or exit public-sector procurement. Esri leverages its decades-long R&D intensity to sustain proprietary format dominance across Australian and Japanese government accounts. SuperMap Software Co., Ltd. anchors its position through deep localization for China's GB-compliant spatial data infrastructure mandates. Hexagon AB competes on sensor-to-software integration, controlling high-precision data capture workflows that differentiate its offerings from pure-play software rivals.
Asia Pacific Geographic Information System technology encompasses hardware, software, and services for capturing, storing, analyzing, and visualizing spatially referenced data, typically operating with sub-meter accuracy through coordinate reference systems aligned to regional geodetic datums. Its primary commercial purpose is to enable location-based decision-making across infrastructure lifecycle management, environmental compliance, and emergency response coordination. Cloud GIS deployment now leads technology adoption as municipal budgets shift from capital-intensive on-premise installations to operational expenditure models, while geospatial analytics represents the fastest-expanding capability layer as artificial intelligence-enhanced pattern recognition penetrates environmental monitoring and transportation planning workflows. Remote sensing retains mature, high-volume status through satellite imagery subscriptions, though margin pools increasingly migrate toward SaaS-based analytics platforms that transform raw imagery into actionable intelligence.
China's SAMR enforces national spatial data security classifications that restrict cross-border data transfers, reshaping how multinational vendors architect cloud deployments for Chinese state clients. Japan's METI coordinates JIS-compliant geospatial frameworks that standardize interoperability between municipal systems and private infrastructure operators, while India's BIS develops domestic spatial data quality benchmarks aligned with its National Geospatial Policy. Australia's national positioning infrastructure regulations, administered through Geoscience Australia, mandate centimeter-level accuracy standards for autonomous vehicle testing corridors. Stakeholders must monitor whether emerging data localization requirements fragment platform architectures into country-specific instances or whether regional interoperability frameworks emerge to preserve economies of scale.
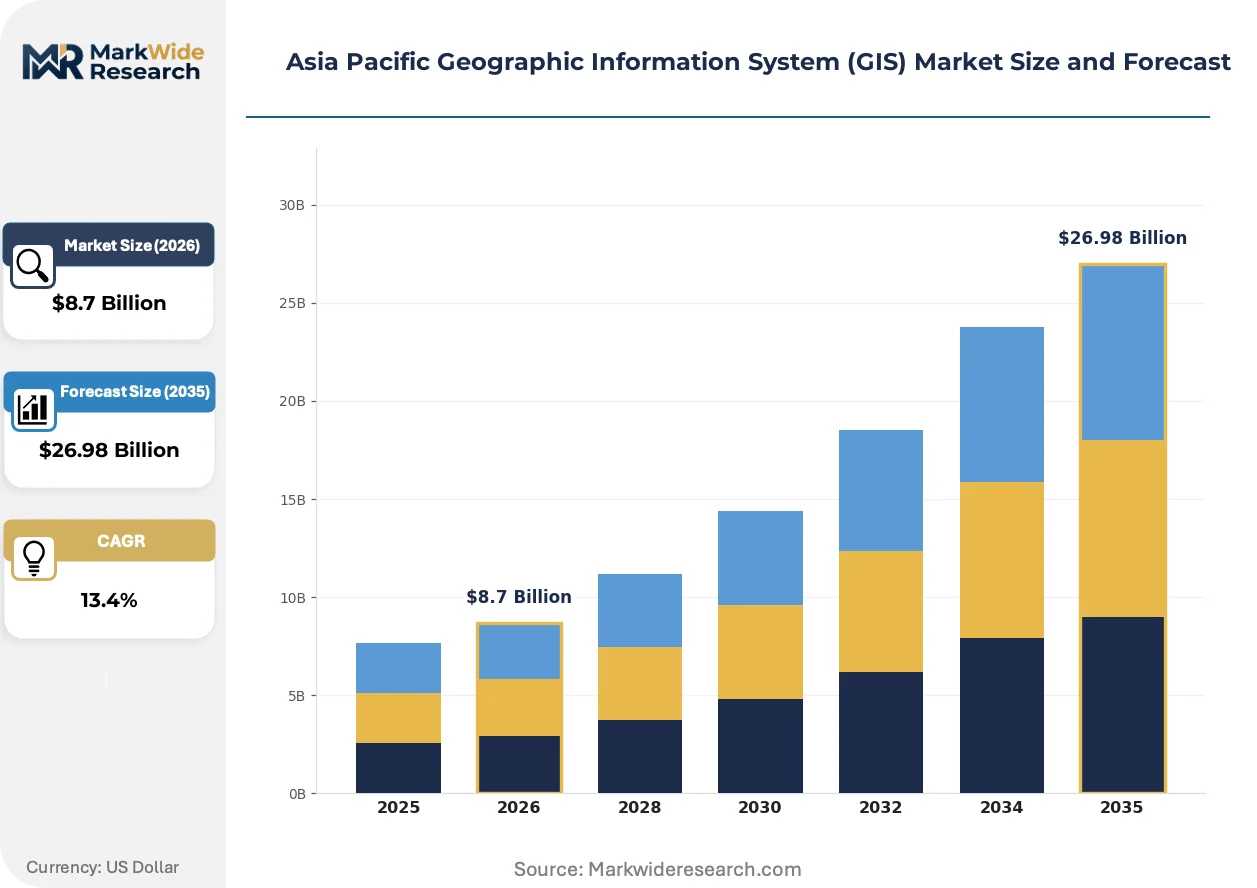
Market Dynamics
Cloud-native deployment architectures are compressing procurement cycles for municipal GIS platforms across Asia Pacific, forcing legacy on-premise vendors to restructure pricing models or surrender public-sector contracts to subscription-based competitors.
Growth Catalysts
- China's dual carbon monitoring mandates:Provincial environmental bureaus now require real-time emissions tracking through spatial analytics, pulling utility operators toward integrated GIS-IoT platforms.
- Smart city infrastructure digitization:Urban planning authorities in India and Vietnam deploy cloud GIS for traffic corridor optimization and flood-risk mapping, accelerating vendor qualification among regional system integrators.
- AI-enhanced satellite imagery analytics:Pattern recognition algorithms applied to remote sensing data are penetrating agricultural yield forecasting and coastal erosion monitoring, expanding addressable use cases beyond traditional cadastral applications.
Market Restraints
- Cross-border data transfer restrictions:China's SAMR national spatial data security classifications force multinational vendors to maintain country-isolated cloud instances, fragmenting platform architectures and diluting economies of scale.
- Geodetic datum heterogeneity:Japan's JIS-compliant frameworks, China's GB standards, and India's BIS benchmarks create interoperability friction that prolongs system integration timelines and inflates deployment costs.
- High-precision sensor import dependencies:LiDAR and GNSS receiver supply concentrates among specialized manufacturers in Germany and Switzerland, exposing Asia Pacific integrators to currency volatility and extended lead times.
Strategic Opportunities
- Indonesia's archipelagic maritime mapping gap:The national geospatial agency's incomplete bathymetric coverage creates white space for hydrographic survey services and coastal zone management platforms.
- Philippines disaster resilience bonds:Catastrophe-linked financing instruments tied to geospatial risk modeling are channeling development capital toward flood and landslide early-warning system deployments.
- 5G network digital twin convergence:Telecommunications operators in South Korea and Australia are layering GIS with radio propagation modeling to optimize small-cell placement, opening new vertical demand.
Industry Challenges
- ISO 19115 metadata certification bottlenecks:Smaller platform providers face compressed vendor qualification windows as public-sector procurement tightens compliance requirements, forcing accelerated R&D expenditure or exit decisions.
- Geospatial data scientist scarcity:The intersection of remote sensing expertise, machine learning proficiency, and domain knowledge in urban planning or environmental science remains under-supplied across Asia Pacific labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Geographic Information System (GIS) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Urban Planning, Environmental Monitoring, Disaster Management, Transportation Planning Technology: Remote Sensing, Data Management, Geospatial Analytics, Cloud GIS End User: Government Agencies, Engineering Firms, Utility Companies, Real Estate Developers Deployment: On-Premise, Cloud-Based, Hybrid Solutions, SaaS |
| Companies Covered | Esri, Hexagon AB, Autodesk Inc., Trimble Inc., Bentley Systems Incorporated, SuperMap Software Co., Ltd., Topcon Corporation, Caliper Corporation, Mappointasia (Thailand) Public Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Geographic Information System (GIS) Market Trends and Innovations
Edge computing architectures and AI inference at the sensor level are redistributing analytical workloads away from centralized cloud instances, compressing latency for real-time infrastructure monitoring applications.
Embedded GNSS receivers and solid-state LiDAR modules are miniaturizing to handheld and drone-mountable form factors. Surveying contractors in Australia and Japan are adopting these reduced-weight payloads for rapid deployment in dense urban corridors and hazardous terrain. The technology is miniaturizing hardware procurement thresholds, enabling municipal governments and smaller engineering consultancies to bypass capital-intensive mobile mapping vehicle investments.
Japan's METI-coordinated JIS X 7105 geospatial interoperability framework is mandating standardized API protocols between municipal GIS platforms and private infrastructure operators. The regulation forces legacy system vendors to expose data layers through open interfaces, eroding proprietary format lock-in that previously protected incumbent market positions. Transportation and utilities sectors face the steepest compliance timelines, with Tokyo Metropolitan Government contracts already requiring certified interoperability testing.
Subscription-based SaaS analytics are displacing perpetual-license software sales across provincial and municipal procurement channels. Australian local governments now prioritize operational expenditure models that bundle imagery processing, feature extraction, and dashboard visualization under single annual contracts. This preference shift concentrates vendor selection criteria on recurring service quality metrics rather than upfront feature comparisons, rewarding platform providers with robust cloud infrastructure over traditional desktop software specialists.
Asia Pacific Geographic Information System (GIS) Market Segmentation
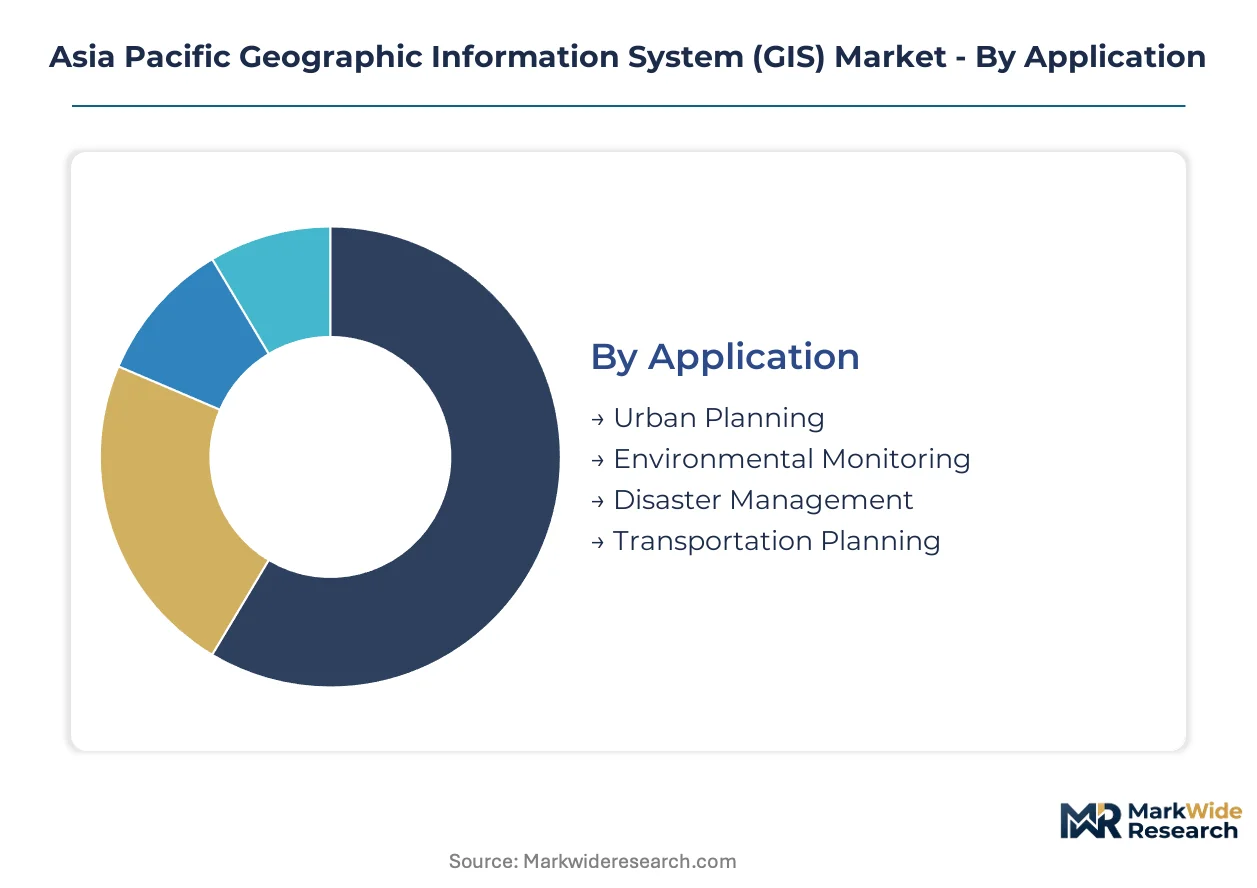
GIS procurement patterns diverge sharply across Asia Pacific, with municipal governments favoring perpetual-license hardware-software bundles while private infrastructure operators migrate toward subscription analytics. Segment boundaries increasingly blur as cloud-native platforms absorb traditional deployment categories and AI-enhanced capabilities reshape application hierarchies.
Application:
Channel mix varies by application maturity, with established urban planning workflows flowing through systems integrators and emerging environmental monitoring use cases shifting direct-to-vendor.
- Urban Planning:Municipal zoning authorities deploy 3D cadastral mapping and corridor optimization tools for smart city masterplans. China's eastern coastal provinces concentrate procurement volume as provincial governments consolidate spatial data infrastructure under unified cloud platforms.
- Environmental Monitoring:Real-time emissions tracking and ecosystem health assessment now absorb the majority of new AI-enhanced satellite imagery subscriptions. Provincial environmental bureaus across China pull utility operators toward integrated GIS-IoT platforms under dual carbon compliance mandates.
- Disaster Management:Flood-risk mapping and landslide early-warning systems channel development capital through catastrophe-linked financing instruments in the Philippines.
- Transportation Planning:Traffic corridor optimization and autonomous vehicle testing corridor mapping concentrate demand in India and Vietnam's urban planning authorities.
Urban Planning dominates installed base. Environmental Monitoring is where expansion concentrates.
Technology:
Cost tier stratification separates high-margin analytics layers from commoditized data capture infrastructure, with premium pricing attaching to AI inference capabilities.
- Remote Sensing:Satellite imagery subscriptions retain mature, high-volume status though margin pools migrate toward SaaS-based analytics platforms that transform raw imagery into actionable intelligence. Agricultural yield forecasting and coastal erosion monitoring now absorb pattern recognition algorithm deployments.
- Geospatial Analytics:Machine learning-enhanced pattern recognition penetrates environmental monitoring and transportation planning workflows, commanding premium pricing through outcome-based service models. The capability layer is expanding most quickly as municipal budgets prioritize operational expenditure models over capital-intensive hardware procurement.
- Cloud GIS:Municipal governments across Australia now prioritize subscription bundles that consolidate imagery processing, feature extraction, and dashboard visualization under single annual contracts.
- Data Management:Spatial database administration and metadata compliance tools anchor back-end infrastructure for ISO 19115-certified deployments.
Remote Sensing anchors revenue volume. Geospatial Analytics is climbing the fastest.
End User:
Customer type determines procurement complexity, with government agencies demanding certified interoperability while private developers prioritize speed-to-insight.
- Government Agencies:Municipal and provincial authorities drive procurement volume through smart city digitization mandates and national geospatial policy compliance. Japan's METI-coordinated JIS X 7105 framework forces legacy vendors to expose data layers through standardized API protocols, eroding proprietary format lock-in.
- Utility Companies:Electricity, water, and telecommunications operators integrate GIS with SCADA and network digital twin platforms for real-time infrastructure monitoring. South Korean and Australian telecommunications operators layer GIS with radio propagation modeling to optimize 5G small-cell placement.
- Engineering Firms:Surveying contractors adopt miniaturized solid-state LiDAR and embedded GNSS payloads for rapid deployment in dense urban corridors and hazardous terrain.
- Real Estate Developers:Site selection and portfolio risk assessment workflows increasingly source location intelligence through SaaS analytics rather than in-house GIS departments.
Government Agencies command largest contract value. Utility Companies are gaining share fastest.
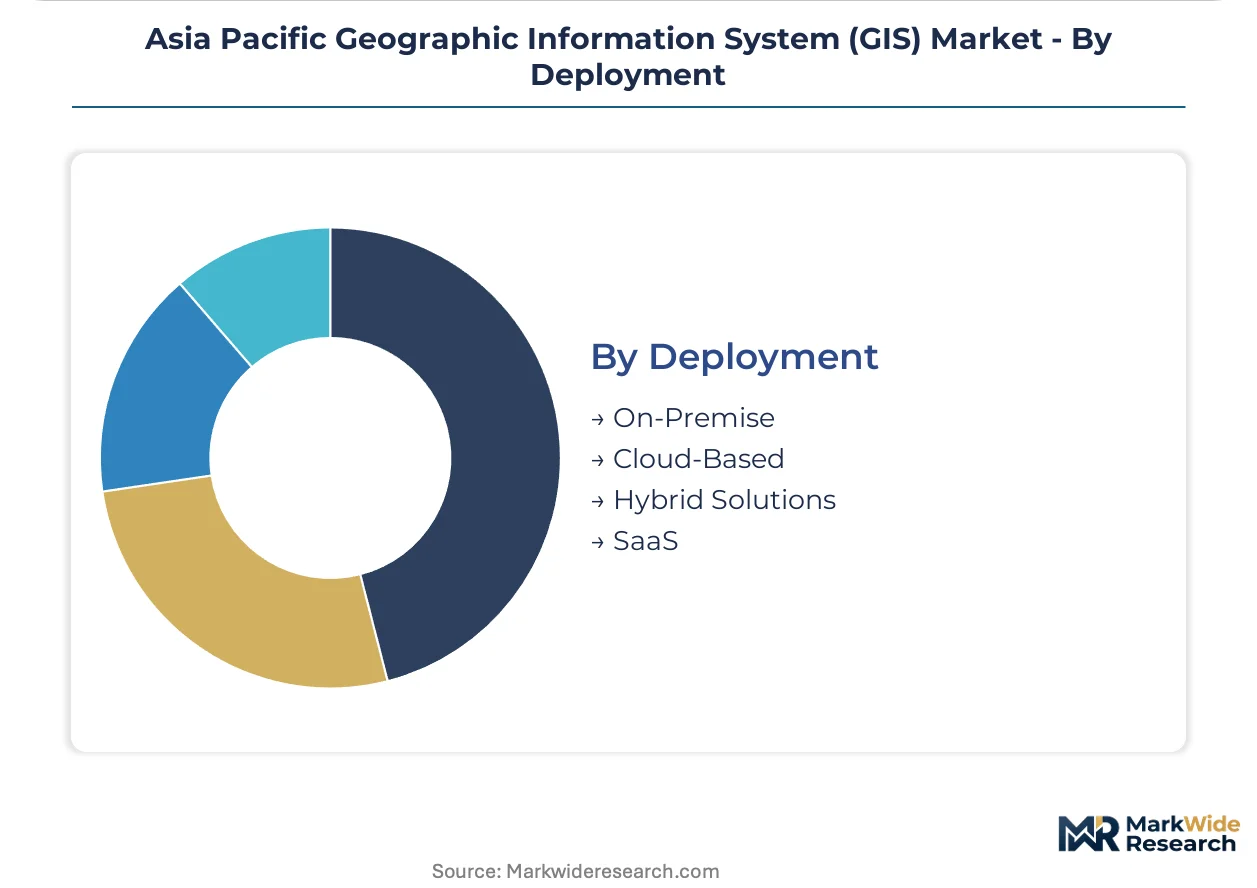
Deployment:
Supply concentration in hyperscale cloud infrastructure is reshaping competitive positioning, with regional data residency requirements fragmenting platform architectures.
- Cloud-Based:Municipal budgets shift from capital-intensive on-premise installations to operational expenditure models, compressing procurement cycles and forcing legacy vendors to restructure pricing. China's SAMR national spatial data security classifications force multinational vendors to maintain country-isolated cloud instances.
- SaaS:Subscription-based analytics displace perpetual-license software sales across provincial and municipal procurement channels, concentrating vendor selection on recurring service quality metrics. Australian local governments now bundle imagery processing, feature extraction, and dashboard visualization under single annual contracts.
- Hybrid Solutions:Edge computing architectures redistribute analytical workloads between centralized cloud instances and sensor-level inference for latency-sensitive applications.
- On-Premise:Legacy installations persist in classified government facilities and critical infrastructure operators subject to air-gapped security requirements.
On-Premise retains installed base in sensitive facilities. Cloud-Based is where vendor competition concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal governments and utility operators concentrate procurement across coastal provinces and metropolitan corridors where smart city mandates intersect with environmental compliance deadlines.
China
Provincial environmental bureaus in Jiangsu and Guangdong deploy cloud GIS for real-time emissions tracking under dual carbon mandates. SAMR enforces national spatial data security classifications that restrict cross-border transfers, forcing multinational vendors into country-isolated cloud architectures. Shanghai and Shenzhen municipal governments consolidate spatial data infrastructure under unified platforms for infrastructure monitoring.
Japan
Tokyo Metropolitan Government contracts require JIS X 7105-certified interoperability testing between municipal platforms and private infrastructure operators. METI coordinates geospatial frameworks that standardize API protocols, eroding proprietary format lock-in among legacy vendors. Osaka and Nagoya transportation authorities face steep compliance timelines for open data layer exposure.
India
Urban planning authorities in Maharashtra and Karnataka deploy cloud GIS for traffic corridor optimization and flood-risk mapping under National Geospatial Policy alignment. BIS develops domestic spatial data quality benchmarks that accelerate vendor qualification among regional system integrators. Bengaluru and Mumbai concentrate smart city digitization procurement.
Australia
Geoscience Australia administers national positioning infrastructure regulations mandating centimeter-level accuracy for autonomous vehicle testing corridors in Victoria and Queensland. Local governments prioritize subscription bundles bundling imagery processing and dashboard visualization under single annual contracts. Sydney and Melbourne municipal budgets shift from capital-intensive on-premise installations to operational expenditure models.
South Korea
Telecommunications operators in Seoul and Busan layer GIS with radio propagation modeling to optimize 5G small-cell placement. National digital twin initiatives channel procurement toward integrated sensor-to-software workflows. Gyeonggi Province authorities deploy edge computing architectures for latency-sensitive infrastructure monitoring applications.
Asia Pacific Geographic Information System (GIS) Market Competitive Landscape
Player mix skews toward diversified geospatial technology conglomerates with sensor manufacturing capabilities and pure-play software specialists with deep localization expertise. Market structure exhibits tiered concentration where proprietary format dominance persists in government accounts while subscription-based challengers compress procurement cycles. Two strategic archetypes define competitive positioning: sensor-integrated platform providers controlling high-precision data capture workflows, and cloud-native analytics vendors bundling AI-enhanced pattern recognition. Dominant competitive moves include geographic localization investments to satisfy data residency requirements and portfolio diversification into SaaS analytics to capture recurring revenue streams.
Within the sensor-integrated tier, Hexagon AB and Topcon Corporation exemplify hardware-software convergence strategies that differentiate offerings from pure-play rivals. Among Asia-Pacific-based specialists, SuperMap Software Co., Ltd. anchors its position through deep localization for national spatial data infrastructure mandates. Esri occupies a position representing decades-long R&D intensity sustaining proprietary format dominance across Australian and Japanese government accounts.
| Leading Market Players |
|---|
| Esri |
| Hexagon AB |
| Autodesk Inc. |
| Trimble Inc. |
| Bentley Systems Incorporated |
| SuperMap Software Co., Ltd. |
| Topcon Corporation |
| Caliper Corporation |
| Mappointasia (Thailand) Public Company Limited |
| Others |
Pricing and Supply Chain Analysis
Annual subscription bundles bundling imagery processing, feature extraction, and dashboard visualization lock in municipal procurement commitments across Australian and Japanese local governments while providing vendors predictable recurring revenue visibility. These multi-year SaaS contracts tie price stability to cloud infrastructure scale, compressing margins for legacy on-premise vendors unable to match operational expenditure flexibility.
Pricing Analysis
Cost-plus contracts with GNSS receiver and solid-state LiDAR indexation dominate hardware-software integration procurement. Three-tier pricing structure across premium certification-grade, standard compliance-tier, and economy self-service levels separates Esri's proprietary ecosystem from SuperMap's localization bundles and Hexagon's sensor-integrated workflows. Pricing pressure stems from compressed municipal procurement cycles forcing legacy vendors toward subscription restructuring. Government agencies exhibit lowest price sensitivity due to compliance mandates, while smaller engineering consultancies face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of high-precision sensors prevails among Japanese and Australian integrators exposed to German and Swiss LiDAR lead time volatility, while Chinese vendors maintain just-in-time component flows through domestic supply chain density. Hardware concentration centers on Germany, Switzerland, and China for LiDAR modules, GNSS receivers, and embedded processors. Raw material dependencies span rare earth elements for solid-state laser components, precision optical glass, and semiconductor substrates. Single-source vulnerability concentrates in Swiss GNSS receiver manufacturers. Distribution runs through regional system integrators holding SAMR, METI, and BIS certification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific GIS penetration remains in early-cycle expansion as cloud-native deployment architectures displace perpetual-license procurement across municipal governments. Smart city digitization mandates in India and Vietnam accelerate this substitution pattern.
For Market Incumbents: Secure proprietary format dominance through accelerated ISO 19115 certification investments before compressed qualification windows close smaller competitors. Lock in sensor-to-software integration workflows controlling high-precision data capture to defend against pure-play SaaS challengers. Vertical integration into solid-state LiDAR manufacturing reduces German-Swiss supply dependency exposure. For New Entrants and Emerging Players: White-space in Indonesia's incomplete bathymetric coverage and Philippine catastrophe-linked financing instruments offers beachhead entry points. Municipal environmental monitoring in Vietnam's Mekong Delta provinces presents the most penetrable segment given limited incumbent localization. Channel partnerships with regional system integrators holding BIS and SAMR certifications accelerate vendor qualification timelines. For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native analytics specialists with AI-enhanced pattern recognition capabilities and established hyperscaler infrastructure relationships. Long-term viability hinges on recurring revenue model transition completion and data residency compliance architecture deployment. Watch for SAMR cross-border transfer rule tightening as inflection indicator forcing multinational vendor localization investments.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Subscription restructuring captures Australian municipal operational expenditure shifts from capital-intensive legacy procurement. |
| AI-Enhanced Analytics Layer Development | Machine learning inference capabilities penetrate environmental monitoring workflows under China's dual carbon compliance mandates. |
| Sensor Hardware Integration | LiDAR-GNSS convergence differentiates offerings from pure-play software rivals in Japanese government accounts. |
| Localization Certification Investment | SAMR, METI, and BIS compliance architectures preserve public-sector procurement access across fragmented regulatory regimes. |
| Strategic Partnership with System Integrators | Regional channel control accelerates vendor qualification among Indian and Vietnamese urban planning authorities. |
Research Methodology
Operator-level perspectives from municipal GIS procurement officers, cloud platform engineers, surveying contractors, and environmental bureau technical leads anchored the qualitative base. These primary interviews combined with secondary validation from SEC filings of listed geospatial technology providers, METI and SAMR regulatory disclosure databases, and hyperscaler cloud infrastructure capex reports. Bottom-up municipal procurement pipeline analysis triangulated against top-down market sizing from hardware shipment tracking and SaaS subscription disclosure patterns.
Sensitivity analysis across deployment model, end-user vertical, and certification tier dimensions informed the analytical framework over the projection horizon. CAGRs derived from segment-level adoption curves weighted by municipal budget allocation patterns and utility capital expenditure disclosure trends. Forecast inputs incorporated cloud infrastructure availability zone expansion timelines and national geospatial policy implementation schedules.
Forecasts assume regulatory continuity in China's SAMR data classification regime, Japan's METI-coordinated JIS frameworks, and India's National Geospatial Policy alignment; material policy shifts would require re-modeling. Cross-border transfer restriction tightening, geodetic datum standardization breakthroughs, or precision sensor export control expansion represent specific revision triggers. Revision becomes warranted when cloud procurement penetration in municipal budgets crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
US Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
Nigeria Geospatial Analytics Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
Global Digital Maps Market
Geographic Information Systems (GIS)
Location Intelligence Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Satellite Image Data Services Market
Geographic Information Systems (GIS)
US Location-Based Services Market