
 Geospatial Analytics Market | 2026-2036
Geospatial Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Geospatial Analytics Market Intelligence
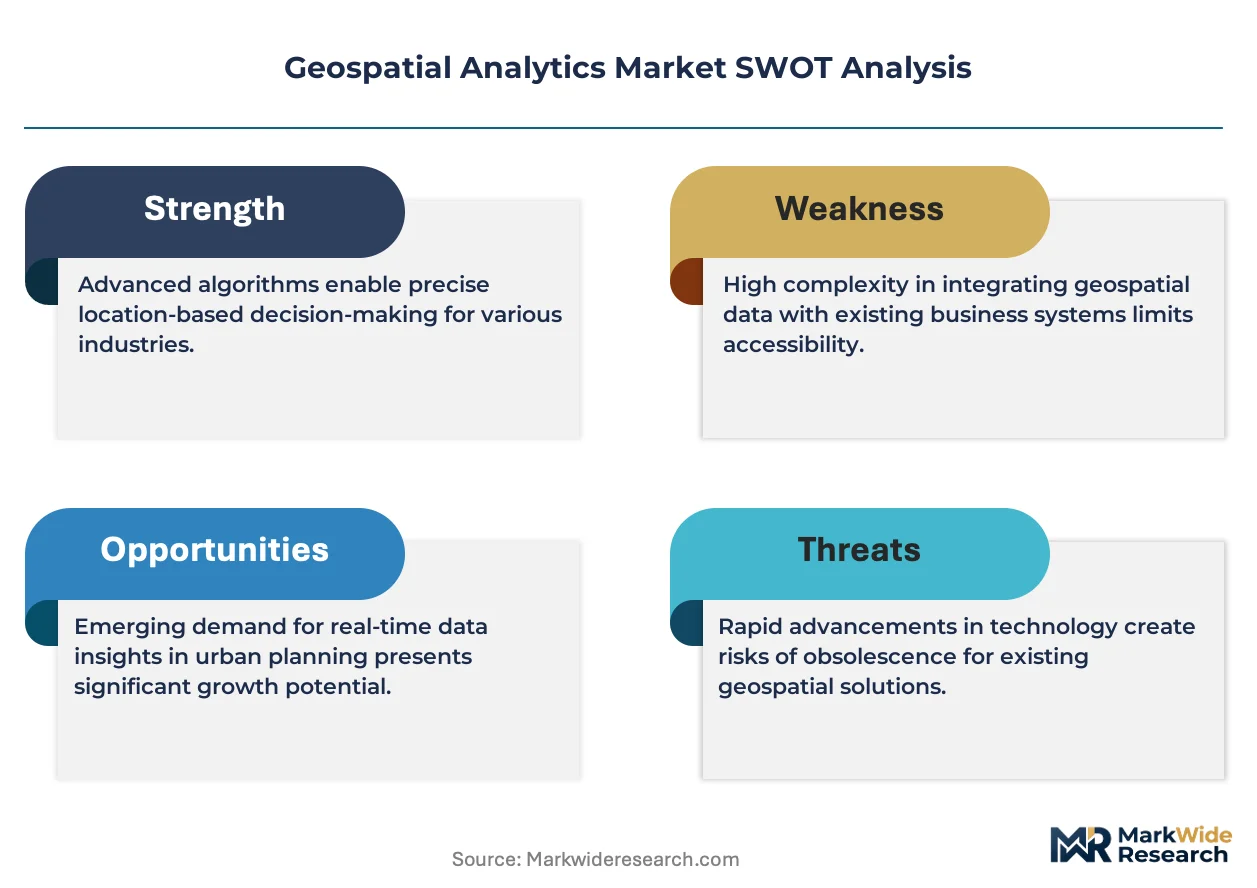
Project finance for satellite constellation deployments is tilting competitive dynamics toward capital-light analytics providers. Esri leverages its ArcGIS platform dominance to anchor enterprise subscriptions across municipal agencies. Trimble Inc. competes through precision agriculture hardware-software integration that extends its reach into farm-level decision systems. Hexagon AB specializes in sensor fusion for autonomous mapping vehicles, sustaining premium positioning in surveying markets.
Geospatial analytics encompasses the capture, processing, and visualization of location-based data through coordinate-referenced information systems, typically operating at sub-meter spatial resolution for commercial applications. Its primary purpose is to transform satellite imagery, LiDAR point clouds, and GPS trajectories into actionable intelligence for asset tracking, risk assessment, and infrastructure planning. Artificial Intelligence within the technology segment leads in growth velocity as machine learning pipelines automate feature extraction from multispectral imagery. Cloud-Based deployment captures expanding margin pools by eliminating on-premises infrastructure barriers for mid-size utilities and insurance carriers. Government end users remain the largest revenue category, though Agriculture is accelerating fastest as variable-rate input optimization spreads.
The EU Green Deal and CSRD disclosure rules are mandating geospatial verification of land-use change and carbon stock estimates, directly shaping procurement specifications for environmental monitoring platforms. The US FAA regulates commercial remote sensing licensing thresholds, while EPA spill response protocols embed satellite-derived flood extent maps into emergency operations. India's BIS geospatial data quality standards and DGFT liberalization of map access are restructuring who can sell location intelligence domestically. Stakeholders must monitor which regulatory jurisdictions will next mandate real-time spatial disclosure as a condition of market access.
Market Dynamics
Cloud-native architectures are collapsing the capital barrier that historically separated defense-scale buyers from municipal utilities and agricultural cooperatives, redistributing purchasing power across entirely new customer tiers.
Growth Catalysts
- EU Green Deal disclosure mandates:Environmental verification requirements are forcing corporations to procure satellite-derived land-use monitoring as a compliance input.
- India's national geospatial policy liberalization:DGFT map access reforms are unlocking private-sector participation in surveying and location intelligence services.
- Machine learning feature extraction:Automated object detection from multispectral imagery is compressing analyst labor costs for infrastructure inspection workflows.
Market Restraints
- Launch capacity concentration:Reliance on a narrow set of orbital deployment providers creates constellation deployment bottlenecks and schedule risk.
- US FAA remote sensing licensing thresholds:Regulatory friction for commercial satellite operators delays market entry for new imaging constellations.
- LiDAR sensor import dependencies:Precision hardware supply chains remain concentrated in East Asian manufacturing clusters, exposing cost volatility.
Strategic Opportunities
- Variable-rate agriculture in Brazil:Farm-level input optimization using GPS-guided application systems remains underpenetrated outside North American and European core markets.
- CSRD-aligned carbon stock verification:EU disclosure rules are creating procurement pull for remote sensing platforms that quantify above-ground biomass.
- Edge computing convergence with satellite terminals:Onboard processing capabilities are enabling real-time analytics for disaster response without ground station latency.
Industry Challenges
- Geospatial data scientist scarcity:The intersection of remote sensing expertise and machine learning engineering remains thinly staffed across vendor organizations.
- Legacy GIS integration complexity:Enterprise migration from on-premises ArcGIS deployments to cloud-native architectures encounters workflow disruption and retraining costs.
- BIS quality standard certification timelines:India's data quality compliance requirements extend sales cycles for foreign platform providers entering the domestic market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geospatial Analytics Market |
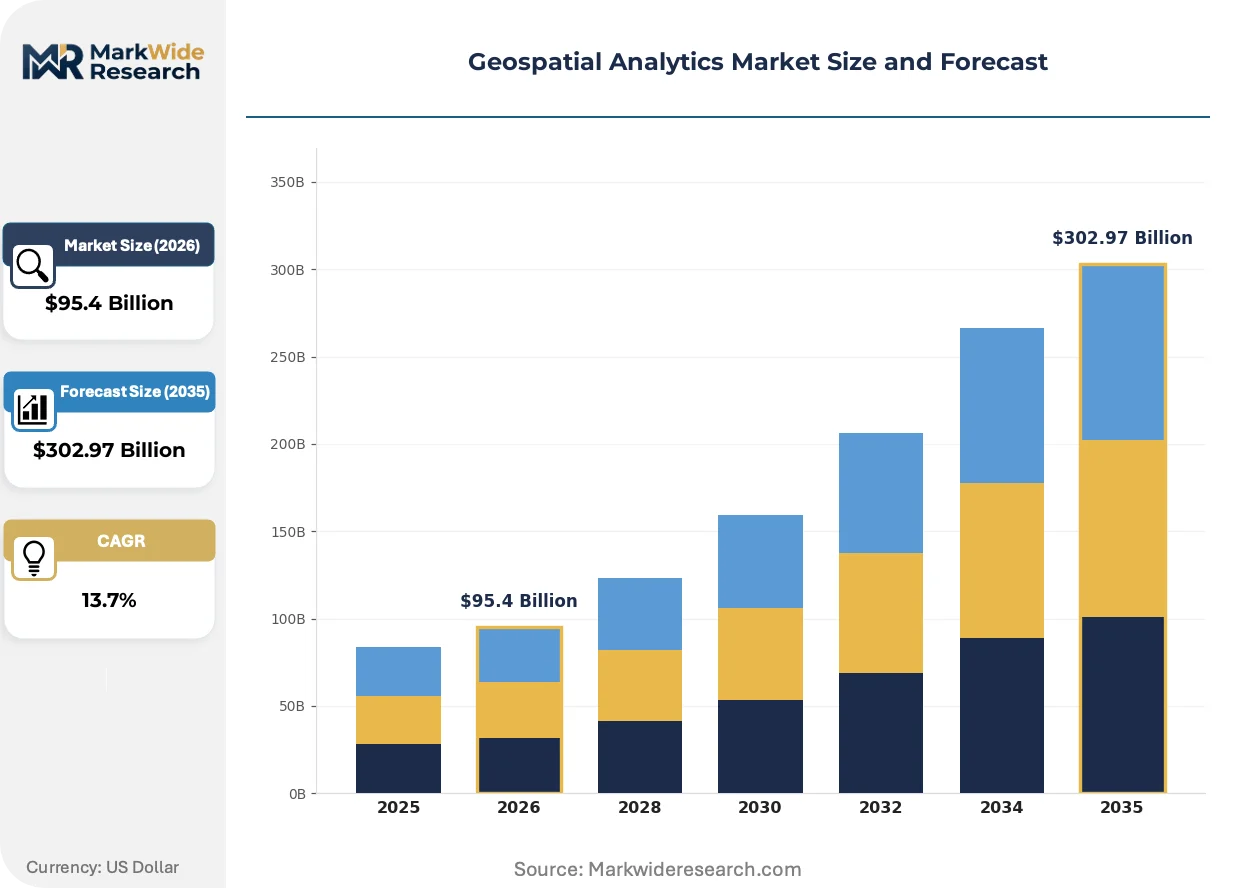
| Market Size in 2026 | $95.4 Billion |
| Market Size in 2035 | $302.97 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GIS, Remote Sensing, GPS, Artificial Intelligence Application: Urban Planning, Environmental Monitoring, Transportation Management, Disaster Response End User: Government, Agriculture, Utilities, Insurance Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Esri, Trimble Inc., Hexagon AB, Google (Alphabet Inc.), Bentley Systems, Inc., Fugro NV, Alteryx, Inc., Oracle Corporation, Maxar Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geospatial Analytics Market Strategic Shifts & Innovations
Synthetic aperture radar is penetrating cloud cover that previously blinded optical systems, while regulatory disclosure mandates are hardcoding geospatial verification into corporate reporting workflows.
Foundation models trained on planetary-scale imagery archives are collapsing the cost structure of feature extraction workflows that previously required specialist analyst teams. Agricultural cooperatives and mid-size insurers are adopting these pipelines without building in-house Earth observation expertise. The result compresses pricing power for traditional analytics boutiques that sold labor-intensive interpretation services.
The EU CSRD and Green Deal disclosure frameworks are mandating spatially explicit verification of land-use change and carbon stock estimates. Corporations subject to these rules must now procure remote sensing platforms as compliance infrastructure. Forestry and agricultural commodity traders are responding fastest, embedding satellite monitoring into supplier audit protocols.
Municipal procurement offices are unbundling satellite imagery subscriptions from bundled analytics services, purchasing raw data through cloud marketplaces and contracting processing separately. This disintermediates traditional systems integrators that historically captured margin through end-to-end solution packaging. The pattern is most visible in German and Dutch municipal governments, where public tender specifications now separate data acquisition from algorithmic analysis.
Geospatial Analytics Market Segmentation
Geospatial analytics vendors structure their offerings across four distinct dimensions that shape procurement patterns and margin capture. Technology choices determine processing architecture. Application focus dictates regulatory alignment. End-user verticals set pricing tolerance. Deployment models redistribute infrastructure ownership between vendor and client.
Technology:
Cost tier separates legacy positioning systems from AI-augmented processing pipelines that command premium licensing.
- Artificial Intelligence:Machine learning pipelines automate feature extraction from multispectral imagery, collapsing analyst labor requirements for infrastructure inspection. Demand concentrates in agricultural cooperatives and mid-size insurers seeking automated crop health assessment without in-house Earth observation expertise.
- Remote Sensing:Satellite and aerial data capture systems operating across optical, radar, and thermal bands enable land-use monitoring at sub-meter resolution. European corporations subject to CSRD disclosure mandates are procuring these platforms as mandatory compliance infrastructure for carbon stock verification.
- GIS:Spatial data management and visualization systems anchor enterprise workflows across municipal agencies.
- GPS:Satellite-based positioning infrastructure enables centimeter-level accuracy for surveying and navigation applications.
Artificial Intelligence commands the established base. The steepest expansion runs through Remote Sensing.
Application:
Geography determines which use cases attract regulatory investment versus purely commercial procurement.
- Environmental Monitoring:Land-use change detection, carbon stock quantification, and ecosystem health assessment through satellite-derived metrics. EU Green Deal mandates are hardcoding this application into corporate reporting workflows across forestry and agricultural commodity trading.
- Disaster Response:Real-time flood extent mapping, wildfire perimeter tracking, and damage assessment using synthetic aperture radar that penetrates cloud cover. India's national geospatial policy liberalization is accelerating municipal procurement for monsoon and cyclone preparedness.
- Urban Planning:Zoning analysis, infrastructure siting, and population density mapping for municipal development authorities.
- Transportation Management:Route optimization, fleet tracking, and autonomous vehicle mapping for logistics operators.
Environmental Monitoring captures the largest compliance-driven budgets. Disaster Response is climbing the fastest as climate adaptation funding redirects toward real-time spatial intelligence.
End User:
Customer type stratifies between regulatory-mandated procurement and discretionary technology investment.
- Government:Defense agencies, municipal planning departments, and environmental regulators consuming satellite imagery and analytics for sovereignty and compliance purposes. Procurement specifications in Germany and the Netherlands now separate raw data acquisition from algorithmic analysis, disintermediating traditional systems integrators.
- Agriculture:Farm-level input optimization using GPS-guided variable-rate application systems. Brazil's underpenetrated market outside North American and European core regions presents expansion opportunity for precision agriculture hardware-software integration.
- Utilities:Grid infrastructure monitoring, vegetation management, and asset tracking for electricity and water distribution networks.
- Insurance:Catastrophe modeling, claims verification, and risk assessment using remote sensing-derived property and crop damage estimates.
Government maintains the deepest procurement relationships. Agriculture is gaining share fastest as variable-rate optimization spreads beyond established markets.
Deployment:
Margin structure shifts with infrastructure ownership and processing location decisions.
- Cloud-Based:Pay-per-use platforms eliminating on-premises infrastructure barriers for mid-size utilities and insurance carriers. Cloud-native architectures are redistributing purchasing power toward municipal utilities and agricultural cooperatives previously excluded by capital requirements.
- Hybrid:Split processing across edge devices and centralized cloud resources, enabling sensitive data retention on-premises while leveraging scalable analytics.
- On-Premises:Self-hosted installations maintaining data sovereignty for defense and intelligence applications with strict security protocols.
- Mobile:Field-deployable applications on tablets and smartphones for surveyors and emergency responders requiring offline functionality.
Cloud-Based deployment anchors new customer acquisition. Hybrid configurations are expanding most quickly as edge computing convergence with satellite terminals enables real-time analytics without ground station latency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal disclosure mandates and India's geospatial policy liberalization are redistributing procurement authority toward municipal governments and agricultural cooperatives previously excluded by capital barriers.
United States
FAA commercial remote sensing licensing thresholds and EPA spill response protocols embed satellite-derived analytics into federal emergency operations. Municipal utilities in California and Texas are unbundling imagery subscriptions from bundled services, purchasing raw data through cloud marketplaces. The Pacific Northwest corridor hosts precision agriculture hardware-software integration clusters serving variable-rate input optimization.
Germany
CSRD-aligned carbon stock verification requirements are forcing forestry and agricultural commodity traders to procure remote sensing platforms as compliance infrastructure. BSI quality standards and public tender specifications in Dutch and German municipal offices now separate data acquisition from algorithmic analysis. The Rhine-Ruhr metropolitan region concentrates autonomous mapping vehicle sensor fusion development.
India
DGFT map access reforms and BIS geospatial data quality standards are unlocking private-sector participation in surveying and location intelligence services. State disaster management authorities in Maharashtra and Gujarat are accelerating procurement for monsoon and cyclone preparedness using real-time flood extent mapping. The Bangalore-Hyderabad corridor anchors machine learning feature extraction pipelines for infrastructure inspection workflows.
Brazil
Farm-level GPS-guided variable-rate application systems remain underpenetrated outside North American and European core markets, creating expansion opportunity for precision agriculture integration. ANVISA regulatory frameworks for agricultural input monitoring are embedding spatial verification into supplier audit protocols. The São Paulo-Paraná agricultural belt concentrates demand for automated crop health assessment without in-house Earth observation expertise.
United Kingdom
Environment Agency flood risk mapping mandates and Ofwat infrastructure monitoring requirements are driving cloud-native platform adoption among water utilities. Municipal planning departments in Greater London and the Midlands are migrating from on-premises ArcGIS deployments to cloud architectures. The Cambridge-Oxford corridor hosts edge computing convergence development for satellite terminal real-time analytics.
Geospatial Analytics Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered structure where platform dominance and hardware-software integration define distinct competitive vectors. The vendor base clusters around three strategic archetypes: cloud-native analytics platforms, precision hardware-software integrators, and sensor fusion specialists. M&A activity concentrates on machine learning pipeline acquisitions and constellation deployment partnerships. Geographic expansion into India's liberalized surveying market and Brazil's agricultural belt represents the dominant competitive move.
Within the platform-dominant tier, Esri anchors enterprise subscription relationships across municipal agencies through spatial data management systems. Trimble Inc. exemplifies the hardware-software integration archetype, extending precision agriculture reach into farm-level decision systems. Hexagon AB occupies the sensor fusion specialist position, sustaining premium positioning in autonomous mapping vehicle markets for surveying applications.
| Leading Market Players |
|---|
| Esri |
| Trimble Inc. |
| Hexagon AB |
| Google (Alphabet Inc.) |
| Bentley Systems, Inc. |
| Fugro NV |
| Alteryx, Inc. |
| Oracle Corporation |
| Maxar Technologies |
| Others |
Cost & Logistics Intelligence
East Asian LiDAR sensor manufacturing clusters anchor cost volatility for precision hardware, compressing margin capture for downstream analytics providers dependent on imported components. Cloud-native deployment architectures redistribute infrastructure ownership toward pay-per-use models, shifting pricing power from capital-heavy systems integrators to software-centric platforms.
Pricing Analysis
Certification level under BIS geospatial data quality standards creates the primary spread between premium platform licenses and entry-level subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments by processing resolution, API call volume, and analyst support tiers. Cost compression in mid-market municipal utilities intensifies because procurement offices unbundle raw imagery from analytics services. Agricultural cooperatives exhibit highest price sensitivity, while defense agencies maintain lowest sensitivity due to sovereignty requirements.
Supply Chain Analysis
Upstream feedstock for optical and synthetic aperture radar payloads concentrates in United States, Germany, and Israel for sensor fabrication. Precision optics, gallium arsenide substrates, and radiation-hardened electronics feed from specialized semiconductor foundries. Single-source vulnerability runs through narrow orbital launch provider networks concentrated in United States, China, and Russia. Distribution runs through cloud marketplaces and direct enterprise sales for platform vendors, with systems integrators retaining project-based channel control for complex municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning feature extraction pipelines are collapsing analyst labor costs, creating a high-growth disruption as agricultural cooperatives and mid-size insurers adopt automated workflows without building in-house Earth observation expertise.
For Market Incumbents: Entrench platform dominance by deepening API ecosystem lock-in across municipal ArcGIS deployments threatened by cloud-native disintermediation. Acquire machine learning pipeline specialists to defend against boutique analytics providers collapsing feature extraction pricing. Prioritize certification investment under BIS and EU Green Deal disclosure frameworks to maintain compliance infrastructure positioning.
For New Entrants and Emerging Players: Build out variable-rate agriculture capabilities in Brazil's underpenetrated farm-level input optimization market beyond North American and European core regions. Target India's liberalized surveying and location intelligence services unlocked by DGFT map access reforms. Pursue carbon stock verification platforms as the most penetrable segment, leveraging CSRD-aligned procurement pull from forestry and agricultural commodity traders.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native analytics sub-segments as satellite imagery subscriptions eliminate constellation ownership requirements. Long-term viability favors capital-light platform vendors over hardware-dependent integrators across the projection horizon. Target acquisition profiles center on machine learning pipeline assets with proven agricultural or insurance vertical penetration. Monitor FAA commercial remote sensing licensing threshold relaxation as the signal indicating constellation deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Pipeline Acquisition | Automated feature extraction from multispectral imagery collapses analyst labor costs for infrastructure inspection workflows. |
| Cloud Marketplace Distribution Partnership | Raw imagery unbundling through AWS and Azure marketplaces disintermediates traditional systems integrators in German municipal procurement. |
| CSRD Compliance Platform Development | EU Green Deal disclosure mandates hardcode satellite-derived land-use verification into corporate reporting infrastructure. |
| Edge Computing Satellite Terminal Integration | Onboard processing capabilities enable real-time flood extent analytics for India's monsoon preparedness without ground station latency. |
| Precision Agriculture Hardware-Software Bundling | GPS-guided variable-rate application systems extend platform reach into Brazil's underpenetrated farm-level decision systems. |
Research Approach
Initial hypotheses were tested against primary input from satellite imagery procurement officers, municipal planning directors, agricultural cooperative technology leads, and insurance catastrophe modelers, and refined through secondary validation. Data synthesis combined structured interviews with platform vendors and end-users alongside regulatory filing review, hyperscaler capex disclosures, and customs trade records for precision hardware imports. Bottom-up segmentation modeling and top-down macroeconomic anchoring provided cross-verification across analytical approaches.
Demand-supply-balance framing anchored the quantitative framework, with adoption curves modeled across technology, application, end-user, and deployment dimensions throughout the forecast period. Segment-level CAGRs derived from penetration rate differentials, pricing elasticity estimates, and regulatory mandate implementation timelines. Constellation deployment schedules, cloud infrastructure expansion trajectories, and machine learning model accuracy improvements served as industry-specific forecast inputs.
Stress conditions across FAA licensing timeline delays, LiDAR sensor import tariff escalations, and EU CSRD enforcement variance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud migration velocity and agricultural automation adoption curves. Cross-checking against hyperscaler geospatial service revenue disclosures and national space agency budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global System Monitoring Market
Analytics
Cloud Analytics Market
Analytics
Global Enterprise Data Visualization Platform Market
Analytics
APAC Retail Analytics Market
Analytics
Procurement Analytics Market
Analytics
Canada Contact Center Analytics Market
Analytics
Global in-Store Analytics Market
Analytics
Europe Data Monetization Market
Analytics
France Contact Center Analytics Market
Analytics
Attribution Software Market
Analytics
Europe Emotion Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Global Sales Performance Management Market
Analytics
Global Big Data Market
Analytics
Practice Analytics Market
Analytics
Customer Data Platform Market