
 Imagery Analytics Market | 2026-2036
Imagery Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Imagery Analytics Market Outlook
The imagery analytics sector is splitting between premium AI-powered analysis platforms and commodity satellite imagery feeds. Maxar Technologies leverages its high-resolution satellite constellation to sustain defense and intelligence contracts. Planet Labs PBC anchors its position through daily global coverage and open data APIs for enterprise developers. Google dominates cloud-based geospatial analytics by integrating computer vision tools with its mapping infrastructure.
Imagery analytics encompasses the extraction of actionable intelligence from visual data captured via satellite, aerial, and terrestrial sensors, processed through spectral analysis and machine learning algorithms to measure land use, asset conditions, or environmental change. The technology serves commercial, governmental, and scientific users requiring spatial decision support at scale. Satellite imagery leads in revenue contribution due to persistent orbital coverage and defense procurement cycles. 3D imaging captures the fastest expansion as urban planners and infrastructure engineers adopt LiDAR-derived elevation models for digital twin construction. Geospatial data remains mature with established GIS vendors controlling enterprise workflow integration.
The EU AI Act classifies certain geospatial analytics as high-risk AI systems, mandating conformity assessments for automated image recognition deployed in critical infrastructure monitoring. The US Federal Aviation Administration governs commercial remote sensing licensing under the Land Remote Sensing Policy Act, shaping market access for domestic satellite operators. ISO 19115 metadata standards enforce interoperability requirements across national spatial data infrastructures. Stakeholders must monitor evolving cross-border data localization rules that determine where raw satellite imagery can be stored and processed.
Market Dynamics
Defense procurement cycles and precision agriculture automation are compressing satellite imagery delivery timelines from days to hours, forcing analytics providers to restructure cloud processing architectures around near-real-time inference pipelines.
Growth Catalysts
- EU AI Act compliance mandates:Automated infrastructure monitoring systems now require conformity assessments, creating certified vendor demand for defense contractors and utility operators seeking regulatory clarity.
- LiDAR-derived elevation modeling:Urban planners in Singapore and Rotterdam are deploying 3D point cloud analytics for flood risk simulation and digital twin construction at municipal scale.
- Spectral analysis for crop stress detection:Brazil's soybean belt and Australia's wheat regions are driving hyperspectral satellite subscriptions for irrigation optimization and yield prediction.
Market Restraints
- Launch capacity concentration:Orbital slot access depends on a narrow supplier base in California, French Guiana, and Kazakhstan, creating payload backlog risks for constellation expansion.
- GDPR cross-border processing restrictions:Raw imagery storage location requirements fragment cloud infrastructure economics and complicate multi-tenant platform architectures.
- Optical sensor weather dependency:Persistent cloud cover over tropical agriculture zones forces redundant SAR satellite capacity, inflating customer acquisition costs for equatorial markets.
Strategic Opportunities
- Indonesia maritime surveillance gap:Archipelago nation lacks sovereign satellite capacity for exclusive economic zone monitoring, creating procurement openings for foreign analytics consortia.
- Carbon credit verification protocols:REDD+ forest monitoring standards are mandating satellite-based above-ground biomass measurement, pulling new buyers into geospatial subscriptions.
- Edge inference on orbital platforms:Onboard GPU clusters are enabling raw data triage before downlink, reducing bandwidth costs for time-critical defense and disaster response applications.
Industry Challenges
- Geospatial data scientist scarcity:Remote sensing PhD pipelines at TU Delft, ITC Enschede, and Wuhan University cannot match commercial demand for spectral unmixing and change detection specialists.
- ISO 19115 metadata harmonization:National spatial data infrastructures in Germany, Japan, and Canada maintain incompatible catalog schemas, forcing expensive ingestion pipeline customization.
- Legacy GIS workflow integration:Enterprise ArcGIS installations resist API-first analytics platforms, extending sales cycles for cloud-native vendors targeting government accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Imagery Analytics Market |
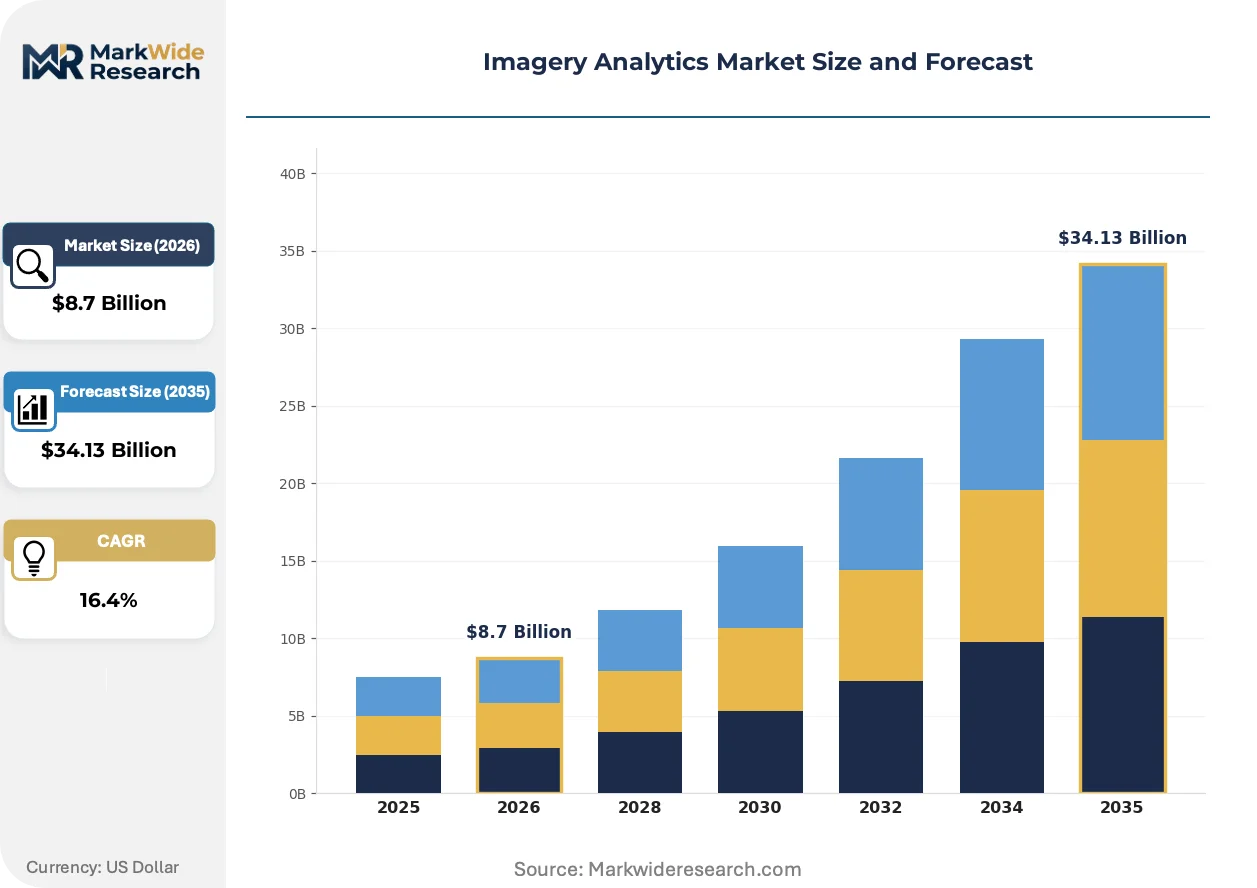
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Imaging, 3D Imaging, Geospatial Data, Satellite Imagery Application: Agriculture, Defense, Environmental Monitoring, Urban Planning End User: Governments, Enterprises, NGOs, Academic Institutions Technology: AI-Powered Analysis, Machine Learning, Computer Vision, Image Recognition |
| Companies Covered | Google, Esri, Hexagon AB, Maxar Technologies, TomTom, Trimble, Planet Labs PBC, Airbus Defence and Space, Spire Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Imagery Analytics Market Strategic Shifts
Foundation model architectures trained on billion-scale image corpora are compressing model development timelines and collapsing the cost structure for domain-specific classification tasks.
Foundation models for remote sensing are consolidating computer vision development around pretrained backbones from NASA's Prithvi and IBM's geospatial foundation model. Agricultural technology vendors and insurance underwriters are fine-tuning these weights for crop classification and damage assessment rather than training from scratch. This consolidation is compressing the competitive moat of proprietary training datasets and shifting differentiation toward inference latency and API reliability.
The EU AI Act's high-risk system classification for critical infrastructure monitoring is mandating algorithmic audit trails and human-in-the-loop review protocols. Satellite analytics providers serving European utility and transport operators must now document training data provenance and model performance across demographic and geographic subgroups. German and French defense integrators are responding by segmenting AI pipelines between classification stages that require certification and those that permit automated processing.
Subscription fatigue among mid-sized agriculture cooperatives is fragmenting demand toward usage-based pricing and per-hectare analytic credits. Brazilian and Australian grain buyers are unbundling annual platform licenses in favor of pay-per-insight models triggered by growing season events. This behavioral shift pressures vendors to instrument consumption telemetry and restructure sales compensation around activation metrics rather than contract value.
Imagery Analytics Market Segmentation
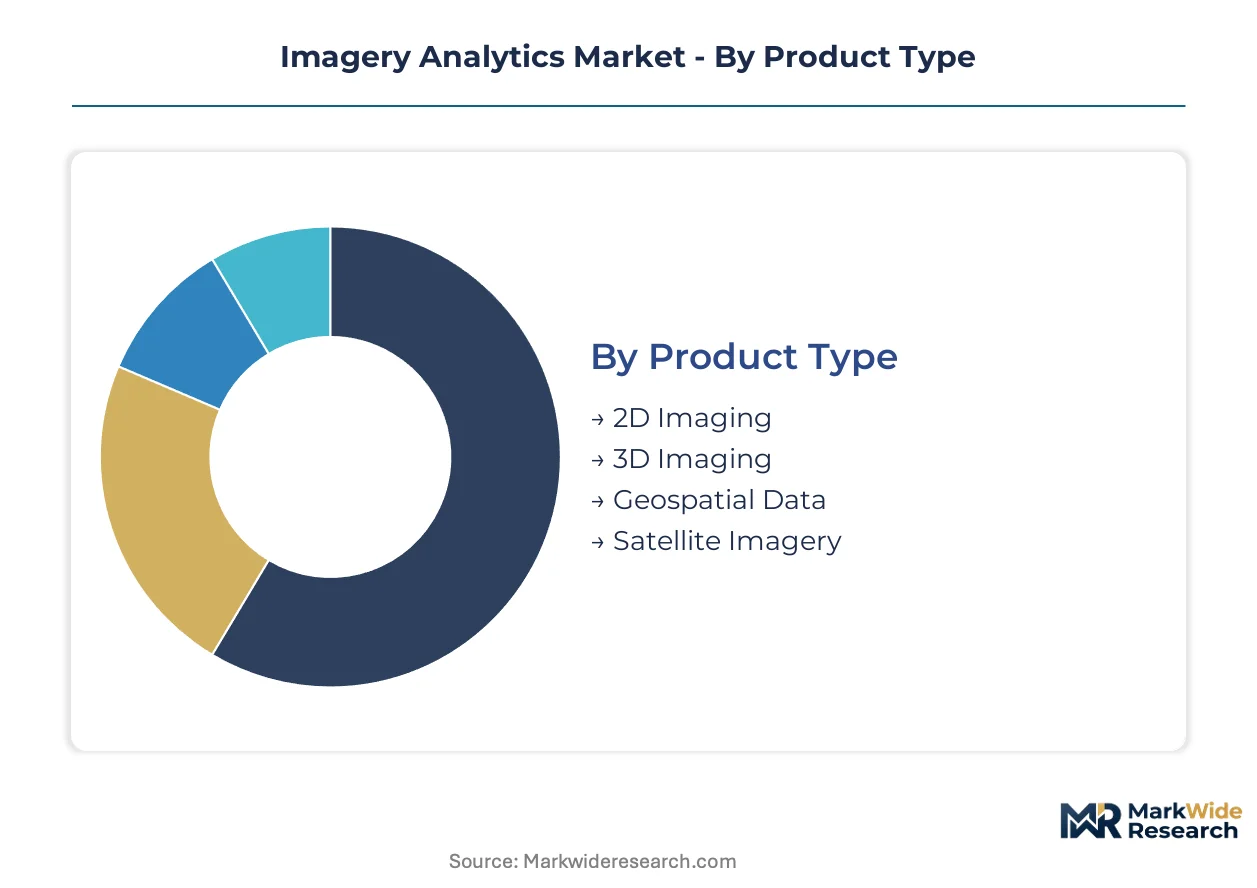
Imagery analytics procurement patterns diverge sharply across technical specifications, mission requirements, and compliance obligations. Buyers prioritize different performance thresholds, integration architectures, and data sovereignty guarantees depending on their operational context and regulatory exposure.
Product Type:
Defense contractors and precision agriculture buyers diverge most sharply on resolution requirements and delivery latency tolerances.
- Satellite Imagery:Persistent orbital coverage from electro-optical and synthetic aperture radar sensors enables defense intelligence cycles and agricultural monitoring at continental scale. US federal agencies and Brazilian soybean cooperatives drive subscription demand for sub-meter resolution tasked collections.
- 3D Imaging:LiDAR-derived point clouds and photogrammetric elevation models support digital twin construction for flood simulation and infrastructure planning. Singapore and Rotterdam municipal authorities are deploying these datasets for climate resilience modeling at district scale.
- 2D Imaging:Aerial and terrestrial photography serves tactical mapping and asset inspection with lower processing overhead. Drone operators in Australia's mining belt favor this format for rapid site surveys.
- Geospatial Data:Vector layers and attributed feature sets integrate with enterprise GIS workflows. German and Japanese national spatial data infrastructures enforce ISO 19115 metadata compliance for catalog interoperability.
Satellite imagery leads volumes today; 3D imaging is gaining share fastest.
Application:
Mission-criticality determines whether buyers accept algorithmic audit requirements under the EU AI Act or prioritize speed-to-insight.
- Defense:Intelligence, surveillance, and reconnaissance workflows demand near-real-time tipping and cueing between satellite constellations. NATO member states and Five Eyes partners procure AI-powered change detection under strict security clearance protocols.
- Agriculture:Hyperspectral crop stress indices and yield prediction models optimize irrigation and input scheduling. Brazil's Mato Grosso region and Australia's wheat belt are converting to per-hectare analytic credit pricing.
- Environmental Monitoring:REDD+ forest carbon verification and illegal logging detection rely on above-ground biomass estimation. Indonesia's maritime surveillance gaps are pulling foreign analytics consortia into exclusive economic zone monitoring contracts.
- Urban Planning:Zoning enforcement, informal settlement mapping, and transportation corridor design consume high-resolution stereo pairs. Municipal governments in the Netherlands and UAE specify digital twin compatibility for procurement.
Defense commands the largest contract values; agriculture is expanding most quickly.
End User:
Budget cycles and data sovereignty requirements fragment procurement authority across institutional categories.
- Governments:National mapping agencies and defense ministries operate classified processing environments with domestic storage mandates. GDPR cross-border restrictions and US Land Remote Sensing Policy Act licensing shape vendor selection.
- Enterprises:Insurance underwriters and agricultural technology vendors fine-tune foundation models for damage assessment and crop classification. These buyers favor API-first platforms with consumption-based pricing over perpetual licenses.
- NGOs:Humanitarian organizations and conservation groups prioritize open data access and transparent methodologies. Their procurement emphasizes cost recovery rates and public-facing documentation.
- Academic Institutions:Remote sensing research programs at TU Delft, ITC Enschede, and Wuhan University train spectral unmixing specialists while contributing training data to public benchmarks.
Governments dominate absolute spending; enterprises are climbing the fastest.
Technology:
Foundation model architectures are collapsing the cost structure for domain-specific classification while redrawing competitive differentiation.
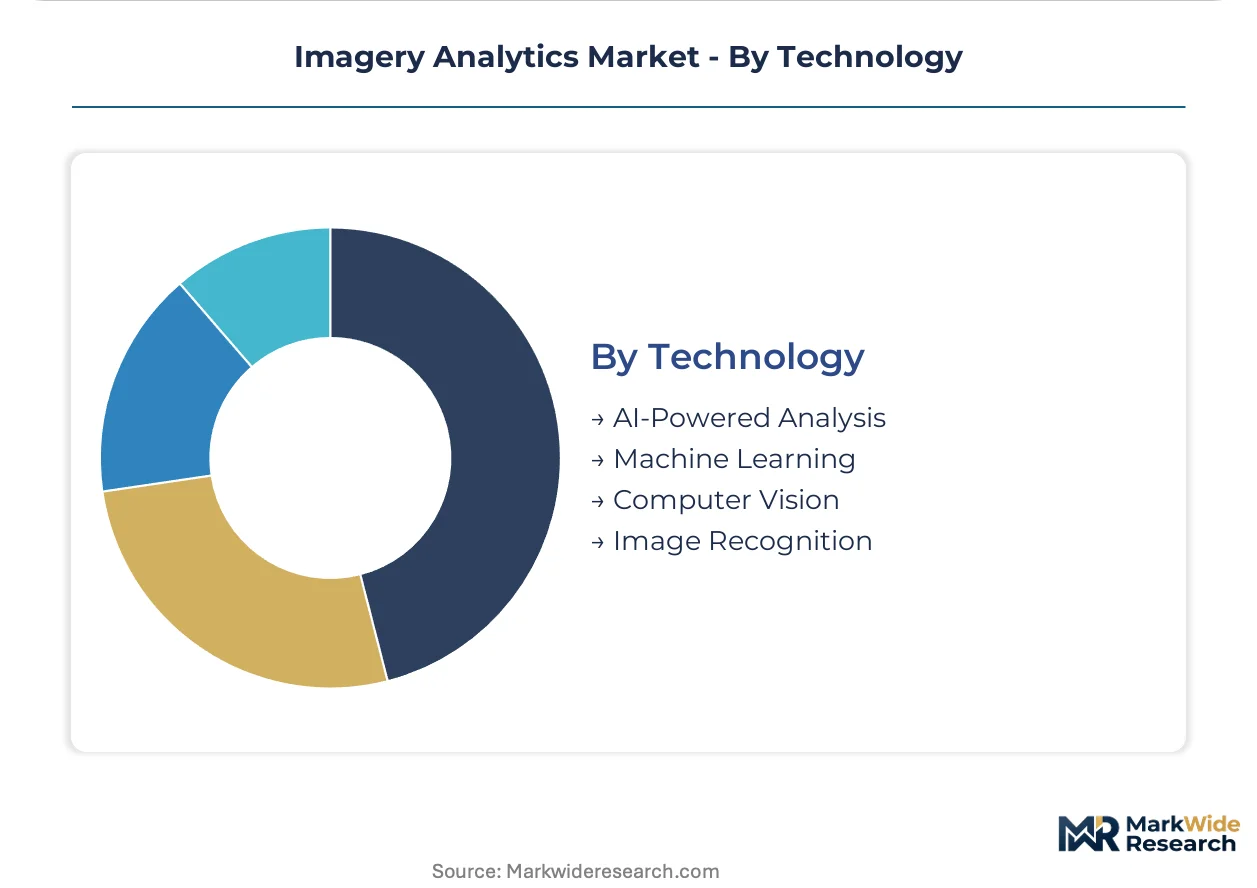
- AI-Powered Analysis:Pretrained backbones from NASA's Prithvi and IBM's geospatial foundation model compress development timelines for agricultural and insurance applications. Vendors now compete on inference latency rather than proprietary training datasets.
- Computer Vision:Object detection and semantic segmentation pipelines process satellite and aerial frames for asset counting and land cover mapping. Edge inference on orbital GPU clusters is enabling raw data triage before downlink.
- Machine Learning:Traditional supervised learning with Random Forest and Support Vector Machine classifiers persists in legacy GIS workflows. Enterprise ArcGIS installations resist cloud-native API integration.
- Image Recognition:Pattern matching for specific infrastructure types and vessel identification serves maritime surveillance and critical infrastructure monitoring. EU AI Act high-risk system classification mandates conformity assessments for European utility deployments.
AI-powered analysis leads deployment scale; computer vision shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Remote sensing PhD programs at TU Delft, ITC Enschede, and Wuhan University supply spectral unmixing specialists to imagery analytics vendors worldwide. These talent pipelines concentrate in the Netherlands, China, and select US research clusters. Procurement authority fragments across defense ministries, agricultural cooperatives, and municipal planning departments with divergent data sovereignty requirements.
United States
Federal agencies and precision agriculture enterprises drive procurement of AI-powered satellite analytics with near-real-time delivery requirements. The FAA governs commercial remote sensing licensing under the Land Remote Sensing Policy Act, shaping market access for domestic satellite operators. The Greater Boston corridor hosts defense contractors integrating change detection algorithms into classified intelligence workflows.
Germany
Defense integrators and utility operators demand algorithmic audit trails for EU AI Act high-risk system compliance in critical infrastructure monitoring. The national spatial data infrastructure enforces ISO 19115 metadata standards for catalog interoperability across federal and state mapping agencies. Munich and Stuttgart clusters specialize in synthetic aperture radar analytics for all-weather agricultural monitoring.
China
Municipal governments and infrastructure conglomerates deploy LiDAR-derived elevation models for digital twin construction in flood-prone river basins. The Ministry of Ecology and Environment mandates satellite-based environmental monitoring for carbon accounting and pollution enforcement. The Yangtze River Delta concentrates computer vision startups fine-tuning foundation models for urban planning applications.
Brazil
Soybean cooperatives in Mato Grosso and grain traders across the Cerrado biome are converting to per-hectare analytic credit pricing for hyperspectral crop stress detection. ANVISA regulates agricultural drone operations that feed imagery into subscription analytics platforms. São Paulo hosts insurance underwriters integrating satellite yield prediction into parametric crop coverage products.
Singapore
Municipal authorities deploy 3D point cloud analytics for district-scale flood risk simulation and climate resilience modeling. The national mapping agency enforces strict data localization for geospatial processing under cross-border transfer restrictions. The one-north research corridor attracts vendors specializing in edge inference for maritime surveillance applications.
Imagery Analytics Market Competitive Environment
Top-tier vendors anchor the premium analytics tier, while constellation operators and cloud platforms occupy differentiated positions below. The market structure concentrates around three strategic archetypes: satellite constellation owners with proprietary sensor networks, cloud hyperscalers integrating computer vision APIs, and specialized geospatial software vendors with entrenched GIS workflows. Competitive moves center on foundation model licensing partnerships and consumption-based pricing restructuring to capture mid-sized agricultural cooperative demand.
Within the satellite constellation tier, Maxar Technologies and Planet Labs PBC exemplify divergent coverage strategies—tasked high-resolution collections versus daily global monitoring. Google occupies a distinct position bridging cloud infrastructure and consumer mapping integration. Among established geospatial software vendors, Esri anchors enterprise GIS workflow dominance despite API-first platform pressure.
| Leading Market Players |
|---|
| Esri |
| Hexagon AB |
| Maxar Technologies |
| TomTom |
| Trimble |
| Planet Labs PBC |
| Airbus Defence and Space |
| Spire Global |
| Others |
Value Chain & Pricing Dynamics
Captive integration into orbital sensor manufacturing anchors both supply security and pricing power for constellation operators. Defense contractors and agricultural technology vendors that control upstream payload production command premium positioning, while analytics platforms dependent on third-party imagery feeds absorb margin compression from launch backlog risks and cross-border data localization mandates.
Pricing Analysis
Bundled satellite tasking with AI-powered analytics commands subscription premiums, while unbundled imagery feeds face commoditization pressure. Three-tier pricing structure across premium, standard, and economy levels separates defense-grade near-real-time delivery from agricultural monitoring with 24-hour latency. Price differentiation rests on resolution grade and EU AI Act certification tier. Cost compression in the economy tier is intensifying because Brazilian cooperatives are converting to per-hectare analytic credits. Mid-sized agriculture buyers exhibit highest price sensitivity; NATO defense integrators show lowest.
Supply Chain Analysis
Freight costs for satellite components are negligible compared to launch logistics, where payload integration in California, French Guiana, and Kazakhstan creates geographic chokepoints. Supply concentrates in the United States for electro-optical sensors, France for synthetic aperture radar payloads, and China for commercial launch services. Raw material dependencies include indium phosphide semiconductors, carbon fiber composites, and precision optics. Single-source vulnerability runs through SpaceX and Arianespace for orbital insertion. Distribution runs through direct defense procurement channels and API-first cloud platforms for enterprise developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between GDPR-restricted European processing environments and US cloud infrastructure creates cost differentials for analytics vendors. Regulatory fragmentation in data localization mandates rewards multi-region architecture investments.
For Market Incumbents: Deploy foundation model licensing as the primary lever. Maxar Technologies and Planet Labs PBC should consolidate pretrained backbone partnerships to compress competitor development timelines. Backward integration into edge inference hardware for orbital GPU clusters counters emerging satellite-as-a-service entrants. Certification investment for EU AI Act high-risk system conformity protects defense contract renewals against audit-capable challengers.
For New Entrants and Emerging Players: Indonesian maritime surveillance authorities represent an underserved buyer archetype lacking sovereign satellite capacity. Foreign analytics consortia can capture exclusive economic zone monitoring contracts through local data residency partnerships. Carbon credit verification protocols for REDD+ forest monitoring pull new buyers into geospatial subscriptions with limited incumbent penetration. Go-to-market through parametric insurance underwriters in São Paulo and Sydney bypasses direct competition with established platform vendors.
For Investors and Strategic Acquirers: Roll-up economics work for specialized geospatial software vendors because ISO 19115 metadata harmonization costs prevent organic expansion across national spatial data infrastructures. Long-term viability hinges on API-first architecture migration away from legacy ArcGIS dependencies. Acquisition targets should demonstrate consumption-based pricing instrumentation and agricultural cooperative activation metrics. Foundation model fine-tuning capabilities signal defensible positioning as pretrained backbones commoditize core classification tasks.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundation Model Licensing Partnership | Compresses development timelines for agricultural insurance vendors using NASA Prithvi weights. |
| Edge Inference Hardware Deployment | Enables raw data triage on orbital GPU clusters before downlink to defense command centers. |
| EU AI Act Certification Investment | Secures conformity assessment for critical infrastructure monitoring contracts with German utilities. |
| Per-Hectare Pricing Restructuring | Captures Brazilian Mato Grosso cooperatives converting from annual platform licenses. |
| Multi-Region Cloud Architecture | Resolves GDPR cross-border processing restrictions for European government accounts. |
Study Parameters
Multiple input streams — primary interviews with satellite constellation operators, defense procurement officers, and agricultural technology vendors; secondary validation through FAA licensing records, EU AI Act implementation guidance, and ISO 19115 metadata registries; plus hyperscaler capex disclosures and constellation launch manifests — were reconciled through bottom-up and top-down triangulation. Conversations with utility operators in Germany and municipal planners in Singapore provided demand-side calibration for compliance-driven procurement patterns.
Historical capacity deployment patterns were cross-referenced against panel input from remote sensing PhD programs at TU Delft, ITC Enschede, and Wuhan University. The analytical framework models product type, application, end user, and technology dimensions across the analysis window. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic assumptions. Forecast inputs included defense budget appropriation cycles, precision agriculture automation adoption curves, and foundation model development trajectories.
Inputs from classified defense procurement databases and commercial satellite operator revenue disclosures were available through the study window; gaps in emerging market agricultural cooperative spending patterns introduce uncertainty bands around Asia-Pacific and Latin America projections. Forecasts reflect documented assumptions regarding launch capacity expansion and regulatory enforcement timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global Mobile BI Market
Analytics
Investigative Analytics Market
Analytics
Global Customer Experience Analytics Market
Analytics
Israel ICT Market
Analytics
Europe Network and Location Analytics Market
Analytics
Service Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Global Sales Performance Management Market
Analytics
Capacity Management Analytics Market
Analytics
Geospatial Analytics Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Mobile Business Intelligence Market
Analytics
Global Systems of Insight Market
Analytics
Global People and HR Analytics Software Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
Complex Event Processing Market