
 Digital Freight Matching Market | 2026-2036
Digital Freight Matching Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Freight Matching Market Analytics
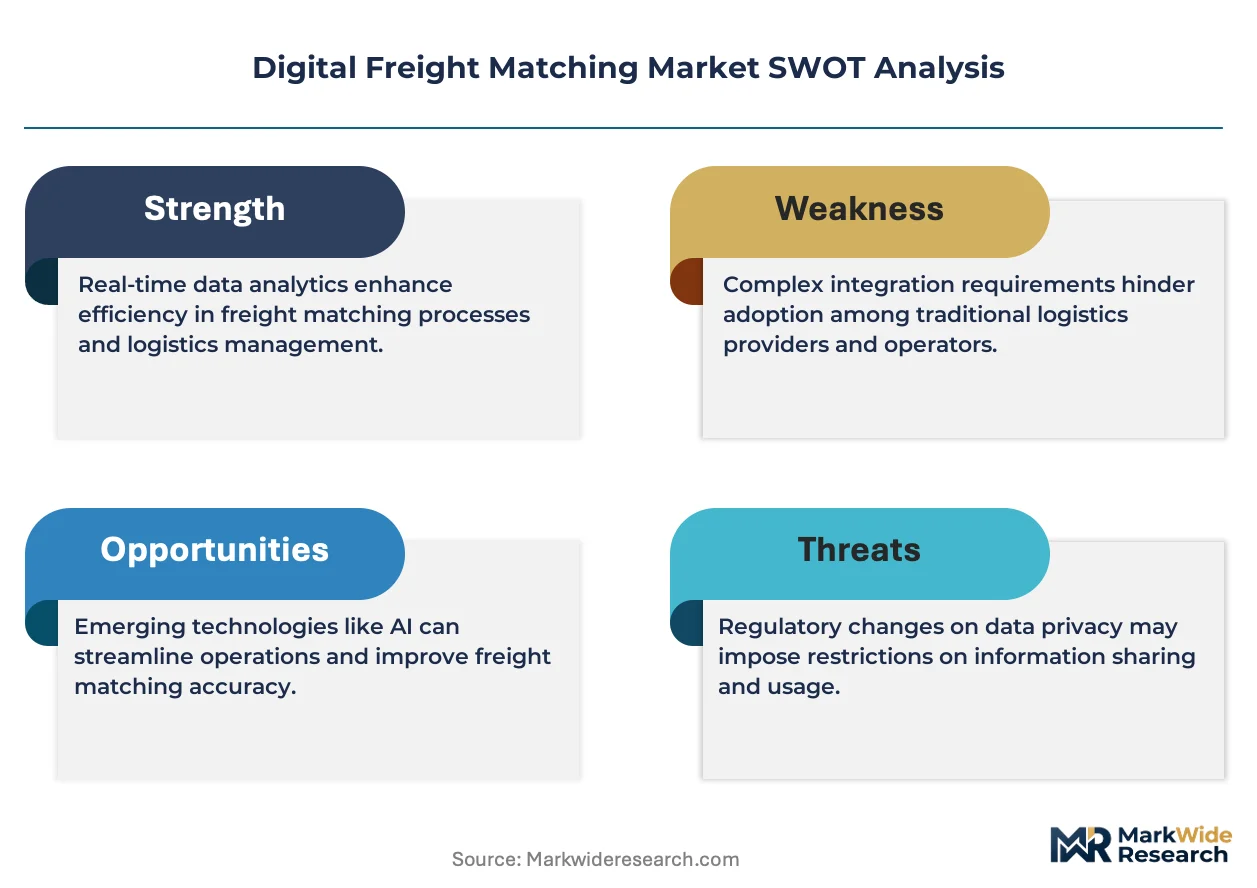
The premium segment is shifting toward real-time capacity optimization with predictive pricing, while commodity tiers remain stuck on static load-board visibility. DAT Freight & Analytics leverages its historical rate database to anchor contract negotiation tools for enterprise shippers. J.B. Hunt 360 sustains an integrated play by combining brokerage capacity with owned fleet data feeds. Uber Freight competes on instant booking density in spot markets, using its driver-app install base to control last-mile access.
Digital freight matching denotes algorithmic platforms that pair available truck capacity with shipper loads through automated pricing, carrier qualification, and execution workflows. Cloud-native architectures process GPS telemetry, dwell-time signals, and lane-density indices to collapse tender-to-accept intervals from hours to minutes. Load board services still occupy the largest revenue pool, though AI algorithm layers are capturing the fastest expansion as shippers pay premiums for predictive matching accuracy. SaaS deployment dominates new implementations, while hybrid configurations persist among asset-heavy operators guarding proprietary dispatch data.
The US DOT ELD mandate and FMCSA hours-of-service rules compress available driving windows, amplifying demand for platforms that minimize deadhead miles through real-time repositioning. The EU Green Deal and emerging CO2 reporting under CSRD push European shippers toward matched consolidation loads that cut empty kilometers. Stakeholders must monitor how carbon-accounting requirements rewrite rate structures and carrier scoring before compliance deadlines lock in platform selection.
Market Dynamics
Algorithmic load-carrier pairing is compressing tender-to-accept intervals from hours to minutes, forcing legacy brokerages to rebuild pricing engines around real-time GPS telemetry and dwell-time signals or lose volume to cloud-native platforms.
Growth Catalysts
- US ELD Mandate Enforcement:FMCSA hours-of-service rules compress carrier availability windows, amplifying demand for platforms that minimize deadhead miles through automated repositioning algorithms.
- Retail E-commerce Velocity:Same-day and next-day delivery promises from major retailers require dynamic capacity sourcing that static load boards cannot fulfill.
- Cloud-Native Architecture:API-first platforms process lane-density indices and predictive pricing models at scale, collapsing integration costs for mid-market shippers.
Market Restraints
- Data Silo Fragmentation:Asset-heavy operators guard proprietary dispatch data in hybrid on-premise configurations, limiting network effects for multi-tenant SaaS platforms.
- Carrier Churn Economics:Small fleet owner-operators exhibit high platform-hopping behavior, eroding matching algorithm training data quality and prediction accuracy.
- Spot Rate Volatility:Diesel price swings and seasonal demand surges destabilize algorithmic pricing models, forcing manual override protocols that slow execution.
Strategic Opportunities
- CSRD Carbon Reporting:European shippers face emerging CO2 disclosure requirements under the EU Green Deal, creating demand for matched consolidation loads that document empty-kilometer reductions.
- Southeast US Corridor Density:Port congestion at Savannah and Charleston combined with inland distribution hub expansion generates acute load-capacity imbalances suited for predictive matching.
- Intermodal Rail Integration:Convergence of truck brokerage platforms with Class I railroad APIs enables door-to-door pricing transparency previously fragmented across modes.
Industry Challenges
- API Standardization Gaps:Inconsistent data formats between telematics providers, TMS vendors, and carrier dispatch systems force expensive custom integration projects.
- Algorithmic Bias in Carrier Scoring:Historical performance weights in matching engines disadvantage newer carriers, requiring manual intervention to ensure capacity access equity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Freight Matching Market |
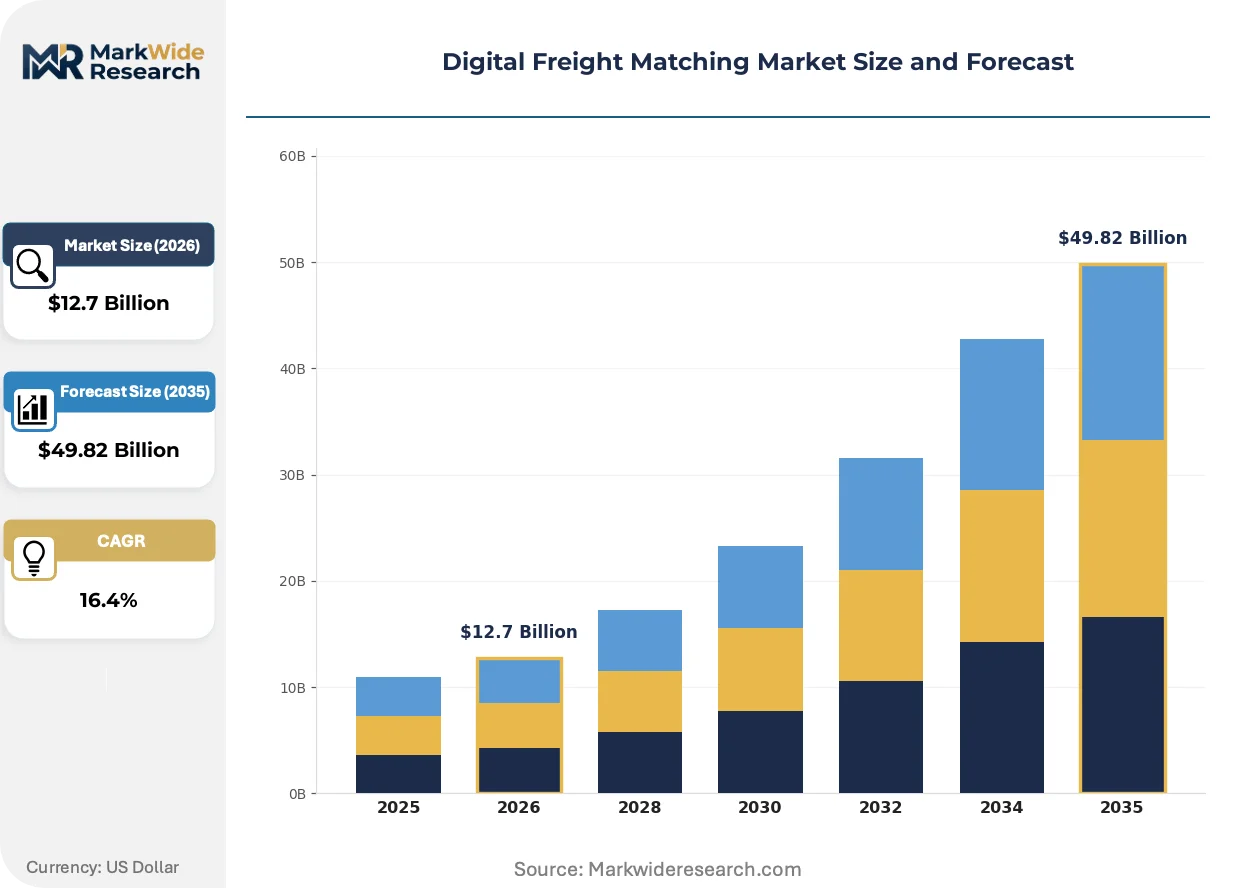
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $49.82 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Load Board, Freight Brokerage, Carrier Management, Asset-Based Services Technology: Cloud Computing, Mobile Applications, Blockchain, AI Algorithms Customer Type: Shippers, Freight Forwarders, Carriers, Brokers Deployment: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | DAT Freight & Analytics, J.B. Hunt 360, Uber Freight, Cargomatic, Flexport, C.H. Robinson, Convoy, Redwood Logistics, XPO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Freight Matching Market Evolving Landscape
Real-time visibility infrastructure is converging with automated execution layers, collapsing the traditional separation between freight tracking and freight procurement into single-workflow platforms.
Machine learning rate prediction is converging with instant booking interfaces, allowing large enterprise shippers to lock capacity without human broker intervention. Food and beverage distributors with temperature-controlled requirements are adopting these tools fastest, compressing their tender acceptance windows from four hours to under ten minutes. The structural consequence is that static annual routing guides are converging with dynamic spot market access, blurring contract and spot pricing boundaries.
The EU Green Deal and emerging CSRD carbon disclosure rules are mandating documented emissions reductions across transport procurement. Shippers must now report scope 3 logistics emissions, pushing matching platforms to calculate and display CO2 per lane alternative. European retail and automotive verticals are responding by embedding carbon intensity scores alongside price in carrier selection algorithms.
Shipper procurement teams are consolidating vendor relationships from fragmented broker panels toward integrated platform subscriptions that bundle matching, visibility, and payment. Mid-sized manufacturers are replacing spot-market email blasts with API-connected freight platforms that feed directly into their ERP systems. This concentration is most visible in the US Southeast and German industrial corridors, where procurement heads have eliminated secondary broker relationships entirely.
Digital Freight Matching Market Segmentation
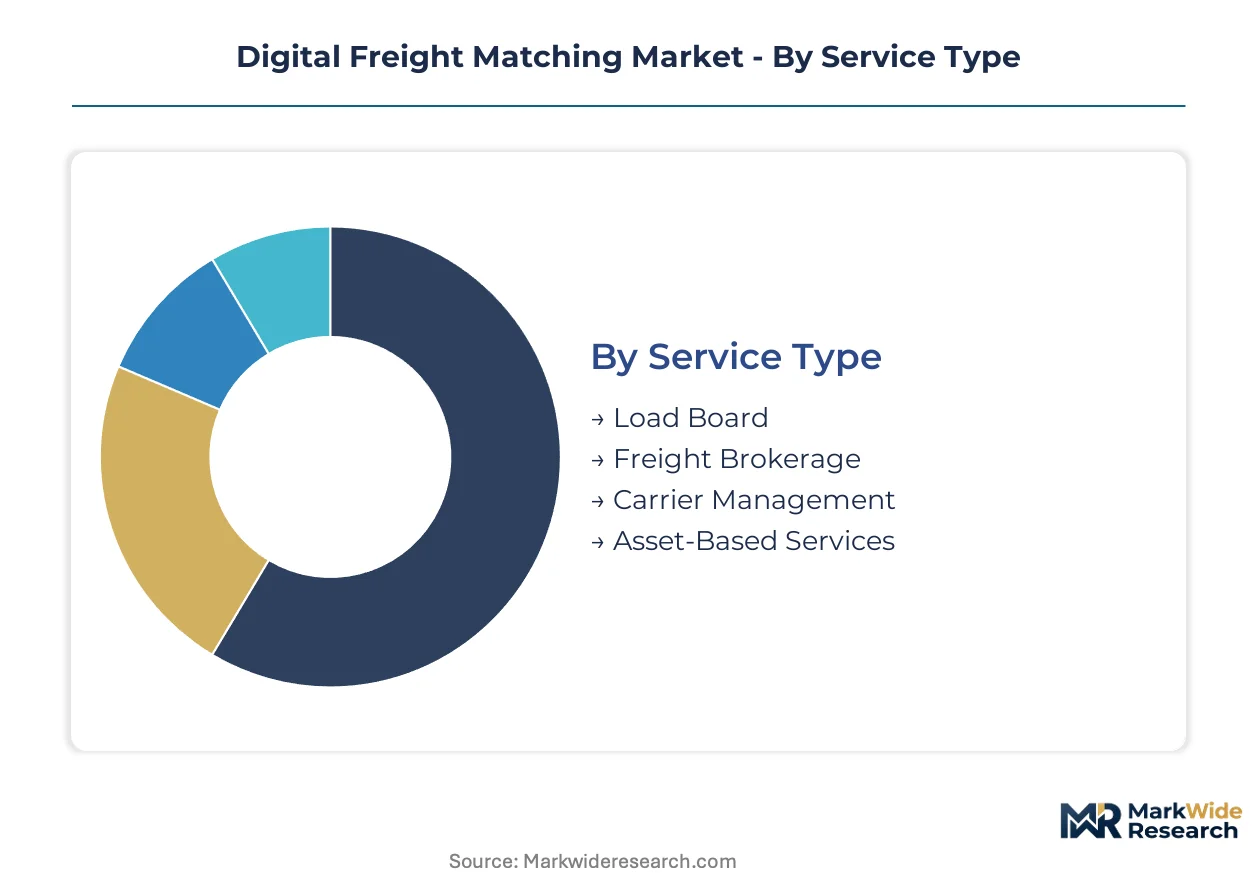
Digital freight matching platforms serve heterogeneous logistics workflows spanning spot-market volatility, contracted lane stability, and multi-party coordination. Segmentation reveals how technology architecture and procurement relationships determine platform economics and vendor selection criteria.
Service Type:
Standardized matching services compete against configurable brokerage layers across this spectrum, with customization depth correlating directly to shipper IT integration requirements.
- Load Board:Digital marketplaces publish available freight and truck capacity with basic search and filtering. Demand concentrates among small fleet owner-operators in the US Southeast corridor, where port congestion at Savannah and Charleston generates acute spot-market imbalances that static boards cannot resolve efficiently.
- Freight Brokerage:Managed services combine algorithmic matching with human intervention for exception handling and relationship management. Large retail and automotive shippers in Germany's industrial corridors are consolidating vendor relationships toward these integrated subscriptions that bundle matching, visibility, and payment.
- Carrier Management:Performance scoring, compliance verification, and capacity planning tools for ongoing carrier relationships.
- Asset-Based Services:Platforms operated by fleet owners integrating proprietary dispatch data with external brokerage capacity.
Leading the category by volume: Load Board. Expanding most quickly: Freight Brokerage.
Technology:
Legacy infrastructure migration costs segment adopters by fleet scale and IT maturity, with cloud-native architectures commanding premium pricing against on-premise alternatives.
- Cloud Computing:Scalable infrastructure processing GPS telemetry and dwell-time signals at volume. Food and beverage distributors with temperature-controlled requirements adopt these fastest, compressing tender acceptance windows from four hours to under ten minutes.
- AI Algorithms:Machine learning models predicting rates, optimizing repositioning, and scoring carrier reliability. European retail verticals embed carbon intensity scores alongside price in carrier selection algorithms to satisfy CSRD disclosure requirements.
- Mobile Applications:Driver-facing interfaces for instant booking, document capture, and real-time communication.
- Blockchain:Distributed ledger systems for smart contracts, payment settlement, and document verification.
Dominant by deployment scale: Cloud Computing. Steepest expansion trajectory: AI Algorithms.
Customer Type:
Procurement centralization versus decentralized spot-buying patterns separate enterprise adopters from fragmented small-fleet behavior.
- Shippers:Manufacturing and retail enterprises sourcing truck capacity directly. Mid-sized manufacturers in the US Southeast are replacing spot-market email blasts with API-connected platforms feeding directly into ERP systems.
- Carriers:Fleet operators and owner-operators seeking backhaul optimization and reduced deadhead miles.
- Freight Forwarders:Intermediaries coordinating multi-modal international movements requiring door-to-door pricing transparency.
- Brokers:Traditional intermediaries rebuilding pricing engines around real-time telemetry to defend volume against cloud-native platforms.
Highest transaction volume: Shippers. Gaining share fastest: Freight Forwarders.
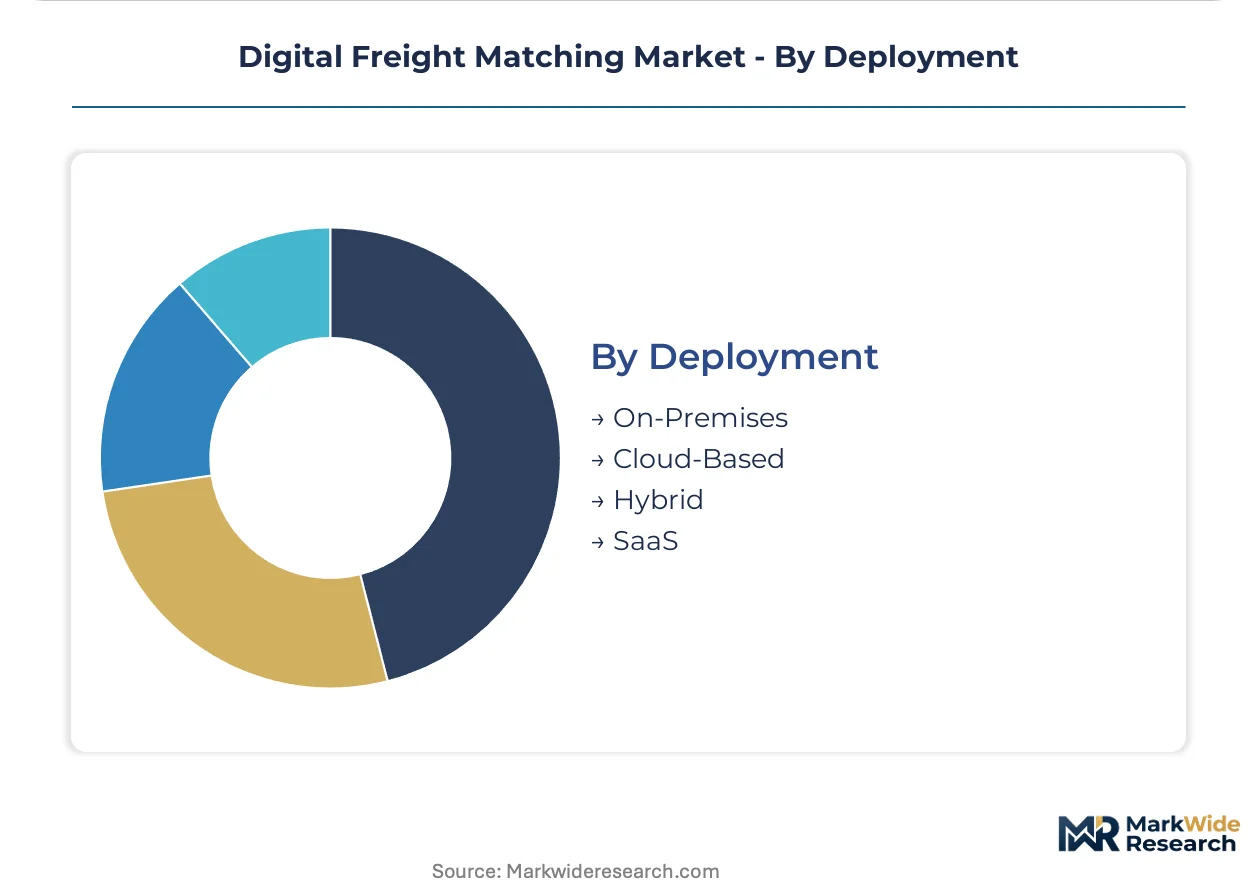
Deployment:
Data sovereignty requirements and legacy system integration complexity drive configuration choices across asset-heavy and asset-light operators.
- SaaS:Multi-tenant subscription platforms with standardized APIs and rapid implementation. Dominates new implementations as mid-market shippers prioritize collapsing integration costs.
- Hybrid:Split architectures preserving proprietary dispatch data on-premise while leveraging cloud matching engines. Asset-heavy operators favor this configuration, limiting network effects for pure SaaS vendors.
- Cloud-Based:Fully hosted solutions without on-premise components, distinct from SaaS in single-tenant or custom deployment models.
- On-Premises:Self-managed installations within shipper or carrier data centers for maximum control.
Leading new implementations: SaaS. Persisting among incumbents: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Southeast corridor concentrates the most acute freight imbalances, with Savannah and Charleston port congestion compressing carrier availability windows and amplifying demand for algorithmic matching platforms.
United States
FMCSA hours-of-service enforcement and the ELD mandate have structurally tightened truck capacity across the Southeast and Midwest manufacturing belts. The US DOT continues tightening compliance windows, forcing shippers toward platforms that minimize deadhead miles. Retail and e-commerce logistics teams in the Atlanta and Dallas distribution hubs are replacing static load boards with predictive pricing tools.
Germany
CSRD disclosure requirements under the EU Green Deal are mandating documented scope 3 emissions reductions across automotive and retail supply chains. ECHA and national regulators are aligning transport procurement rules with carbon intensity scoring. The Rhine-Ruhr and Stuttgart industrial corridors show the fastest consolidation toward integrated platform subscriptions bundling matching, visibility, and payment.
China
Dual carbon goals and MIIT smart logistics initiatives are accelerating cloud-native platform adoption among domestic freight networks. SAMR data governance rules are reshaping how GPS telemetry and carrier dispatch data flow through matching algorithms. The Yangtze River Delta and Pearl River Delta manufacturing clusters are deploying AI-driven lane optimization to address chronic port-to-inland imbalances.
India
PLI scheme incentives for manufacturing scale are intensifying freight density between Gujarat textile hubs and Maharashtra automotive corridors. The Ministry of Road Transport and Highways is digitizing toll and fleet compliance data, enabling API-first matching platforms. Bangalore and Hyderabad technology centers are emerging as development hubs for mobile-first driver applications serving fragmented owner-operator markets.
United Kingdom
Post-Brexit customs complexity and Northern Ireland protocol friction are driving demand for multi-modal matching platforms spanning road and short-sea routes. The UK's Transport Decarbonisation Plan is embedding carbon reporting into logistics procurement rules. The Midlands distribution triangle and London satellite hubs are consolidating broker relationships toward SaaS platforms with ERP integration.
Digital Freight Matching Market Competitive Landscape
Capital-heavy asset operators compete with asset-light platform designers for control of freight data flows. The market structures around three tiers: integrated carriers with proprietary fleet feeds, cloud-native brokers scaling through API density, and legacy intermediaries rebuilding pricing engines around real-time telemetry. Dominant competitive moves include M&A to capture historical rate databases and strategic partnerships to embed matching tools inside shipper ERP systems.
Within the cloud-native broker tier, DAT Freight & Analytics and Uber Freight exemplify divergent scale strategies—one anchoring enterprise contract negotiation through historical data depth, the other capturing spot-market density through driver-app install bases. J.B. Hunt 360 occupies a hybrid position, combining owned fleet telemetry with external brokerage capacity to sustain integrated platform control.
| Leading Market Players |
|---|
| DAT Freight & Analytics |
| J.B. Hunt 360 |
| Uber Freight |
| Cargomatic |
| Flexport |
| C.H. Robinson |
| Convoy |
| Redwood Logistics |
| XPO |
| Others |
Value Network & Pricing Analysis
Horizontal integration between cloud-native matching platforms and telematics data providers anchors supply position while concentrating pricing power among API-first operators that control real-time capacity feeds. Asset-heavy carriers guarding proprietary dispatch data in hybrid configurations cede margin to multi-tenant SaaS vendors that aggregate network effects across fragmented owner-operator bases.
Pricing Analysis
Outcome-based pricing tied to tender-to-accept compression anchors the premium tier, with food and beverage distributors paying for sub-ten-minute matching guarantees while commodity shippers accept static load-board visibility. Price differentiation rests on predictive accuracy tiers and ERP integration depth, with API-connected platforms commanding premiums over email-based spot sourcing. Pricing pressure stems from carrier churn eroding algorithm training quality, forcing manual override investments that slow execution. Small fleet owner-operators exhibit highest price sensitivity, while enterprise retail shippers prioritize matching speed over per-load cost.
Supply Chain Analysis
Empty-mile repositioning flows and backhaul optimization circuits constitute the reverse-logistics backbone of digital freight matching, with algorithms minimizing deadhead by redirecting capacity toward inbound demand signals. Platform infrastructure draws from cloud computing clusters concentrated in the United States, Germany, and China, while GPS telemetry hardware sources from Taiwan and South Korea semiconductor fabs. Supply chain risk centers on single-source vulnerability in telematics provider APIs, where inconsistent data formats force expensive custom integration projects. Distribution runs through multi-tenant SaaS deployments for mid-market shippers and hybrid configurations for asset-heavy operators guarding proprietary dispatch data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US ELD mandate and FMCSA hours-of-service enforcement have erected a cost-of-compliance moat that favors platforms with pre-existing carrier qualification infrastructure, locking out entrants lacking automated HOS monitoring capabilities.
For Market Incumbents: Deploy historical rate database depth as a defensive lever by anchoring enterprise contract negotiation tools that substitute algorithmic pricing for traditional broker relationships. Integrate temperature-controlled matching modules to capture food and beverage distributor demand migrating from static routing guides. Counter the threat of cloud-native entrants through backward integration into telematics hardware partnerships that secure exclusive capacity feeds. For New Entrants and Emerging Players: The mid-market manufacturer segment between enterprise ERP-integrated platforms and small-fleet load boards offers the most penetrable white space, with procurement heads in the US Southeast corridor eliminating secondary broker relationships entirely. Target API-first implementations feeding directly into mid-tier ERP systems, bypassing the hybrid configuration complexity that incumbents exploit. A carbon-intensity scoring module addresses CSRD disclosure requirements without requiring the historical data depth that DAT Freight & Analytics and J.B. Hunt 360 have accumulated. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by enterprise logistics software vendors seeking embedded matching capabilities, with platform install base density and carrier qualification infrastructure as primary valuation anchors. Long-term viability favors operators combining cloud-native architecture with proprietary data moats that resist commoditization. Monitor FMCSA enforcement intensity and diesel price volatility as inflection indicators that accelerate shipper migration toward algorithmic platforms or trigger manual override cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Collapses tender-to-accept intervals from hours to minutes for enterprise shippers. |
| Predictive Pricing Engine Deployment | Locks capacity without human broker intervention using machine learning rate models. |
| Carbon Accounting Module Launch | Embeds CO2 intensity scores alongside price to satisfy EU CSRD disclosure mandates. |
| Telematics Data Partnership | Secures exclusive GPS feed access that differentiates matching accuracy from commodity load boards. |
| Hybrid Configuration Migration | Preserves proprietary dispatch data for asset-heavy operators while leveraging cloud matching scale. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with freight brokerage operations directors, carrier fleet managers, shipper procurement leads, and TMS integration specialists. FMCSA enforcement databases, EU transport emission registries, and SAMR smart logistics disclosures provided regulatory calibration. Bottom-up carrier platform adoption curves and top-down logistics spend allocations were triangulated against cloud infrastructure capex disclosures from hyperscaler filings.
Reconciliation of tender volume indices, GPS telemetry deployment rates, and SaaS subscription billing data informed the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology architecture, customer category, and deployment configuration alongside corridor-specific density indices for the US Southeast and German industrial belts. CAGRs were derived from algorithmic matching penetration curves and spot-market platform transaction growth, with ELD mandate compliance timelines and CSRD disclosure deadlines as structural demand accelerants.
Inputs from carrier dispatch system vendors and shipper ERP providers were available through the study window; gaps in real-time pricing transparency for private fleet operations introduce uncertainty bands around asset-based service projections. Forecasts reflect documented assumptions regarding FMCSA enforcement consistency and diesel price regime stability. Practitioners should monitor port congestion indices at Savannah and Charleston and EU carbon accounting finalization for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Warehousing and Distribution Logistics Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Nigeria Freight and Logistics Market
Logistics and Shipping
Singapore Freight and Logistics Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
South Korea International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Japan Logistics Market