
 Global 3PL in Cold Chain Logistics Market | 2026-2036
Global 3PL in Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3PL in Cold Chain Logistics Market Analysis
Temperature-controlled last-mile delivery revenue is fragmenting across asset-light digital brokers and dedicated fleet operators. Lineage Logistics sustains its position through backward integration into automated high-bay cold storage facilities across North America. Americold Logistics anchors its network with controlled-atmosphere warehousing systems that extend produce shelf life for export-oriented agricultural clients. Kuehne + Nagel competes on pharmaceutical certification density, operating GDP-compliant lanes that connect European manufacturing clusters to emerging distribution hubs.
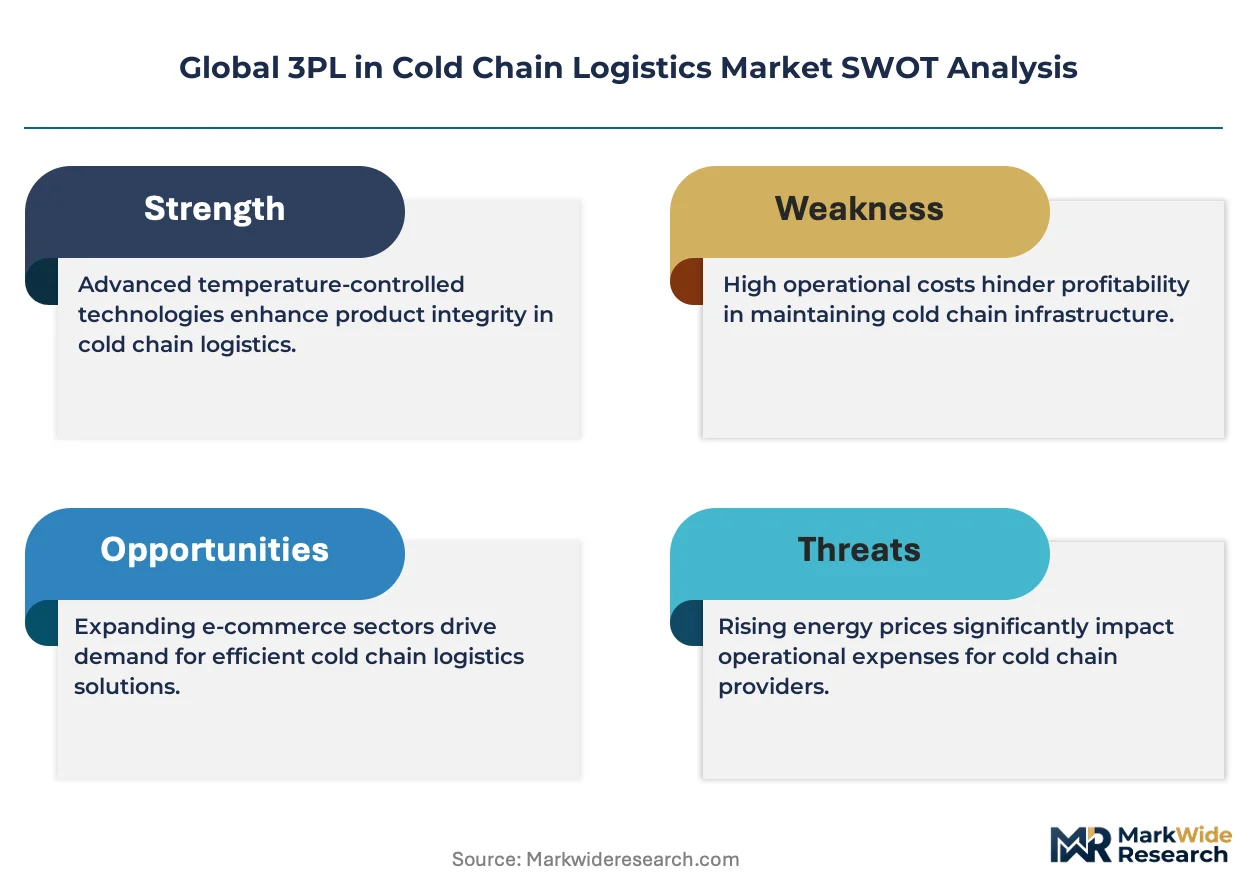
Third-party logistics in cold chain logistics encompasses outsourced management of temperature-sensitive goods movement, requiring continuous thermal monitoring within specified ranges typically between minus 25 degrees Celsius and plus 8 degrees Celsius depending on product category. The primary commercial purpose centers on preserving product integrity across pharmaceutical, food, and biotechnology supply chains while transferring capital-intensive refrigeration asset ownership from shippers to specialized operators. Frozen products command the most intensive infrastructure investment due to energy requirements and equipment redundancy needs, while transport services generate the highest revenue turnover through lane density optimization. Monitoring services represent the fastest-expanding margin pool as real-time IoT sensor deployment becomes a contractual baseline for pharmaceutical and biotechnology clients.
FDA enforcement of the Drug Supply Chain Security Act elevates traceability requirements for pharmaceutical 3PL providers serving United States distribution networks. EMA Good Distribution Practice guidelines and EU F-Gas Regulation phase-down mandates collectively reshape European cold chain equipment procurement and refrigerant management protocols. Stakeholders must evaluate whether to build captive temperature-controlled fleets or deepen outsourcing relationships as regulatory compliance costs diverge across regional enforcement regimes.
Market Dynamics
Pharmaceutical shippers are transferring ownership of capital-intensive refrigeration assets to specialized operators as EU F-Gas Regulation mandates accelerate equipment replacement cycles and compress carrier qualification timelines.
Growth Catalysts
- Biologics pipeline expansion:Cell and gene therapies require minus 150 degrees Celsius cryogenic transport, forcing pharmaceutical manufacturers to outsource rather than build captive ultra-low temperature infrastructure.
- India PLI scheme for food processing:Government incentives for cold storage construction are generating dedicated 3PL demand from mango, grape, and seafood export consortia in Maharashtra and Andhra Pradesh.
- Real-time IoT sensor deployment:GDP-compliant temperature logging is becoming a contractual baseline, expanding margin pools for monitoring-as-a-service offerings across biotechnology distribution networks.
Market Restraints
- Refrigerant input cost volatility:EU F-Gas Regulation phase-down limits hydrofluorocarbon supply, forcing cold storage operators in Germany and France to absorb retrofit costs or pass through to shippers.
- Specialized fleet supply concentration:Refrigerated trailer manufacturing clusters in Poland and Turkey create lead time vulnerability for 3PLs expanding cross-border pharmaceutical lanes.
- Energy intensity ceiling:Automated high-bay cold storage facilities face grid capacity constraints in suburban Boston and Rotterdam logistics corridors, capping expansion velocity.
Strategic Opportunities
- Brazil perishable export corridor:Underdeveloped temperature-controlled warehousing in São Paulo state creates first-mover advantage for operators building GDP-compliant infrastructure ahead of ANVISA enforcement tightening.
- Controlled-atmosphere technology convergence:Integration of ethylene scrubbing with automated inventory systems extends produce shelf life for Chilean cherry and South African citrus export programs.
- Last-mile pharmacy distribution innovation:Urban micro-fulfillment hubs with minus 25 degrees Celsius capability address same-day biologics delivery demand in Tokyo and Singapore dense residential zones.
Industry Challenges
- Refrigeration technician skill scarcity:Specialized ammonia and CO2 cascade system expertise concentrates in aging workforces across Midwestern US cold storage hubs, constraining facility commissioning schedules.
- GDP certification timeline compression:EMA audit backlogs delay European pharmaceutical 3PL qualification, freezing lane expansion plans for operators awaiting compliance verification.
- Legacy warehouse management system integration:Proprietary temperature monitoring protocols from 1990s-era installations resist API connectivity with modern IoT sensor networks, fragmenting data visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3PL in Cold Chain Logistics Market |
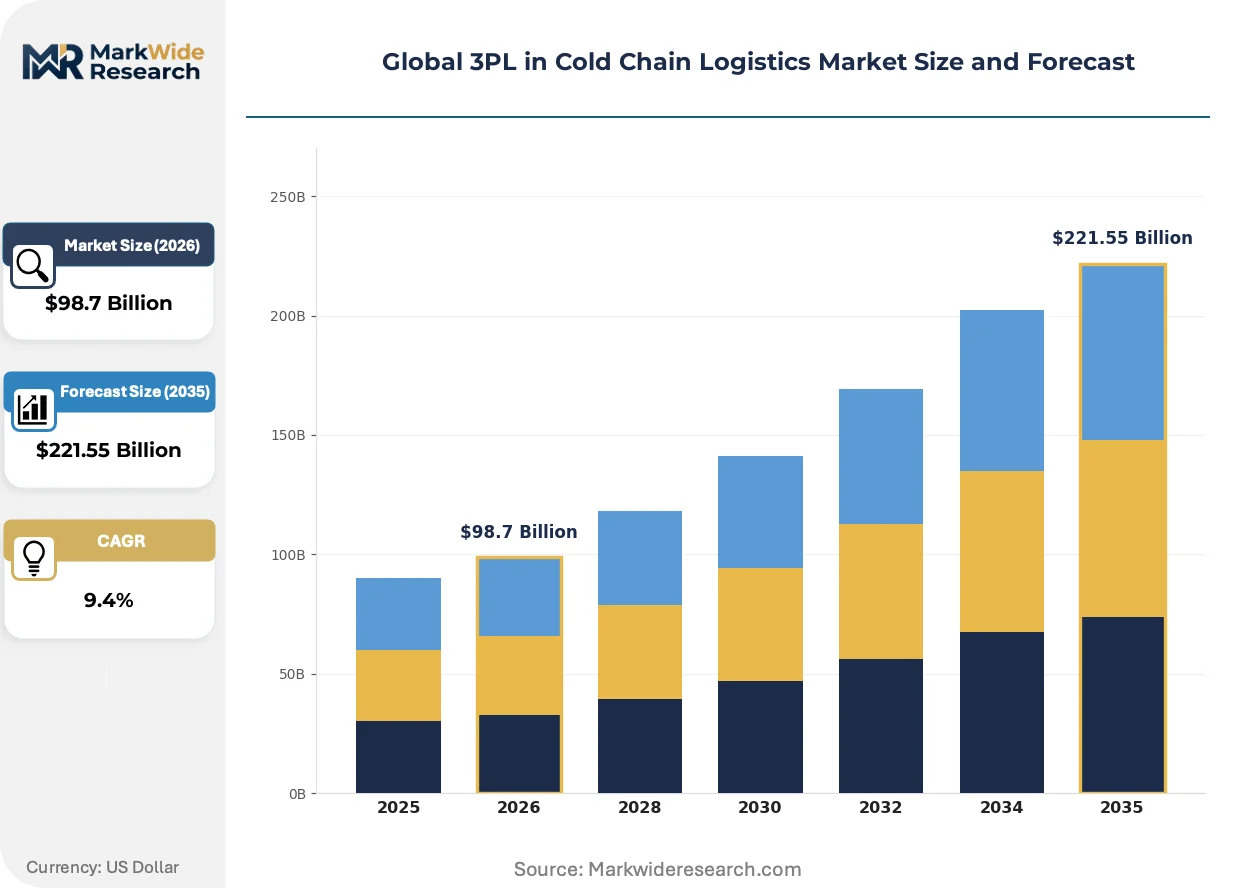
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $221.55 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled Products, Frozen Products, Ambient Products, Perishable Goods Distribution Channel: Direct Sales, Third-party Distributors, Online Retailers, E-commerce Platforms End User: Pharmaceuticals, Food & Beverage, Agriculture, Biotechnology Service Type: Transport Services, Warehousing Services, Monitoring Services, Handling Services |
| Companies Covered | Lineage Logistics, Americold Logistics, DHL Supply Chain, Kuehne + Nagel, Maersk Logistics, UPS Supply Chain Solutions, FedEx, DB Schenker, Nichirei Logistics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3PL in Cold Chain Logistics Market Emerging Trajectories
Digital freight platforms and autonomous cold storage robotics are compressing operating cost structures while regulatory traceability mandates rewire contractual relationships between pharmaceutical manufacturers and logistics providers.
Autonomous mobile robots with minus 30 degrees Celsius rating are collapsing labor cost structures in high-bay frozen warehouses. Pharmaceutical distributors in Switzerland and the Netherlands are deploying these units at pilot scale, with full rollout timelines compressing from five years to eighteen months. The technology is collapsing the historical trade-off between storage density and picking speed that constrained automated cold facility design.
EU F-Gas Regulation mandates complete phase-out of refrigerants with global warming potential above 2,500 by 2030. Cold storage operators in Germany and France face accelerated equipment replacement, with ammonia-CO2 cascade systems becoming the default specification for new construction. Frozen food 3PLs serving export-oriented agricultural clients in these markets are absorbing retrofit costs to maintain carrier qualification status.
Biopharma procurement teams are unbundling temperature-controlled transport from integrated supply contracts, creating spot market liquidity for certified lanes. Large molecule manufacturers in Massachusetts and Basel are disaggregating long-term 3PL relationships into modular service components. This pattern concentrates most visibly in clinical trial logistics, where sponsor companies demand lane-specific performance guarantees rather than network-wide commitments.
Global 3PL in Cold Chain Logistics Market Segmentation
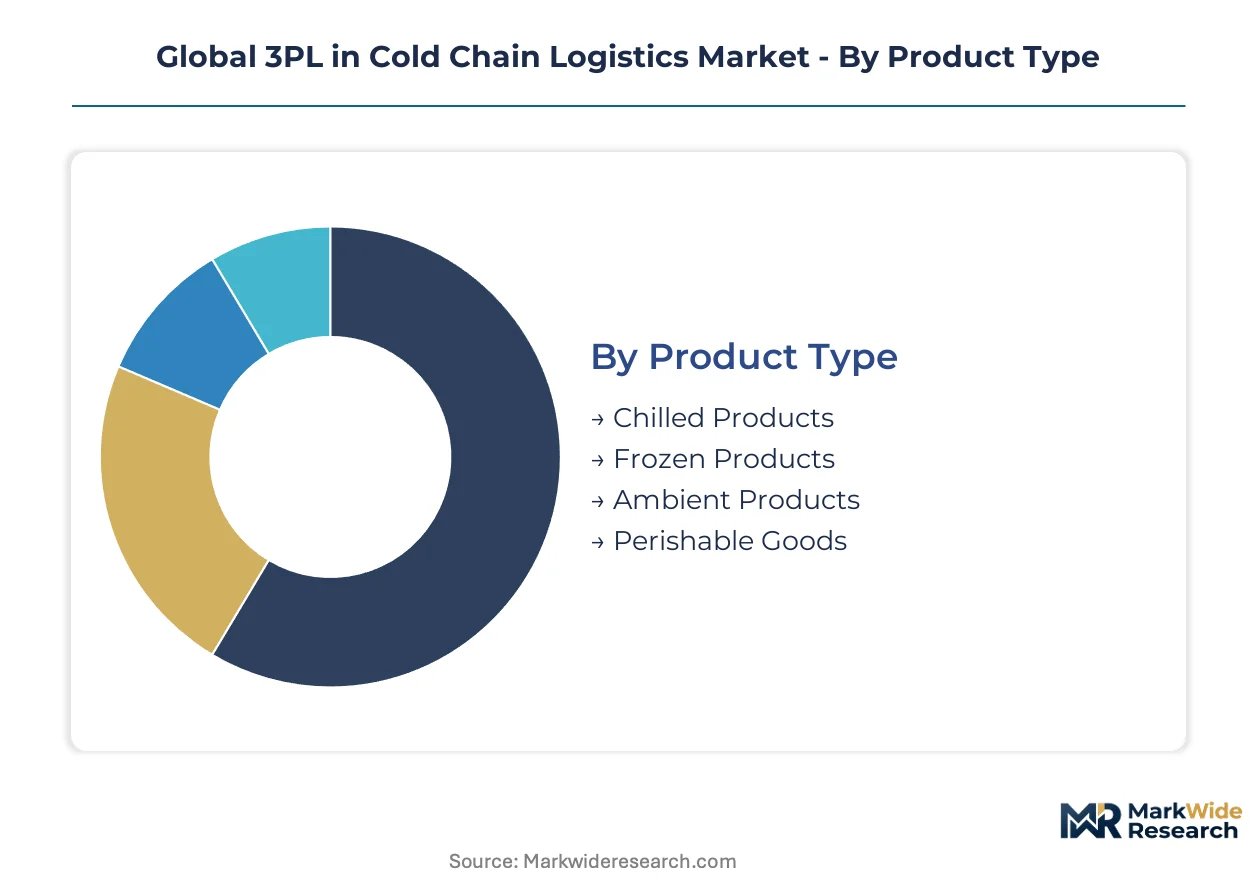
Cold chain 3PL segmentation reveals how thermal requirements, channel complexity, and regulatory density fragment service economics. Each dimension carries distinct margin profiles and capital intensity thresholds that reshape competitive positioning across pharmaceutical, food, and biotechnology supply chains.
Product Type:
Cost tier differentiation separates infrastructure-heavy frozen operations from lighter chilled and ambient configurations.
- Frozen Products:Minus 25 degrees Celsius continuous operation demands ammonia-CO2 cascade refrigeration systems with redundant compressor arrays. Demand concentrates in export-oriented seafood processors across Norway and Chile, where EU F-Gas Regulation compliance timelines compress carrier qualification windows.
- Chilled Products:Zero to plus 8 degrees Celsius range serves pharmaceutical distribution networks with GDP-compliant lane density requirements. German and Dutch 3PLs are rotating capacity toward biologics manufacturers seeking controlled-room-temperature stability for mRNA vaccine distribution.
- Ambient Products:Non-refrigerated segments within temperature-sensitive portfolios capture seasonal produce and certain packaged pharmaceuticals. Indian mango exporters in Maharashtra leverage ambient staging before chilled consolidation for Middle East air freight corridors.
- Perishable Goods:Short-shelf-life categories spanning dairy, fresh meat, and cut flowers require rapid throughput design. Brazilian floriculture exporters in São Paulo state drive demand for pre-cooling infrastructure integrated with cold storage facilities.
Frozen Products holds installed capacity. Chilled Products is rotating up the share rankings.
Distribution Channel:
Channel structure determines asset ownership boundaries between 3PL operators and their shipper clients.
- Direct Sales:Manufacturer-controlled distribution retains temperature integrity accountability within captive fleet or dedicated 3PL arrangements. Swiss pharmaceutical manufacturers in Basel maintain direct sales channels for high-value biologics requiring chain-of-custody documentation.
- Third-party Distributors:Independent wholesale intermediaries aggregate fragmented shipper volumes across regional pharmaceutical and food networks. Japanese drug distributors in Tokyo prefecture are consolidating third-party relationships to meet PMDA serialization requirements.
- Online Retailers:E-grocery platforms with last-mile cold delivery mandates drive urban micro-fulfillment investment. Singapore-based fresh produce platforms are contracting dedicated minus 25 degrees Celsius urban hubs for same-day seafood delivery.
- E-commerce Platforms:Marketplace models with multi-seller temperature requirements create spot-market liquidity for certified lanes. South Korean beauty and health platforms are segmenting pharmaceutical-grade from food-grade fulfillment infrastructure under MFDS guidance.
Direct Sales anchors premium pharmaceutical flows. Online Retailers is expanding most quickly in urban last-mile configurations.
End User:
Application-specific compliance requirements fragment service specifications and pricing power across customer verticals.
- Pharmaceuticals:GDP-compliant operations with continuous temperature logging and deviation investigation protocols command highest service premiums. Massachusetts-based cell therapy manufacturers are outsourcing minus 150 degrees Celsius cryogenic transport rather than building captive ultra-low infrastructure.
- Food & Beverage:Diverse thermal requirements from frozen seafood to controlled-atmosphere produce create segmentation opportunities within integrated networks. Australian beef exporters are contracting controlled-atmosphere services for extended shelf-life Middle East shipments.
- Agriculture:Seasonal harvest patterns and export certification requirements drive demand for flexible cold storage with fumigation capabilities. South African citrus exporters in Western Cape are integrating ethylene scrubbing with automated inventory systems.
- Biotechnology:Clinical trial logistics with patient-specific dosing and temperature excursion liability demands lane-specific performance guarantees. Netherlands-based gene therapy sponsors are unbundling transport from integrated supply contracts to access modular service components.
Pharmaceuticals dominates value concentration. Biotechnology is climbing the fastest on cell and gene therapy pipeline expansion.
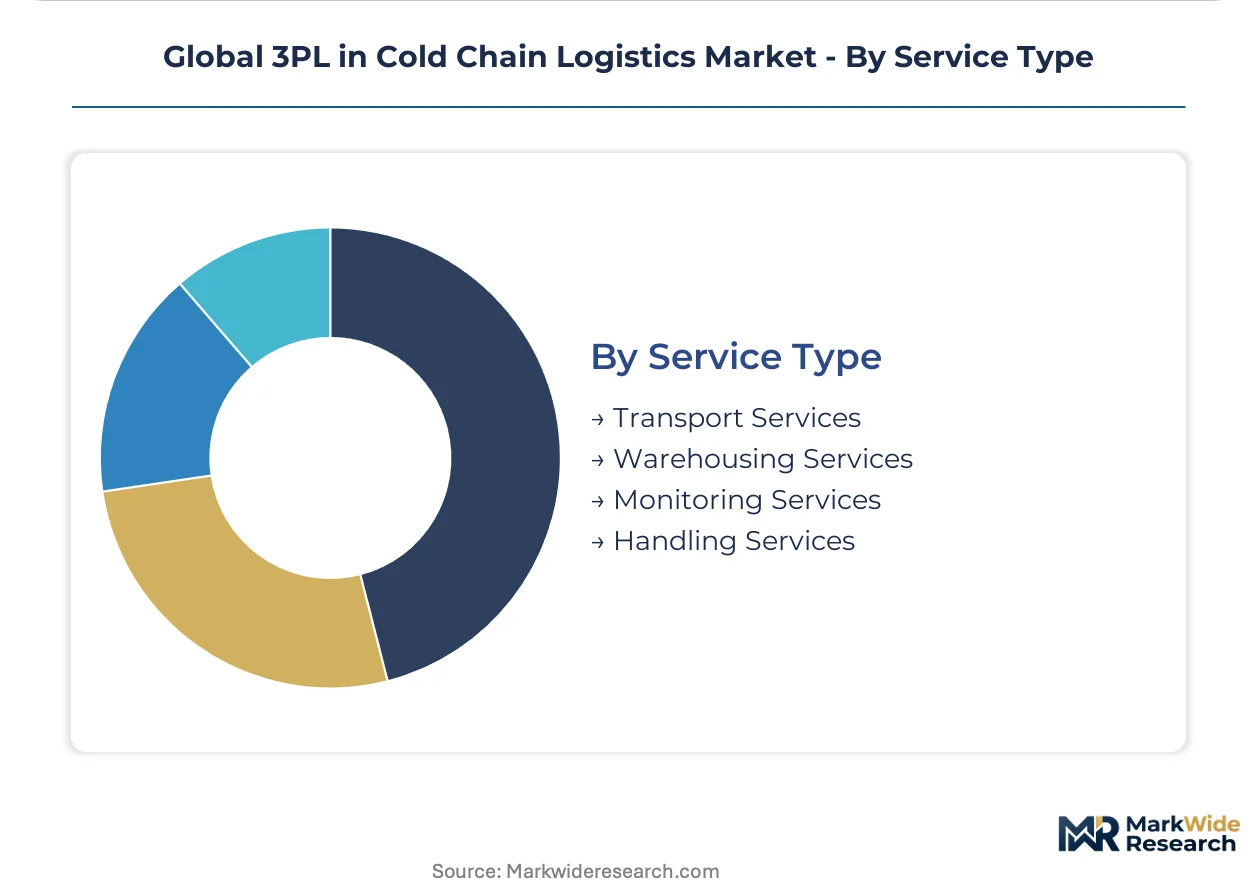
Service Type:
Margin structure inverts between capital-intensive warehousing and high-turnover transport services.
- Transport Services:Lane density optimization across pharmaceutical and food corridors generates highest revenue turnover but compresses margins without backhaul efficiency. Cross-border operators between Germany and Poland are absorbing EU F-Gas retrofit costs to maintain qualification status.
- Warehousing Services:Automated high-bay cold storage with robotic picking systems captures economies of scale in frozen food consolidation. Lineage Logistics sustains positioning through backward integration into North American automated facilities.
- Monitoring Services:Real-time IoT sensor deployment with GDP-compliant temperature logging is becoming contractual baseline. Swiss and Dutch pharmaceutical distributors are expanding margin pools through monitoring-as-a-service offerings.
- Handling Services:Cross-docking, repackaging, and customs brokerage within temperature-controlled environments adds value at consolidation nodes. Indian seafood exporters in Andhra Pradesh are contracting dedicated handling services for EU export certification.
Transport Services commands volume leadership. Monitoring Services shows steepest expansion trajectory on IoT sensor standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical shippers in Germany absorb EU F-Gas retrofit costs with minimal price elasticity, while Indian mango exporters in Maharashtra negotiate aggressively on chilled transport rates. Brazil's underdeveloped cold storage infrastructure creates first-mover premiums for qualified operators.
Germany
Frozen food exporters and biologics manufacturers drive ammonia-CO2 cascade system demand. EU F-Gas Regulation phase-down mandates accelerate equipment replacement in Hamburg and Frankfurt logistics corridors. Automated high-bay facilities in Lower Saxony face grid capacity constraints that cap expansion velocity.
United States
Cell therapy manufacturers in Massachusetts outsource minus 150 degrees Celsius cryogenic transport rather than build captive infrastructure. FDA enforcement of DSCSA traceability requirements elevates 3PL qualification standards. Suburban Boston cold storage operators encounter energy intensity ceilings that limit facility commissioning.
India
Seafood export consortia in Andhra Pradesh and grape shippers in Maharashtra generate dedicated 3PL demand. PLI scheme incentives for cold storage construction expand temperature-controlled warehousing capacity. Mumbai and Visakhapatnam logistics clusters concentrate government-backed infrastructure investment.
Brazil
São Paulo state floriculture and beef exporters require pre-cooling infrastructure integrated with export certification capabilities. ANVISA enforcement tightening ahead of regulatory deadlines creates qualification urgency for GDP-compliant warehouse construction. Underdeveloped temperature-controlled warehousing in the state generates premium pricing for first-mover operators.
Japan
Urban micro-fulfillment hubs with ultra-low temperature capability address same-day biologics delivery demand in Tokyo dense residential zones. PMDA serialization requirements consolidate third-party distributor relationships. Kanto region pharmaceutical distributors deploy autonomous mobile robots at pilot scale to compress labor cost structures.
Global 3PL in Cold Chain Logistics Market Vendor Landscape
Asset-heavy cold storage operators and asset-light digital brokers split the market along capital intensity lines. Consolidation concentrates in automated high-bay frozen warehousing, while transport services fragment across lane-specific specialists. Three archetypes dominate: backward-integrated facility owners, GDP-certified pharmaceutical lane operators, and IoT-enabled monitoring service providers. M&A activity targets automated warehouse robotics capabilities, and strategic partnerships secure ammonia-CO2 cascade system expertise.
Within the integrated infrastructure tier, Lineage Logistics and Americold Logistics exemplify backward integration into automated cold storage networks. Kuehne + Nagel occupies a position among pharmaceutical certification specialists with dense GDP-compliant lane coverage. These three anchors represent divergent strategic bets on facility ownership versus service modularity.
| Leading Market Players |
|---|
| Lineage Logistics |
| Americold Logistics |
| DHL Supply Chain |
| Kuehne + Nagel |
| Maersk Logistics |
| UPS Supply Chain Solutions |
| FedEx |
| DB Schenker |
| Nichirei Logistics Group |
| Others |
Supply Flow & Price Mechanics
Refrigerated trailer manufacturing clusters in Poland and Turkey concentrate upstream capacity, directing margin capture toward GDP-certified lane operators and automated warehouse owners downstream. EU F-Gas Regulation compliance costs cascade through equipment procurement, compressing carrier qualification timelines and reshaping where pricing power accumulates.
Pricing Analysis
Monitoring-as-a-service contracts with pharmaceutical manufacturers drive lifetime value through recurring revenue streams rather than spot transport margins. Three-tier pricing structure across GDP-certified premium, standard cold chain, and economy ambient tiers separates pharmaceutical shippers from food exporters and seasonal agricultural clients. Pricing pressure stems from EU F-Gas retrofit cost absorption requirements in Germany and France, where frozen food 3PLs face compressed margins. Indian mango exporters in Maharashtra demonstrate highest price sensitivity, while Massachusetts cell therapy manufacturers accept premium rates for minus 150 degrees Celsius cryogenic capability.
Supply Chain Analysis
Contract manufacturing for ammonia-CO2 cascade refrigeration systems concentrates in Germany, Denmark, and Japan, with component fabrication feeding global cold storage construction. Equipment procurement draws from specialized steel fabrication, compressor arrays, and IoT sensor networks. Single-source vulnerability sits with European refrigerant supply under F-Gas Regulation phase-down mandates. Distribution runs through pharmaceutical manufacturing clusters in Massachusetts and Basel connecting to emerging hubs in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. GDP certification density creates switching costs that lock pharmaceutical manufacturers into qualified carrier networks.
For Market Incumbents: Harden certification moats through accelerated EMA audit preparation while EMA backlogs freeze competitor qualification timelines. Deepen backward integration into automated high-bay facilities in Lower Saxony and Hamburg corridors where grid capacity constraints cap new entrant expansion. Threat substitution from asset-light digital brokers demands lane-specific performance guarantees rather than network-wide commitments.
For New Entrants and Emerging Players: São Paulo state underpenetration in GDP-compliant temperature-controlled warehousing offers first-mover premium capture ahead of ANVISA enforcement tightening. Maharashtra seafood export consortia generate dedicated 3PL demand with government-backed infrastructure investment through PLI scheme incentives. Target lane-specific pharmaceutical certification rather than integrated network competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automated cold storage operators in North America and Western Europe seeking robotics capability bolt-ons. Five-to-ten year viability hinges on ammonia-CO2 cascade system expertise concentration and IoT sensor network integration. Signal to watch: EMA audit backlog clearance rates as inflection indicator for qualification velocity and lane expansion permissioning.
| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | EMA-compliant lane density locks pharmaceutical manufacturers into qualified carrier networks. |
| Automated Warehouse Robotics | Autonomous mobile robots with minus 30 degrees Celsius rating collapse labor cost structures in frozen facilities. |
| Ammonia-CO2 Cascade Retrofit | EU F-Gas Regulation compliance maintains carrier qualification status in German and French corridors. |
| Urban Micro-Fulfillment Buildout | Tokyo and Singapore same-day biologics delivery demand drives ultra-low temperature hub construction. |
| Monitoring-as-a-Service Expansion | Real-time IoT sensor deployment captures margin pools from biotechnology distribution networks. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across pharmaceutical shippers, cold storage facility managers, and refrigerated fleet operators. Primary interviews captured lane density optimization practices, GDP compliance cost structures, and EMA audit preparation timelines. Secondary validation drew from EMA guidance documents, FDA DSCSA enforcement records, EU F-Gas Regulation phase-down schedules, and customs trade data for temperature-controlled equipment. Bottom-up facility capacity modeling and top-down pharmaceutical distribution spend analysis were triangulated.
Calibration against historical qualification velocity and retrofit cost absorption patterns anchored projections across the analysis window. Segmentation dimensions modeled include product thermal tier, distribution channel structure, end-user compliance requirements, and service type margin profiles. CAGRs were derived from equipment replacement cycle compression and lane expansion permissioning rates. Forecast inputs incorporated EU F-Gas phase-down enforcement intensity and ANVISA regulatory tightening timelines.
Practitioners should monitor EMA audit backlog clearance rates, refrigerant input cost volatility, and grid capacity constraint resolutions for early signals of qualification velocity and expansion permissioning shifts. Quarterly review of carrier qualification status changes and automated facility commissioning schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Outbound Logistics Market
Logistics and Shipping
Delivery Tracking Platform Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
United States Freight Brokerage Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
High-Tech Logistics Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
United States Air Freight Market