
 US Reverse Logistics Market | 2026-2036
US Reverse Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
US Reverse Logistics Market Analytics
The capital-intensity gap between asset-heavy networks and technology-first platforms is collapsing as cloud-based orchestration tools democratize scale. FedEx Corporation leverages its integrated ground-air network to sustain dense returns density in metropolitan corridors. XPO Logistics anchors its position through specialized last-mile reverse capacity for big-box retail clients. Optoro Inc differentiates via AI-driven disposition routing that minimizes landfill diversion costs for electronics and apparel channels.
Reverse logistics encompasses the systematic movement of goods from final consumers back to origin points for returns, refurbishment, recycling, or regulatory-compliant disposal, requiring real-time inventory tracking, condition grading protocols, and multi-modal transport coordination. Returns Management commands the largest service-type volume as e-commerce penetration sustains elevated return rates across apparel and consumer electronics categories. Warehouse Management Systems within the technology segment represent the fastest-advancing investment area, while Blockchain applications remain nascent due to implementation cost barriers. Third-Party Logistics providers capture expanding margin pools as shippers outsource complexity rather than build captive reverse infrastructure.
The EPA enforces hazardous waste handling standards for electronics and batteries under RCRA, while OSHA mandates warehouse safety protocols that directly affect returns processing labor costs. State-level extended producer responsibility frameworks in California and New York are forcing OEMs to contract dedicated reverse channels or face compliance penalties. Stakeholders must monitor how the SEC's emerging supply chain disclosure rules will require public documentation of reverse logistics emissions and circularity metrics.
Market Dynamics
California's extended producer responsibility laws are forcing OEMs to internalize end-of-life costs, collapsing the traditional arm's-length returns model and accelerating captive reverse infrastructure buildouts across apparel and consumer electronics channels.
Growth Catalysts
- EPA RCRA hazardous waste standards:Electronics recyclers must recover lithium-ion batteries and rare earth elements under tighter material purity thresholds, expanding specialized processing demand.
- E-commerce return rate elevation:Apparel and consumer electronics categories sustain elevated return volumes that mandate dedicated reverse fulfillment nodes in metropolitan corridors.
- Texas distribution hub concentration:Major 3PLs are anchoring returns processing capacity near Dallas-Fort Worth and Houston to capture cross-border refurbishment flows.
Market Restraints
- Labor cost escalation:OSHA warehouse safety mandates and condition grading protocols inflate returns processing headcount requirements beyond automation substitution rates.
- Blockchain implementation barriers:Provenance tracking for circularity certification faces capital intensity and interoperability gaps that stall enterprise deployment.
- Landfill diversion cost volatility:Regional tipping fee spreads and hazardous waste transport distances compress margin predictability for electronics disposition.
Strategic Opportunities
- AI-driven disposition routing:Machine learning models that match returned goods to resale, refurbishment, or recycling channels based on real-time demand signals remain underdeployed.
- New York state EPR framework expansion:Pending legislation would mandate producer-funded collection infrastructure for additional product categories beyond electronics.
- Cloud-based orchestration platforms:Asset-light technology layers that coordinate fragmented carrier and processor networks enable mid-market retailer participation without captive infrastructure.
Industry Challenges
- Condition grading standardization:Absence of universal cosmetic and functional assessment protocols creates arbitrage disputes between retailers, 3PLs, and secondary market buyers.
- WMS integration complexity:Reverse-specific inventory states and disposition workflows require customization of forward-optimized warehouse management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Reverse Logistics Market |
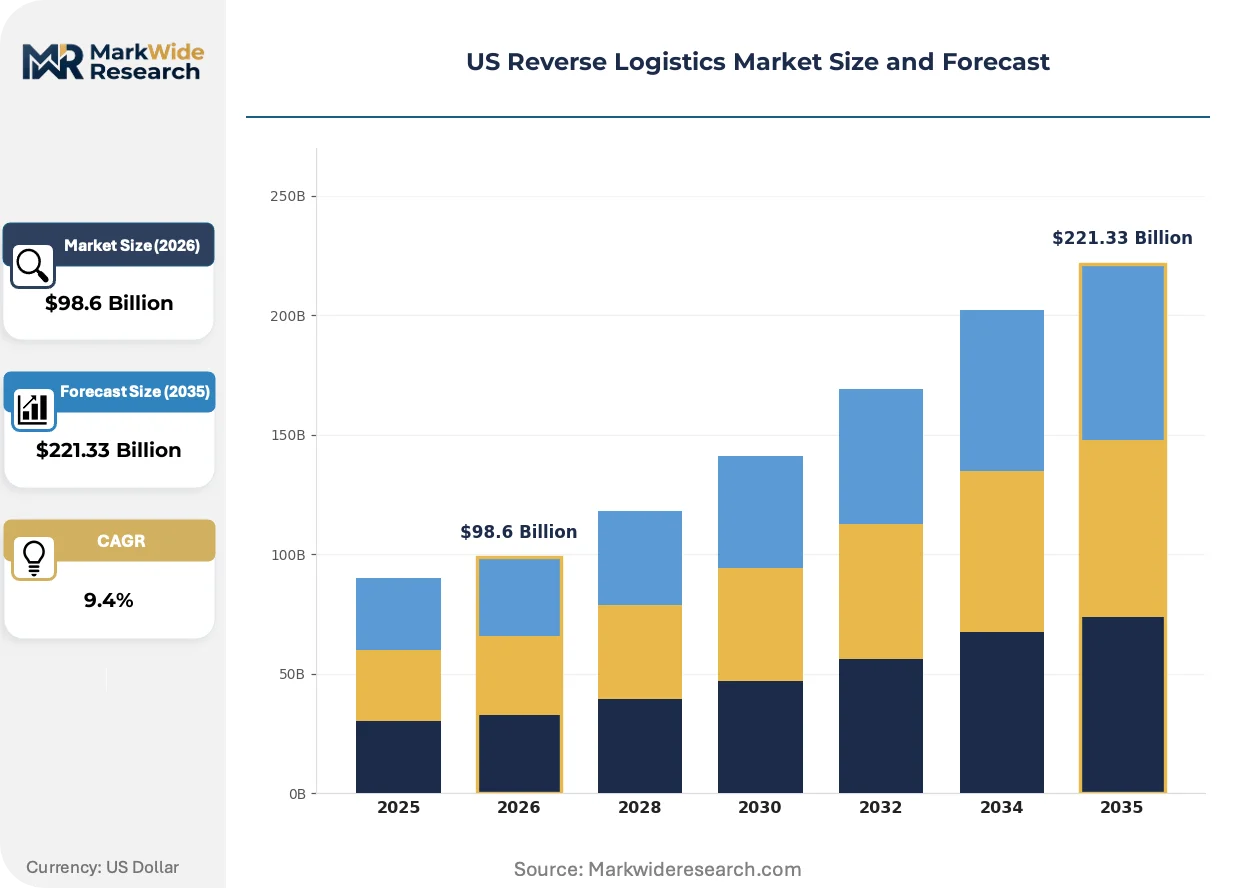
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $221.33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Returns Management, Remanufacturing, Repair Services, Recycling End User: Retail, E-Commerce, Electronics, Automotive Technology: Warehouse Management Systems, Blockchain, Cloud Solutions, IoT Distribution Channel: Direct Sales, Third-Party Logistics, Service Centers, Online Platforms |
| Companies Covered | United Parcel Service, Inc., FedEx Corporation, XPO Logistics, DHL Supply Chain, DB SCHENKER, Optoro Inc, ShipBob, Newgistics, Yusen Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Reverse Logistics Market Evolving Landscape
Digital thread technologies and policy mandates are converging to transform how returned goods are traced, valued, and reinserted into supply chains. Three developments are compressing legacy operational models.
Computer vision-based condition assessment is decomposing manual inspection bottlenecks in high-volume returns facilities. Major apparel retailers and electronics refurbishers are deploying multi-angle imaging systems that grade cosmetic damage and functional status within seconds per unit. This compression of labor-intensive triage is enabling same-day disposition decisions that previously required 48-72 hour holding periods.
SEC climate disclosure rules are mandating documented circularity metrics for public companies. The emerging requirement to report reverse logistics emissions and material recovery rates is forcing OEMs to contract dedicated audit trails or face shareholder litigation exposure. Electronics and battery manufacturers with California operational footprints are responding fastest, embedding blockchain-anchored provenance records into supplier agreements.
Buyers are unbundling after-sales service from product acquisition, treating returns as a discrete procurement category with separate vendor selection criteria. Retailers are disaggregating transportation, processing, and resale functions across specialized providers rather than defaulting to integrated 3PL packages. This fragmentation is most visible in Texas and California, where dedicated refurbishment marketplaces and secondary sales platforms are capturing margin pools that previously accrued to traditional logistics providers.
US Reverse Logistics Market Segmentation
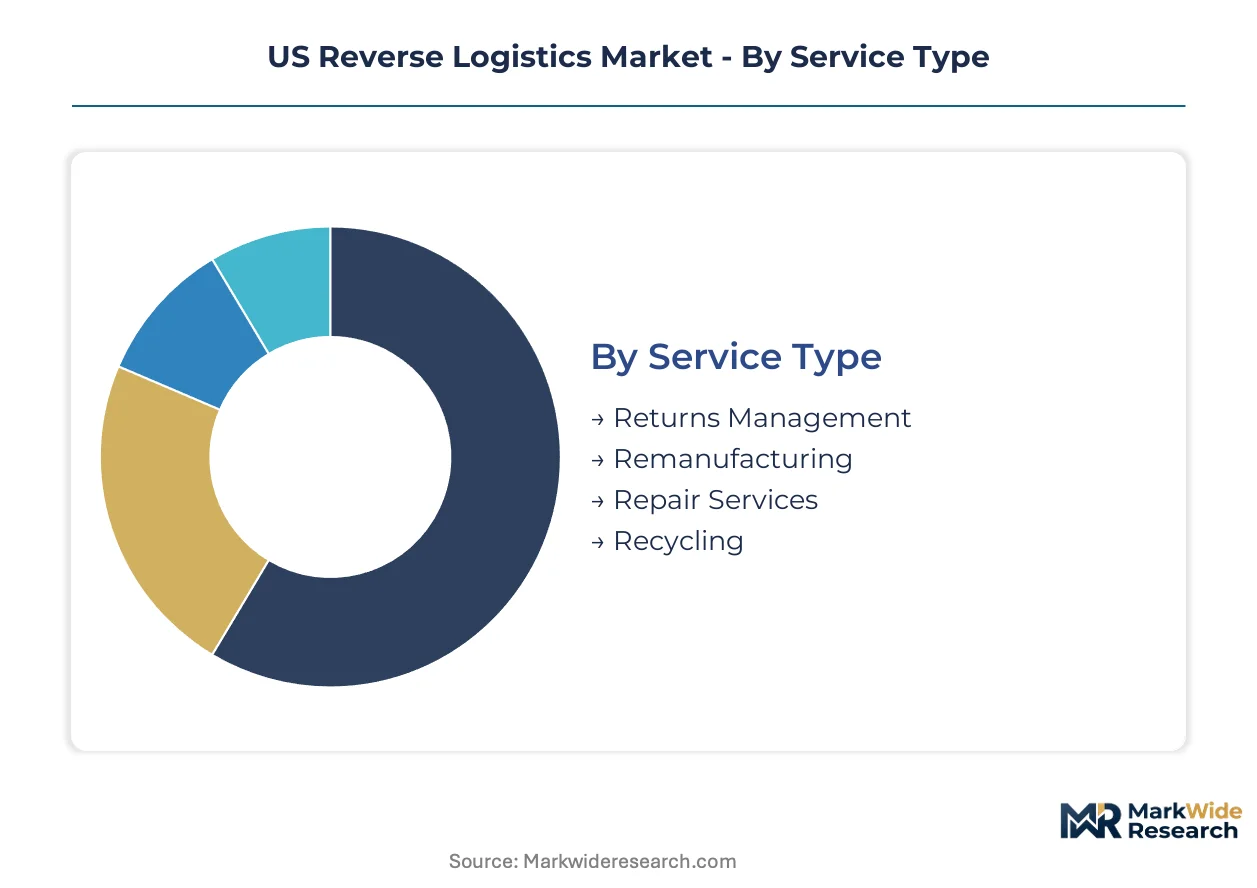
Reverse logistics segmentation reveals how regulatory pressure and channel complexity fragment service requirements across the value chain. EPA hazardous waste mandates and state extended producer responsibility laws create divergent compliance burdens that reshape technology and service investments.
Service Type:
EPA RCRA standards and California's electronics recycling mandates differentiate processing intensity across service tiers.
- Returns Management:Encompasses intake verification, condition grading, and disposition routing for e-commerce and retail channels. Demand concentrates in California and Texas metropolitan corridors where e-commerce return volumes sustain dedicated fulfillment nodes and OSHA warehouse safety protocols elevate labor cost structures.
- Remanufacturing:Involves component-level restoration to original specifications for automotive and electronics OEMs. Texas distribution hubs anchor capacity near Dallas-Fort Worth to capture cross-border refurbishment flows and serve automotive OEMs with captive reverse infrastructure.
- Repair Services:Warranty and post-warranty restoration for consumer electronics and automotive systems.
- Recycling:Material recovery under EPA lithium-ion battery and rare earth element purity thresholds.
Established volume favors Returns Management; emerging adoption favors Remanufacturing.
End User:
Channel-specific return rates and product lifecycles determine infrastructure scale and technology deployment priorities.
- Retail:Brick-and-mortar networks integrating omnichannel returns processing with forward fulfillment operations. Apparel and consumer electronics categories sustain elevated return rates that mandate in-store intake systems and centralized grading facilities in California distribution clusters.
- E-Commerce:Pure-play digital retailers with return rates exceeding physical retail benchmarks. Specialized last-mile reverse capacity concentrates in Texas and California where 3PLs anchor dedicated processing nodes for big-box retail clients.
- Electronics:OEMs and retailers managing end-of-life devices under EPA RCRA hazardous waste standards.
- Automotive:Parts remanufacturing and warranty returns governed by core exchange programs.
Current infrastructure investment clusters in E-Commerce; regulatory compliance spending tilts toward Electronics.
Technology:
Capital intensity and integration complexity separate deployed solutions from emerging platforms.
- Warehouse Management Systems:Reverse-optimized inventory tracking with disposition workflow customization. Cloud-based orchestration tools democratize scale for mid-market retailers without captive infrastructure, representing the steepest expansion trajectory as shippers outsource complexity.
- Blockchain:Provenance tracking for circularity certification and SEC climate disclosure compliance. Implementation cost barriers and interoperability gaps stall enterprise deployment despite California OEMs embedding blockchain-anchored records into supplier agreements.
- Cloud Solutions:Asset-light coordination platforms for fragmented carrier and processor networks.
- IoT:Real-time condition monitoring during transport and storage for high-value electronics.
Near-term deployment favors WMS platforms; audit trail requirements favor Blockchain pilots.
Distribution Channel:
Control over customer touchpoints and margin capture drives channel selection across end-user segments.
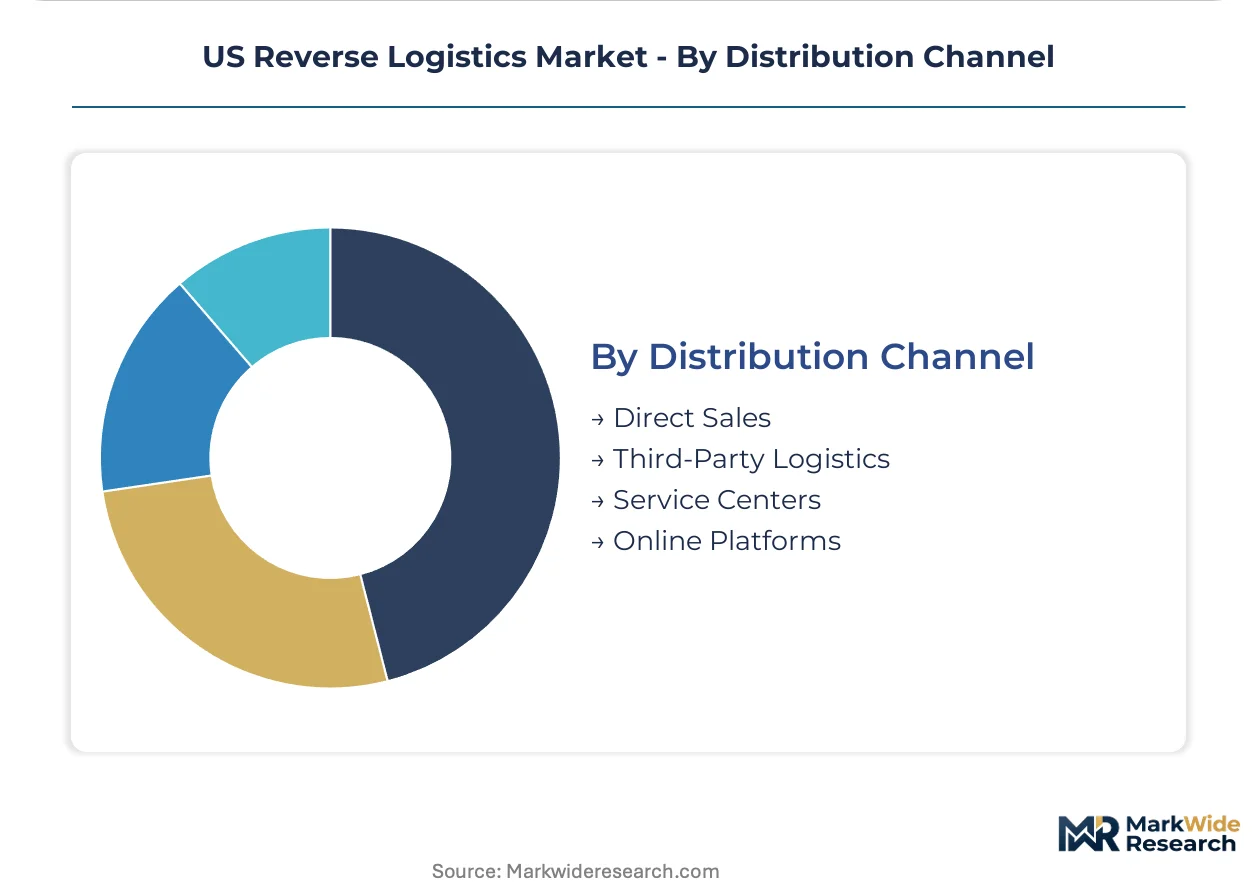
- Third-Party Logistics:Outsourced returns processing, transportation, and disposition coordination. Major 3PLs capture expanding margin pools as retailers disaggregate functions across specialized providers rather than defaulting to integrated packages.
- Direct Sales:Captive reverse infrastructure built by OEMs to comply with California and New York extended producer responsibility frameworks. OEMs face compliance penalties without dedicated channels, accelerating internal buildouts across apparel and consumer electronics.
- Service Centers:Authorized repair and refurbishment facilities for warranty and post-warranty work.
- Online Platforms:Digital marketplaces connecting returned goods to secondary buyers and refurbishment specialists.
Margin compression in traditional logistics favors Online Platforms; regulatory risk favors Direct Sales investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Return processing costs vary sharply across US sub-regions, with California and Texas buyers absorbing premium rates for compliance-heavy electronics handling while Southeast and Midwest markets prioritize cost-minimized apparel disposition.
California
Extended producer responsibility mandates and EPA RCRA hazardous waste standards drive the nation's strictest electronics recycling protocols. CalRecycle enforcement of lithium-ion battery recovery requirements forces OEMs to maintain captive processing facilities. The Inland Empire logistics corridor anchors dedicated returns nodes for consumer electronics and apparel e-tailers.
Texas
Cross-border refurbishment flows and automotive parts remanufacturing sustain dense reverse logistics infrastructure. Dallas-Fort Worth distribution clusters capture Mexico-originated core returns for transmission and engine component rebuilding. Houston's port complex enables hazardous waste export coordination for battery recyclers facing domestic landfill restrictions.
New York Metro
Pending state EPR legislation for textiles and packaging drives preemptive retailer infrastructure investment. OSHA warehouse safety mandates elevate labor costs beyond automation substitution rates in last-mile returns processing. New Jersey's Meadowlands distribution zone concentrates apparel grading facilities serving omnichannel retail networks.
Southeast
Florida and Georgia markets prioritize low-cost apparel disposition over compliance-heavy electronics handling. Savannah and Charleston port access supports export-oriented secondary market channels for graded consumer goods. Regional 3PLs compete on per-unit processing rates rather than specialized hazardous material certifications.
Midwest
Chicago's intermodal rail hub anchors returns consolidation for national retail distribution networks. Ohio and Michigan automotive corridors sustain core exchange programs for powertrain remanufacturing. Cold-weather logistics constraints limit year-round processing capacity expansion compared to Sun Belt alternatives.
US Reverse Logistics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with national parcel carriers and asset-heavy 3PLs controlling dense metropolitan corridors while technology platforms and regional processors capture fragmented mid-market volume. The upper tier combines owned transportation networks with dedicated returns facilities; the specialist tier competes on AI-driven disposition routing or single-channel expertise. Competitive moves concentrate on cloud-based orchestration partnerships and condition grading automation deployment.
Within the integrated logistics tier, FedEx Corporation and United Parcel Service, Inc. represent the scale-driven archetype through ground-air network density. XPO Logistics occupies a position in specialized last-mile reverse capacity for big-box retail. Optoro Inc exemplifies the technology-first platform model through AI-driven disposition routing systems.
| Leading Market Players |
|---|
| United Parcel Service, Inc. |
| FedEx Corporation |
| XPO Logistics |
| DHL Supply Chain |
| DB SCHENKER |
| Optoro Inc |
| ShipBob |
| Newgistics |
| Yusen Logistics |
| Others |
Value Network & Pricing Analysis
Cloud-based orchestration platforms substituting for captive warehouse networks are redrawing cost structures across metropolitan corridors while compressing margin pools for traditional asset-heavy providers.
Pricing Analysis
After-sales service revenue from refurbishment and resale channels drives lifetime value capture for reverse logistics providers. Three-tier pricing structure across premium certified, standard graded, and economy liquidation tiers separates electronics OEMs from apparel retailers and secondary market aggregators. Cost compression in last-mile intake is intensifying because OSHA warehouse safety mandates inflate labor headcount beyond automation substitution rates. E-commerce pure-plays exhibit the highest price sensitivity, while automotive OEMs with captive core exchange programs demonstrate the lowest.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific manufacturing clusters through Los Angeles and Long Beach port complexes shape total landed cost for returned electronics refurbishment. Domestic processing capacity draws from Mexico, China, and Vietnam for consumer electronics components, while rare earth element recovery rests on Canadian and Australian mining outputs. Single-source vulnerability in lithium-ion battery cell supply creates exposure for EPA RCRA-compliant recyclers. Distribution runs through third-party logistics networks that coordinate fragmented carrier and processor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reverse logistics penetration remains early-cycle as extended producer responsibility laws force first-mover OEMs to build dedicated returns infrastructure ahead of compliance deadlines.
For Market Incumbents: Compound network density advantages by anchoring specialized last-mile capacity in Dallas-Fort Worth and Inland Empire corridors where return volumes sustain scale. Invest in computer vision-based condition grading automation to offset OSHA-mandated labor cost inflation. Defend against AI-native disposition platforms by embedding cloud orchestration layers into existing warehouse management systems. For New Entrants and Emerging Players: Lead with asset-light technology platforms targeting mid-market apparel retailers lacking captive reverse infrastructure. White-space concentrates in cloud-based coordination of fragmented carrier networks for omnichannel returns. New York state EPR framework expansion creates immediate procurement opportunity for producer-funded collection infrastructure. Go-to-market should emphasize per-unit pricing transparency against integrated 3PL bundled rates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional processors holding hazardous waste certifications in California and Texas. Five-to-ten year viability hinges on regulatory enforcement continuity for circularity metrics and SEC climate disclosure rules. Acquisition targets should combine EPA RCRA-compliant facilities with AI-driven routing capabilities. Monitor CalRecycle enforcement actions as inflection indicator for compliance-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Disposition Routing Deployment | Machine learning models from Optoro reduce landfill diversion costs for electronics and apparel channels. |
| Extended Producer Responsibility Compliance Infrastructure | Captive reverse buildouts in California satisfy CalRecycle enforcement and preempt New York legislative expansion. |
| Computer Vision Condition Assessment Integration | Multi-angle imaging systems compress manual inspection bottlenecks to same-day disposition decisions. |
| Cloud-Based Orchestration Platform Partnership | ShipBob and similar platforms enable mid-market retailer participation without captive infrastructure investment. |
| Hazardous Waste Certification Expansion | EPA RCRA-compliant lithium-ion battery recovery capacity captures specialized processing demand from OEMs. |
Research Methodology
The analysis maps returns management, remanufacturing, repair services, and recycling segments, each validated through 3PL operations directors, OEM reverse logistics managers, EPA compliance officers, and secondary market platform executives. Primary interviews with FedEx, XPO Logistics, and Optoro functional heads combined with secondary validation from EPA RCRA enforcement records, CalRecycle facility databases, SEC supply chain disclosure filings, and OSHA warehouse incident reports. Bottom-up service-type demand modeling triangulated against top-down e-commerce return rate projections.
Consistency checks against Bureau of Transportation Statistics freight flows and Census Bureau retail sales data validated volume outputs across the projection horizon. Segmentation dimensions modeled include service type, end-user channel, technology deployment tier, and distribution channel structure. CAGRs derived from regression analysis of historical returns volume against e-commerce penetration curves, with EPA regulatory stringency indices and state EPR adoption timelines as scenario inputs.
Forecasts assume regulatory continuity in EPA RCRA enforcement and California extended producer responsibility regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
North America Road Freight Transport Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
North America Long-Haul Transport Market
Transportation & Logistics
Africa Cross Border Road Freight Transport Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Transportation Condensing Units Market
Transportation & Logistics
Asia-Pacific Customs Brokerage Market
Transportation & Logistics
Reverse Logistics Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
Freight Transport Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Fuel Management Systems (FMS) Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
Cable Car and Ropeways Market