
 Europe Courier, Express and Parcel (CEP) Market | 2026-2036
Europe Courier, Express and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Courier, Express and Parcel (CEP) Market Intelligence
Modular service bundling is repositioning buyer choice across the Europe Courier, Express and Parcel landscape, as shippers unbundle express guarantees from standard tracking and reassemble them into subscription logistics contracts. DHL Group leverages its intermodal ground-air network to sustain next-day coverage across the continent. La Poste Group anchors rural last-mile density through automated parcel locker deployments in secondary French cities.
Courier, Express and Parcel services constitute time-definite logistics offerings that integrate pickup, sortation, line-haul transport, and delivery within contracted service windows, typically measured in hours for express and days for standard products. The primary commercial purpose centers on reducing inventory carrying costs for manufacturers and enabling just-in-time replenishment for retailers. Same-day delivery commands premium positioning in dense urban corridors, while scheduled delivery captures margin pools from pharmaceutical and automotive contract logistics. Ground transport dominates volume flows, though air freight retains structural importance for cross-border express and perishable goods.
The EU Green Deal and its Fit for 55 framework, enforced by the European Commission and national transport regulators, mandate progressive CO2 reduction from commercial vehicle fleets and reshape diesel-to-electric transition timelines for parcel carriers. The EU AI Act, supervised by national market surveillance authorities, imposes algorithmic transparency requirements on automated route-optimization and dynamic pricing systems. Stakeholders must monitor how emissions compliance costs transfer into fuel surcharges and whether electric van deployment timelines align with charging infrastructure buildout across Eastern European member states.
Market Dynamics
The EU Green Deal's Fit for 55 framework is compressing diesel fleet replacement timelines while e-commerce fulfillment density is redrawing last-mile infrastructure requirements across the continent.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics shipping is pulling insulated parcel volumes into express networks. EMA's Good Distribution Practice mandates are tightening custody documentation requirements.
- EU Emissions Trading System extension:Road transport's inclusion in the carbon market is accelerating carrier investment in electric van fleets. The mechanism creates compliance-driven demand for route-optimization software.
- Rhine-Ruhr multimodal consolidation:Benelux-Northern France corridor freight is concentrating through Duisburg and Rotterdam hubs. Intermodal rail connections are absorbing long-haul parcel volumes from pure trucking.
Market Restraints
- Charging infrastructure asymmetry:Eastern European member states lag Western deployment of high-capacity depot charging. Poland and Romania electric van penetration remains constrained by grid upgrade timelines.
- Last-mile labor cost escalation:Driver availability tightens in Germany and France as gig-economy reclassification debates intensify. Collective bargaining coverage in the sector is expanding wage floor pressure.
- Air freight slot scarcity:Peak-season belly-hold capacity constraints at Frankfurt and Paris-Charles de Gaulle limit cross-border express scaling. Freighter lease rates are compressing margin on premium products.
Strategic Opportunities
- Secondary city locker density:Automated parcel machine deployment in Spain and Italy remains below Northern European penetration. Infrastructure subsidy programs in Portugal are creating deployment incentives.
- Reverse logistics monetization:E-commerce return flows are absorbing underutilized line-haul capacity on backhauls. Fashion and electronics verticals are piloting consolidated return consolidation centers.
- CSRD supply-chain disclosure:Corporate Sustainability Reporting Directive requirements are pulling Scope 3 emissions tracking into carrier selection criteria. Early compliance positioning offers differentiation leverage.
Industry Challenges
- Algorithmic audit readiness:EU AI Act route-optimization transparency requirements are forcing documentation of automated pricing and dispatch logic. Technical compliance teams are scarce relative to implementation deadlines.
- Depot electrification capex:Grid connection upgrades and on-site battery storage are absorbing disproportionate capital allocation. Financing structures for fleet-and-infrastructure bundles remain underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Courier, Express and Parcel (CEP) Market |
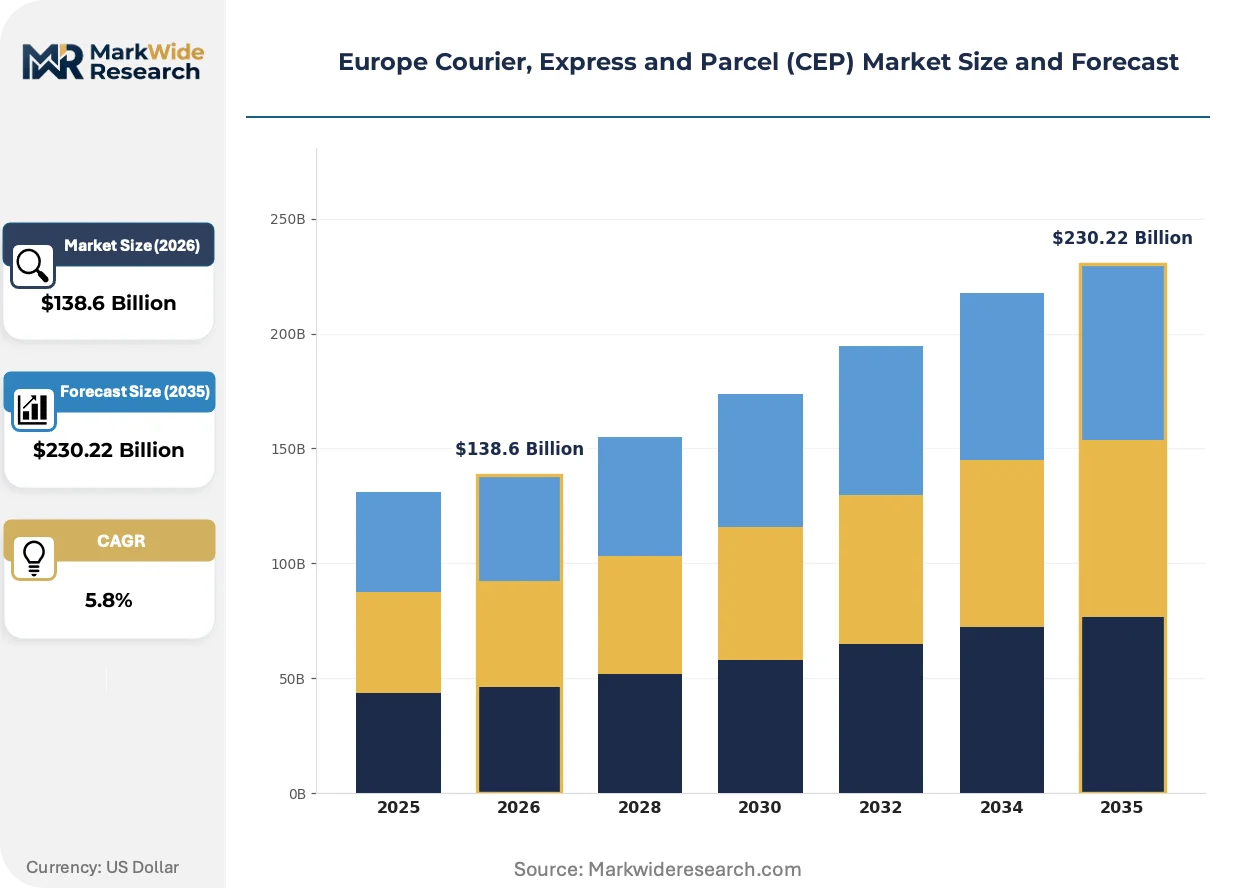
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $230.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Standard Delivery Delivery Mode: Ground, Air, International, Local Customer Type: B2B, B2C, E-commerce, Retail Package Type: Parcels, Documents, Pallets, Bulk |
| Companies Covered | DHL Group, FedEx Corporation, United Parcel Service Inc., Deutsche Post AG, La Poste Group, International Distributions Services, Koninklijke PostNL, InPost, DSV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Courier, Express and Parcel (CEP) Market Strategic Shifts & Innovations
Digital freight matching and predictive capacity platforms are restructuring how parcel flows align with available transport assets across European networks.
Dynamic route-optimization engines incorporating real-time traffic, weather, and delivery density data are absorbing dispatcher decision-making. Mid-sized carriers in the Netherlands and Belgium are adopting these systems fastest. The technology is compressing headcount in traditional transport planning functions while raising service consistency metrics.
EU AI Act algorithmic transparency mandates are forcing documentation of automated dispatch and surge-pricing logic. Carriers must maintain explainable decision trails for market surveillance authorities. The requirement is most acute for same-day and instant delivery segments where dynamic pricing density is highest.
Subscription logistics contracts are displacing transactional shipment purchasing among mid-market retailers. Fixed-monthly fee structures bundle standard delivery with expedited upgrade entitlements. German omnichannel retailers are piloting these arrangements most aggressively, locking in volume commitments against capacity guarantees.
Europe Courier, Express and Parcel (CEP) Market Segmentation
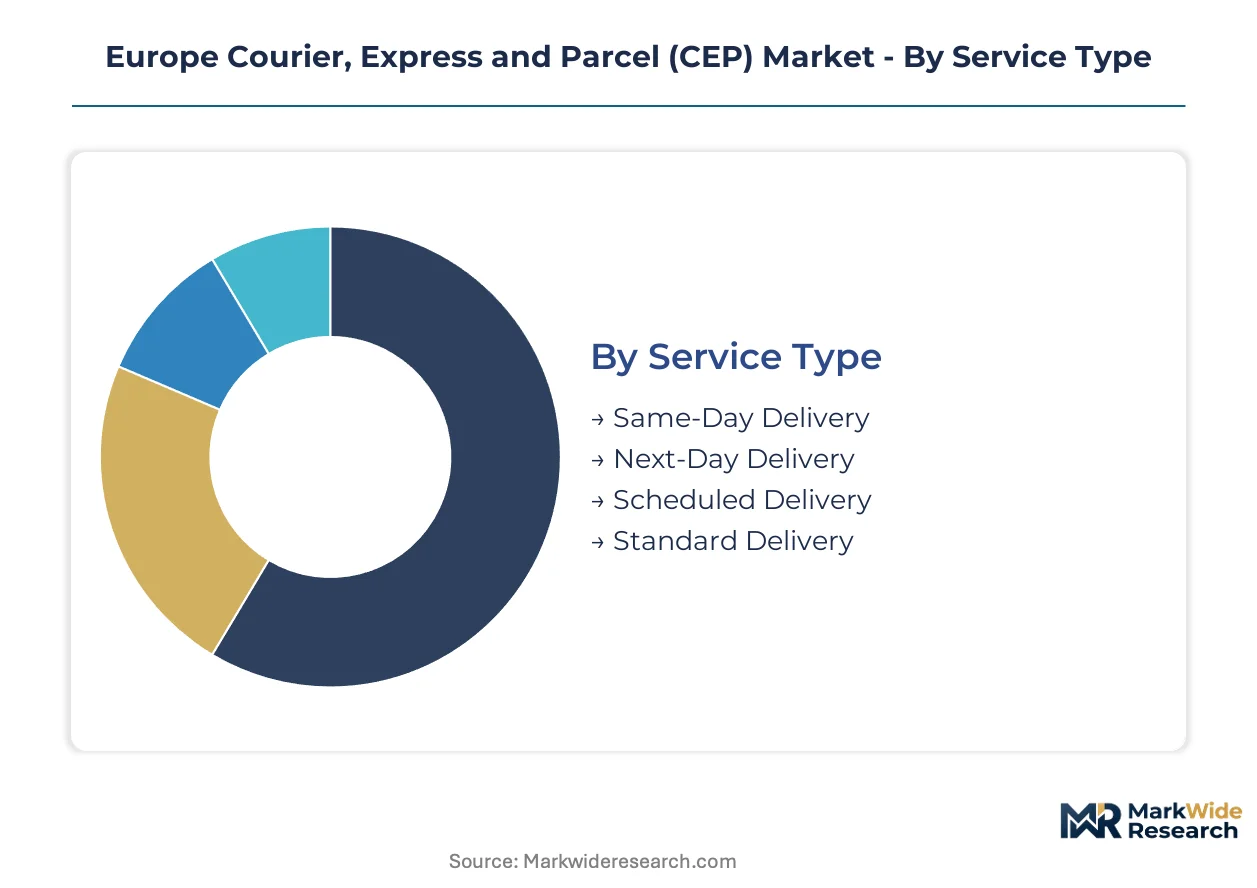
Service differentiation across the Europe Courier, Express and Parcel market determines carrier profitability and infrastructure investment priorities. Shippers select service tiers based on inventory carrying cost trade-offs against transportation spend, with pharmaceutical and automotive verticals driving premium segment adoption.
Service Type:
Speed guarantees command the primary buyer decision hierarchy, with contracted delivery windows determining network design and pricing architecture.
- Same-Day Delivery:Time-critical shipments completing pickup-to-delivery cycles within single operating hours. German urban corridors and Benelux dense zones absorb the highest volumes as omnichannel retailers compete on fulfillment speed.
- Next-Day Delivery:Guaranteed 24-hour delivery windows supported by integrated ground-air networks and overnight sortation hubs. Cross-border express flows between France, Germany, and Italy concentrate demand here, with EMA cold-chain mandates pulling pharmaceutical volumes into this tier.
- Scheduled Delivery:Appointment-based arrival windows optimizing receiver availability and reducing redelivery costs. Automotive parts suppliers and healthcare distributors in the Rhine-Ruhr corridor favor this predictability for just-in-line replenishment.
- Standard Delivery:Non-guaranteed multi-day service maximizing line-haul efficiency and minimizing per-unit cost. Eastern European e-commerce penetration and price-sensitive B2C shippers in Spain and Italy sustain volume concentration.
Next-Day Delivery leads on scale; Same-Day Delivery leads on momentum.
Delivery Mode:
Modal choice reflects distance-cost optimization and emissions compliance pressure under the EU Green Deal.
- Ground:Road-based transport dominating intra-European parcel flows through diesel and electric van fleets. Germany's autobahn network and France's motorway density enable overnight line-haul coverage across 500-kilometer radii.
- Air:Belly-hold and freighter capacity reserved for cross-border express and perishable goods. Frankfurt and Paris-Charles de Gaulle slot scarcity constrains peak-season scaling for premium products.
- International:Cross-border customs-cleared movements requiring bonded warehouse infrastructure and transit documentation. Benelux hub concentration facilitates EU single-market frictionless flows.
- Local:Urban last-mile density operations from micro-fulfillment depots and automated locker networks. Secondary French and Italian cities show underpenetrated deployment opportunity.
Ground transport anchors volume throughput; electric fleet conversion is accelerating fastest in local operations.
Customer Type:
Contract structure and volume predictability separate commercial buyer segments.
- B2B:Recurring contractual relationships with manufacturers and distributors prioritizing reliability over speed. Automotive and industrial supply chains in Germany generate consistent palletized parcel demand.
- B2C:Individual residential deliveries with high first-attempt failure rates and return flow complexity. Subscription logistics contracts are displacing transactional purchasing among mid-market retailers.
- E-commerce:Platform-aggregated shipment volumes with seasonal peaks and reverse logistics requirements. Fashion and electronics verticals pilot consolidated return centers.
- Retail:Store-based fulfillment and click-and-collect integration for omnichannel networks. Automated parcel locker deployments support this segment in secondary Spanish and Portuguese cities.
B2B contracts deliver margin stability; e-commerce volumes are climbing the fastest.
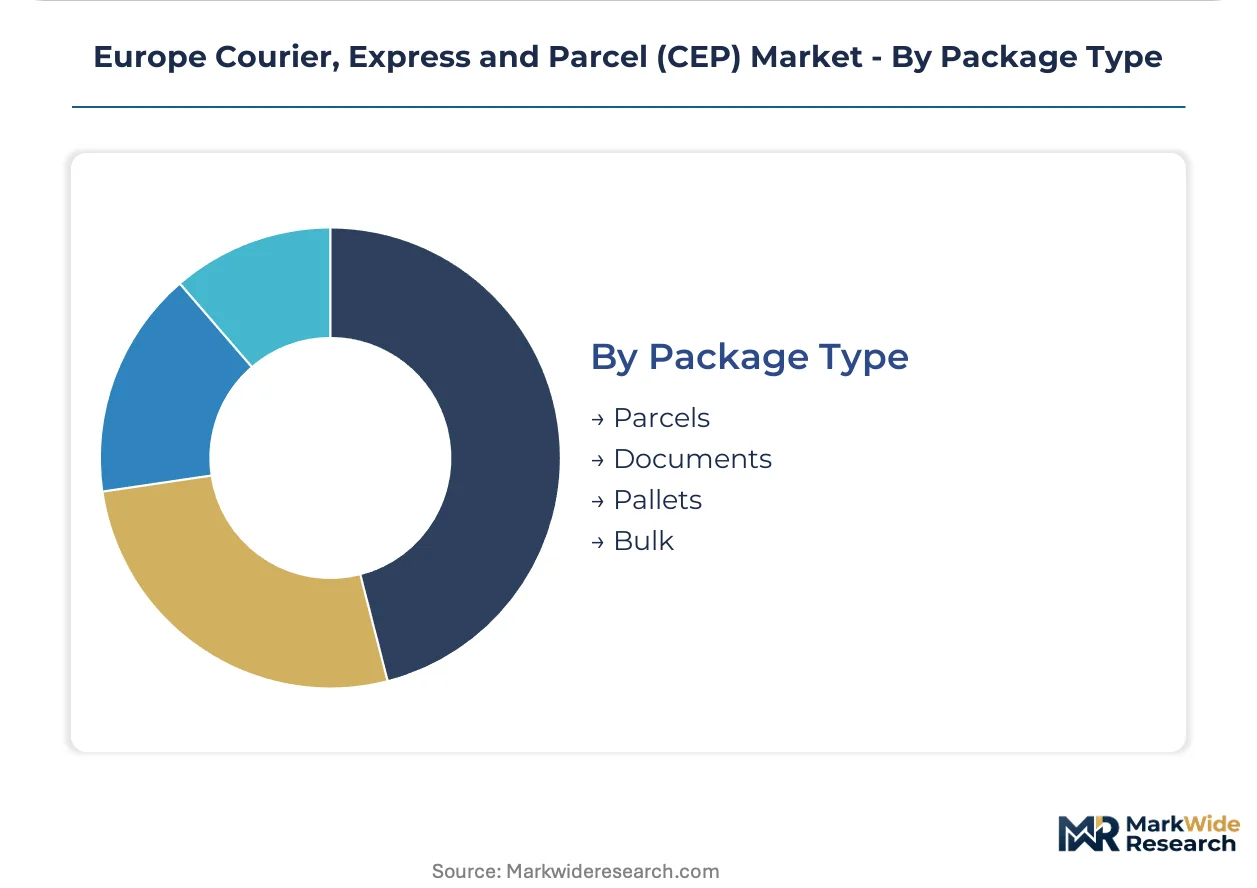
Package Type:
Physical characteristics dictate handling infrastructure and vehicle configuration.
- Parcels:Standardized carton shipments comprising the majority of e-commerce and retail volumes. Sortation hub automation in Rotterdam and Duisburg processes these at highest throughput.
- Documents:Time-sensitive paper-based shipments declining as digital substitution advances. Legal and financial services in London and Frankfurt sustain residual demand.
- Pallets:Unitized freight requiring forklift-capable vehicles and dock-height infrastructure. B2B industrial flows between Germany and Poland concentrate here.
- Bulk:Non-containerized loose freight absorbing backhaul capacity on underutilized line-haul routes. Reverse logistics monetization targets this segment for return consolidation.
Parcels dominate revenue contribution; palletized B2B flows show steadiest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern parcel logistics trace their European origins to the 19th-century postal monopolies of Germany and France, where state-run networks first established time-definite delivery standards that later deregulated into competitive courier markets.
Germany
Automotive just-in-time supply chains and pharmaceutical cold-chain mandates from the EMA drive express volumes. The EU Green Deal's Fit for 55 framework accelerates electric van fleet mandates through KBA vehicle-type approvals. The Rhine-Ruhr corridor anchors continental parcel consolidation, with Duisburg's trimodal terminal absorbing Benelux-Northern France freight flows.
France
Omnichannel retail fulfillment and rural last-mile locker deployment sustain network density. CSRD supply-chain disclosure requirements reshape carrier selection criteria for corporate shippers. Secondary cities in Occitanie and Nouvelle-Aquitaine show underpenetrated automated parcel machine opportunity against saturated Paris basin coverage.
United Kingdom
Cross-border e-commerce return flows and fashion vertical consolidation centers absorb underutilized line-haul capacity. Post-Brexit customs documentation requirements complicate EU frictionless movements. The Midlands logistics triangle around Birmingham and Leicester concentrates sortation hub investment for domestic next-day coverage.
Netherlands
Port-centric distribution and Rotterdam's automated container handling integrate maritime parcel flows with European road networks. REACH chemical transport regulations influence hazardous materials handling infrastructure. The Randstad urban agglomeration enables same-day delivery density that secondary Dutch markets cannot replicate.
Italy
Pharmaceutical temperature-controlled shipments from Lombardy biotech clusters pull insulated express volumes. ANSM national regulatory oversight aligns with EMA Good Distribution Practice mandates. Northern industrial zones around Milan and Bologna contrast with underdeveloped locker penetration in Southern regions.
Europe Courier, Express and Parcel (CEP) Market Key Industry Players
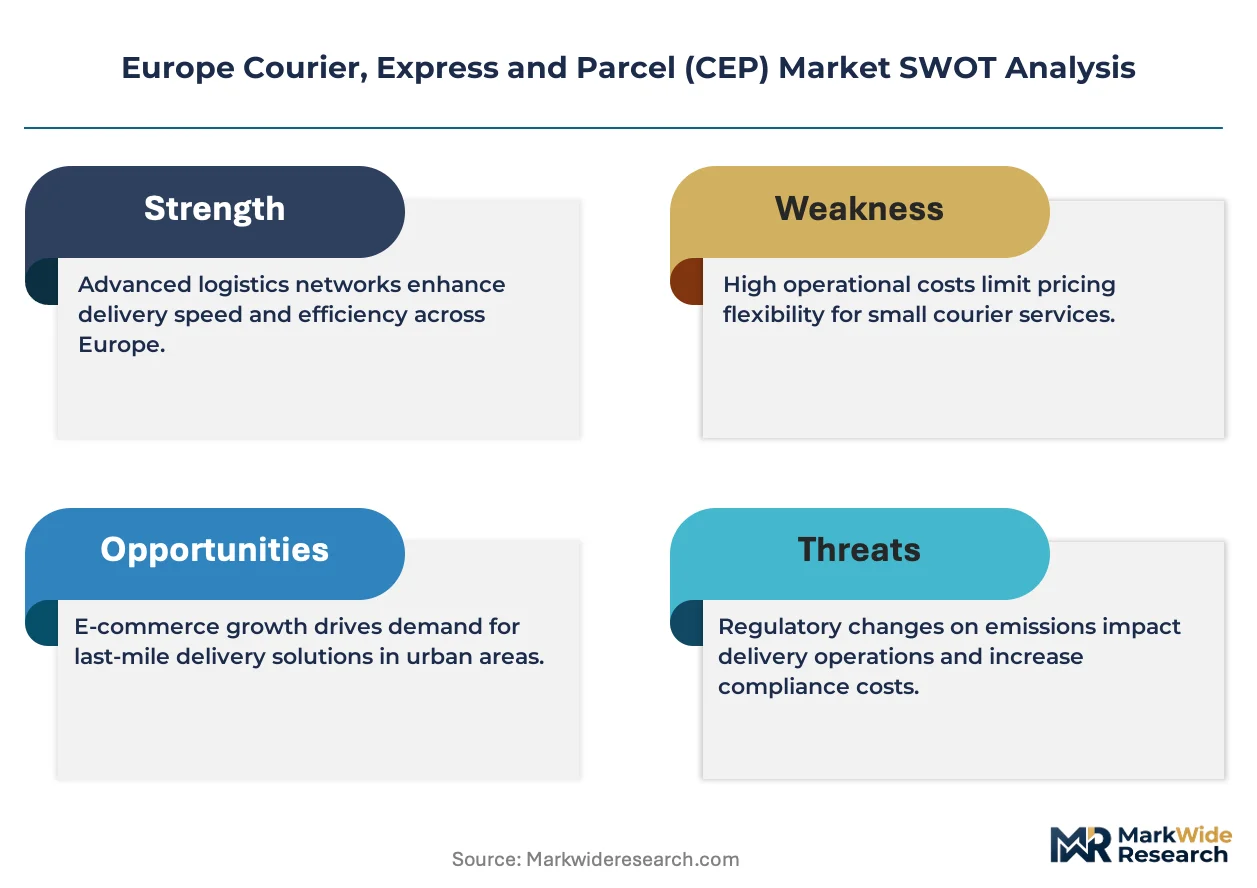
The competitive structure tilts toward integrated pan-European networks over fragmented national operators. Consolidation pressure intensifies as emissions compliance costs and depot electrification capex demands favor scale. Three archetypes dominate: postal incumbents with legacy last-mile density, global integrators with intermodal ground-air assets, and specialized e-commerce logistics platforms. Capacity expansion through automated sortation hubs and strategic partnerships for charging infrastructure sharing represent the primary competitive vectors.
Within the postal incumbent tier, DHL Group and La Poste Group exemplify legacy network leverage, while United Parcel Service Inc. occupies a position as a global integrator with European hub concentration. These entities anchor the competitive spectrum between public service obligations and commercial express margins.
| Leading Market Players |
|---|
| DHL Group |
| FedEx Corporation |
| United Parcel Service Inc. |
| Deutsche Post AG |
| La Poste Group |
| International Distributions Services |
| Koninklijke PostNL |
| InPost |
| DSV |
| Others |
Cost & Logistics Intelligence
Horizontal consolidation across last-mile networks anchors pricing power for parcel carriers while compressing margins for fragmented regional operators. DHL Group's intermodal ground-air integration and La Poste Group's automated locker density in France demonstrate how scale concentration translates into subscription logistics contract premiums. The EU Green Deal's emissions trading system feeds compliance costs into fuel surcharges, reshaping carrier procurement toward electric fleet bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates same-day delivery guarantees from next-day express and deferred standard service. Price differentiation hinges on speed certification and volume scale commitments, with pharmaceutical cold-chain shippers absorbing premium tiers for EMA-compliant custody documentation. Cost compression in standard delivery intensifies as e-commerce platforms consolidate shipment purchasing into fixed-fee subscriptions. B2C residential deliveries exhibit highest price sensitivity, while automotive just-in-time contracts prioritize reliability over unit cost.
Supply Chain Analysis
Electric van fleet procurement rests on battery cell supply from South Korean and Chinese manufacturers, with charging infrastructure hardware drawing from German and Dutch industrial producers. Sortation hub automation depends on conveyor systems and optical character recognition modules sourced from German engineering specialists. Single-source vulnerability concentrates in lithium-ion cell supply chains subject to EU Critical Raw Materials Act restrictions. Distribution runs through Rhine-Ruhr multimodal terminals connecting Benelux ports with Northern France road networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Courier, Express and Parcel market functions as a regulatory compounder where EU Green Deal emissions mandates and CSRD disclosure requirements continuously expand compliance-driven service demand.
For Market Incumbents: To counter gig-economy reclassification threats in Germany and France, secure driver availability through collective bargaining coverage expansion and automate dispatcher functions with EU AI Act-compliant route-optimization engines. Deploy depot electrification capex through fleet-and-infrastructure bundled financing structures. Scale automated parcel locker density in underpenetrated Spanish and Italian secondary cities to defend last-mile margin position. For New Entrants and Emerging Players: Algorithmic transparency platforms for automated pricing audit trails offer technology-first entry into compliance services gaps left by incumbent technical team shortages. Target reverse logistics monetization in fashion and electronics verticals where consolidated return centers absorb underutilized line-haul capacity. Pursue infrastructure subsidy programs in Portugal for automated parcel machine deployment as the primary go-to-market anchor. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized Benelux and Netherlands carriers because emissions compliance costs and depot electrification demands favor scale concentration over fragmented national operators. Five-to-ten year viability hinges on electric fleet conversion timelines aligning with charging infrastructure buildout. Watch Poland and Romania grid upgrade completion rates as the inflection signal for Eastern European penetration viability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | EU Green Deal Fit for 55 mandates compress diesel replacement timelines across German and French carrier operations. |
| Automated Sortation Hub Expansion | Rotterdam and Duisburg trimodal terminals absorb Benelux-Northern France freight consolidation volumes. |
| Subscription Logistics Contracts | German omnichannel retailers pilot fixed-fee structures bundling standard delivery with expedited upgrade entitlements. |
| Reverse Logistics Center Buildout | Fashion and electronics verticals consolidate return flows to monetize underutilized line-haul backhaul capacity. |
| Charging Infrastructure Partnership | Depot electrification capex sharing reduces grid connection upgrade burdens for mid-sized carriers in Eastern Europe. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, transport planning managers, e-commerce logistics procurement leads, and EU regulatory compliance officers with secondary validation from customs trade data, KBA vehicle registration filings, EMA Good Distribution Practice guidance documents, and national emissions trading system registries. Bottom-up carrier capacity modeling and top-down e-commerce shipment volume estimates were triangulated against Rhine-Ruhr corridor freight flow data.
Comparable-period anchoring linked historical express volume growth patterns to projected e-commerce penetration curves across the analysis window. Segmentation dimensions modeled include service type speed tier, delivery mode modal choice, customer type contract structure, and package type physical characteristics, with pharmaceutical cold-chain and automotive just-in-time verticals treated as distinct demand drivers. CAGRs were derived from logistic curve fitting to adoption saturation limits, incorporating electric van fleet deployment schedules and charging infrastructure buildout timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Emissions Trading System price volatility and Eastern European grid upgrade completion rates. Assumptions reflect documented carrier investment commitments and regulatory implementation timelines. A small set of triggers—air freight slot scarcity at Frankfurt and Paris-Charles de Gaulle, gig-economy reclassification court rulings, and lithium-ion cell supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Automotive Logistics Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Freight Transport Management Market
Logistics and Shipping
China International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Sea Freight Forwarding Market
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia-Pacific FMCG Logistics Market
Logistics and Shipping
Big Data in Logistics Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Thailand Cold Chain Logistics Market
Logistics and Shipping
Real-Time Inventory-in-Transit Positioning Platforms Market
Logistics and Shipping
Russia 3PL Market