
 Canada Freight and Logistics Market | 2026-2036
Canada Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Freight and Logistics Market Outlook
E-commerce retailers is redrawing freight demand patterns across Canada, pulling volume away from traditional bulk manufacturing shippers. TFI International leverages its asset-light brokerage model to capture fragmented last-mile demand. Canadian National Railway Company anchors intermodal capacity along the Vancouver-Prince Rupert corridor. Cargojet dominates domestic air cargo networks, sustaining overnight delivery commitments to northern and remote communities.
Canada freight and logistics encompasses the physical movement, storage, and coordination of goods across road, rail, air, and marine infrastructure, typically measured by tonne-kilometres and warehouse throughput capacity. The sector functions as the circulatory system for Canadian trade, with temperature-controlled transport and cross-border customs facilitation serving as critical technical parameters. Road freight transportation leads service type revenue due to deregulated trucking rates and flexible routing, while supply chain management solutions are expanding fastest as shippers outsource inventory optimization. Rail delivery mode retains structural importance for bulk commodities and transcontinental container flows, though margin pools increasingly shift toward technology-enabled freight forwarding platforms.
Transport Canada enforces commercial vehicle safety standards and hours-of-service regulations that directly constrain fleet productivity and driver availability. The Canadian Transportation Agency adjudicates rate disputes and access rights, shaping competitive dynamics between rail and trucking modes. Environment and Climate Change Canada applies emissions standards under the Clean Fuel Regulations, elevating compliance costs for diesel-intensive operations. Stakeholders must weigh electrification capital commitments against regulatory trajectory uncertainty and cross-border policy divergence with the United States.
Market Dynamics
Transport Canada's Electronic Logging Device mandate is compressing fleet utilization rates and forcing carriers to reconfigure driver scheduling and asset deployment across long-haul corridors. This regulatory inflection point is accelerating consolidation among mid-sized trucking operators while amplifying demand for digital freight-matching platforms.
Growth Catalysts
- E-commerce warehouse expansion:Retailers are enlarging fulfillment footprints across Ontario and British Columbia, generating sustained demand for last-mile capacity and regional distribution infrastructure.
- Clean Fuel Regulations:Environment and Climate Change Canada's emissions standards are accelerating fleet turnover toward lower-carbon alternatives, creating retrofit and replacement cycles across diesel-intensive operations.
- Cold chain concentration:Temperature-controlled logistics demand is clustering in the Greater Toronto Area and Calgary corridor, pulling specialized reefer capacity and pharmaceutical-grade storage investment toward these nodes.
Market Restraints
- Driver availability constraints:Hours-of-service regulations enforced by Transport Canada are structurally limiting fleet productivity and expanding wage pressure across long-haul segments.
- Fuel cost volatility:Diesel price exposure remains unhedged for most asset-heavy carriers, compressing margins during supply shocks and geopolitical disruptions.
- Cross-border policy divergence:Regulatory misalignment with United States hours-of-service and emissions standards creates operational friction for transcontinental operators.
Strategic Opportunities
- Northern remote delivery:Air cargo networks serving isolated communities present underpenetrated white space for specialized operators with overnight reliability capabilities.
- Intermodal rail-truck convergence:Vancouver-Prince Rupert corridor expansion offers modal shift potential for containerized imports seeking port diversification away from US West Coast congestion.
- Supply chain outsourcing:Inventory optimization services represent expanding addressable market as manufacturers divest in-house logistics functions to third-party platforms.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require costly retrofitting to achieve real-time visibility and regulatory compliance reporting.
- Electrification capex burden:Battery-electric and hydrogen fuel cell vehicle procurement demands substantial upfront capital with uncertain residual value and charging infrastructure availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Freight and Logistics Market |
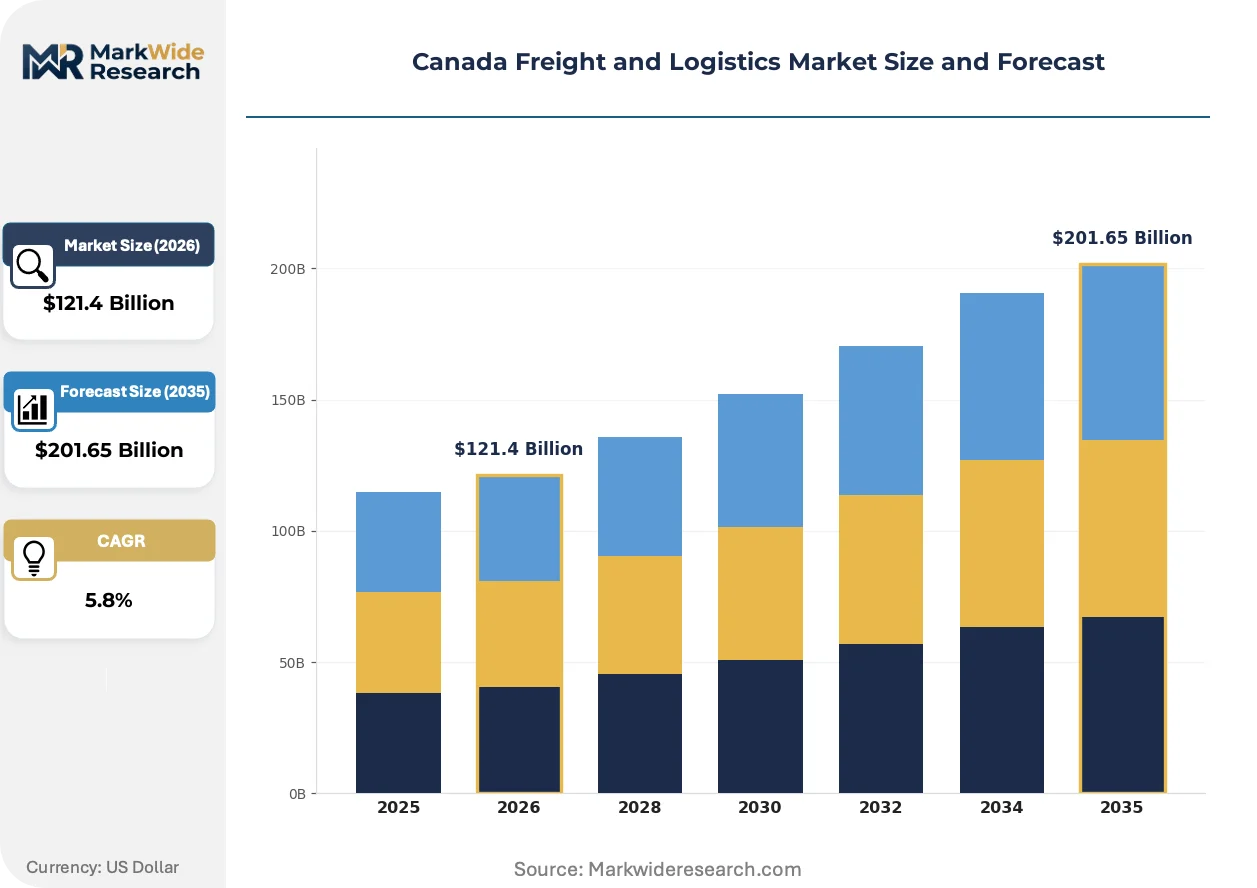
| Market Size in 2026 | $121.4 Billion |
| Market Size in 2035 | $201.65 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Supply Chain Management End User: Manufacturers, Retailers, E-commerce, Distributors Delivery Mode: Road, Rail, Air, Sea Technology: Fleet Management, IoT Solutions, Blockchain, Automation |
| Companies Covered | TFI International, Canadian National Railway Company, Canadian Pacific Kansas City, Canada Post Corporation, Cargojet, Mullen Group, Day and Ross, Canada Cartage, Challenger Motor Freight, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Freight and Logistics Market Strategic Shifts
Digital freight platforms are rewiring how Canadian shorters source capacity, compressing procurement cycles and disintermediating traditional broker relationships. Automation and data analytics are penetrating warehouse operations and cross-border customs processes simultaneously.
Autonomous truck platooning technology is supplanting conventional convoy operations on designated highway corridors. Major retailers and bulk commodity shippers are piloting linked-vehicle formations between distribution centers. This technology is compressing labor requirements per tonne-kilometre while raising cybersecurity and liability protocols for fleet operators.
Transport Canada's commercial vehicle safety standards are tightening enforcement protocols around driver fatigue monitoring and vehicle maintenance records. Carriers face expanded documentation requirements and audit frequencies. Long-haul trucking segments are responding by accelerating investment in integrated electronic logging and predictive maintenance systems.
Shippers are unbundling transportation from warehousing and customs brokerage, selecting specialized providers for each leg rather than single-source 3PL contracts. This fragmentation is disrupting traditional full-service logistics relationships. E-commerce verticals in southern Ontario are most visibly adopting componentized procurement, driving demand for API-connected freight marketplaces.
Canada Freight and Logistics Market Segmentation
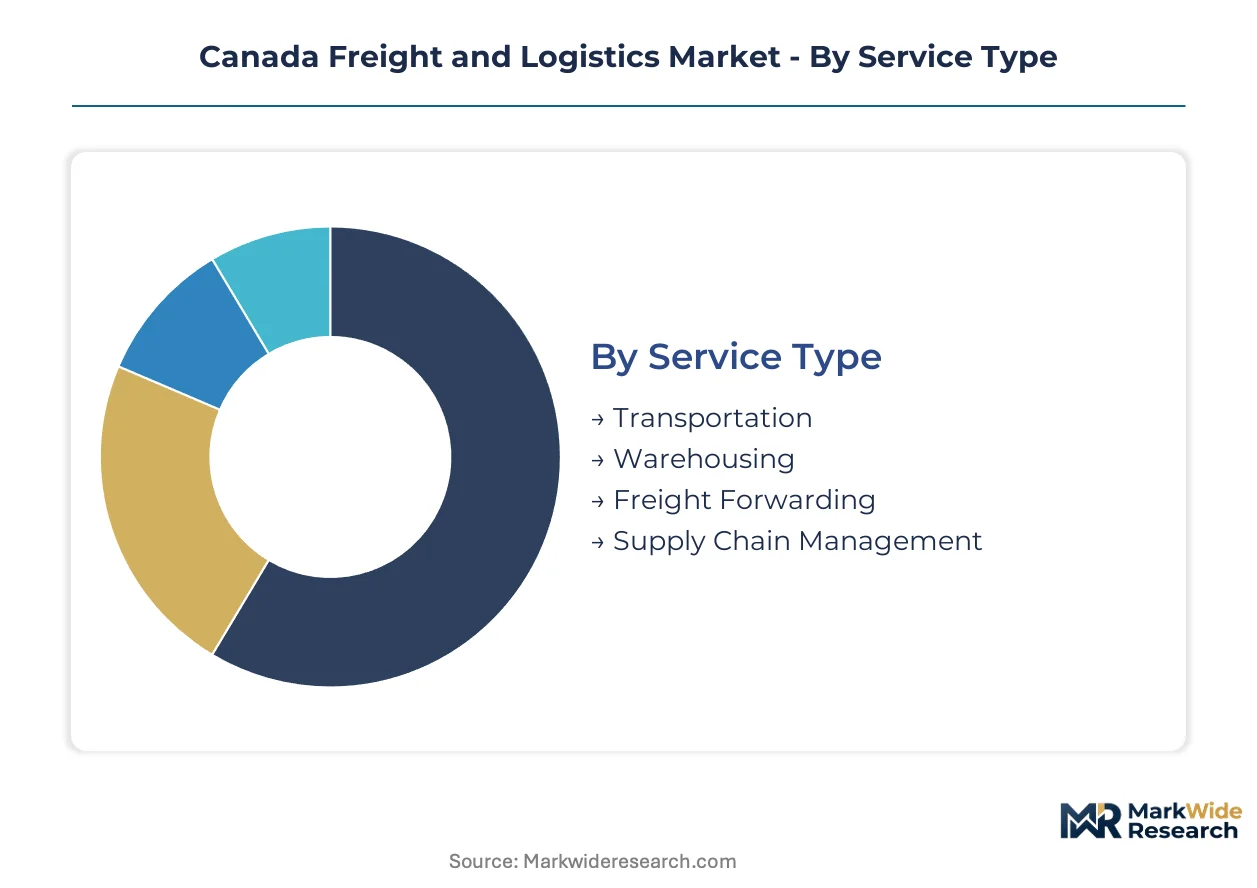
Canada freight and logistics segmentation reveals how modal substitution and service unbundling are fragmenting traditional revenue pools. Shippers increasingly decouple transportation from warehousing, forcing providers to defend position within narrower capability bands.
Service Type:
Substitution pressure from digital freight platforms is most acute in brokerage-heavy segments where asset-light competitors erode incumbent margins.
- Transportation:Asset-heavy trucking and specialized hauling operations move goods across road, rail, air, and marine infrastructure. Demand concentrates in Ontario-Quebec corridors serving automotive and retail distribution networks, with Transport Canada's ELD mandate compressing fleet utilization and amplifying driver wage pressure.
- Supply Chain Management:End-to-end inventory optimization and network design services encompassing demand forecasting, supplier coordination, and distribution strategy. E-commerce retailers across Greater Toronto Area and Vancouver are outsourcing these functions to third-party platforms, pulling spend away from in-house logistics departments.
- Warehousing:Temperature-controlled and ambient storage facilities with value-added fulfillment services.
- Freight Forwarding:Cross-border customs brokerage and international shipment coordination.
Transportation retains volume leadership; Supply Chain Management holds the steepest expansion curve.
End User:
Cost tier stratification separates high-velocity e-commerce shippers from bulk commodity manufacturers with divergent service requirements.
- E-commerce:Direct-to-consumer retailers demanding same-day and next-day fulfillment with high SKU fragmentation. Volume clusters in Ontario and British Columbia warehouse nodes, with cold chain requirements for grocery and pharmaceutical verticals driving specialized reefer investment.
- Manufacturers:Industrial producers of automotive parts, raw materials, and finished goods requiring scheduled, high-volume movements. Just-in-time assembly plants in Windsor-Oshawa corridor and resource extraction sites in Alberta depend on reliable inbound material flows.
- Retailers:Brick-and-mortar chains replenishing regional distribution centers.
- Distributors:Wholesale intermediaries consolidating shipments for fragmented downstream customers.
Manufacturers retain volume leadership; E-commerce holds the steepest expansion curve.
Delivery Mode:
Application-specific routing constraints determine modal selection, with port congestion and border clearance times driving corridor-level substitution.
- Road:Flexible trucking networks serving last-mile and regional haulage with deregulated rate structures. Deregulated routing flexibility and door-to-door service capabilities concentrate demand in Ontario-Quebec manufacturing belts and prairie agricultural distribution.
- Rail:Bulk commodity and intermodal container movements across transcontinental networks. Canadian National Railway Company anchors capacity along Vancouver-Prince Rupert corridor, with port diversification away from US West Coast congestion pulling import volume northward.
- Air:Time-critical and high-value shipments including pharmaceuticals and electronics.
- Sea:International container and bulk commodity movements through Pacific and Atlantic gateways.
Road retains volume leadership; Rail holds the steepest expansion curve.
Technology:
Customer type segmentation separates enterprise shippers with integrated technology stacks from mid-market operators purchasing point solutions.
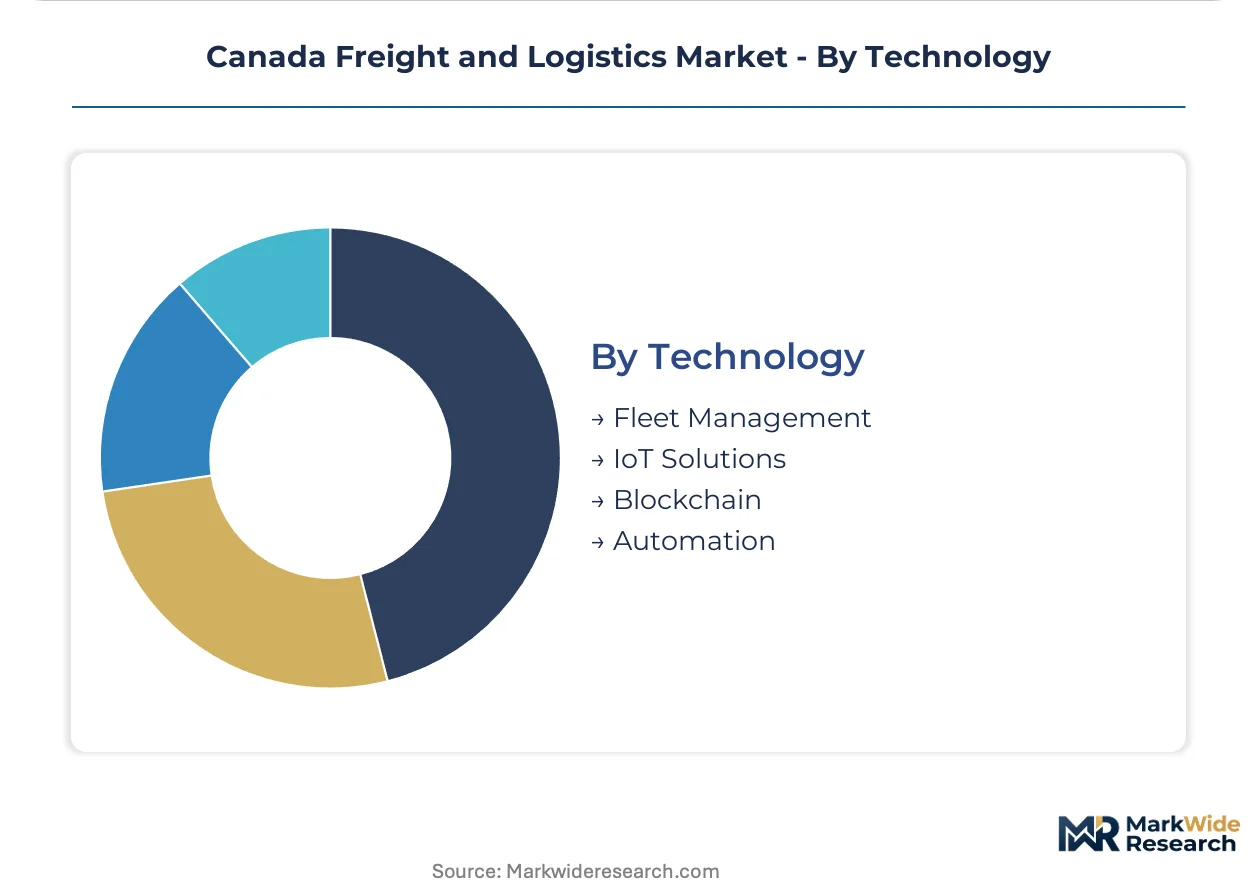
- Fleet Management:Telematics, route optimization, and driver compliance systems for asset-heavy carriers. Real-time visibility platforms and predictive maintenance algorithms concentrate demand among long-haul trucking fleets responding to Transport Canada documentation requirements.
- IoT Solutions:Sensor networks for cargo condition monitoring and warehouse automation. Temperature-sensitive pharmaceutical and food shipments across Greater Toronto Area and Calgary corridor drive cold chain tracking deployment.
- Automation:Robotic warehouse systems and autonomous yard operations.
- Blockchain:Distributed ledger applications for cross-border documentation and provenance verification.
Fleet Management retains volume leadership; IoT Solutions holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Vancouver anchors Canada's Pacific gateway position, handling containerized imports destined for Ontario and prairie distribution centers. Transcontinental rail corridors connect this maritime infrastructure to the Greater Toronto Area, creating a bipolar freight geography.
Ontario
Automotive assembly plants in Windsor-Oshawa and e-commerce fulfillment centers in Peel Region drive concentrated trucking demand. Transport Canada enforces hours-of-service regulations that compress fleet utilization across the 401 corridor. The Greater Toronto Area hosts the country's densest cold chain logistics cluster, with pharmaceutical-grade warehouses expanding near Pearson International Airport.
Quebec
Montreal's port diversification strategy pulls container volume from US East Coast alternatives, supporting intermodal rail growth. The Canadian Transportation Agency adjudicates rate disputes affecting Quebec-Ontario freight flows. Quebec City and Montreal anchor specialized reefer capacity serving European seafood and agricultural export markets.
Alberta
Oil sands extraction and petrochemical processing in the Edmonton-Calgary corridor generate bulk commodity movements by rail and pipeline. Environment and Climate Change Canada applies Clean Fuel Regulations elevating compliance costs for diesel-intensive operations. Calgary's logistics park development concentrates temperature-controlled storage investment for prairie agricultural distribution.
British Columbia
Vancouver-Prince Rupert port competition diversifies Asian import routing away from US West Coast congestion. The Canadian Transportation Agency shapes competitive dynamics between rail and trucking modes serving interior markets. E-commerce warehouse expansion in the Lower Mainland generates sustained last-mile capacity demand for cross-border e-commerce fulfillment.
Prairie Provinces
Saskatchewan and Manitoba grain handling networks move bulk commodities toward Vancouver and Thunder Bay export terminals. Transport Canada's Electronic Logging Device mandate forces carriers to reconfigure driver scheduling across sparse population corridors. Regina and Winnipeg serve as consolidation nodes for agricultural inputs and machinery distribution to remote farming communities.
Canada Freight and Logistics Market Competitive Environment
Listed leaders compete with private specialists across asset ownership models, creating a tiered competitive structure. Asset-heavy rail operators and trucking fleets dominate volume-based segments, while asset-light brokerage platforms capture fragmented last-mile demand. Three archetypes define competitive positioning: integrated multimodal operators, specialized cold chain providers, and digital freight-matching platforms. Consolidation accelerates through mid-sized trucking acquisitions, while technology partnerships reshape customer procurement patterns.
Within the integrated multimodal tier, TFI International exemplifies the asset-light brokerage approach to fragmented demand, while Canadian National Railway Company anchors transcontinental intermodal capacity. Cargojet occupies a distinctive position in domestic air cargo networks serving northern remote communities. These three entities represent divergent strategic bets on modal specialization versus service breadth.
| Leading Market Players |
|---|
| TFI International |
| Canadian National Railway Company |
| Canadian Pacific Kansas City |
| Canada Post Corporation |
| Cargojet |
| Mullen Group |
| Day and Ross |
| Canada Cartage |
| Challenger Motor Freight |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with tier-one e-commerce shippers lock in dedicated fleet access and insulate carriers from spot-rate volatility across the Ontario-Quebec corridor. Transport Canada's ELD mandate compresses utilization rates and pushes contract pricing toward cost-plus structures that pass through diesel exposure.
Pricing Analysis
Volume-discount tiering structures separate enterprise shippers committing to annual minimums from mid-market operators purchasing transactional capacity. Three-tier pricing stratifies across premium guaranteed-service, standard scheduled-delivery, and economy deferred tiers. Cost compression in the economy tier intensifies because digital freight platforms disintermediate traditional broker markups. Small and mid-sized manufacturers exhibit highest price sensitivity, while pharmaceutical and grocery verticals prioritize reliability over rate negotiation.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive and electronics manufacturing, while agricultural and resource extraction sectors maintain strategic stockpiles against seasonal disruption. Equipment manufacturing rests on China, USA, and Germany for chassis, powertrain, and telematics components. Diesel fuel, steel, and semiconductor-based fleet management systems constitute critical input dependencies. Single-source vulnerability concentrates in advanced driver-assistance sensors and electronic logging hardware. Distribution runs through hub-and-spoke networks anchored at Toronto, Calgary, and Vancouver with spoke extensions to northern remote communities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against asset-light digital platforms that are substituting traditional brokerage relationships with API-connected freight marketplaces.
For Market Incumbents: Fortify driver retention through guaranteed mileage programs and predictive maintenance investment that minimizes downtime penalties under Transport Canada documentation requirements. Deepen backward integration into specialized reefer equipment manufacturing to capture margin pools in pharmaceutical-grade cold chain segments. Consolidate mid-sized trucking acquisitions before ELD compliance costs force distressed exits. For New Entrants and Emerging Players: Lead with overnight reliability capabilities targeting northern remote communities where Cargojet's dominance leaves white space for specialized regional operators. Penetrate the Calgary corridor temperature-controlled storage segment where agricultural distribution demand outpaces specialized reefer capacity expansion. Pursue direct contracts with prairie grain elevator networks bypassing established broker relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors asset-light technology platforms with embedded fleet management software over pure-play trucking operators. Long-term viability hinges on electrification capital deployment timing and charging infrastructure access rights. Target acquisition archetype: mid-sized carriers with dense Ontario-Quebec lane coverage and compliant ELD infrastructure already deployed. Watch Transport Canada zero-emission vehicle mandate announcements as fleet turnover inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Battery-electric vehicle procurement with charging infrastructure developers reduces compliance exposure under Environment and Climate Change Canada regulations. |
| Intermodal Rail Convergence | Vancouver-Prince Rupert corridor capacity expansion captures containerized import volume diversifying from US West Coast port congestion. |
| Digital Freight Platform Integration | API-connected marketplace deployment disintermediates traditional broker relationships and compresses procurement cycles for e-commerce shippers. |
| Cold Chain Specialization | Pharmaceutical-grade warehouse investment near Pearson International Airport anchors temperature-controlled logistics expansion in Greater Toronto Area. |
| Driver Retention Program | Guaranteed mileage and predictive maintenance investment mitigates wage pressure from Transport Canada hours-of-service constraints. |
Study Parameters
Desk research of Transport Canada regulatory filings, Canadian Transportation Agency rate dispute records, and Environment and Climate Change Canada emissions standards preceded structured interviews with fleet operations directors, third-party logistics procurement managers, intermodal rail planners, and cold chain facility developers. Secondary validation drew from carrier financial disclosures, port authority throughput statistics, and customs trade data. Bottom-up carrier capacity modeling and top-down macroeconomic trade flow analysis were triangulated against segment-level revenue estimates.
Variance decomposition across service type, delivery mode, end-user vertical, and technology adoption rate shaped the analytical framework over the projection horizon. Modeled dimensions encompassed transportation versus supply chain management spend splits, road-rail-air modal substitution elasticities, and fleet management versus IoT solution technology penetration. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs included ELD mandate compliance cost trajectories and Clean Fuel Regulations retrofit cycle assumptions.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce warehouse expansion or cross-border trade policy stability would require recalibration. Forecasts reflect documented assumptions around driver availability trends and diesel price volatility ranges. Revision becomes warranted when Transport Canada zero-emission vehicle mandate timing or US-Canada regulatory divergence crosses thresholds that alter fleet investment payback calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
Turkey Cold Chain Logistics Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Fleet of Containers Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Saudi Arabia Freight and Logistics Market