
 China EV Battery Pack Market | 2026-2036
China EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
China EV Battery Pack Market Insights
China's dual carbon goals and MIIT battery passport requirements are rebalancing the cost-of-entry calculus for new pack assemblers. CATL leverages its vertical cell-to-pack integration to sustain margin leadership across premium passenger vehicle programs. BYD anchors the mid-market through in-house blade battery production that spans vehicle and energy storage applications. Gotion High-Tech competes on LFP specialization, securing supply positions with European and domestic OEMs seeking lower-cobalt chemistries.
An EV battery pack integrates cells, modules, thermal management systems, and battery management electronics into a sealed enclosure rated for IP67 or higher ingress protection, typically operating at 300-800 volts DC to deliver traction energy to electric drivetrains. The assembly serves as both an energy reservoir and a structural chassis element in modern skateboard platforms. Lithium iron phosphate technology leads volume shipments due to thermal stability and nickel-cobalt-free cost structures, while solid-state chemistries attract R&D capital for next-generation energy density targets. Passenger vehicle packs dominate value pools, though energy storage applications are expanding fastest as grid-scale deployments absorb retired automotive cells and new stationary capacity.
MIIT sets pack energy density floors and recycling recovery rate mandates that force design-for-disassembly investments, while GB standards govern electrical safety and crashworthiness testing protocols that shape product development timelines. SAMR enforces market access rules through compulsory certification that filters out subscale producers. Stakeholders must monitor how NMPA-aligned battery traceability requirements and provincial NEV subsidy taper schedules reshape procurement priorities across OEM and fleet operator segments.
Market Dynamics
Cell-to-pack architectures are compressing module assembly steps across Jiangsu and Guangdong manufacturing bases, forcing legacy module suppliers to retool or exit as OEMs consolidate procurement tiers.
Growth Catalysts
- NEV Credit Mandates:MIIT's tightening credit requirements compel domestic OEMs to expand premium electric SUV battery pack procurement, accelerating demand for high-energy-density assemblies.
- Lithium Iron Phosphate Chemistry:Nickel-cobalt-free cost structures and thermal stability properties drive LFP adoption across passenger vehicle and energy storage applications.
- Guangdong Manufacturing Clusters:Concentrated cell production and pack assembly capabilities in the Pearl River Delta reduce logistics costs and supplier qualification timelines.
Market Restraints
- Lithium Carbonate Volatility:Raw material price swings compress pack assembler margins and destabilize long-term supply contracts with cathode suppliers.
- Cell Supplier Concentration:Domestic cell production concentrates among vertically integrated producers, limiting independent pack assemblers' bargaining power and input security.
- GB Standard Compliance Burden:Compulsory electrical safety and crashworthiness testing protocols extend product development timelines and raise certification costs for new entrants.
Strategic Opportunities
- Second-Life Stationary Storage:Retired automotive cells from Jiangsu passenger vehicle packs feed grid-scale deployments, creating circular revenue streams for pack service providers.
- Dual Carbon Goals Alignment:Provincial green procurement incentives favor pack assemblers with verified low-carbon production footprints and renewable-powered manufacturing.
- Cell-to-Chassis Integration:Convergence of structural battery enclosures with vehicle platform engineering opens design partnerships with OEM skateboard platform teams.
Industry Challenges
- Thermal Management Engineering Talent:Shortage of specialists in liquid cooling loop design and simulation slows pack development cycles for mid-tier assemblers.
- Battery Passport Traceability Systems:NMPA-aligned data infrastructure requirements demand capital investment in blockchain-enabled supply chain tracking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China EV Battery Pack Market |
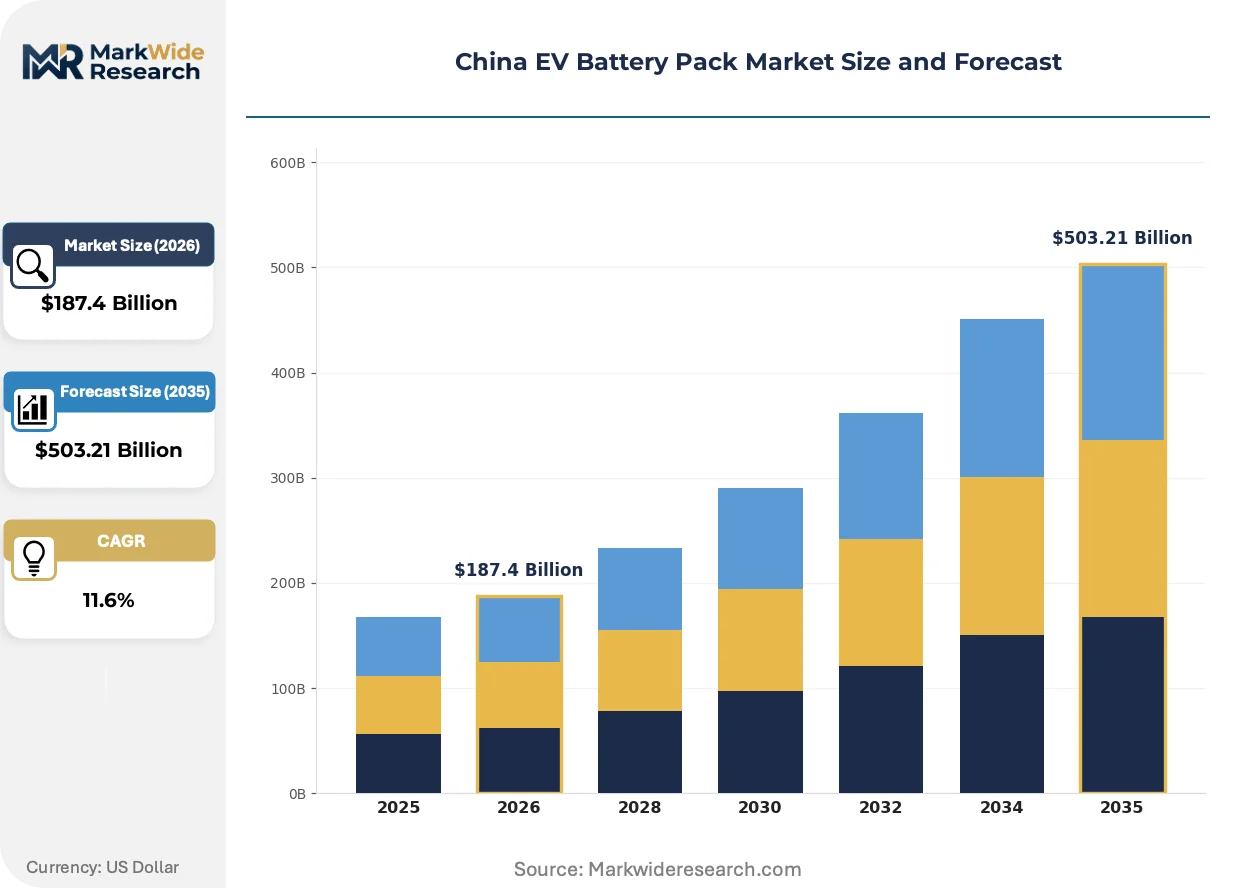
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $503.21 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-Ion, Solid State, Nickel-Cobalt Manganese, Lithium Iron Phosphate Product Type: Passenger Vehicle, Commercial Vehicle, Two-Wheeler, Energy Storage End User: OEMs, Fleet Operators, Individual Consumers, Public Transport Capacity: Below 20 kWh, 20-40 kWh, 40-60 kWh, Above 60 kWh |
| Companies Covered | CATL, BYD, CALB, Gotion High-Tech, EVE Energy, SVOLT Energy Technology, Sunwoda EVB, Farasis Energy, LEAPENERGY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China EV Battery Pack Market Trends and Innovations
Pack architecture simplification and software-defined thermal control are compressing hardware differentiation while elevating battery management system capabilities as the primary value layer.
Cell-to-pack technology is modularizing the traditional three-tier assembly hierarchy by eliminating module housings and busbar interconnections. Premium passenger vehicle OEMs are adopting these architectures fastest, cutting pack weight and part count. The shift is modularizing supplier relationships as cell producers assume direct pack integration responsibilities previously held by independent module assemblers.
MIIT battery passport requirements are mandating full lifecycle traceability from raw material extraction through recycling recovery. Pack assemblers must deploy digital twin infrastructure to document cell origin, manufacturing parameters, and state-of-health degradation. Premium SUV programs face the steepest compliance investment as they source heterogeneous cell chemistries across multiple suppliers.
Fleet operators are consolidating battery pack procurement through direct long-term supply agreements rather than OEM-mediated purchasing. Commercial vehicle and taxi fleet managers in Jiangsu and Guangdong are negotiating service-level contracts encompassing pack performance guarantees and residual value recovery. This channel compression is most visible in urban logistics electrification programs where total cost of ownership calculations dominate supplier selection.
China EV Battery Pack Market Segmentation
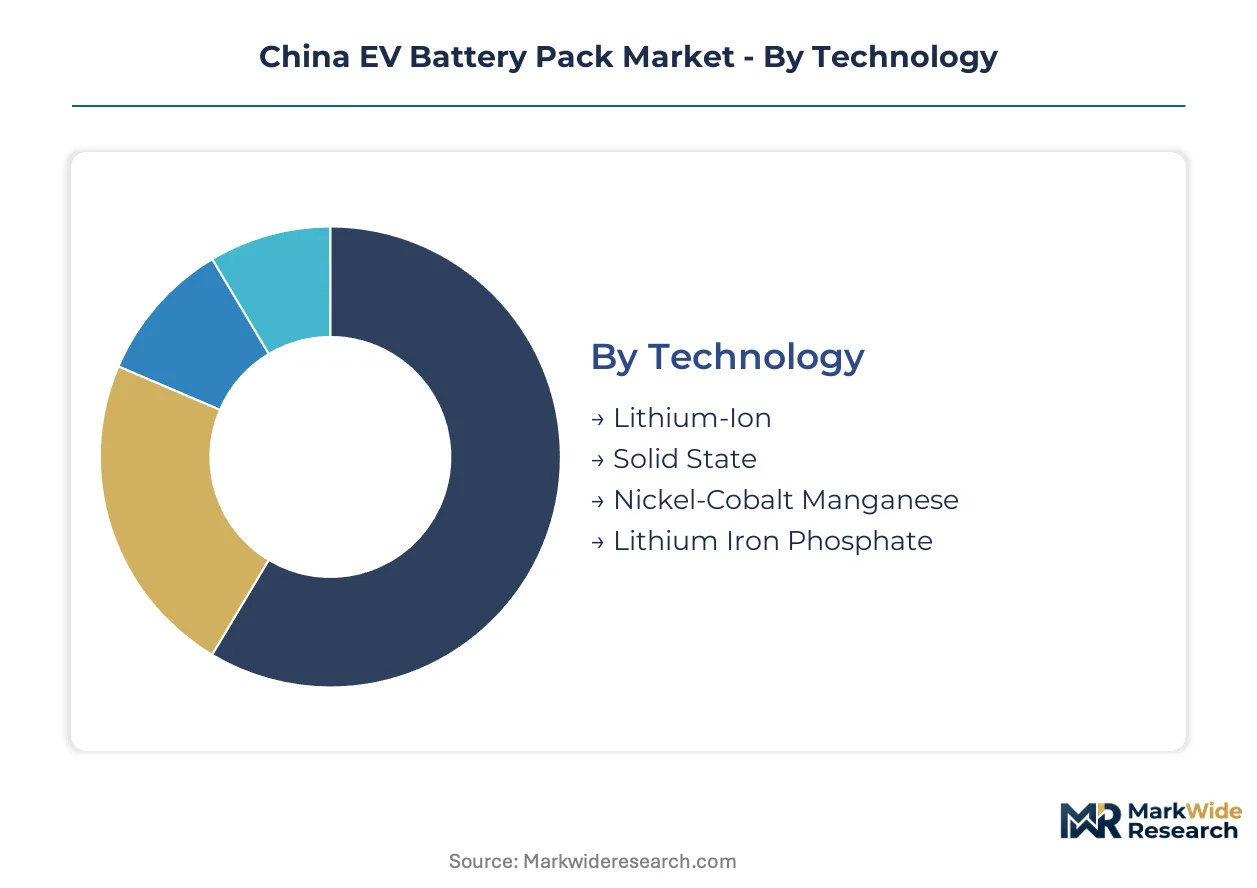
Segmentation in the China EV battery pack market reveals how procurement priorities diverge across chemistry choices, vehicle platforms, and customer scale. Each dimension carries distinct margin profiles and regulatory exposure that shape assembler strategy.
Technology:
Cost sensitivity and thermal stability requirements separate buyers across chemistry types.
- Lithium Iron Phosphate:Nickel-cobalt-free cathode composition delivers superior thermal stability and lower bill-of-materials cost. Demand concentrates in Jiangsu manufacturing clusters for mid-market passenger vehicles where MIIT energy density floors still permit LFP qualification.
- Solid State:Ceramic or polymer electrolyte architectures replace liquid electrolytes to enable higher energy density and reduced fire risk. Development programs target premium electric SUVs in Guangdong where OEMs absorb prototype costs for next-generation platform positioning.
- Lithium-Ion:Conventional graphite-anode systems with liquid electrolytes dominate installed base.
- Nickel-Cobalt Manganese:High-nickel layered oxide cathodes maximize gravimetric energy density for range-critical applications.
Volume sits with Lithium Iron Phosphate; growth tilts toward Solid State.
Product Type:
Application scale determines pack architecture complexity and service model requirements.
- Passenger Vehicle:Integrated skateboard platforms demand structural enclosures with 300-800V DC operation and IP67 ingress protection. Procurement concentrates with domestic OEMs expanding premium electric SUV lineages under tightening NEV credit mandates.
- Energy Storage:Stationary systems repurpose retired automotive cells alongside new LFP capacity for grid-scale deployments. Jiangsu and Guangdong utility procurements absorb second-life supply from passenger vehicle retirements.
- Commercial Vehicle:Heavy-duty platforms require thermal management for high-cycle-duty operation.
- Two-Wheeler:Swappable pack formats dominate urban mobility fleets.
Passenger Vehicle commands current revenue pools; Energy Storage climbs the fastest.
End User:
Procurement sophistication and contract structure distinguish customer categories.
- OEMs:Vertically integrated vehicle manufacturers specify pack performance through platform engineering partnerships. CATL and BYD anchor supply positions through direct cell-to-pack integration agreements.
- Fleet Operators:Commercial vehicle and taxi fleet managers negotiate service-level contracts with performance guarantees and residual value recovery clauses. Direct procurement bypasses OEM markups in Jiangsu urban logistics programs.
- Individual Consumers:Replacement and upgrade demand follows vehicle ownership cycles.
- Public Transport:Municipal procurement favors standardized specifications and local content requirements.
OEMs dominate unit volume; Fleet Operators gain share fastest.
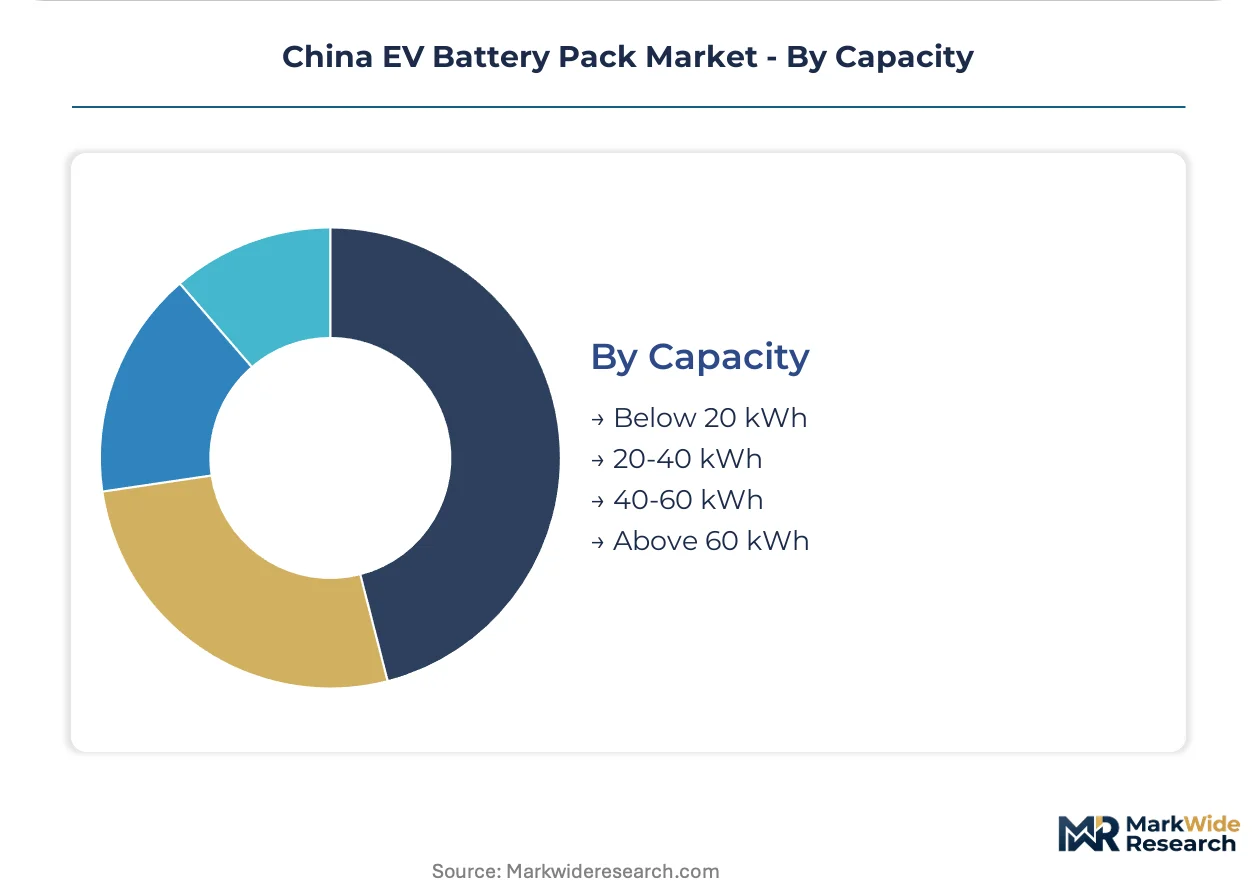
Capacity:
Energy content tiers align with vehicle class segmentation and duty cycle intensity.
- Above 60 kWh:High-capacity assemblies enable 500km-plus range ratings for premium electric SUVs. Guangdong OEM procurement favors these configurations where NEV credit calculations reward battery capacity scaling.
- 40-60 kWh:Mid-range capacity tier balances cost and range for mass-market passenger vehicles. Jiangsu production lines optimize cell-to-pack architectures around this segment's volume concentration.
- 20-40 kWh:Compact vehicle and range-extended hybrid applications.
- Below 20 kWh:Two-wheeler and auxiliary power unit specifications.
40-60 kWh anchors current production; Above 60 kWh expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate cell-to-pack manufacturing investments as provincial governments compete for NEV supply chain anchoring through tax abatement programs.
Jiangsu Province
Changzhou and Suzhou industrial parks host CATL and Gotion High-Tech pack assembly lines serving domestic OEM premium SUV programs. MIIT energy density floors permit LFP qualification for mid-market vehicles here. The province's NEV subsidy taper schedule accelerates fleet operator direct procurement negotiations.
Guangdong Province
Shenzhen and Dongguan manufacturing clusters reduce logistics costs for Pearl River Delta vehicle assembly plants. SAMR compulsory certification filters subscale producers from this concentrated production base. BYD anchors blade battery output across passenger vehicle and energy storage applications from Shenzhen headquarters.
Anhui Province
Hefei's battery industrial park attracts second-tier cell producers seeking lower land costs than coastal provinces. Provincial green procurement incentives favor pack assemblers with renewable-powered manufacturing footprints. Gotion High-Tech maintains R&D facilities here alongside production scale-up operations.
Fujian Province
Ningde hosts CATL's founding cell production complex with backward integration into cathode material processing. Local government industrial funds support pack assembly joint ventures with European OEMs seeking China supply security. The municipality's port infrastructure facilitates export-bound pack shipments.
Shandong Province
Qingdao and Yantai vehicle assembly plants source regionally manufactured LFP packs for commercial vehicle electrification programs. Provincial dual carbon implementation timelines pressure fleet operators toward verified low-carbon battery procurement. Second-life stationary storage deployments absorb retired passenger vehicle cells from Jiangsu supply pipelines.
China EV Battery Pack Market Competitive Landscape
Jiangsu and Guangdong producers anchor the volume tier; Anhui and Fujian specialists hold technology differentiation positions. The market structure concentrates among vertically integrated cell-to-pack operators with captive cathode supply, forcing independent assemblers toward niche energy storage applications. Three archetypes dominate: integrated cell-pack conglomerates, LFP chemistry specialists, and second-life service providers. Competitive moves center on backward integration into cathode production and strategic partnerships with OEM skateboard platform engineering teams.
Within the integrated conglomerate tier, CATL and BYD occupy positions defined by captive cell supply and direct OEM platform partnerships. Gotion High-Tech exemplifies the LFP specialization archetype, securing supply positions with European and domestic OEMs seeking lower-cobalt chemistries. These three entities represent the competitive core around which mid-tier assemblers and second-life service providers orbit.
| Leading Market Players |
|---|
| CATL |
| BYD |
| CALB |
| Gotion High-Tech |
| EVE Energy |
| SVOLT Energy Technology |
| Sunwoda EVB |
| Farasis Energy |
| LEAPENERGY |
| Others |
Pricing and Supply Chain Analysis
NEV credit mandate tightening accelerates premium electric SUV procurement, compelling pack assemblers to absorb cathode cost volatility while OEMs consolidate supplier tiers around vertically integrated cell producers. This demand compression reshapes pricing power toward input security holders and away from module-dependent independents.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as OEMs pay 8-15% above baseline for accelerated qualification timelines under MIIT energy density deadlines. Three-tier pricing structure across premium, standard, and economy levels separates CATL and BYD direct partnerships from second-tier LFP specialists and spot-market independents. Pricing pressure stems from lithium carbonate volatility compressing assembler margins, with fleet operators in Jiangsu exhibiting highest price sensitivity due to total cost of ownership calculations, while Guangdong premium SUV programs show lowest sensitivity to cell cost fluctuations.
Supply Chain Analysis
MIIT battery passport requirements and provincial dual carbon implementation timelines reshape sourcing toward verified low-carbon cathode suppliers with renewable-powered manufacturing footprints. Geographic supply concentration centers on China, South Korea, and Japan for cell production, with Australia, Chile, and Indonesia feeding lithium and nickel raw material pipelines. Raw material dependencies rest on lithium carbonate, nickel sulfate, and cobalt hydroxide cathode precursors. Single-source vulnerability concentrates in Jiangsu and Guangdong manufacturing clusters where CATL and BYD control captive cell supply. Distribution runs through OEM direct procurement channels and emerging fleet operator service-level agreements bypassing vehicle manufacturer markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT energy density floors and GB standard compliance burdens are forcing subscale pack assemblers toward exit or acquisition, consolidating viable supply positions among vertically integrated cell-to-pack operators with cathode backward integration.
For Market Incumbents: Extend platform engineering partnerships with OEM skateboard teams to lock in multi-year cell-to-chassis integration contracts before second-tier competitors achieve GB certification. Deepen upstream control over LFP cathode production in Jiangsu manufacturing clusters to defend margin position against lithium carbonate volatility. Threat substitution from solid-state development programs in Guangdong demands accelerated R&D investment in next-generation thermal management architectures. For New Entrants and Emerging Players: Launch via second-life stationary storage service models in Shandong and Anhui provinces, where retired Jiangsu passenger vehicle cells feed grid-scale deployments with lower certification barriers than automotive qualification. Target energy storage applications as the most penetrable segment, leveraging provincial green procurement incentives for verified low-carbon production footprints. Go-to-market angle should emphasize circular revenue streams encompassing performance guarantees and residual value recovery clauses. For Investors and Strategic Acquirers: The window for entry favors LFP chemistry specialists with European OEM supply positions and renewable-powered manufacturing footprints in Anhui or Fujian. Long-term viability hinges on 5-10 year cathode supply security and battery passport traceability infrastructure deployment. Acquisition target archetype: mid-tier assemblers with MIIT certification and stranded module assembly capacity suitable for retooling to cell-to-pack architectures. Signal to watch: provincial NEV subsidy taper schedules accelerating fleet operator direct procurement negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Transition | Eliminates module assembly steps, compressing part count and weight for premium SUV platforms. |
| LFP Cathode Backward Integration | Secures nickel-cobalt-free supply chains against raw material volatility in Jiangsu clusters. |
| Battery Passport Traceability Deployment | MIIT mandates blockchain-enabled lifecycle documentation from extraction through recycling recovery. |
| Second-Life Storage Partnership | Retired automotive cells from Guangdong feed Shandong grid-scale deployments with circular revenue. |
| OEM Skateboard Platform Integration | Structural battery enclosures converge with vehicle engineering, locking in multi-year supply positions. |
Research Methodology
Document review covered MIIT regulatory filings, GB standard compliance databases, and provincial NEV subsidy schedules, complemented by interviews with OEM platform engineers, pack assembler procurement directors, cathode material suppliers, and fleet operator sustainability officers. Secondary validation drew from SAMR certification records, customs trade data for lithium carbonate imports, and utility procurement disclosures for grid-scale storage deployments. Bottom-up cell production capacity estimates triangulated against top-down OEM vehicle production forecasts across the analysis window.
Segment-level projections incorporated chemistry type, vehicle class, capacity tier, and end-user procurement channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical production data against NEV credit mandate trajectories and provincial dual carbon implementation timelines. Industry-specific inputs included MIIT energy density floor escalations, GB standard revision schedules, and lithium carbonate price elasticity coefficients from cathode supplier contract disclosures.
Raw material price volatility, regulatory timeline acceleration, and technology substitution from solid-state development programs are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding OEM platform launch schedules and provincial subsidy taper trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
Traction Battery Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
North America Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market