
 Global Data Center Energy Management Solution Market | 2026-2036
Global Data Center Energy Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Center Energy Management Solution Market Intelligence
The bundling of software analytics with hardware power distribution units is pivoting buyer preference towards integrated systems. Schneider Electric SE leverages its EcoStruxure platform to deliver these combined offerings. Vertiv Holdings Co competes by specializing in thermal management and critical power integration for large-scale facilities. Eaton Corporation differentiates with its electrical power management solutions tailored for colocation and enterprise clients.
Data center energy management solutions are integrated systems of hardware and software designed to monitor and control power consumption. Their primary function is to improve Power Usage Effectiveness (PUE) ratios, a key metric for operational efficiency. Among end users, hyperscale data centers represent the largest and fastest-growing segment due to their immense power needs. Within solution types, cooling optimization and consumption analytics are critical for managing the high-density server racks common in modern facilities.
Regulations such as the EPA's ENERGY STAR program in the United States and the EU Green Deal's efficiency mandates shape system requirements. In China, national dual carbon goals are pushing data center operators to adopt greener energy management practices. Operators must now decide whether to retrofit existing infrastructure or invest in new, inherently more efficient designs to meet these evolving standards.
Market Dynamics
The central dynamic shaping the data center energy management market is the collision between escalating power densities from AI workloads and stringent government mandates for energy efficiency, forcing a fundamental redesign of power and cooling architectures.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and similar efficiency standards in the United States create a non-discretionary need for operators to invest in advanced monitoring and control systems to meet compliance and reporting requirements.
- High-Density Computing:The proliferation of server racks for artificial intelligence and machine learning applications, which consume significantly more power, drives demand for sophisticated thermal management and power distribution solutions to prevent overheating and optimize costs.
- Emerging Market Build-Outs:Greenfield data center construction in regions like Southeast Asia and the Middle East provides a significant opportunity for the installation of modern, integrated energy management systems from the initial design phase.
Market Restraints
- High Retrofit Costs:The substantial capital investment required to upgrade legacy data center infrastructure with modern power distribution units, sensors, and cooling systems presents a major financial barrier for many enterprise operators.
- Integration Complexity:Significant technical hurdles exist in integrating new energy management software with older, often proprietary, building management systems (BMS), leading to implementation delays and compatibility issues for facility managers.
- Component Scarcity:Supply chain constraints for specialized electrical components, such as high-capacity transformers and switchgear, can lead to extended project timelines and increased costs for both new builds and facility upgrades.
Strategic Opportunities
- AI-Driven Analytics:The convergence of DCIM software with artificial intelligence offers a new frontier for predictive analytics, enabling proactive load balancing, automated fault detection, and optimization of energy consumption in real time.
- Liquid Cooling Systems:The shift towards direct-to-chip and immersion liquid cooling for next-generation processors creates a new market for specialized energy management solutions that can control and monitor fluid dynamics and heat exchange.
- Edge Computing Expansion:The deployment of numerous smaller edge data centers requires scalable, remotely manageable energy solutions, creating an opportunity for modular and standardized products that can be deployed efficiently across distributed locations.
Industry Challenges
- Specialized Talent Shortage:A scarcity of engineers and data scientists with hybrid expertise in both electrical power systems and software analytics hinders the ability of operators to fully leverage the capabilities of advanced energy management platforms.
- Vendor Interoperability:The lack of universal communication protocols between hardware and software from different vendors complicates the creation of a unified energy management dashboard, forcing operators into single-vendor ecosystems or complex integration projects.
- Legacy System Constraints:Integrating modern energy management tools with aging electrical and mechanical infrastructure in older data centers presents significant operational challenges, often limiting the effectiveness of new software-based optimizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Center Energy Management Solution Market |
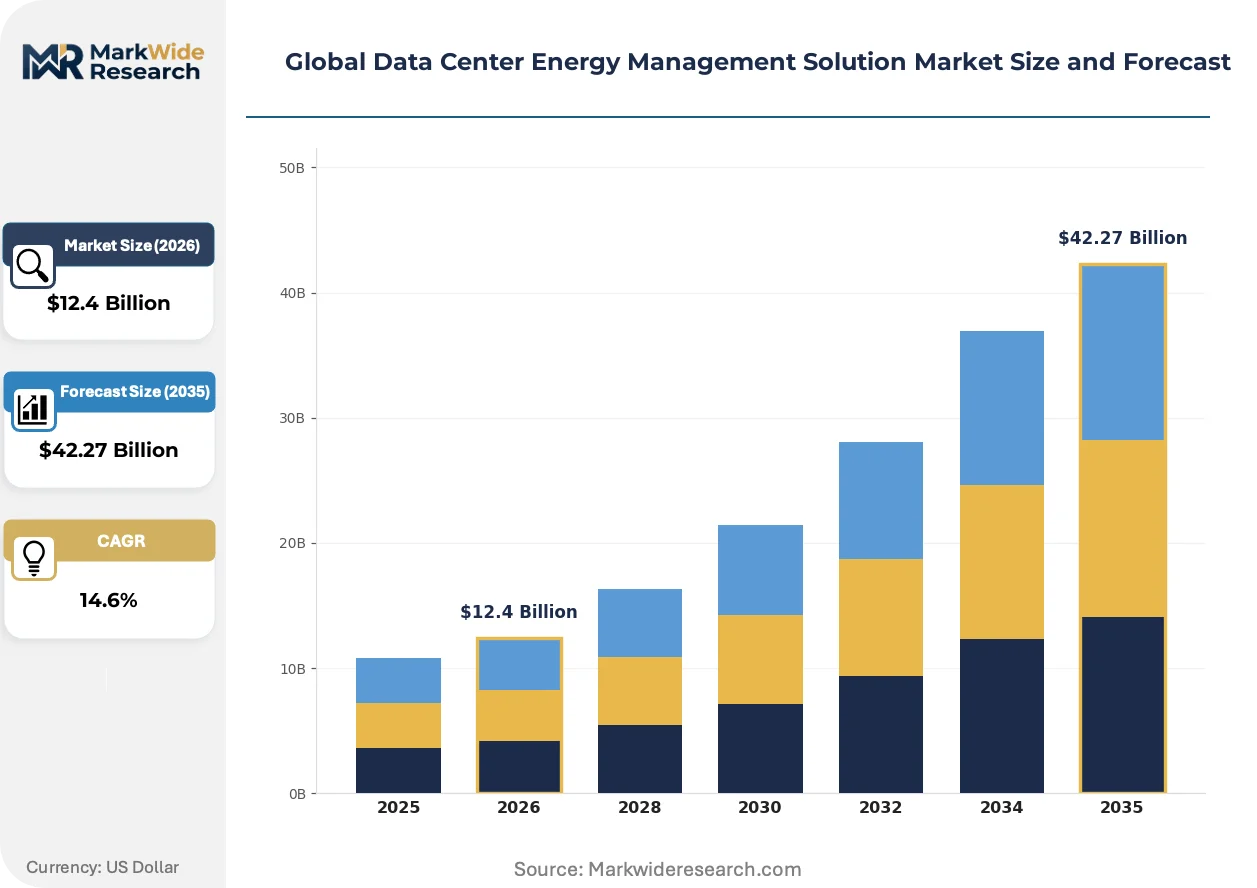
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $42.27 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Energy Monitoring, Consumption Analytics, Cooling Optimization, Power Usage Effectiveness, Asset Management Deployment Mode: On-Premises, Cloud-Based, Hybrid, Edge Computing Application: Server Load Management, HVAC Control, Renewable Integration, Capacity Planning, Peak Shaving End User: Colocation Facilities, Cloud Providers, Telecommunication Operators, Hyperscale Data Centers |
| Companies Covered | Schneider Electric SE, Vertiv Holdings Co, ABB Ltd, Eaton Corporation, Delta Electronics Inc, Siemens AG, Legrand SA, Johnson Controls, Huawei Technologies Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Center Energy Management Solution Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive pivot from reactive monitoring of power consumption to predictive, automated control over the entire energy lifecycle. This transition is enabled by software intelligence layered on top of advanced hardware.
AI-powered digital twin technology provides a virtual simulation of a data center's power and thermal infrastructure. Hyperscale and large colocation providers are the primary adopters, using it to model the impact of equipment changes before physical deployment. This technology is automating the process of capacity planning and identifying stranded power or cooling resources within a facility.
China's national dual carbon goals mandate specific Power Usage Effectiveness (PUE) targets for both new and existing data centers. This policy forces operators to invest in high-efficiency power supplies, renewable energy integration, and advanced cooling technologies like free-air or liquid cooling. The colocation sector in primary markets such as Shanghai and Beijing is most affected, accelerating retrofits to meet these stringent environmental standards.
A notable shift in purchasing behavior involves enterprise clients procuring colocation services with contracts that specify energy efficiency SLAs. This model transfers the responsibility for energy optimization from the tenant to the data center operator, who must now deliver measurable efficiency as a core service. This trend is most visible in North American and European markets, where corporate sustainability reporting drives procurement decisions.
Global Data Center Energy Management Solution Market Segmentation
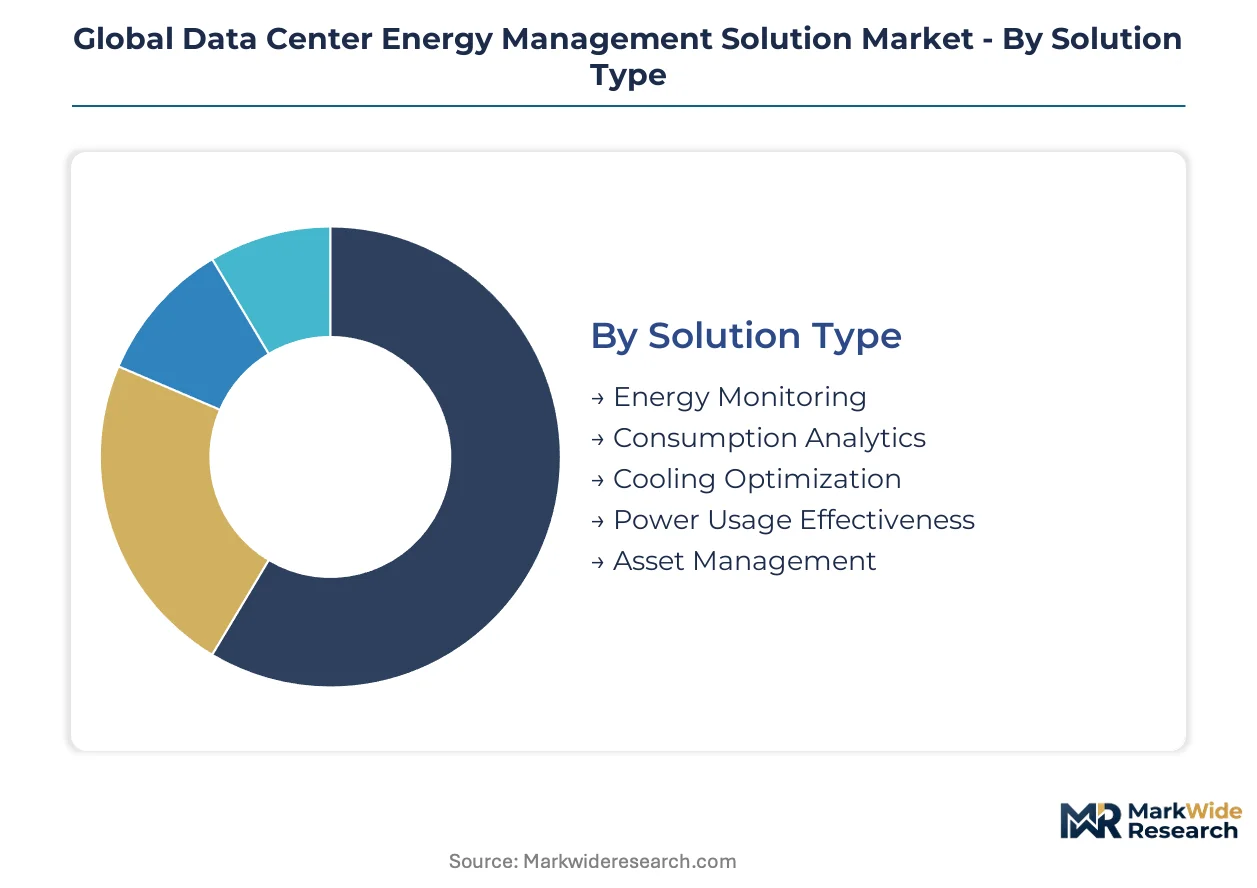
The Global Data Center Energy Management Solution Market segments reflect the diverse operational needs and technological requirements across various data center environments. Tailored solutions are essential for addressing specific challenges, from managing high-density workloads to optimizing power consumption in distributed facilities. This segmentation highlights the specialized nature of energy management tools required for modern infrastructure.
Solution Type:
The upgrade and replacement cycles for data center infrastructure heavily influence the demand for specific energy management solution types.
- Cooling Optimization:These solutions manage and fine-tune data center cooling infrastructure, including CRAC/CRAH units and advanced liquid cooling systems. Demand is concentrating in hyperscale data centers, driven by the need to efficiently dissipate heat from high-density AI server racks.
- Consumption Analytics:This involves software platforms that collect, process, and visualize power consumption data across various data center components. Cloud providers utilize these analytics for real-time load balancing and identifying energy waste within their vast infrastructures.
- Energy Monitoring:Hardware and software systems track real-time power usage at cabinet, rack, and device levels.
- Power Usage Effectiveness:Tools and metrics specifically designed to calculate and improve the PUE ratio for operational efficiency.
- Asset Management:Solutions that track and manage physical assets within the data center, often integrated with power monitoring.
Energy Monitoring sits at the top of the volume ranking, with Cooling Optimization climbing the fastest.
Deployment Mode:
Customer type and operational scale significantly influence the choice of deployment mode for data center energy management solutions.
- Cloud-Based:These solutions are delivered as Software-as-a-Service (SaaS), offering remote monitoring and management capabilities. Telecommunication operators increasingly adopt cloud-based deployments for managing distributed edge data centers efficiently.
- Edge Computing:Energy management systems specifically designed for smaller, decentralized data centers located closer to data sources. Demand is accelerating for these solutions to support latency-sensitive applications in remote and localized environments.
- On-Premises:Software and hardware installed directly within the data center facility, managed internally.
- Hybrid:A combination of on-premises and cloud-based components, offering flexibility and data control.
Cloud-Based deployments are gaining share fastest due to their scalability and reduced infrastructure overhead.
Application:
Specific applications drive the adoption of data center energy management solutions, targeting distinct operational efficiencies and sustainability goals.
- Server Load Management:Software tools that dynamically distribute workloads across servers to optimize power consumption and prevent overprovisioning. Hyperscale data centers use these systems to maximize resource utilization and improve overall energy efficiency.
- Renewable Integration:Solutions that enable data centers to incorporate and manage power from renewable energy sources, such as solar or wind. Colocation providers increasingly invest in these applications to meet corporate sustainability goals and regulatory mandates.
- HVAC Control:Management systems that regulate heating, ventilation, and air conditioning equipment for optimal thermal performance.
- Capacity Planning:Software tools that forecast future power and cooling needs based on current usage and growth projections.
- Peak Shaving:Strategies and systems to reduce power demand during peak pricing periods, lowering operational costs.
Renewable Integration shows the steepest expansion trajectory, driven by global environmental initiatives.
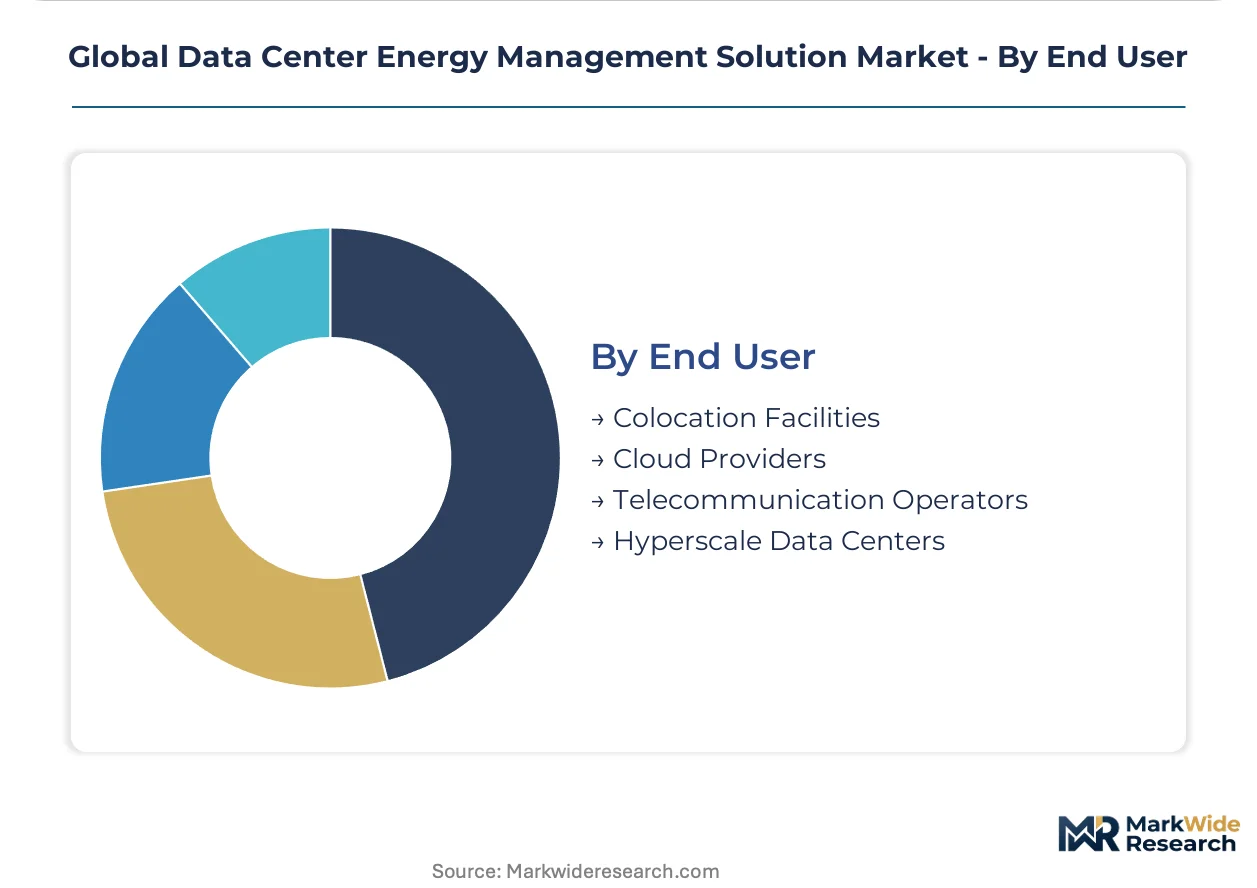
End User:
The volume of data processing and power consumption dictates the energy management needs of different end-user segments.
- Hyperscale Data Centers:Large-scale facilities operated by major cloud providers and internet companies, characterized by massive power demands. These users represent the largest segment, driven by the need for advanced solutions to manage immense energy consumption.
- Colocation Facilities:Data centers that lease space, power, and cooling to multiple tenants, requiring robust, multi-tenant energy management. Demand from colocation providers is concentrating in established data center clusters like Northern Virginia.
- Cloud Providers:Companies offering cloud computing services, utilizing energy management to optimize their vast server farms.
- Telecommunication Operators:Providers of communication services, managing energy in their network infrastructure and data centers.
Hyperscale Data Centers are expanding most quickly, necessitating continuous investment in advanced energy management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center energy management solutions first scaled significantly in the United States, driven by the rapid expansion of internet infrastructure. Early adoption concentrated in major tech hubs as hyperscale operators sought to optimize immense power consumption. This established the foundation for global market development, influencing subsequent regional growth patterns and technological advancements.
United States
Hyperscale and colocation facilities in the United States drive substantial demand for advanced energy management. The EPA's ENERGY STAR program encourages operators to invest in efficiency solutions for compliance and cost savings. Northern Virginia and Silicon Valley remain primary clusters, experiencing continuous build-outs and upgrades for high-density AI workloads.
China
China's national dual carbon goals mandate specific Power Usage Effectiveness (PUE) targets, accelerating investment in high-efficiency solutions. Operators in China are adopting advanced cooling technologies and renewable energy integration to meet these stringent environmental standards. The colocation sector in primary markets such as Shanghai and Beijing is particularly affected, undergoing significant retrofits.
Germany
Germany's data center market experiences strong demand for energy management solutions, influenced by the EU Green Deal's stringent efficiency targets. These regulations compel operators to deploy advanced monitoring and control systems. Frankfurt, a major European internet exchange point, sees significant investment in green data center technologies and sustainable operational practices.
Singapore
Greenfield data center construction in Singapore provides a significant opportunity for installing modern, integrated energy management systems from the initial design phase. Government sustainability initiatives and a focus on regional digital infrastructure bolster demand for efficient power and cooling. Major data center parks in Jurong and other industrial zones are incorporating advanced energy analytics.
United Arab Emirates
Emerging market build-outs in the United Arab Emirates are driving the adoption of advanced energy management solutions. Government-led digital transformation initiatives and sustainability targets encourage investment in efficient data center infrastructure. Dubai and Abu Dhabi's tech parks are integrating renewable energy sources and smart grid technologies to power new facilities efficiently.
Global Data Center Energy Management Solution Market Key Industry Players
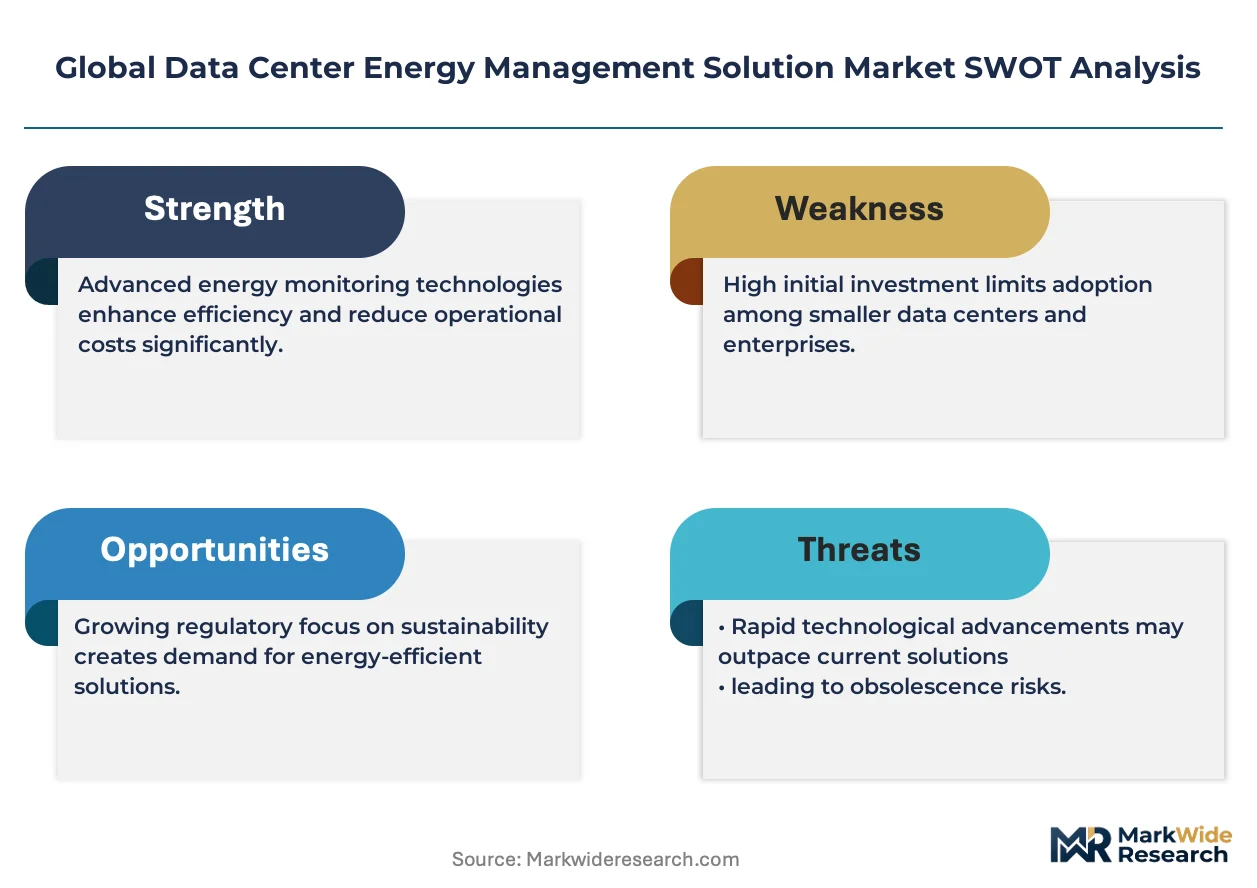
Premium-margin players sit above commodity-margin players across solution complexity and integration capabilities within the data center energy management market. The market structure exhibits a tiered approach, with specialized vendors offering integrated hardware-software systems. Strategic archetypes include integrated system providers, thermal management specialists, and electrical power management solution vendors. Key competitive moves involve portfolio diversification and strategic partnerships to deliver comprehensive offerings.
Specialists in integrated hardware and software platforms include Schneider Electric SE, leveraging its EcoStruxure platform for combined offerings. Vertiv Holdings Co, a US-based entity, occupies a position focused on thermal management and critical power integration for large-scale facilities. Eaton Corporation, an Ireland-domiciled company, exemplifies a vendor providing electrical power management solutions tailored for colocation and enterprise clients. These companies anchor distinct segments of the market by emphasizing their core strengths and solution architectures.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Holdings Co |
| ABB Ltd |
| Eaton Corporation |
| Delta Electronics Inc |
| Siemens AG |
| Legrand SA |
| Johnson Controls |
| Huawei Technologies Co Ltd |
| Others |
Cost & Logistics Intelligence
Specialized engineering talent concentrated in established tech hubs like Silicon Valley drives significant labor costs, influencing the premium pricing tiers for integrated data center energy management solutions.
Pricing Analysis
Project-based pricing dominates the procurement of integrated data center energy management solutions, reflecting the bespoke nature of large-scale deployments. Price differentiation stems from the level of customization required for complex infrastructure and the extent of after-sales support bundled with software licenses. Pricing softness in basic monitoring solutions stems from increased competition and commoditization of entry-level hardware. Hyperscale data centers exhibit the least price sensitivity due to their critical need for operational efficiency, while enterprise clients are more budget-conscious.
Supply Chain Analysis
Regional distribution centers strategically located near major data center clusters, such as those in Northern Virginia and Frankfurt, form the backbone of the supply chain for energy management hardware. Supply concentration for critical electrical components like high-capacity transformers and switchgear primarily resides in China, Germany, and the United States. The market draws from specialized sensors and power distribution units. Component scarcity represents a structural supply chain risk, leading to extended lead times. Distribution runs through direct sales channels to large operators and specialized system integrators for smaller deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The data center energy management market is evolving into a late-cycle quality story, driven by a demand shift towards premium, integrated solutions for AI workload management.
For Market Incumbents: Lock in existing hyperscale and colocation clients by continuously enhancing integrated hardware-software platforms like EcoStruxure. Acquire niche AI analytics firms to counter the threat of specialized software entrants and expand predictive optimization capabilities. Deepen vertical integration into specialized component manufacturing for critical power infrastructure to mitigate supply chain risks.
For New Entrants and Emerging Players: AI-driven predictive analytics offers a technology-first wedge for new entrants to disrupt traditional monitoring solutions. Target the underpenetrated edge computing segment with modular, cloud-based energy management systems that offer remote management capabilities. A SaaS-based go-to-market angle with flexible subscription tiers can attract smaller, distributed data center operators.
For Investors and Strategic Acquirers: Industrial conglomerates and major software vendors are the most active acquirers in this space, seeking to expand their integrated offerings. Long-term viability hinges on the sustained growth of AI workloads and the non-discretionary need for energy efficiency in data centers. Look for specialized software firms offering advanced cooling control or AI/ML optimization as prime acquisition targets. Increased M&A activity from large cloud providers is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance AI-Powered Analytics | This improves predictive capabilities for energy optimization and proactive fault detection for hyperscale data centers. |
| Invest in Liquid Cooling Integration | This addresses the rising heat density from AI servers, offering efficient thermal management solutions for modern facilities. |
| Develop Modular Edge Solutions | This captures the growing demand for scalable and remotely manageable energy systems in distributed edge environments. |
| Strengthen Regulatory Compliance Tools | This helps operators meet evolving efficiency mandates like the EU Green Deal and China's dual carbon goals. |
| Form Strategic Partnerships | This combines hardware expertise with software intelligence, delivering comprehensive integrated systems to end-users. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights from data center operators and facility managers with extensive secondary validation. The analysis incorporated perspectives from energy efficiency consultants and hardware engineers. Secondary data sources included EPA ENERGY STAR reports, EU Green Deal policy documents, company financial filings, and industry association publications. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy and consistency.
Segment-weighting across solution type, deployment mode, application, and end-user categories formed the core of the forecasting framework over the projection horizon. Compound annual growth rates were derived from historical trends, market drivers, and expert projections. Key industry-specific forecast inputs included AI workload growth rates and the evolution of Power Usage Effectiveness (PUE) targets across different regions.
The model holds under assumptions of sustained data center expansion and evolving energy efficiency mandates; deviation in component supply chain stability or AI technology adoption rates would shift projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Smart Air Cleaners Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
Smart Utilities Management Market