
 Italy Courier Market | 2026-2036
Italy Courier Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Courier Market Insights
Multi-source outsourcing among Italian retailers is hardening as a dominant procurement pattern. Poste Italiane leverages its unrivaled last-mile density across rural postal codes to sustain universal service obligations. BRT Bartolini anchors B2B pallet distribution through its dedicated hub network in Emilia-Romagna. GLS Italy competes on price-sensitive e-commerce volumes with automated sorting infrastructure near Bologna.
A courier operation encompasses the collection, transit, and terminal delivery of parcels and documents under contracted service levels, typically employing barcode tracking, route optimization algorithms, and fleet assets ranging from electric vans to cargo aircraft. The primary commercial purpose is time-definite movement of goods between businesses and consumers. Same-day delivery commands premium pricing in dense northern corridors, while standard delivery occupies the volume base across southern regions where infrastructure costs constrain margin pools. International shipping extends revenue per parcel for operators with customs brokerage capabilities, though Brexit-related documentation has shifted some flows toward multimodal ground-sea alternatives.
Italy's courier sector operates under EU Green Deal emission targets, national ANSFISA road safety mandates, and local ZTL urban access restrictions in Rome, Milan, and Florence that penalize diesel vehicles during daytime hours. These frameworks are accelerating fleet replacement schedules and reshaping depot location strategies around peripheral electrification hubs. Stakeholders must monitor how proposed EU Packaging and Packaging Waste Regulation revisions will alter dimensional pricing and reusable container requirements before committing to long-term automation investments.
Market Dynamics
EU Green Deal emission mandates are compressing diesel fleet replacement timelines across Italian logistics operators, forcing capital reallocation toward electrification infrastructure and peripheral depot repositioning around Milan's northern corridor.
Growth Catalysts
- E-commerce platform outsourcing:Major Italian retailers are hardening multi-source procurement patterns for last-mile delivery, expanding contracted network capacity across Lombardy and Veneto distribution zones.
- ANSFISA road safety mandates:National vehicle compliance requirements are accelerating telematics adoption and driver monitoring systems across commercial fleets.
- Alpine intermodal connectivity:Northern logistics corridors linking Swiss and Austrian freight routes to domestic distribution centers are concentrating parcel volume in Milan-hubbed networks.
Market Restraints
- Lithium battery supply concentration:Fleet electrification timelines depend on Asian cell manufacturers, exposing operators to input cost volatility and extended procurement cycles for electric vans.
- ZTL urban access restrictions:Rome, Milan, and Florence penalize diesel vehicles during daytime hours, creating structural friction for operators without electrified last-mile assets.
- Southern infrastructure cost density:Lower parcel volume per postal code across Calabria and Sicily constrains automated sorting investment returns relative to northern benchmarks.
Strategic Opportunities
- Reusable packaging mandates:Proposed EU Packaging and Packaging Waste Regulation revisions will create dimensional pricing advantages for operators investing in return-container logistics.
- Customs brokerage integration:Brexit-related documentation complexity is diverting cross-border flows toward Italian operators with multimodal ground-sea capabilities and in-house clearance expertise.
- Rural postal code density:Universal service obligation networks in Apennine and southern regions remain underpenetrated by automated competitors, preserving margin pools for density-optimized operators.
Industry Challenges
- Electrification technician scarcity:Fleet maintenance operations face skill gaps in high-voltage systems diagnostics and battery thermal management, extending vehicle downtime.
- Depot reconfiguration capex:Peripheral electrification hubs require land acquisition and grid connection investments before ZTL enforcement timelines mature.
- Legacy route optimization integration:Algorithmic dispatch systems must interface with established barcode tracking infrastructure without disrupting real-time customer visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Courier Market |
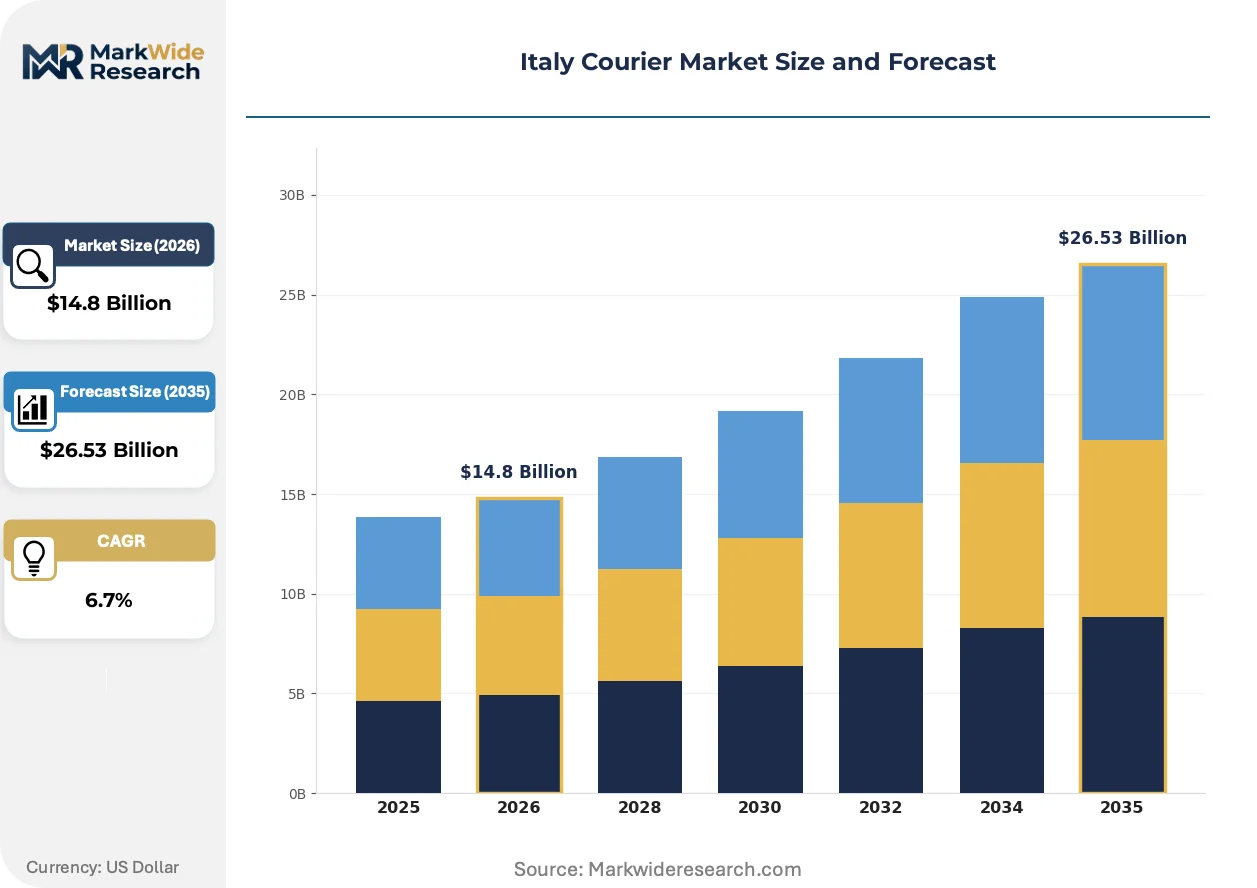
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, International Shipping Delivery Mode: Ground, Air, Sea, Multimodal End User: E-commerce, Retail, Healthcare, Manufacturing Packaging Type: Box, Envelope, Pallet, Crate |
| Companies Covered | Poste Italiane, BRT Bartolini, GLS Italy, DHL Express, UPS, FedEx, Amazon Logistics, Sailpost SpA, Speedy SRL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Courier Market Trends and Innovations
Italian courier operations are converging on electrified fleet assets, regulatory compliance automation, and restructured buyer-supplier contracting models that compress delivery windows while expanding service tier differentiation.
Light electric commercial vehicles are electrifying urban last-mile operations across Milan, Turin, and Bologna. Grocery and fashion e-commerce platforms are adopting these assets fastest, pressured by ZTL diesel bans and ESG procurement scoring. The technology is electrifying competitive positioning in dense northern corridors where depot-to-door distances favor battery range economics.
EU Green Deal emission targets are hardening into enforceable fleet replacement schedules with binding 2030 milestones. Logistics operators must document CO2 reduction pathways or face exclusion from public sector contracts and large retailer panels. Emilia-Romagna and Lombardy-based hubs are responding fastest, securing peripheral land for charging infrastructure ahead of enforcement windows.
Multi-year framework agreements with volume commitments and penalty clauses are displacing spot-market parcel tendering among mid-market Italian retailers. These contracts bundle same-day, next-day, and economy tiers with unified tracking portals, consolidating supplier panels from five-plus vendors to two or three preferred partners. The shift is most visible in Milan's fashion and luxury goods verticals where delivery reliability directly impacts brand equity.
Italy Courier Market Segmentation
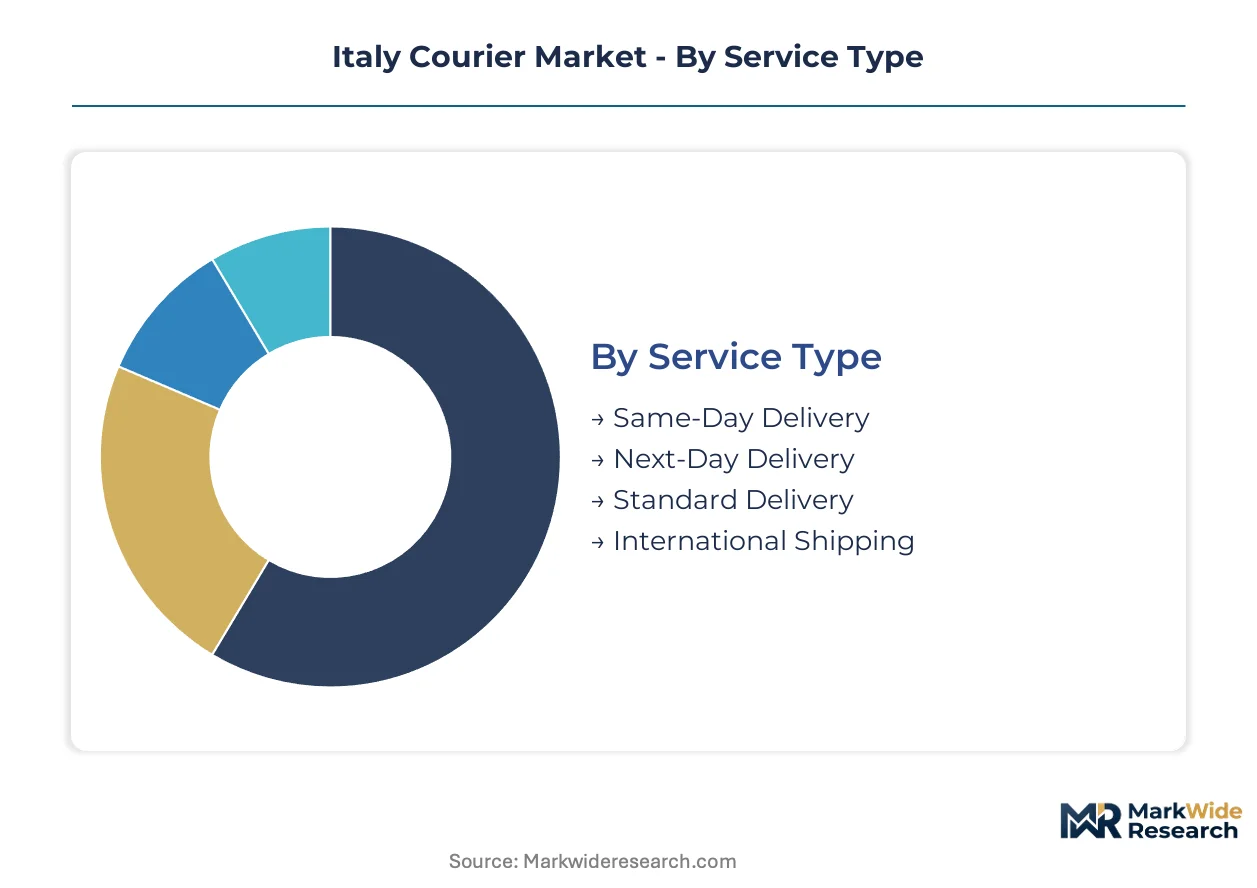
Service tier differentiation determines capital allocation and fleet composition across Italian courier operations. Segmentation by delivery urgency, transport mode, and end-use vertical reveals where margin pools concentrate and where electrification investments yield fastest returns.
Service Type:
Standalone premium services operate on dedicated fleet assets with contracted SLAs, while embedded economy tiers ride shared network infrastructure.
- Same-Day Delivery:Time-definite urban circuits employing electric vans and micro-depots within ZTL zones. Milan's fashion and luxury verticals absorb premium pricing for guaranteed four-hour windows. Electrified fleet mandates and ESG procurement scoring accelerate carrier qualification for this tier.
- Next-Day Delivery:Hub-and-spoke networks with evening sortation and morning distribution slots. Lombardy and Veneto e-commerce fulfillment centers generate concentrated volume for carriers with automated Bologna-area infrastructure. Retailer panel consolidation favors operators offering unified tracking across same-day and next-day tiers.
- Standard Delivery:Two-to-three-day ground transport utilizing shared line-haul capacity. Southern postal codes in Calabria and Sicily rely on this tier due to infrastructure cost constraints.
- International Shipping:Customs-cleared multimodal flows requiring brokerage integration. Brexit documentation complexity diverts cross-border volume toward Italian operators with ground-sea capabilities.
Standard delivery leads volumes today; same-day delivery is gaining share fastest.
Delivery Mode:
Cost tier segmentation separates asset-heavy owned operations from contracted multimodal solutions.
- Ground:Diesel and electric road fleets handling last-mile and domestic line-haul. ANSFISA telematics mandates and EU Green Deal emission targets compress replacement timelines for commercial vehicles.
- Air:Time-critical domestic and cross-border parcel flows through Milan Malpensa and Rome Fiumicino cargo terminals. Premium per-kilogram pricing applies to pharmaceutical and high-value manufacturing shipments.
- Sea:Containerized pallet movements connecting southern ports to Mediterranean distribution hubs. Lower unit economics suit non-urgent B2B freight.
- Multimodal:Integrated ground-sea-air routing optimizing cost-speed tradeoffs. Alpine intermodal corridors linking Swiss and Austrian freight routes to Milan-hubbed networks favor this mode for northern European destinations.
Ground transport dominates revenue today; multimodal is climbing the fastest as Brexit reshapes cross-border flows.
End User:
Application-based segmentation distinguishes consumer-facing platforms from industrial supply chain integration.
- E-commerce:Platform-fulfilled parcel volumes driving outsourced last-mile expansion. Multi-year framework agreements with volume commitments displace spot-market tendering among mid-market retailers.
- Retail:Store replenishment and click-and-collect logistics. Fashion verticals in Milan prioritize delivery reliability for brand equity protection.
- Healthcare:Temperature-controlled pharmaceutical distribution with GDP compliance requirements. Cold chain infrastructure concentrates around northern logistics corridors.
- Manufacturing:B2B pallet and component flows with scheduled delivery windows. Emilia-Romagna automotive and machinery suppliers demand dedicated hub networks.
E-commerce leads volume concentration today; healthcare is expanding most quickly on cold chain investment.
Packaging Type:
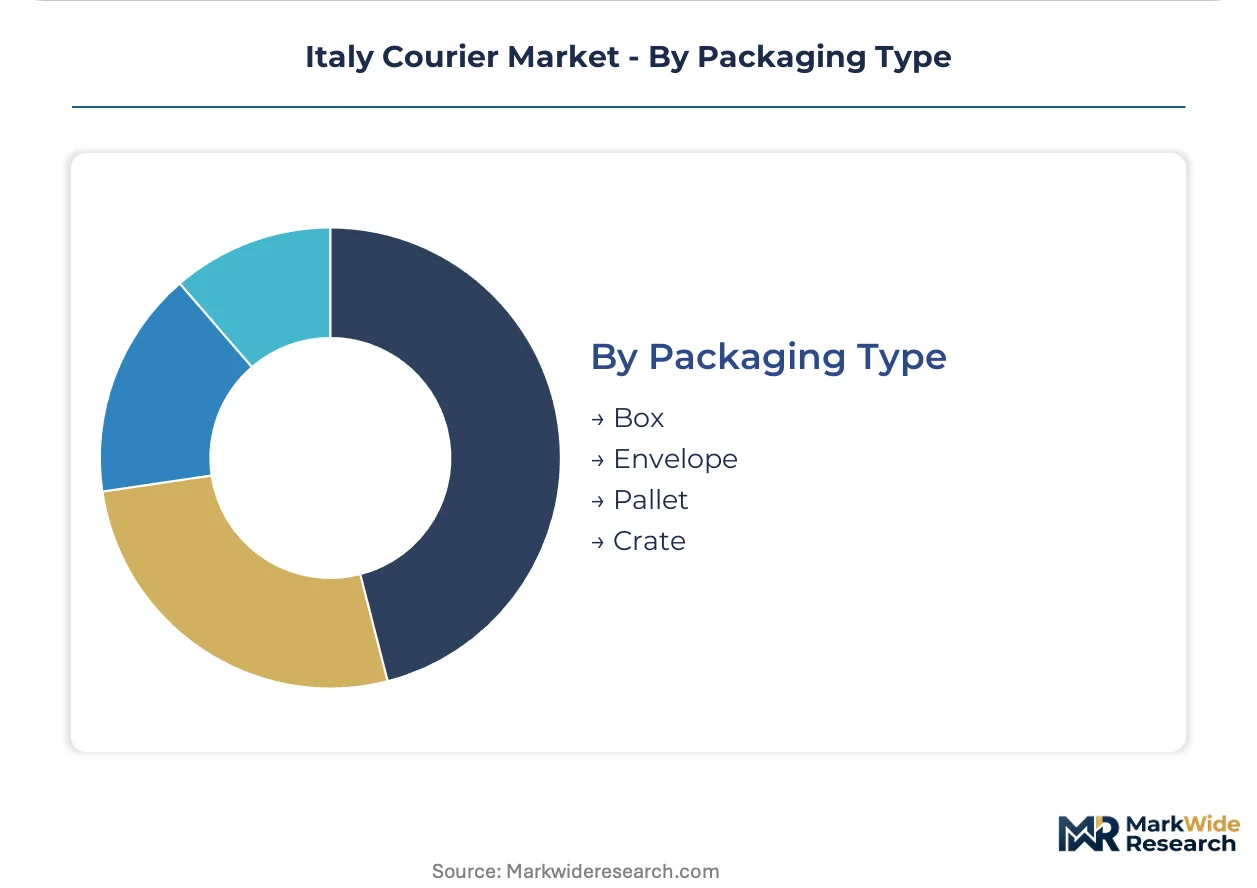
Volume-based segmentation aligns handling infrastructure with dimensional weight economics.
- Box:Standardized corrugated containers for general merchandise. Automated sorting systems near Bologna process high volumes for e-commerce platforms.
- Envelope:Document and small-item delivery with minimal handling requirements. Poste Italiane's rural postal code density sustains universal service obligation coverage for this format.
- Pallet:Unitized B2B freight requiring forklift-capable depot infrastructure. BRT Bartolini's dedicated hub network in Emilia-Romagna anchors this segment.
- Crate:Reusable packaging for high-value or fragile goods. Proposed EU Packaging and Packaging Waste Regulation revisions favor return-container logistics investment.
Box shipments dominate parcel counts today; crate utilization is gaining share fastest on reusable packaging mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's northern logistics corridor anchors Italian courier demand through Milan's intermodal hubs connecting Alpine freight routes to domestic distribution centers.
Lombardy
Milan's fashion and luxury verticals drive premium same-day delivery volumes through electrified urban fleets. EU Green Deal emission targets compress diesel replacement timelines for operators serving ZTL-restricted city centers. The Milan-hubbed northern corridor concentrates automated sorting investment near intermodal Alpine connectors.
Veneto
E-commerce fulfillment centers around Verona and Padua generate concentrated parcel volumes for outsourced last-mile networks. ANSFISA road safety mandates accelerate telematics adoption across commercial fleets operating Emilia-Romagna transit routes. The Port of Venice anchors multimodal ground-sea alternatives for Brexit-diverted cross-border flows.
Emilia-Romagna
Automotive and machinery suppliers demand dedicated B2B pallet distribution with scheduled delivery windows. EU Packaging and Packaging Waste Regulation revisions reshape dimensional pricing for reusable container logistics. Bologna-area automated sorting infrastructure processes high e-commerce volumes for price-sensitive market tiers.
Lazio
Rome's ZTL urban access restrictions penalize diesel vehicles during daytime hours, forcing fleet electrification for central district coverage. Poste Italiane leverages unrivaled rural postal code density to sustain universal service obligations across Apennine regions. Fiumicino cargo terminals handle time-critical pharmaceutical shipments requiring GDP compliance.
Piedmont
Turin's manufacturing base generates component flows with contracted SLA requirements for just-in-time delivery. Local ZTL enforcement windows accelerate peripheral depot repositioning around electrification hubs. The Alpine tunnel connectivity to France and Switzerland favors multimodal routing for northern European destinations.
Italy Courier Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrified last-mile specialization and rural density optimization. The vendor base organizes around three archetypes: postal incumbents with universal service obligations, dedicated B2B pallet networks, and price-sensitive e-commerce specialists. Dominant competitive moves include multi-year framework agreements with volume commitments and peripheral depot reconfiguration around charging infrastructure.
Among Italy-based operators, Poste Italiane exemplifies the postal incumbent archetype through rural postal code coverage, while BRT Bartolini anchors B2B pallet distribution. GLS Italy occupies a position within the price-sensitive e-commerce tier. DHL Express, UPS, and FedEx represent international integrators competing on customs brokerage capabilities. Amazon Logistics exemplifies platform-captive delivery assets, while Sailpost SpA and Speedy SRL sit within regional specialist positioning.
| Leading Market Players |
|---|
| Poste Italiane |
| BRT Bartolini |
| GLS Italy |
| DHL Express |
| UPS |
| FedEx |
| Amazon Logistics |
| Sailpost SpA |
| Speedy SRL |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal emission mandates gate qualified supply access and premium-tier pricing power for Italian courier operators, compressing diesel fleet replacement timelines while concentrating electrified asset premiums in Milan's ZTL corridors. Fleet operators lacking peripheral charging infrastructure face structural exclusion from same-day fashion and luxury contracts where ESG procurement scoring determines panel qualification.
Pricing Analysis
Input-cost pass-through from lithium battery procurement cycles and high-voltage technician scarcity is intensifying margin compression across electrified fleet tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery velocity and ZTL compliance certification, with same-day Milan fashion verticals absorbing the steepest premiums. Cost compression in standard delivery runs through southern infrastructure constraints where lower parcel density dilutes automated sorting returns. E-commerce platforms exhibit highest price sensitivity, while healthcare cold chain and luxury fashion verticals prioritize reliability over unit cost.
Supply Chain Analysis
Workforce availability constraints in German and Polish commercial vehicle manufacturing are extending electric van delivery timelines for Italian fleet operators. Battery cell supply draws from South Korean and Chinese producers, creating single-source vulnerability for cathode materials and thermal management systems. Distribution runs through Alpine intermodal corridors connecting Milan-hubbed networks to Swiss and Austrian freight routes, with Brexit documentation complexity diverting cross-border volume toward ground-sea multimodal alternatives through Venice and Genoa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy courier market functions as a stable compounder where e-commerce platform outsourcing sustains contracted volume growth across Lombardy and Veneto fulfillment corridors.
For Market Incumbents: Anticipate lithium battery supply concentration and electrification technician scarcity by securing long-term cell procurement agreements with South Korean manufacturers and funding high-voltage diagnostics training partnerships with Emilia-Romagna technical institutes. Peripheral depot repositioning around Milan's charging infrastructure represents the priority defensive lever against ZTL enforcement timelines. For New Entrants and Emerging Players: EU Green Deal emission mandates in Italy open a window for electrified last-mile specialization targeting Rome and Florence ZTL zones where diesel penalties create immediate qualification barriers for legacy operators. Rural postal code density across Calabria and Sicily remains the most penetrable white-space, with universal service obligation networks preserving margin pools for density-optimized entrants deploying micro-depot models. For Investors and Strategic Acquirers: Roll-up economics work for regional electrified specialists because EU Green Deal compliance costs are forcing fragmentation among sub-scale operators unable to fund peripheral charging infrastructure independently. Target acquisition archetypes include Veneto-based automated sorting operators with Bologna-area real estate and established retailer panel relationships. Watch lithium carbonate price volatility as the inflection signal for fleet replacement capex timing and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Peripheral Electrification Hub Development | Secures ZTL-compliant depot positioning ahead of Milan diesel enforcement windows. |
| Multi-Year Framework Agreement Negotiation | Consolidates retailer panels from fragmented vendor pools to preferred partner status. |
| High-Voltage Technician Training Program | Addresses fleet maintenance skill gaps extending electric vehicle downtime. |
| Reusable Packaging Logistics Investment | Positions for EU Packaging and Packaging Waste Regulation dimensional pricing advantages. |
| Customs Brokerage Capability Integration | Captures Brexit-diverted cross-border flows through ground-sea multimodal routing. |
Research Methodology
Bottom-up e-commerce fulfillment modeling reconciled against top-down fleet electrification tracking forms the analytical core of this study. Primary interviews with logistics procurement directors at Italian fashion retailers, fleet operations managers at Lombardy-based carriers, ANSFISA compliance officers, and charging infrastructure developers combined with secondary validation from EU Green Deal implementation timelines, ANSFISA telematics mandate filings, and Italian customs brokerage transaction records. Triangulation between parcel volume data from automated sorting facilities and carrier capex disclosures ensures methodological consistency.
Input-output matrix framing connects lithium battery procurement cycles, electric van delivery lead times, and ZTL enforcement schedules to projected fleet composition across the analysis window. Segmentation dimensions modeled include service tier velocity, delivery mode asset type, end-use vertical concentration, and regional infrastructure density. CAGRs derive from reconciling bottom-up parcel volume projections against top-down logistics sector investment flows, with specific weighting applied to Alpine intermodal corridor capacity expansion and southern postal code automation thresholds.
Revisions become necessary when lithium supply contract renegotiations, ANSFISA mandate acceleration, or EU Packaging Regulation enforcement delays materialize differently than baseline assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Germany Last Mile Delivery Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
Iraq Air Freight Transport Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Europe Container Terminal Operations Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Shipping Supplies Market