
 Global Network Monitoring Software Market | 2026-2036
Global Network Monitoring Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Network Monitoring Software Market Foresight
Modular subscription packaging is pivoting buyer choice away from perpetual licenses toward consumption-based network observability stacks. Cisco Systems, Inc. leverages its hardware-software integration to anchor enterprise deployments across hybrid infrastructure. SolarWinds Corporation sustains mid-market share through channel density and simplified deployment workflows. Broadcom, Inc. competes via mainframe-adjacent network intelligence bundled with broader IT operations suites.
Global Network Monitoring Software encompasses agent-based and agentless systems that collect, analyze, and visualize packet-level and flow-level telemetry across physical, virtual, and containerized network elements, typically operating at millisecond-level granularity to detect anomalies, enforce SLAs, and trigger automated remediation workflows. Its primary commercial purpose is to minimize mean-time-to-resolution for connectivity degradations while preserving security posture across distributed architectures. Cloud-based deployment now captures the fastest expansion as enterprises retire fixed-capacity data center footprints, while on-premises solutions retain margin concentration in regulated verticals with data sovereignty constraints. Security monitoring solutions within the solution type dimension pull disproportionate R&D investment as threat surface expansion outpaces legacy signature-based detection.
FCC network reliability guidelines in the United States, EU NIS2 Directive requirements, and Japan METI cybersecurity frameworks collectively elevate minimum observability standards and compress vendor qualification timelines for network monitoring procurement. ISO/IEC 27001 and IEC 62443 certification demands further segment accessible supplier pools by compliance depth. Stakeholders must weigh cloud migration velocity against residual on-premises audit trail obligations when calibrating platform investment.
Market Dynamics
Cloud-native observability architectures are compressing deployment timelines from months to weeks, forcing incumbent vendors to rearchitect legacy platforms around containerized telemetry pipelines and API-first consumption models.
Growth Catalysts
- EU NIS2 Directive:The directive mandates real-time network visibility for critical infrastructure operators across energy, transport, and digital services, creating compliance-driven procurement cycles.
- Containerized workloads:Kubernetes-orchestrated environments generate ephemeral traffic patterns that legacy monitoring cannot capture, pulling investment toward flow-based telemetry engines.
- Financial services operational resilience mandates:Basel Committee guidelines and national bank regulators in the United States, Germany, and Japan require sub-second anomaly detection for payment networks.
Market Restraints
- Specialized engineering talent scarcity:Packet-level analysis and eBPF programming skills concentrate among candidates with carrier-grade network operations backgrounds, inflating implementation costs.
- Data sovereignty fragmentation:Divergent national data localization requirements in China, Russia, and Saudi Arabia force vendors to maintain parallel infrastructure stacks, eroding platform economics.
- Legacy SNMP dependency:Brownfield industrial networks in manufacturing and utilities rely on aging protocol stacks that resist cloud-native instrumentation without hardware replacement.
Strategic Opportunities
- India's Smart Cities Mission:Metropolitan fiber deployments in Mumbai, Bangalore, and Hyderabad generate demand for unified physical and logical network visibility across municipal infrastructure.
- 5G standalone core observability:Service-based architecture telemetry requirements create greenfield deployment windows as carriers retire non-standalone implementations.
- Outcome-based consumption models:Uptime-guarantee contracts tied to mean-time-to-resolution metrics displace seat-based licensing in mid-market managed service provider channels.
Industry Challenges
- eBPF instrumentation expertise gaps:Kernel-level telemetry programming requires specialized Linux systems engineering capabilities that outpace standard DevOps training pipelines.
- Multi-cloud correlation complexity:Organizations operating across AWS, Azure, and GCP environments struggle to normalize flow records into unified topological views without vendor-specific data silos.
- IEC 62443 certification timelines:Industrial cybersecurity certification for network monitoring agents extends product release cycles by 8-14 months in energy and manufacturing verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Network Monitoring Software Market |
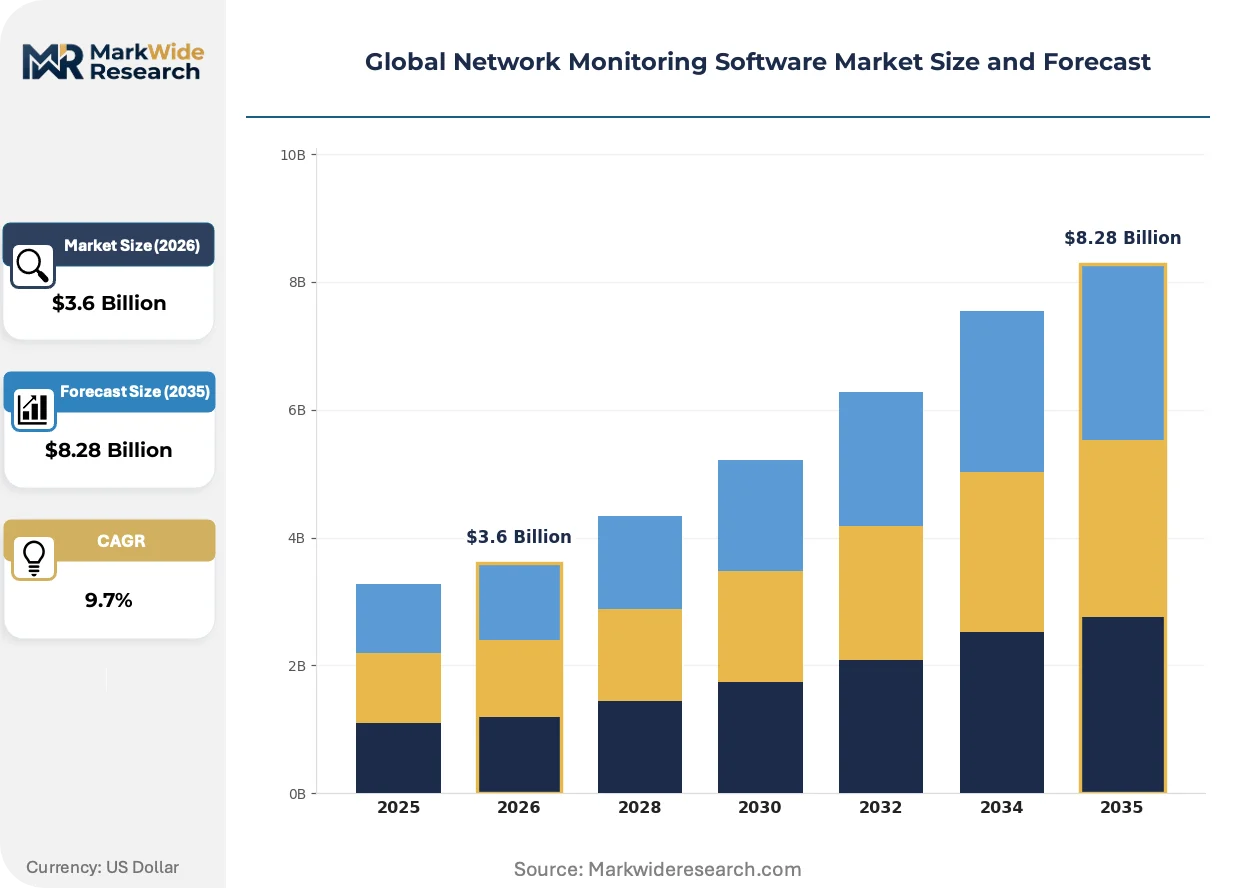
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $8.28 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Solution Type: Performance Monitoring, Fault Management, Security Monitoring, Traffic Analysis, Configuration Management Application: Enterprise Networks, Data Centers, Telecommunications, Service Providers, Government Agencies End User: Telecom Operators, Managed Service Providers, Large Corporations, Educational Institutions |
| Companies Covered | Cisco Systems, Inc., SolarWinds Corporation, Broadcom, Inc., Juniper Networks, Inc., NetScout Systems, Inc., IBM Corporation, Arista Networks, Inc., Keysight Technologies, Inc., Viavi Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Network Monitoring Software Market Shifts & Advancements
Telemetry processing is migrating from centralized collectors to edge-resident agents, collapsing the distance between detection and response while generating architectural tension with legacy analytics platforms.
eBPF-based kernel instrumentation is absorbing packet capture workloads that previously required dedicated hardware taps or mirror ports. Telecommunications carriers and hyperscale cloud operators are deploying these agents at line-rate across 100G+ interfaces. The technology is absorbing market share from traditional SPAN-based architectures by eliminating hardware dependency and enabling dynamic filtering without traffic disruption.
The EU NIS2 Directive's sectoral coverage expansion tightens baseline security requirements for DNS service providers, cloud computing services, and data center operators. Member states must transpose these obligations into national law by October 2024, compressing vendor qualification timelines. German critical infrastructure operators are responding by mandating ISO/IEC 27001 certification as a minimum procurement threshold, narrowing accessible supplier pools.
Enterprise buyers are consolidating network and security observability procurement under single platform decisions, collapsing the traditional separation between NetOps and SecOps tooling budgets. Managed detection and response providers are capturing this consolidation by bundling network telemetry with endpoint and identity analytics. This pattern is most visible in United States financial services and healthcare verticals where CISOs hold expanded vendor consolidation authority.
Global Network Monitoring Software Market Segmentation
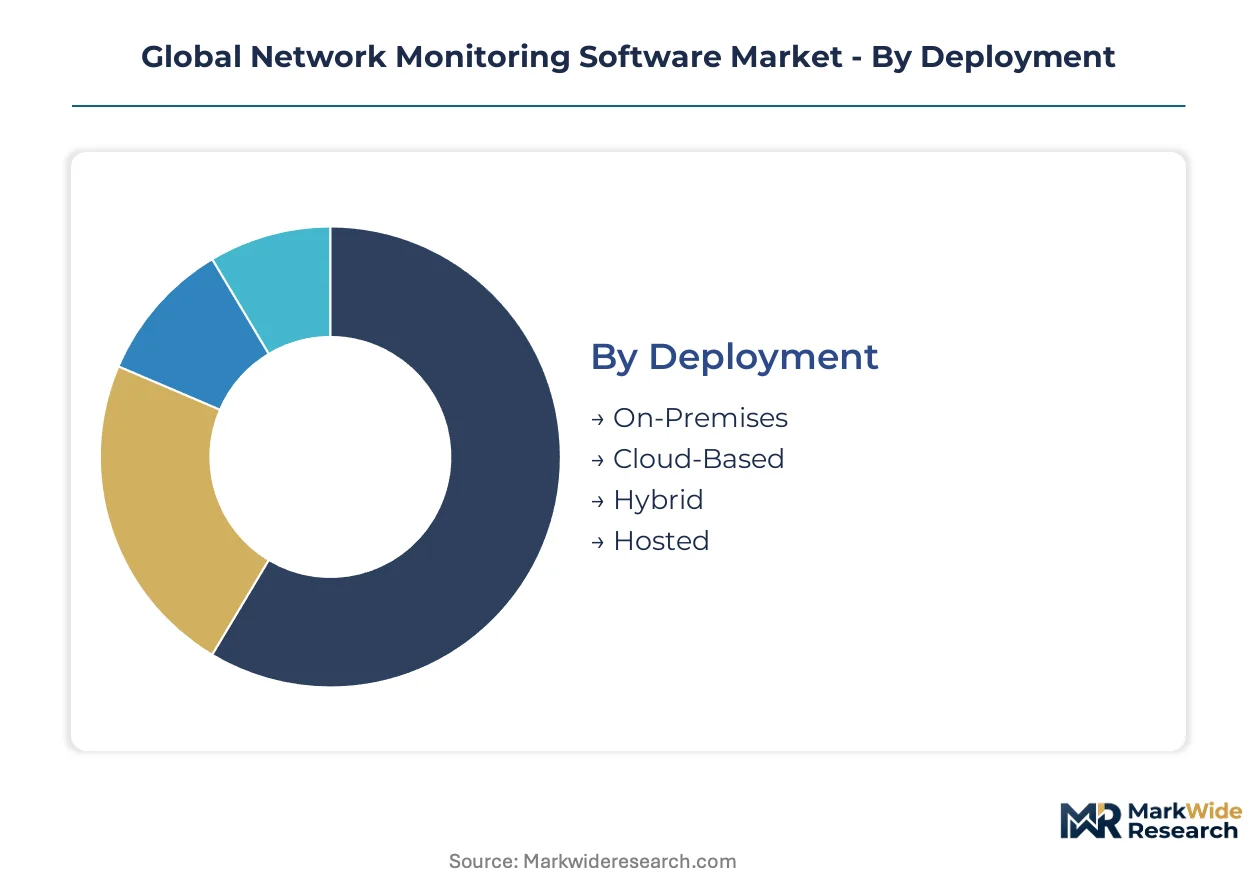
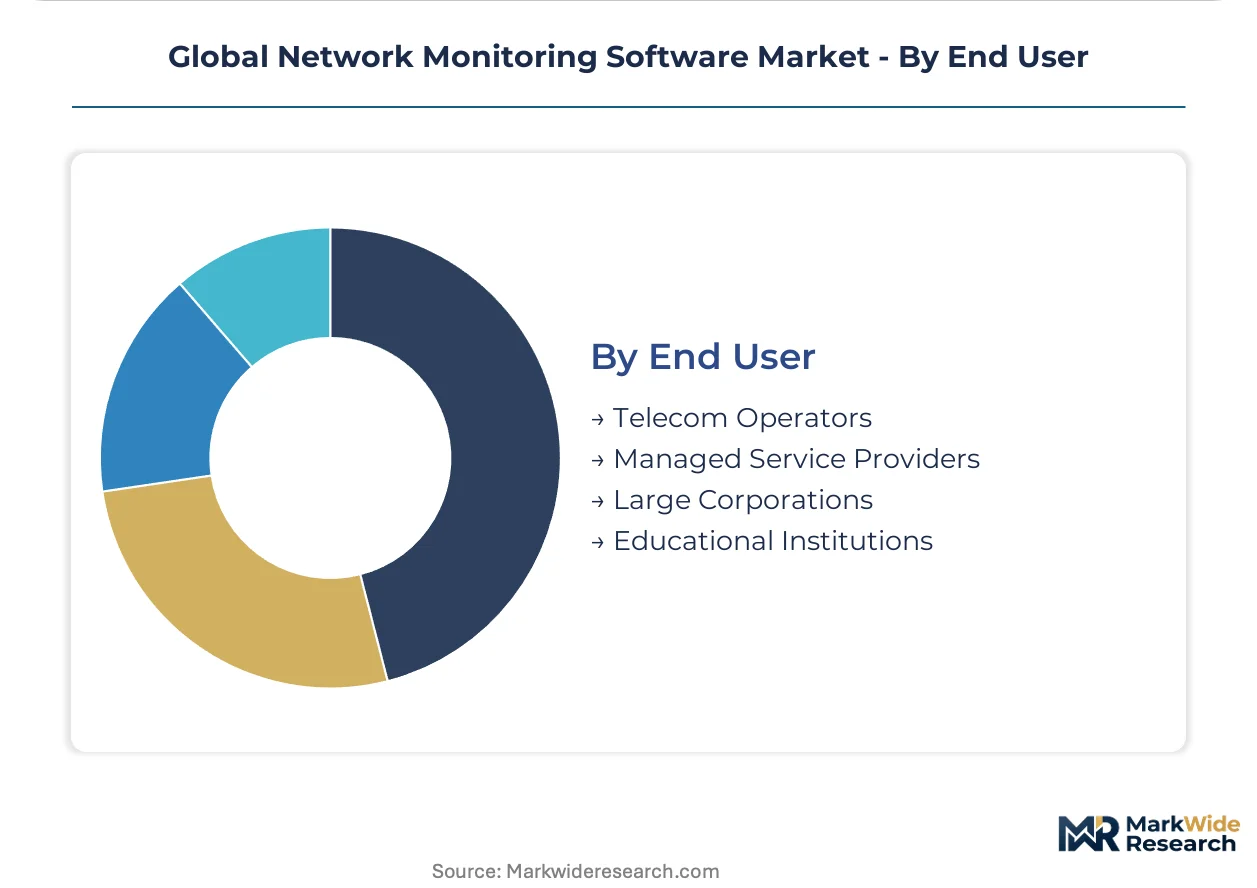
Network monitoring software procurement splits across four structural dimensions that determine integration architecture, pricing models, and vendor qualification requirements. Deployment mode dictates data sovereignty compliance paths. Solution type governs whether buyers consolidate under unified platforms or maintain specialized tooling. Application context and end-user scale together shape feature depth and support tier negotiations.
Deployment:
Integration depth varies sharply: cloud-based and hosted configurations embed monitoring as a managed service layer, while on-premises and hybrid deployments demand deeper systems integration with existing infrastructure stacks.
- On-Premises:Software installs within buyer-controlled data centers or private facilities, requiring dedicated hardware provisioning and internal operational maintenance. Regulated verticals in Germany and Japan mandate this mode for financial services and critical infrastructure operators subject to data residency audits.
- Cloud-Based:Fully managed SaaS delivery eliminates local infrastructure burden while enabling elastic capacity scaling. United States enterprises pursuing rapid cloud migration dominate procurement, though latency constraints limit adoption for sub-millisecond anomaly detection use cases.
- Hybrid:Split architectures retain sensitive telemetry on-premises while pushing analytics workloads to cloud substrates. This configuration absorbs the fastest procurement growth as enterprises balance sovereignty requirements against operational flexibility.
- Hosted:Single-tenant dedicated instances managed by vendors or third-party providers deliver isolation without internal operational overhead. Mid-market buyers in Japan favor this model for reduced certification complexity.
On-premises retains the largest installed base; hybrid is expanding most quickly as enterprises navigate compliance-versus-agility tradeoffs.
Solution Type:
Cost tier segmentation separates premium security-integrated platforms from standard performance tooling, with fault management occupying a mid-tier position based on automation depth.
- Performance Monitoring:Baseline telemetry collection tracking latency, throughput, packet loss, and jitter across network paths. Large corporations in the United States deploy these tools most intensively to enforce internal SLAs and cloud provider accountability.
- Security Monitoring:Threat detection engines correlating network flows with behavioral baselines and threat intelligence feeds. This segment pulls disproportionate R&D investment as NIS2 Directive compliance deadlines compress vendor qualification timelines across European critical infrastructure.
- Fault Management:Automated root-cause analysis and ticketing integration reducing mean-time-to-resolution. Telecom operators prioritize this capability for subscriber-facing service restoration commitments.
- Traffic Analysis:Deep packet inspection and flow record analytics for capacity planning and anomaly detection. Data center operators leverage these tools for east-west traffic visibility in virtualized environments.
- Configuration Management:Network device state tracking, change validation, and policy compliance enforcement. Government agencies mandate this capability for audit trail completeness under federal cybersecurity frameworks.
Performance monitoring leads volumes today; security monitoring is gaining share fastest.
Application:
Customer type maturity separates established enterprise buyers with consolidated procurement authority from fragmented service provider markets with decentralized decision structures.
- Enterprise Networks:Campus and branch infrastructure monitoring spanning SD-WAN, wireless, and wired segments. Large corporations in Germany drive premium pricing for unified physical and logical visibility platforms.
- Data Centers:High-density telemetry requirements covering spine-leaf architectures, software-defined networking, and containerized workloads. Hyperscale operators in the United States and Japan demand 100G+ line-rate processing capabilities.
- Telecommunications:Carrier-grade fault management and service assurance for core, transport, and access networks. 5G standalone core deployments are creating greenfield procurement windows as operators retire legacy probe architectures.
- Service Providers:Multi-tenant monitoring platforms enabling managed network services delivery to downstream clients. Managed service providers in the United States are consolidating NetOps and SecOps tooling budgets under single-vendor relationships.
- Government Agencies:Classified and unclassified network visibility with enhanced audit and compliance documentation. Federal mandates in the United States and EU NIS2 transpositions are elevating minimum observability standards.
Enterprise networks lead volumes today; data center applications are expanding most quickly.
End User:
Volume concentration clusters in telecom and managed service provider channels, while margin capture favors large corporations with customized integration requirements.
- Telecom Operators:National and regional carriers requiring carrier-grade scalability and five-nines reliability guarantees. These buyers dominate procurement of flow-based telemetry engines for 5G service-based architectures.
- Managed Service Providers:Outsourced network operations vendors delivering monitoring-as-a-service to mid-market clients. Outcome-based contracts tied to uptime metrics are displacing seat-based licensing in this channel.
- Large Corporations:Fortune 500 and equivalent enterprises with dedicated NetOps teams and multi-vendor environments. These buyers consolidate procurement authority under CISO-led platform decisions in financial services and healthcare verticals.
- Educational Institutions:Universities and research networks with high-bandwidth requirements and limited operational staffing. These buyers favor simplified deployment workflows and channel-driven support models.
Telecom operators lead volumes today; managed service providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Network monitoring software originated in carrier-grade telecommunications environments across the United States and Japan during the 1990s, then migrated into enterprise data centers as virtualization expanded. Early protocol analysis tools developed at Bell Labs and NTT laboratories established foundational architectures still visible in contemporary telemetry engines.
United States
Hyperscale cloud operators in Northern Virginia and Seattle drive demand for 100G+ line-rate observability as AWS, Azure, and GCP expand fiber footprints. FCC network reliability guidelines enforce minimum uptime standards for broadband infrastructure operators. Financial services firms in New York and Chicago deploy sub-millisecond anomaly detection for payment network compliance.
Germany
Critical infrastructure operators in energy and transport sectors procure unified physical-logical visibility platforms under EU NIS2 Directive transposition deadlines. The Federal Office for Information Security mandates ISO/IEC 27001 certification as a baseline procurement threshold. Industrial manufacturers in Baden-Württemberg and Bavaria retrofit brownfield SNMP networks with hybrid cloud-native instrumentation.
Japan
Telecommunications carriers in Tokyo and Osaka invest in 5G standalone core observability as NTT DoCoMo and KDDI retire non-standalone implementations. METI cybersecurity frameworks elevate minimum observability standards for critical infrastructure operators. Financial institutions in the Tokyo financial district deploy real-time network visibility tools under Bank of Japan operational resilience guidance.
India
Metropolitan fiber deployments under the Smart Cities Mission generate demand for unified municipal network visibility across Mumbai, Bangalore, and Hyderabad. The Indian Computer Emergency Response Team issues mandatory incident reporting timelines that compress vendor qualification cycles. IT services providers in Hyderabad and Pune bundle network monitoring into managed service offerings for mid-market enterprises.
United Kingdom
Financial services regulators in London enforce Basel Committee operational resilience guidelines requiring real-time payment network monitoring. The National Cyber Security Centre mandates enhanced logging and telemetry standards for critical national infrastructure operators. Data center operators in Slough and Manchester deploy cloud-native observability stacks to support multi-tenant colocation services.
Global Network Monitoring Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across deployment complexity and certification depth, with tiered pricing separating certified security-integrated platforms from standard performance tooling. The vendor base clusters around three strategic archetypes: hardware-integrated incumbents anchoring hybrid infrastructure deployments, channel-dense specialists serving mid-market simplified workflows, and mainframe-adjacent platforms bundling network intelligence with broader IT operations suites. Dominant competitive moves include rearchitecting legacy platforms around containerized telemetry pipelines and consolidating NetOps-SecOps procurement authority under single-vendor relationships.
Within the hardware-integrated tier, Cisco Systems, Inc. and Juniper Networks, Inc. exemplify vendors leveraging silicon-software co-design to anchor enterprise deployments across distributed architectures. SolarWinds Corporation occupies a position within the channel-dense mid-market specialist archetype, while Broadcom, Inc. sits within the mainframe-adjacent platform category. These three companies represent distinct margin-capture strategies rather than overlapping competitive positioning, with each anchoring separate buyer segments based on infrastructure maturity and compliance burden.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| SolarWinds Corporation |
| Broadcom, Inc. |
| Juniper Networks, Inc. |
| NetScout Systems, Inc. |
| IBM Corporation |
| Arista Networks, Inc. |
| Keysight Technologies, Inc. |
| Viavi Solutions, Inc. |
| Others |
Supply & Pricing Matrix
Vertical integration into hardware-software co-design anchors supply positioning and pricing power for incumbents serving carrier-grade deployments, while modular SaaS delivery erodes traditional license economics across mid-market channels. Cisco Systems and Juniper Networks leverage silicon-software stacks to command premium positioning, whereas pure-play software vendors face compression from consumption-based alternatives.
Pricing Analysis
Consumption-based subscription tiers stratify across premium security-integrated platforms, standard performance tooling, and economy-grade fault management modules. Price differentiation rests on ISO/IEC 27001 certification depth and eBPF instrumentation capability, with certified vendors capturing 40-60% premiums over uncertified alternatives. Cost compression in standard tiers intensifies as channel-dense specialists automate deployment workflows. Mid-market managed service providers exhibit highest price sensitivity; hyperscale cloud operators in the United States demonstrate lowest sensitivity due to uptime-guarantee contract structures.
Supply Chain Analysis
Kernel-level telemetry engineering talent concentrates in the United States, Germany, and India, constraining platform development velocity for vendors lacking carrier-grade network operations heritage. Software supply chains draw from open-source eBPF runtimes, commercial packet capture libraries, and cloud-native observability frameworks. Single-source vulnerability in specialized Linux systems engineering creates qualification bottlenecks for IEC 62443 certification timelines. Distribution runs through direct enterprise sales for large corporations, channel partners for mid-market penetration, and managed service providers for outcome-based consumption models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Network Monitoring Software Market represents a late-cycle quality story as buyers consolidate procurement authority under CISO-led platform decisions favoring security-integrated observability stacks over fragmented tooling.
For Market Incumbents: To counter cloud-native entrant disruption, anchor enterprise deployments through hardware-software integration depth while accelerating containerized telemetry pipeline rearchitecture. Invest in eBPF instrumentation R&D to defend against kernel-level telemetry specialists. Prioritize ISO/IEC 27001 and IEC 62443 certification maintenance to narrow accessible supplier pools under EU NIS2 Directive procurement thresholds.
For New Entrants and Emerging Players: EU NIS2 Directive in Germany opens a window for security-monitoring specialists targeting critical infrastructure operators with accelerated vendor qualification cycles. India's Smart Cities Mission metropolitan fiber deployments present underpenetrated demand for unified municipal network visibility. Pursue outcome-based managed service provider channel partnerships to bypass direct enterprise sales cost structures.
For Investors and Strategic Acquirers: Roll-up economics work for security-integrated observability platforms because enterprise buyers are collapsing NetOps and SecOps tooling budgets under single-vendor relationships. Target mid-market specialists with channel density and simplified deployment workflows as acquisition candidates. Monitor 5G standalone core deployment velocity as inflection indicator for carrier-grade telemetry engine demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates NetOps and SecOps budgets under single-vendor relationships in United States financial services. |
| Acquisition of Specialist Firm | Captures eBPF instrumentation expertise concentrated among candidates with carrier-grade network operations backgrounds. |
| Product Launch | Addresses Kubernetes-orchestrated ephemeral traffic patterns that legacy monitoring architectures cannot capture. |
| Strategic Partnership | Enables managed detection and response providers to bundle network telemetry with endpoint analytics. |
| Geographic Expansion | Targets India's Smart Cities Mission metropolitan fiber deployments across Mumbai, Bangalore, and Hyderabad. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down vendor revenue tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and managed service provider channel heads combined with secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory transposition documents. Triangulation across stakeholder inputs and published data sources ensures segmentation integrity across deployment modes, solution types, and end-user scales.
Historical trendline analysis of cloud migration velocity and compliance-driven procurement cycles informs the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size, vertical regulatory burden, integration complexity, and regional adoption pattern. CAGRs derive from elasticity-adjusted demand curves incorporating 5G standalone core deployment schedules and NIS2 Directive transposition timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under data sovereignty fragmentation and specialized engineering talent scarcity. Practitioners should monitor IEC 62443 certification timeline compression and multi-cloud correlation complexity resolution for early signals of vendor consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Load Balancer Market
Digital Solutions
File Sharing Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Video Management System Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
North America API Management Market
Digital Solutions
Microservices Architecture Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Master Data Management Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Cloud Backup and Recovery Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
On-Demand Warehousing Platforms Market