
 Digital Commerce Software Market | 2026-2036
Digital Commerce Software Market Size, Share, and Industry Trends Forecast 2026-2036
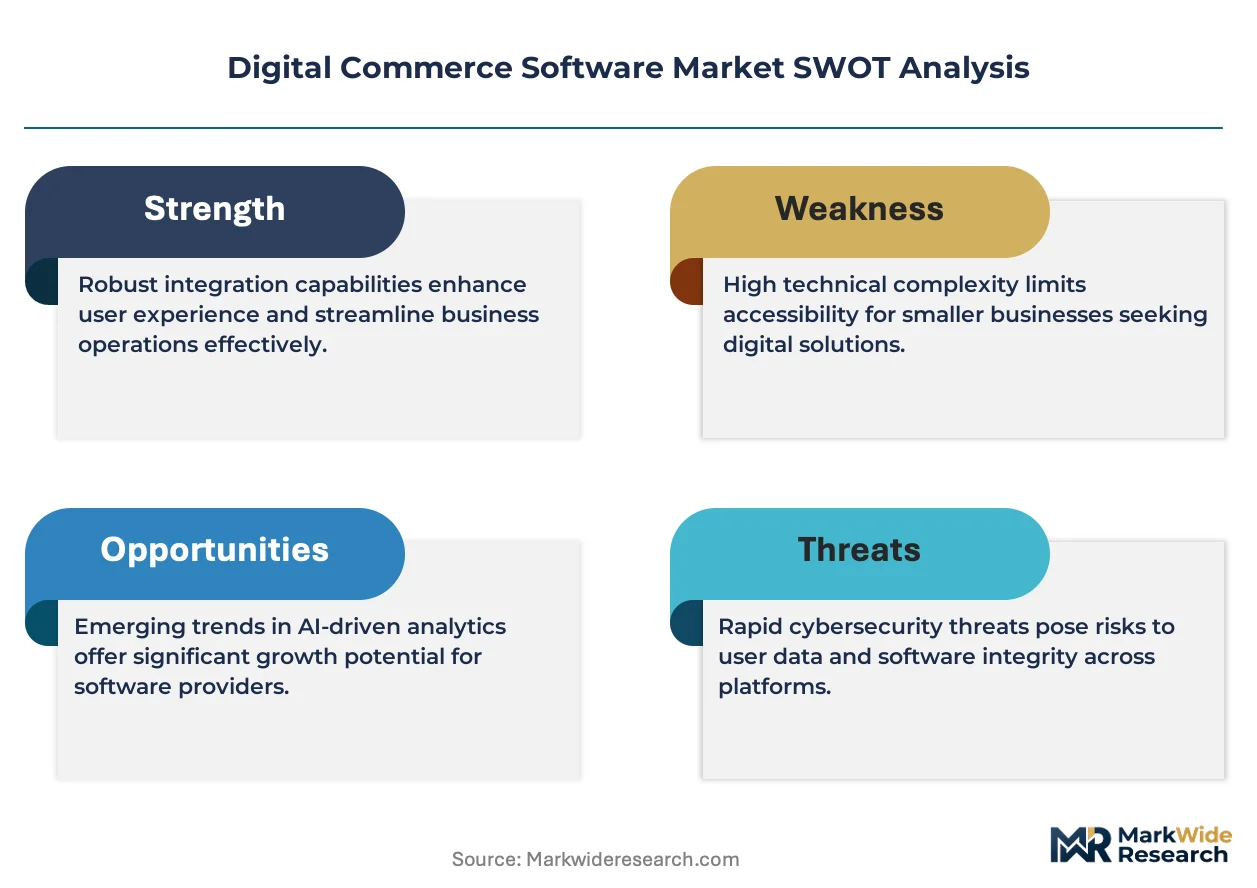
Digital Commerce Software Market Analysis
Multi-source vendor strategies is consolidating as enterprises reduce dependency on monolithic suites. Salesforce Commerce Cloud leverages its CRM-native architecture to anchor enterprise accounts seeking unified customer data layers. commercetools competes through API-first modularity, allowing retailers to compose best-of-breed stacks without full-platform lock-in. Shopify dominates the mid-market and D2C segment through embedded payments and logistics orchestration.
Digital commerce software encompasses the application layer enabling online transaction processing, inventory synchronization, and customer journey orchestration across touchpoints, typically deployed via RESTful APIs and microservices architectures that support sub-100-millisecond response thresholds for checkout flows. E-commerce Platforms and Payment Gateways together capture the majority of current spend, with cloud-based deployment outpacing on-premises installations as merchants prioritize elastic infrastructure for seasonal demand spikes. B2B customer types are expanding fastest as wholesale buyers expect consumer-grade purchasing interfaces with contract pricing and punchout integration.
The US Federal Trade Commission scrutinizes platform fee structures and data usage practices, while the EU's Digital Services Act imposes transparency obligations on marketplace operators that ripple through software procurement requirements. ISO 27001 and SOC 2 Type II certifications have become baseline gating factors for vendor selection in financial services and healthcare-adjacent retail. Stakeholders must evaluate whether their current commerce architecture can absorb emerging AI-driven personalization engines without compromising audit-ready data lineage.
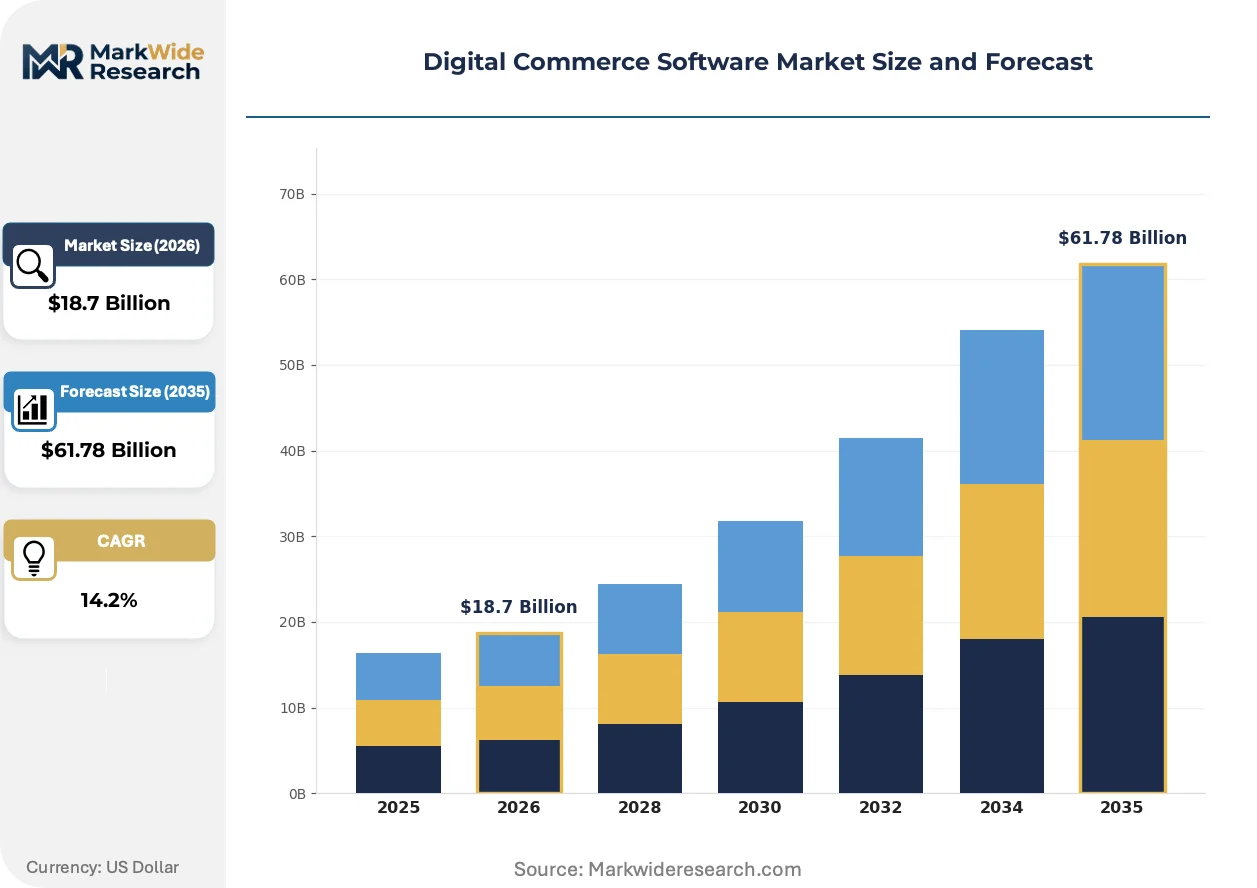
Market Dynamics
Cloud-native microservices architectures are compressing replacement cycles for monolithic commerce suites as enterprises prioritize elastic infrastructure and API composability over single-vendor lock-in.
Growth Catalysts
- GDPR and state-level US privacy laws:Merchants are rebuilding checkout flows to embed consent management and data lineage tracking, creating replacement demand for compliant commerce stacks.
- Headless commerce adoption:Retailers are decoupling front-end presentation layers from back-end transaction engines using GraphQL and REST APIs, enabling faster channel experimentation.
- B2B wholesale digitization:Industrial distributors are deploying punchout-capable procurement portals with contract pricing engines to match consumer-grade purchasing experiences.
Market Restraints
- ISO 27001 and SOC 2 Type II certification costs:Smaller vendors face six-figure audit expenses and 12-18 month compliance timelines that constrain market entry in financial services and healthcare-adjacent retail.
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud control the underlying compute layer for most SaaS commerce deployments, creating single-point-of-failure exposure during regional outages.
- Legacy ERP integration complexity:On-premises SAP and Oracle systems require custom middleware development that extends implementation timelines and inflates professional services costs.
Strategic Opportunities
- AI-driven personalization engines:Machine learning recommendation systems that operate on first-party data are creating new software attach rates for commerce platforms serving enterprise merchants.
- Embedded finance convergence:Commerce software is integrating buy-now-pay-later, insurance, and working capital products directly into checkout flows, capturing interchange revenue streams.
- India and Southeast Asia B2C expansion:Mobile-first commerce adoption in these markets is outpacing legacy infrastructure capacity, creating greenfield opportunities for cloud-native platform providers.
Industry Challenges
- Platform engineering talent scarcity:Kubernetes and event-driven architecture expertise commands premium compensation that stretches vendor R&D budgets and implementation partner capacity.
- Multi-cloud orchestration complexity:Enterprises distributing workloads across AWS, Azure, and Google Cloud require specialized site reliability engineering that most mid-market IT organizations lack.
- Real-time inventory synchronization:Sub-100-millisecond consistency across distributed order management systems demands sophisticated conflict resolution algorithms that strain legacy database architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Commerce Software Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: E-commerce Platforms, Payment Gateways, Shopping Cart Software, Marketing Automation Tools Deployment: Cloud-Based, On-Premises, Hybrid, API-Integrated End User: Retailers, Wholesalers, Brand Owners, Third-Party Sellers Customer Type: B2C, B2B, C2C, D2C |
| Companies Covered | Salesforce Commerce Cloud, commercetools, Shopify, SAP Commerce Cloud, Shopify Plus, Adobe Commerce, WooCommerce, HCL Commerce, BigCommerce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Commerce Software Market Emerging Trajectories
Composability is displacing monolithic platform consolidation as the dominant architectural philosophy, with merchants assembling best-of-breed components through API marketplaces rather than accepting bundled suites.
Edge computing nodes are integrating transaction processing and personalization inference closer to end users, reducing latency for mobile checkout flows. Large apparel and grocery retailers with high seasonal traffic volatility are deploying these distributed architectures most aggressively. The structural result is compressing reliance on centralized cloud regions for time-sensitive commerce operations.
The EU Digital Services Act imposes algorithmic transparency and risk assessment obligations on marketplace operators that use automated recommendation systems. Software procurement contracts now mandate audit trails for ranking parameters and content moderation decisions. Enterprise merchants operating hybrid B2B-B2C models are most affected, with legal teams rewriting vendor agreements to allocate compliance liability.
Subscription and recurring revenue models are displacing perpetual license structures across mid-market commerce software procurement. Merchants prefer consumption-based pricing that scales with transaction volume rather than upfront capital commitments. This shift is most visible in direct-to-consumer verticals where CFOs prioritize cash flow flexibility over depreciation schedules.
Digital Commerce Software Market Segmentation
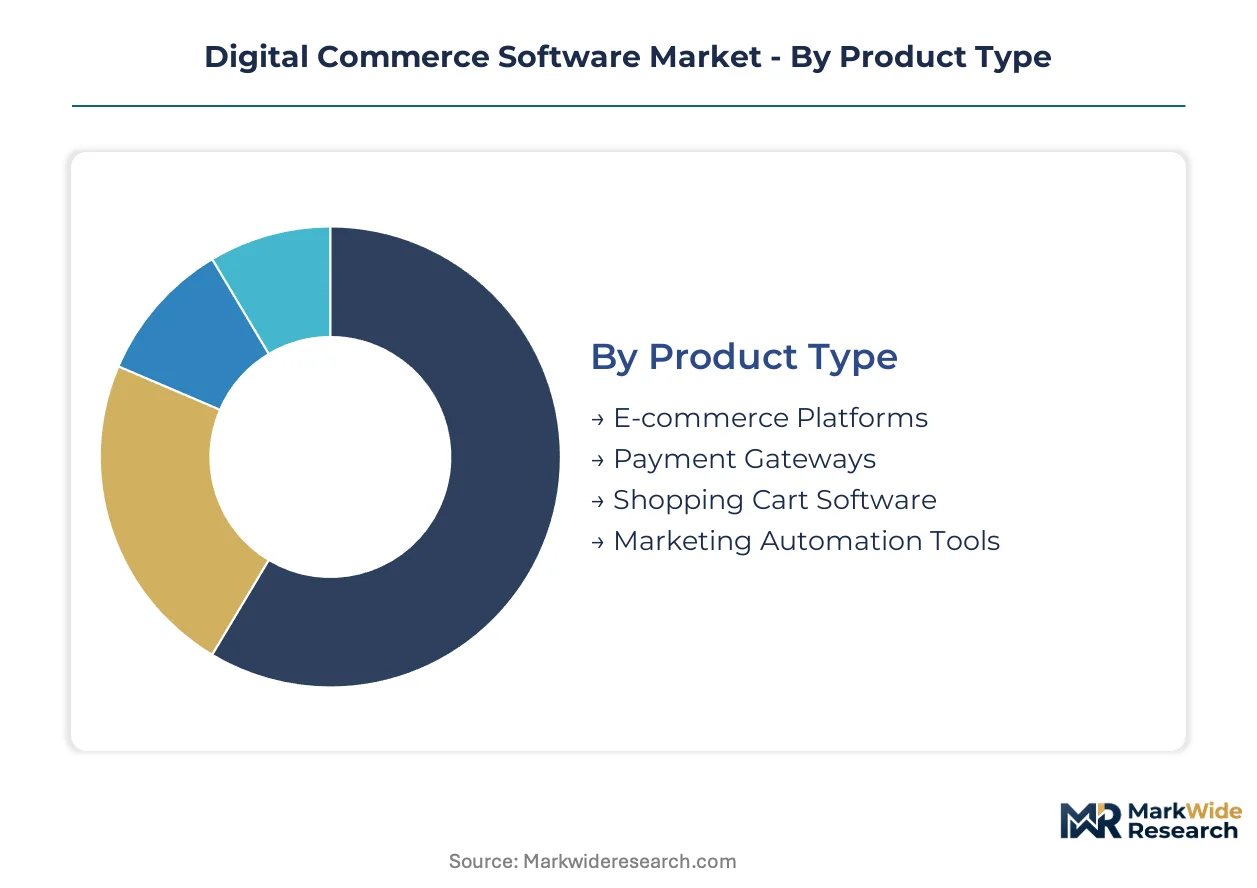
Segmentation reveals how compliance requirements and infrastructure choices fragment procurement patterns across merchant types. Certification burdens and deployment architectures create distinct purchasing clusters that vendors must address separately.
Product Type:
ISO 27001 and SOC 2 Type II certifications gate entry for E-commerce Platforms and Payment Gateways serving financial services and healthcare-adjacent retail, while Marketing Automation Tools face lighter audit requirements.
- E-commerce Platforms:Core transaction engines orchestrate inventory synchronization, checkout flows, and customer journey management through microservices architectures. Enterprise merchants in the United States migrating off legacy on-premises systems drive replacement demand for compliant cloud-native stacks.
- Payment Gateways:PCI-DSS Level 1 certification forms the baseline for processing card-not-present transactions, with tokenization and 3D Secure 2.0 now standard. GDPR and state-level US privacy laws are accelerating rebuilds to embed consent management and data lineage tracking.
- Shopping Cart Software:Lightweight checkout modules prioritize sub-100-millisecond response thresholds for mobile conversion optimization.
- Marketing Automation Tools:Campaign orchestration systems integrate with commerce stacks via RESTful APIs, facing lighter regulatory certification than payment-adjacent software.
E-commerce Platforms sits at the top of the volume ranking, with Payment Gateways climbing the fastest.
Deployment:
Cost tiering separates enterprise-grade elastic infrastructure from constrained mid-market budgets, with professional services attach rates varying dramatically across deployment modes.
- Cloud-Based:SaaS delivery via AWS, Azure, or Google Cloud enables seasonal elasticity without capital commitment. Retailers expanding adoption of cloud-native commerce stacks to unify omnichannel fulfillment favor this model for demand spike absorption.
- API-Integrated:Headless architectures decouple front-end presentation from back-end transaction engines using GraphQL and REST APIs. Composable stacks allow faster channel experimentation without full-platform lock-in.
- Hybrid:Split workloads maintain sensitive data on-premises while pushing scalable operations to public cloud regions.
- On-Premises:Legacy installations persist in highly regulated sectors requiring air-gapped environments, though replacement cycles compress as compliance burdens shift to cloud providers.
Cloud-Based deployment captures the dominant share, while API-Integrated configurations gain share fastest among enterprise replatforming projects.
End User:
Application complexity scales with transaction volume and channel diversity, with Brand Owners and Third-Party Sellers presenting divergent integration requirements.
- Retailers:Multi-channel merchants require distributed order management with real-time inventory synchronization across physical and digital touchpoints. Large apparel and grocery retailers with high seasonal traffic volatility deploy edge computing nodes most aggressively.
- Wholesalers:Industrial distributors deploy punchout-capable procurement portals with contract pricing engines to match consumer-grade purchasing experiences.
- Brand Owners:Direct-to-consumer verticals prioritize subscription and recurring revenue models with consumption-based pricing that scales with transaction volume.
- Third-Party Sellers:Marketplace operators face EU Digital Services Act obligations for algorithmic transparency and risk assessment on automated recommendation systems.
Retailers holds the volume lead, with Wholesalers expanding most quickly as B2B wholesale digitization accelerates.
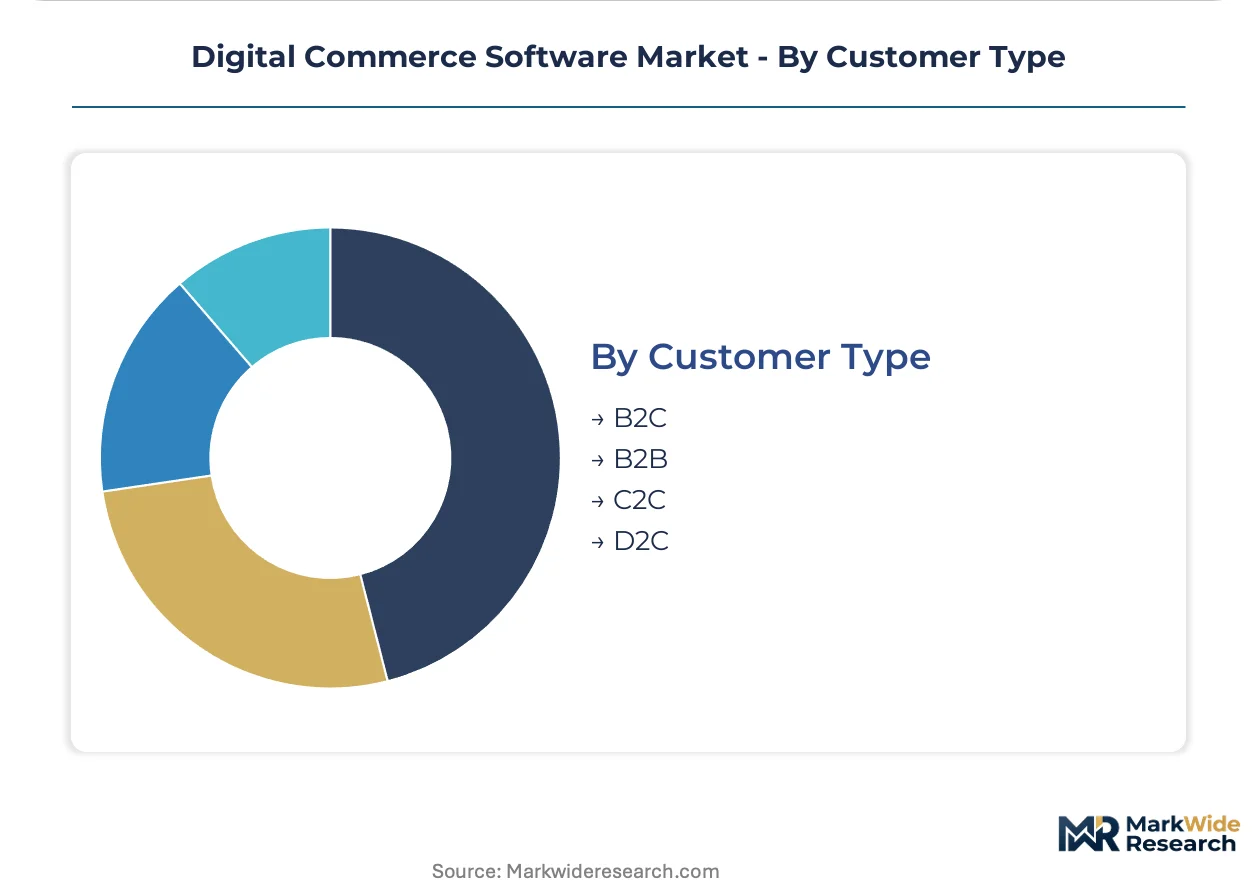
Customer Type:
Margin profiles differ sharply between transaction-heavy B2C and contract-negotiated B2B relationships, with D2C merchants demanding the greatest pricing flexibility.
- B2B:Wholesale buyers expect consumer-grade purchasing interfaces with contract pricing, punchout integration, and approval workflow engines. This segment is expanding fastest as procurement digitization penetrates industrial distribution.
- D2C:Brand-direct merchants prioritize embedded payments and logistics orchestration with consumption-based pricing that preserves cash flow flexibility.
- B2C:Traditional retail-to-consumer transactions concentrate spend in payment processing and marketing automation attach rates.
- C2C:Peer-to-peer marketplace infrastructure requires lighter compliance overhead, though platform operators still face FTC scrutiny on fee structures and data usage practices.
B2C maintains the largest installed base, with B2B posting the steepest expansion trajectory as enterprise procurement modernizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors enterprise demand for cloud-native commerce stacks as US merchants accelerate replatforming off legacy on-premises systems. The FTC scrutinizes platform fee structures and data usage practices across state-level privacy law variations. Regulatory divergence between jurisdictions is fragmenting vendor procurement requirements.
United States
Enterprise merchants in New York and Chicago drive replacement demand for compliant checkout architectures with embedded consent management. The FTC and state-level privacy laws in California and Virginia accelerate rebuilds for data lineage tracking. Seattle's cloud infrastructure cluster hosts the majority of SaaS commerce deployments on AWS and Azure.
Germany
Industrial distributors in Bavaria and North Rhine-Westphalia deploy punchout-capable procurement portals with contract pricing engines. GDPR mandates from the EU and Germany's BSI cybersecurity standards gate vendor selection for financial services commerce. Berlin's startup ecosystem incubates API-first commerce specialists targeting mid-market manufacturers.
United Kingdom
London's fintech corridor demands PCI-DSS Level 1 certified payment gateways with tokenization for card-not-present transactions. The UK's implementation of GDPR and Digital Services Act obligations reshapes marketplace operator procurement. Manchester's retail technology cluster concentrates headless commerce experimentation among apparel merchants.
India
Maharashtra and Karnataka host mobile-first commerce adoption outpacing legacy infrastructure capacity in B2C verticals. RBI payment regulations and emerging data protection frameworks constrain foreign platform operations. Bangalore's SaaS ecosystem produces cloud-native specialists serving Southeast Asian expansion.
Japan
Tokyo's omnichannel retailers prioritize sub-100-millisecond response thresholds for mobile checkout optimization. METI's digital transformation incentives accelerate SME migration from legacy ERP-linked commerce systems. Osaka's industrial distributors modernize procurement interfaces to match consumer-grade purchasing experiences.
Digital Commerce Software Market Vendor Landscape
Global majors compete with regional champions across deployment architecture and customer segment specialization. The vendor base stratifies between CRM-anchored enterprise suites, API-first composable platforms, and embedded-payment mid-market solutions. Two strategic archetypes dominate: unified data-layer providers and best-of-breed stack assemblers. Competitive moves concentrate on M&A for AI personalization capabilities and strategic partnerships for embedded finance convergence.
Within the enterprise suite tier, Salesforce Commerce Cloud and SAP Commerce Cloud represent CRM-native and ERP-anchored archetypes respectively. Shopify and BigCommerce occupy positions across the mid-market and D2C segments with consumption-based pricing models. Commercetools exemplifies the API-first modular approach enabling retailer stack composition without full-platform dependency.
| Leading Market Players |
|---|
| Salesforce Commerce Cloud |
| commercetools |
| Shopify |
| SAP Commerce Cloud |
| Shopify Plus |
| Adobe Commerce |
| WooCommerce |
| HCL Commerce |
| BigCommerce |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure costs from AWS, Azure, and Google Cloud cascade through SaaS delivery models into tiered subscription pricing for enterprise merchants, while API call volumes and data residency requirements stratify procurement decisions across compliance-sensitive buyers.
Pricing Analysis
Input-cost pass-through from hyperscaler compute and storage rates shapes SaaS-tiered subscription models, with ISO 27001 and SOC 2 Type II certification tiers commanding premium positioning over uncertified alternatives. Price differentiation hinges on compliance grade and transaction volume scale, with enterprise merchants showing lowest sensitivity due to replacement cost inertia. Pricing pressure intensifies in the mid-market as consumption-based models compress upfront commitments. Small vendors face margin compression from six-figure audit expenses that larger platforms absorb through scale.
Supply Chain Analysis
Certification gating through PCI-DSS Level 1, ISO 27001, and SOC 2 Type II restricts viable supplier pools to vendors with audit-ready infrastructure, concentrating production-grade commerce stacks among Salesforce, commercetools, Shopify, and SAP. Geographic supply concentration centers on the United States, Germany, and India, with cloud-native specialists clustering in Berlin, Bangalore, and Silicon Valley. Raw material dependencies include Kubernetes orchestration expertise, GraphQL API frameworks, and edge computing nodes. Supply chain risk stems from single-source vulnerability in hyperscaler infrastructure during regional outages. Distribution runs through direct enterprise sales, systems integrator partnerships, and API marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where enterprise procurement favors audit-ready platforms over speculative architectures, with GDPR and state-level US privacy laws accelerating demand-shift toward compliant specifications.
For Market Incumbents: Cement platform stickiness through embedded AI personalization engines and embedded finance convergence that raises switching costs. Deepen vertical integration into edge computing infrastructure to reduce hyperscaler dependency. Defend against API-first modular challengers by expanding CRM-native data layer differentiation. Prioritize certification maintenance as competitive moat in financial services and healthcare-adjacent retail. For New Entrants and Emerging Players: The mid-market gap between Shopify's embedded-payment simplicity and Salesforce's enterprise complexity offers white-space for composable stack assemblers targeting B2B wholesale digitization. Target India's mobile-first commerce expansion where legacy infrastructure capacity lags adoption. Pursue partnership-first go-to-market with systems integrators lacking Kubernetes expertise for hybrid deployment orchestration. For Investors and Strategic Acquirers: Consolidation pressure builds where platform engineering talent scarcity and certification burdens strand sub-scale vendors. Long-term viability favors API-first specialists with demonstrated multi-cloud orchestration capabilities. Acquisition target archetype: mid-market platforms with existing ISO 27001 certification and established channel partner networks. Watch for inflection when edge computing deployment rates accelerate among large apparel and grocery retailers.| Strategic Initiative | Industry Significance |
|---|---|
| AI Personalization Engine Integration | Machine learning recommendation systems operating on first-party data create new attach rates for enterprise merchants. |
| Embedded Finance Convergence | Buy-now-pay-later and working capital products integrated into checkout flows capture interchange revenue streams. |
| Multi-Cloud Orchestration Partnership | Specialized site reliability engineering partnerships address enterprise distribution across AWS, Azure, and Google Cloud. |
| B2B Wholesale Portal Development | Punchout-capable procurement portals with contract pricing engines penetrate industrial distribution digitization. |
| Edge Computing Node Deployment | Distributed transaction processing reduces latency for mobile checkout flows among high-traffic seasonal retailers. |
Methodological Framework
Coverage spans the United States, Germany, United Kingdom, India, and Japan, with primary inputs from each market through structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners. Secondary validation draws from SEC filings, hyperscaler capex disclosures, App Annie mobile commerce data, and EU Digital Services Act implementation documents. Bottom-up merchant spend analysis triangulates against top-down vendor revenue aggregation.
Granularity-level modeling addresses deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic elasticity assumptions. Industry-specific forecast inputs include seasonal traffic volatility patterns and B2B procurement digitization penetration curves.
Caveats apply where regulatory enforcement intensity, hyperscaler pricing resets, or platform engineering wage inflation could materially shift the outlook. Forecasts reflect documented assumptions about compliance timeline acceleration and cloud migration velocity. A model refresh is warranted upon material change in FTC platform scrutiny or EU Digital Services Act liability allocation precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Farm Management Software Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Singapore System Integration Market
Digital Solutions
Europe Digital Pen Market
Digital Solutions
Germany Content Services Platform Market
Digital Solutions
Global Web Hosting Service Market