
 Global Freight Software Market | 2026-2036
Global Freight Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Freight Software Market Foresight
Platform licensing revenue is tilting from perpetual on-premise contracts toward recurring cloud subscriptions. SAP SE leverages its embedded ERP footprint to anchor multimodal freight workflows inside existing enterprise accounts. WiseTech Global sustains technology leadership in customs compliance automation across Asia-Pacific trade lanes. FourKites differentiates through real-time visibility networks that integrate with carrier ELD systems.
Freight software comprises modular applications that manage cargo movement across road, rail, ocean, and air modes through API-connected data layers, typically processing EDI, IoT sensor feeds, and blockchain-verified documentation to optimize load matching and transit predictability. Its primary commercial purpose is reducing empty-mile ratios and demurrage exposure while accelerating customs clearance cycles. Transportation Management solutions dominate value capture due to shipper willingness to pay for dynamic routing algorithms, while Cloud-Based deployment is expanding fastest as carriers retire legacy mainframe stacks. Warehouse Management functions occupy mature margin pools where robotic integration and yard management modules now drive replacement cycles.
The US FAA mandates electronic logging and safety telemetry standards that shape fleet management module requirements, while the EU AI Act imposes algorithmic transparency obligations on automated carrier matching and pricing engines. India's BIS cloud security certifications and China's MIIT data localization rules create divergent compliance architectures for vendors serving cross-border trade corridors. Stakeholders must monitor regulatory fragmentation between the EU Green Deal's emissions reporting mandates and the US EPA freight corridor electrification incentives, as these frameworks will determine which software modules become table stakes versus premium differentiators.
Market Dynamics
Cloud migration mandates from the EU AI Act and US FAA modernization directives are forcing freight software vendors to rearchitect compliance modules, while third-party logistics providers accelerate platform consolidation to unify fragmented multimodal data streams.
Growth Catalysts
- EU AI Act Algorithmic Transparency:Automated carrier matching engines now require explainable decision logic, creating procurement pull for vendors with embedded audit trails.
- Port Digitization Investments:Germany, India, and the United States are deploying blockchain-verified documentation systems that demand API-native freight platforms.
- ELD Integration:Real-time visibility networks that synchronize with carrier electronic logging devices are compressing empty-mile ratios across North American trucking corridors.
Market Restraints
- Data Localization Requirements:China's MIIT rules and India's BIS cloud security certifications force vendors to maintain redundant infrastructure stacks, elevating operational costs.
- Legacy Mainframe Dependencies:Major ocean carriers retain COBOL-based cargo management systems, creating integration friction that delays SaaS migration timelines.
- Cyber Insurance Escalation:Ransomware exposure in maritime logistics software has doubled premium burdens for mid-sized fleet management vendors.
Strategic Opportunities
- EU Green Deal Emissions Reporting:Carbon accounting modules that automate MRV (Monitoring, Reporting, Verification) compliance are becoming table stakes for European shipper RFPs.
- Warehouse Robotics Convergence:Yard management systems that orchestrate autonomous mobile robots and drone inventory counts represent underpenetrated premium tiers.
- India's Multimodal Corridor Buildout:Dedicated freight corridors linking Delhi-Mumbai and Chennai-Bengaluru require indigenous TMS platforms with localized customs automation.
Industry Challenges
- API Standardization Fragmentation:EDI X12, EDIFACT, and proprietary carrier formats coexist without unified protocols, forcing vendors to maintain expensive mapping layers.
- Embedded Systems Talent Scarcity:Shortage of engineers proficient in both industrial IoT sensor integration and maritime regulatory compliance is throttling product velocity.
- Cross-Border Certification Timelines:Dual compliance with US EPA freight corridor electrification incentives and EU CBAM carbon border adjustments extends sales cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Freight Software Market |
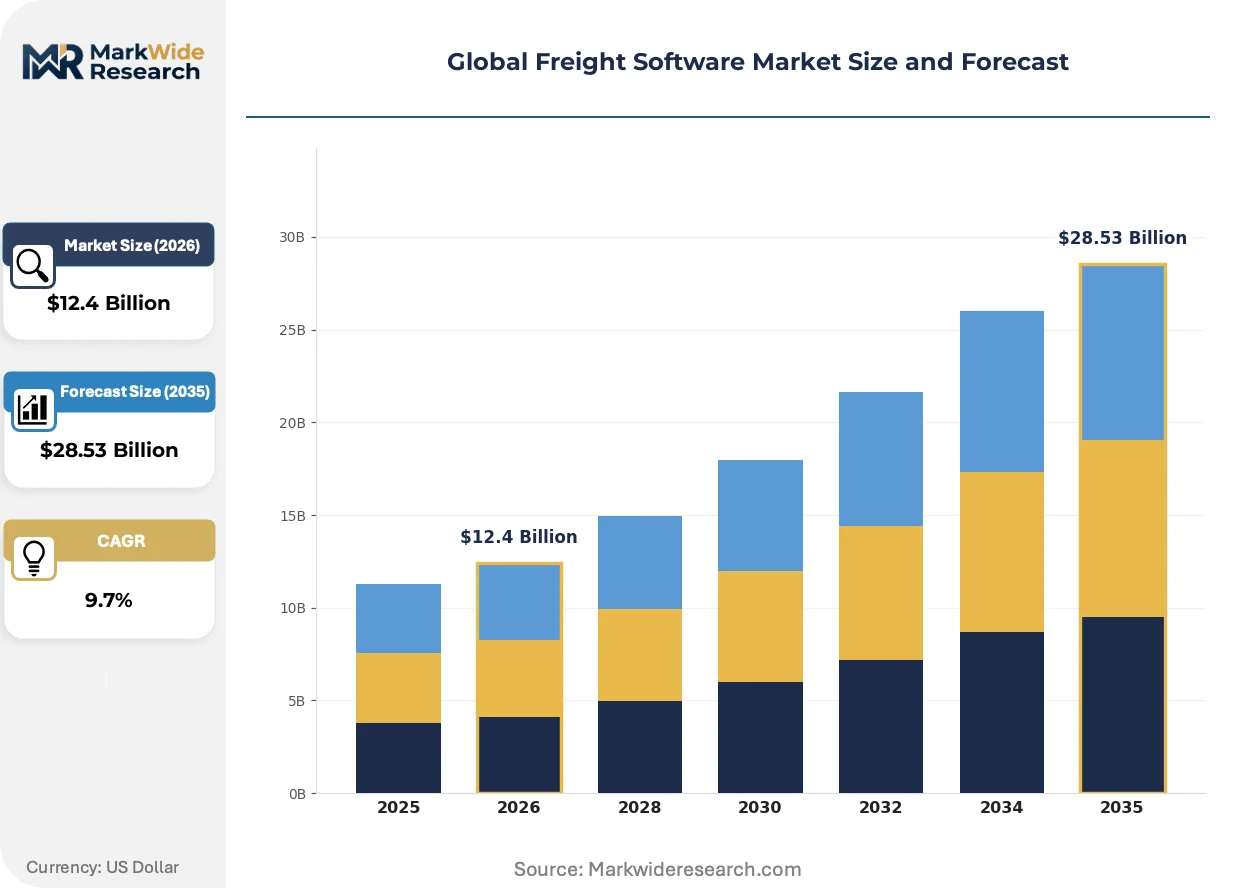
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Type: Transportation Management, Warehouse Management, Fleet Management, Freight Brokerage Application: Supply Chain Optimization, Route Planning, Inventory Visibility, Load Optimization, Carrier Management End User: Third-Party Logistics Providers, Freight Forwarders, Shipping Companies, E-commerce Firms, Retailers |
| Companies Covered | Descartes Systems Group, SAP SE, Oracle Corporation, e2open, Magaya Corporation, MercuryGate International, Infor, WiseTech Global, FourKites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Freight Software Market Shifts & Advancements
Freight software architecture is pivoting from monolithic suites toward composable microservices that embed compliance and visibility functions directly into shipper ERP workflows.
Transportation Management Systems are hybridizing machine learning-based dynamic routing with deterministic rule engines for customs clearance, enabling 3PLs to automate exception handling while retaining human oversight for high-value pharmaceutical and perishable cargo flows.
The EU AI Act's algorithmic transparency obligations are compelling vendors to deploy explainable AI modules that document carrier selection logic, with German and Dutch freight forwarders now requiring audit-ready decision trails as standard procurement criteria.
Shipper buying patterns are compressing contract renewal cycles from multi-year enterprise agreements to annual subscriptions with modular expansion rights, a shift most pronounced among US-based e-commerce fulfillment operators seeking flexibility amid tariff volatility and modal switching demands.
Global Freight Software Market Segmentation
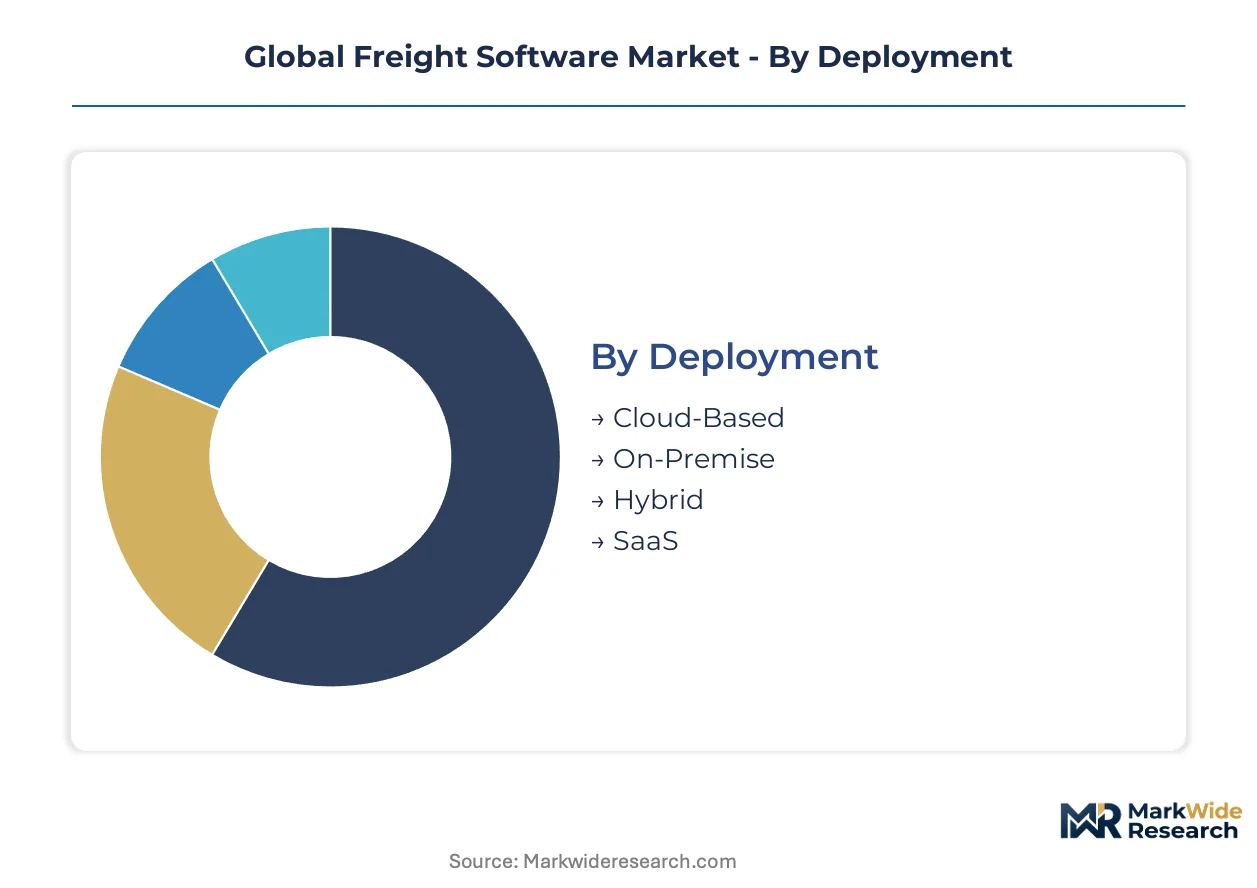
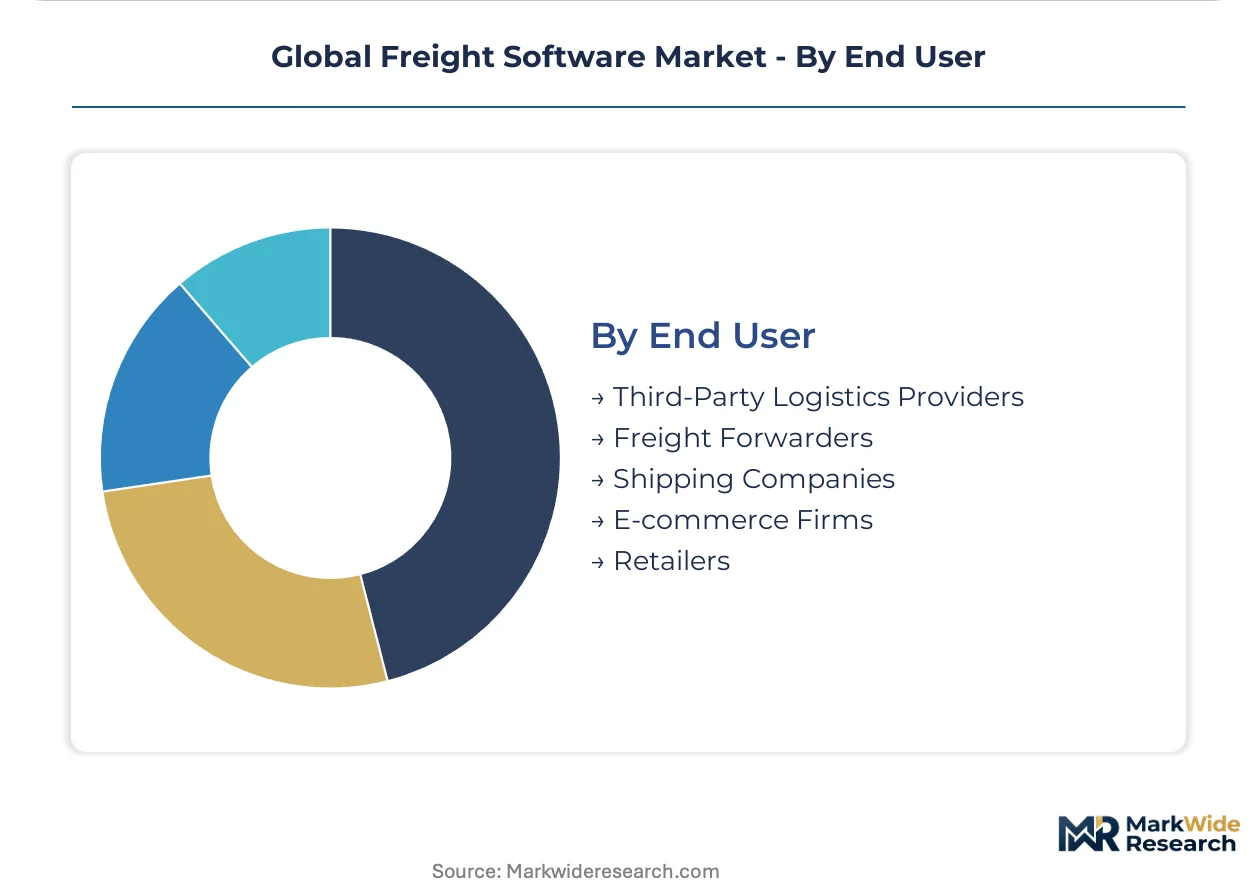
Freight software procurement patterns diverge sharply across deployment architectures, solution types, and end-user operational models. Understanding these segment boundaries clarifies where vendors must anchor compliance modules versus visibility layers.
Deployment:
Carrier IT modernization timelines span from legacy mainframe retirement to cloud-native compliance mandates.
- Cloud-Based:Multi-tenant architectures processing EDI and IoT sensor feeds through API gateways. German port authorities and US freight corridors are mandating cloud deployment for real-time customs data exchange, elevating procurement priority for vendors with EU AI Act audit trails.
- SaaS:Subscription models with modular expansion rights compressing contract cycles from multi-year to annual terms. India's BIS cloud security certifications and US FAA telemetry standards are forcing redundant infrastructure investments that favor established providers with compliance engineering depth.
- Hybrid:Split architectures retaining sensitive customs data on-premise while pushing visibility workloads to cloud edge nodes. China's MIIT data localization rules and EU GDPR cross-border restrictions drive adoption among Asia-Europe trade lane operators.
- On-Premise:Perpetual license stacks persisting in major ocean carrier environments with COBOL-based cargo management dependencies.
Established volume favors On-Premise; emerging adoption favors Cloud-Based.
Solution Type:
Revenue concentration aligns with shipper willingness to pay for dynamic optimization versus operational execution.
- Transportation Management:Machine learning-based routing algorithms integrated with carrier ELD systems and customs clearance rule engines. US e-commerce fulfillment operators and German automotive suppliers are consolidating procurement around platforms that automate exception handling for perishable and pharmaceutical flows.
- Warehouse Management:Yard management modules orchestrating autonomous mobile robots and drone inventory counts. Retail distribution centers in the United States and India's Delhi-Mumbai corridor are driving replacement cycles through robotic integration mandates.
- Fleet Management:Electronic logging and safety telemetry platforms shaped by US FAA mandates and EU driver hour regulations.
- Freight Brokerage:Digital load-matching marketplaces connecting shipper demand with carrier capacity across fragmented North American trucking networks.
Transportation Management commands premium pricing; Warehouse Management is climbing the fastest through robotics convergence.
Application:
Functional modules map to distinct operational pain points across modal corridors and cargo types.
- Supply Chain Optimization:End-to-end visibility layers unifying multimodal data streams from ocean bills of lading to final-mile delivery. Third-party logistics providers in India and the United States are consolidating fragmented point solutions into unified control towers.
- Load Optimization:Algorithms compressing empty-mile ratios through dynamic backhaul matching against carrier ELD availability. North American trucking corridors and Germany's Rhine-Alpine freight corridor show concentrated demand from asset-light freight forwarders.
- Route Planning:Deterministic and ML-based path optimization incorporating real-time traffic, weather, and port congestion signals.
- Inventory Visibility:Blockchain-verified documentation systems tracking cargo provenance through customs clearance cycles.
- Carrier Management:Automated procurement and performance scorecarding against on-time delivery and carbon intensity metrics.
Supply Chain Optimization absorbs the largest implementation budgets; Load Optimization is gaining share fastest among mid-market freight forwarders.
End User:
Buying authority concentrates with intermediaries managing multimodal complexity versus direct asset operators.
- Third-Party Logistics Providers:Platform consolidation mandates unifying road, rail, ocean, and air workflows for shipper clients. EU Green Deal emissions reporting requirements and US EPA freight corridor incentives are forcing 3PLs to procure carbon accounting modules as table stakes.
- E-commerce Firms:Annual subscription preferences with modular expansion rights driven by tariff volatility and modal switching demands. Fulfillment operators in the United States and India require API-native platforms for rapid carrier onboarding during peak seasons.
- Freight Forwarders:Customs compliance automation and documentation verification workflows across Asia-Pacific trade lanes.
- Shipping Companies:Vessel scheduling and port call optimization systems constrained by legacy mainframe dependencies.
- Retailers:Yard management and last-mile orchestration for high-velocity distribution networks.
Third-Party Logistics Providers dominate enterprise contract values; E-commerce Firms are expanding most quickly through flexible procurement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shippers in Germany and the United States demonstrate low price elasticity for compliance-embedded platforms, while Indian freight forwarders prioritize cost-efficient SaaS tiers with modular expansion paths.
United States
E-commerce fulfillment operators and automotive suppliers drive demand for dynamic routing algorithms integrated with carrier ELD systems. FAA modernization directives mandate electronic logging and safety telemetry standards that reshape fleet management procurement. Chicago and Los Angeles anchor the densest concentration of third-party logistics providers consolidating fragmented multimodal data streams.
Germany
Automotive manufacturers and chemical exporters require API-native platforms for real-time customs data exchange across Rhine-Alpine freight corridors. EU AI Act algorithmic transparency obligations compel vendors to deploy explainable decision logic with embedded audit trails. Port authorities in Hamburg and Bremen deploy blockchain-verified documentation systems demanding cloud-compliant freight architectures.
India
Freight forwarders along Delhi-Mumbai and Chennai-Bengaluru corridors seek indigenous TMS platforms with localized customs automation. BIS cloud security certifications force redundant infrastructure investments that elevate operational costs for mid-sized vendors. Gujarat and Maharashtra host the fastest-growing concentration of 3PLs procuring carbon accounting modules for EU Green Deal compliance.
China
Asia-Europe trade lane operators adopt hybrid architectures to satisfy MIIT data localization rules while maintaining cross-border visibility. Dual carbon goals and emissions reporting mandates reshape procurement criteria for container shipping software. Shanghai and Shenzhen dominate vessel scheduling and port call optimization system deployments constrained by legacy mainframe dependencies.
United Kingdom
Post-Brexit customs complexity drives demand for automated documentation verification workflows across North Sea and Channel trade routes. GDPR cross-border restrictions and EU CBAM carbon border adjustments extend sales cycles for vendors serving continental European shippers. London and the Midlands concentrate freight brokerage platforms connecting shipper demand with fragmented trucking capacity.
Global Freight Software Market Competitive Landscape
Enterprise software conglomerates and specialized freight technology vendors split the market between embedded ERP workflows and standalone visibility networks. Consolidation pressures favor vendors with compliance engineering depth across EU AI Act, FAA, and BIS certification architectures. Two strategic archetypes dominate: ERP-anchored suites leveraging existing enterprise footprints, and API-native specialists building real-time carrier networks. Competitive moves center on M&A-driven platform consolidation and geographic expansion through localized compliance partnerships.
Within the ERP-anchored tier, SAP SE and Oracle Corporation occupy positions exemplifying embedded multimodal workflow integration, while WiseTech Global represents the specialized archetype focused on customs compliance automation across Asia-Pacific trade lanes. These three companies illustrate the strategic divergence between leveraging existing enterprise relationships versus building de novo visibility networks.
| Leading Market Players |
|---|
| Descartes Systems Group |
| SAP SE |
| Oracle Corporation |
| e2open |
| Magaya Corporation |
| MercuryGate International |
| Infor |
| WiseTech Global |
| FourKites |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's cost dynamics illustrate how EU AI Act compliance engineering concentrates supply among vendors with embedded audit capabilities, while downstream price differentiation separates enterprise-grade TMS platforms from modular SaaS tiers serving mid-market freight forwarders.
Pricing Analysis
After-sales revenue from implementation services and extended support contracts drives lifetime value more than initial licensing fees. Three-tier pricing structure across premium, standard, and economy levels segments buyers by integration complexity and compliance certification depth. Price differentiation hinges on EU AI Act algorithmic transparency modules and FAA telemetry standard certifications. Cost compression in the economy tier is intensifying because India's BIS cloud security certifications force redundant infrastructure investments. E-commerce fulfillment operators exhibit highest price sensitivity, while German automotive suppliers demonstrate lowest elasticity for compliance-embedded platforms.
Supply Chain Analysis
Export-control regimes limiting semiconductor and cloud infrastructure flows to Chinese data centers constrain hybrid deployment architectures for Asia-Europe trade lane operators. Software engineering talent concentrates in the United States, Germany, and India, with compliance module development anchored in these jurisdictions. Raw material dependencies include cloud compute capacity from hyperscalers, embedded systems engineering expertise, and maritime regulatory knowledge bases. Single-source vulnerability sits with specialized engineers proficient in both industrial IoT integration and customs automation. Distribution runs through direct enterprise sales teams serving 3PLs and freight forwarders, supplemented by systems integrator partnerships for ERP-anchored deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
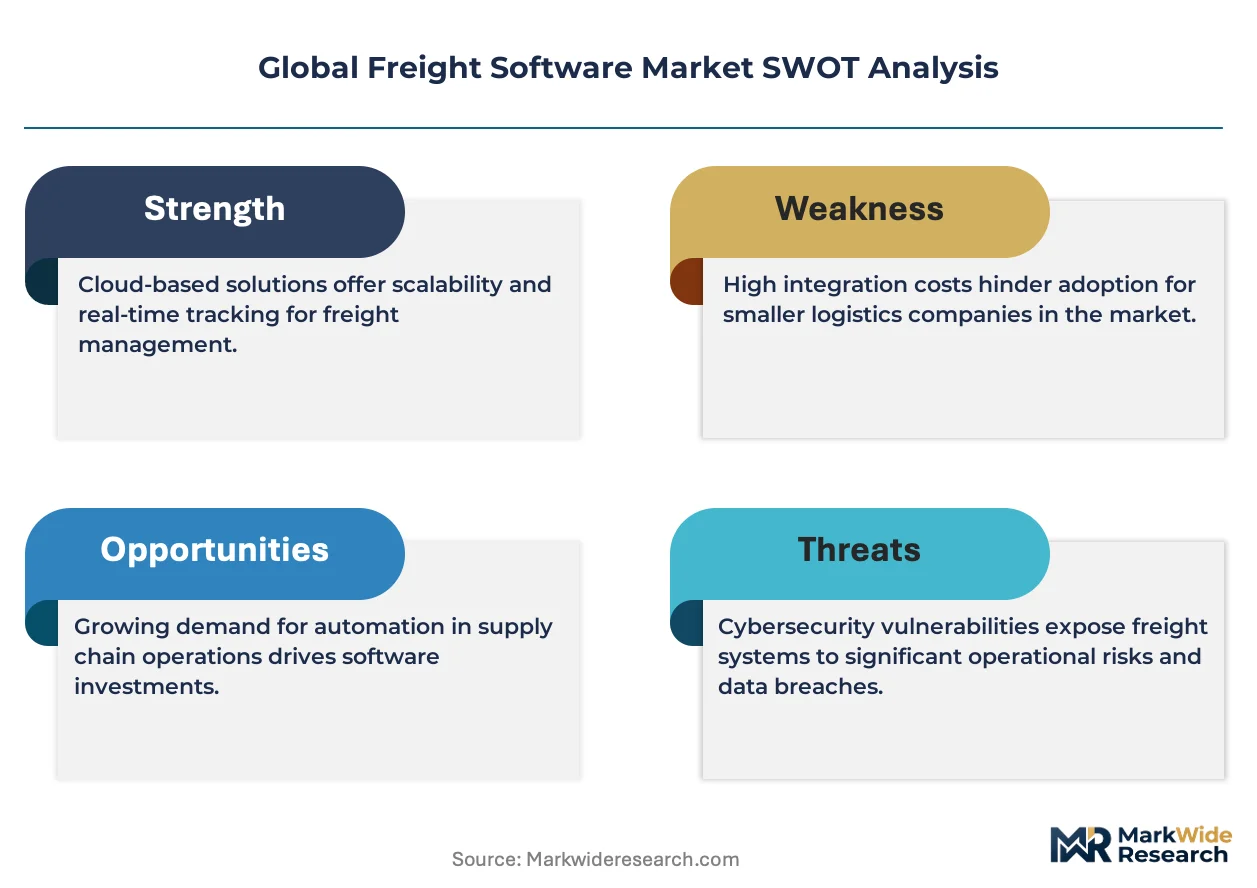
Engineers capable of bridging industrial IoT sensor integration with maritime regulatory compliance remain scarce relative to platform expansion timelines, creating persistent capability gaps that shape competitive outcomes.
For Market Incumbents: Build switching-cost moats through deep ERP workflow integration that embeds freight modules inside SAP and Oracle enterprise accounts. Consolidate around compliance engineering depth spanning EU AI Act, FAA, and BIS certification architectures to defend against API-native specialists. Add capacity in India to capture Delhi-Mumbai and Chennai-Bengaluru corridor demand for indigenous TMS platforms.
For New Entrants and Emerging Players: India's multimodal corridor buildout represents the most penetrable geographic white space, where localized customs automation modules face limited indigenous competition. Target mid-market freight forwarders with modular SaaS tiers offering annual subscription flexibility. Pursue partnership-led go-to-market strategies with regional 3PLs seeking rapid carrier onboarding capabilities.
For Investors and Strategic Acquirers: API-native specialists with real-time visibility networks and carrier ELD integration capabilities present the most compelling acquisition target archetype for long-term viability across the projection horizon. Carbon accounting module vendors with EU Green Deal MRV automation expertise signal inflection potential as emissions reporting becomes table stakes for European shipper RFPs.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded ERP workflows anchor multimodal freight automation inside existing enterprise accounts. |
| Acquisition of Specialist Firm | Carbon accounting module vendors automate EU Green Deal MRV compliance for European shippers. |
| Geographic Expansion | Localized compliance partnerships address India's BIS cloud security certification requirements. |
| Strategic Partnership | Carrier ELD system integrations compress empty-mile ratios across North American trucking corridors. |
| Product Launch | Explainable AI modules document carrier selection logic for EU AI Act algorithmic transparency mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory databases, and customs automation vendor disclosures. Interviews with CTOs at third-party logistics providers, IT procurement officers at freight forwarders, platform engineers at TMS vendors, and integration specialists at ERP consultancies informed demand-side perspectives. Bottom-up triangulation of vendor revenue disclosures and top-down validation against port digitization investment flows anchored market sizing.
Forecast inputs include deployment model adoption curves, organization size penetration patterns, vertical integration complexity tiers, and regional regulatory compliance timelines. Modeled segmentation spans cloud-native versus hybrid architectures, shipper versus carrier buying centers, and multimodal versus single-mode operational footprints. CAGRs were derived from trend extrapolation of ELD integration penetration and customs automation replacement cycles across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed logistics entrants would shift outcomes. Material shifts in EU CBAM carbon border adjustment enforcement timelines or US EPA freight corridor electrification incentive structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Ediscovery Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
AQI App Market
Digital Solutions
Crew Management Systems Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Poland ICT Market
Digital Solutions
Remote Integration Solutions Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Online Voting System Market
Digital Solutions
Track and Trace Solutions Market