
 Laser Page-Turning Pen Market | 2026-2036
Laser Page-Turning Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Page-Turning Pen Market Insights
Wireless connectivity integration is fragmenting the traditional remote-control architecture for page-turning devices into modular, app-extendable ecosystems. Logitech International S.A. leverages its Harmony legacy to sustain premium positioning across multi-device presentation environments. ACCO Brands Corporation anchors institutional procurement channels through established educational supply contracts. DinoFire Industrial Co., Ltd. competes aggressively on cost-engineered Bluetooth variants for price-sensitive consumer segments.
A laser page-turning pen is a handheld wireless peripheral combining a Class 2 or Class 3R laser pointer with radio-frequency or infrared page-advance circuitry, typically operating on 2.4 GHz protocols with 10-30 meter range and powered by lithium-polymer cells or AAA batteries; its primary commercial purpose is to enable hands-free document navigation during presentations, performances, and accessibility-assisted reading. Rechargeable product types command margin concentration due to battery lifecycle economics and reduced e-waste compliance costs. Bluetooth technology segments outpace infrared alternatives as device pairing standardization eliminates dongle dependency. Presentation tools application segments absorb disproportionate volume as hybrid work formats persist across corporate and academic settings.
The Federal Communications Commission governs 2.4 GHz transmission power limits for unlicensed devices sold in the United States, while the EU Radio Equipment Directive mandates CE marking and spectrum harmonization for Bluetooth-enabled peripherals marketed across member states. China's Ministry of Industry and Information Technology enforces SRRC certification for wireless transmitters, creating segmented market access protocols that manufacturers must navigate per destination country. Stakeholders should monitor evolving laser safety classification thresholds as ophthalmological risk assessments tighten product liability exposure across major jurisdictions.
Market Dynamics
Bluetooth Low Energy protocol migration is collapsing the legacy infrared-dongle architecture, forcing component suppliers in Shenzhen's electronics clusters to retool fabrication lines for integrated SoC modules that eliminate physical receivers.
Growth Catalysts
- Hybrid Work Persistence:Corporate and academic institutions maintain distributed presentation formats, sustaining hardware refresh cycles for wireless peripherals in conference room deployments.
- CE Marking Harmonization:The EU Radio Equipment Directive streamlines cross-border certification for Bluetooth-enabled devices, reducing time-to-market for manufacturers targeting European procurement channels.
- Accessibility Mandates:Section 508 compliance requirements in US federal contracting create specified demand for hands-free document navigation tools in government and educational settings.
Market Restraints
- Lithium-Polymer Cost Volatility:Rechargeable battery chemistries face raw material price swings that compress margins on premium product tiers.
- Shenzhen Supply Concentration:Over 70% of RF module fabrication clusters in a single Chinese metropolitan area expose buyers to localized disruption risks.
- Smartphone Substitution:Native gesture-control apps in iOS and Android ecosystems erode addressable market for dedicated hardware peripherals.
Strategic Opportunities
- India Ed-Tech Procurement:Central and state government digital classroom initiatives under the PLI scheme create specified demand for presentation hardware in tier-2 and tier-3 cities.
- Gesture-Voice Convergence:Integration of MEMS accelerometers with edge AI voice recognition enables hands-free operation modes for mobility-impaired users.
- Direct-to-Institution E-Commerce:Bypassing traditional educational supply distributors through specialized B2B marketplaces reduces channel margin extraction.
Industry Challenges
- SRRC Certification Timelines:China's Ministry of Industry and Information Technology approval processes for 2.4 GHz transmitters extend product launch schedules by 8-14 weeks.
- Legacy System Integration:Institutional buyers with locked-down IT environments require custom firmware builds for enterprise security protocols, fragmenting software development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Page-Turning Pen Market |
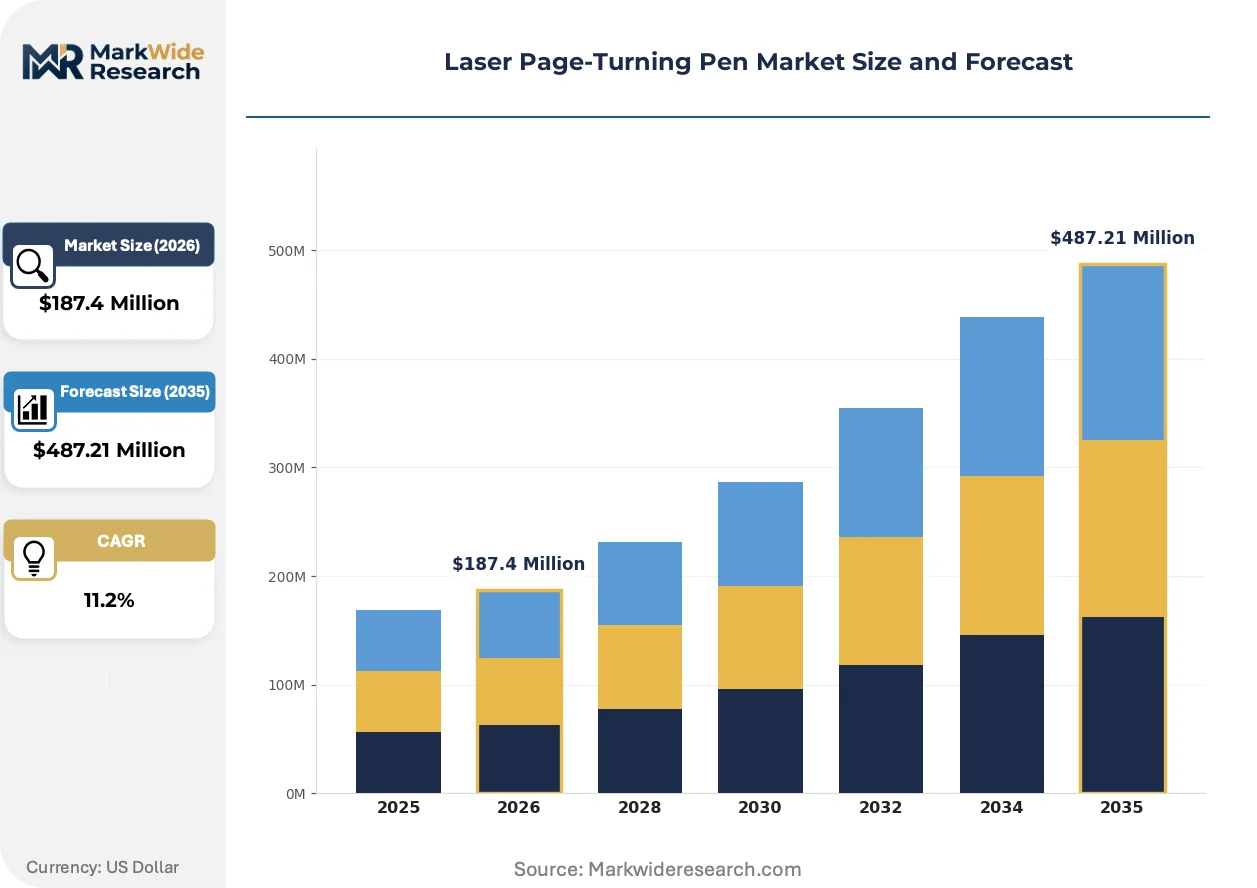
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rechargeable, Disposable, Ergonomic, Compact Technology: Infrared, Touch Sensitive, Bluetooth, Optical End User: Students, Professionals, Artists, Educators Application: Reading Aids, Learning Tools, Accessibility Devices, Presentation Tools |
| Companies Covered | Logitech International S.A., ACCO Brands Corporation, Amazon.com, Inc., Targus Group International LLC, Koolike Co., Ltd., DinoFire Industrial Co., Ltd., Satechi Design & Electronics, Griffin Technology, Inc., Insten LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Page-Turning Pen Market Trends and Innovations
Wireless connectivity standards are fragmenting into modular, app-extendable ecosystems that decouple hardware from proprietary software stacks. This shift enables third-party developers to build custom gesture mappings and accessibility overlays atop standardized Bluetooth HID protocols.
Bluetooth Low Energy 5.3 is collapsing the traditional trade-off between transmission range and power consumption in Class 2 laser pointers. Musicians and stage performers are adopting these extended-range variants for theater-scale venues where 30-meter reliability eliminates line-of-sight anxiety. The technology is collapsing the premium tier's justification for proprietary RF protocols, compressing price differentiation between mid-range and high-end product lines.
The EU's Radio Equipment Directive 2023 refresh tightens electromagnetic compatibility testing for 2.4 GHz devices, mandating additional shielding validation for products marketed across member states. Manufacturers serving European institutional buyers must redesign PCB layouts to satisfy revised harmonic emission limits. Medical and pharmaceutical presentation segments, where CE marking carries liability weight, are absorbing compliance costs fastest while delaying hardware refresh cycles.
Corporate procurement teams are unbundling after-sales support from hardware acquisition, treating presentation peripherals as consumables rather than capital assets. Channel partners respond with volume-tiered pricing and minimal warranty terms. This pattern concentrates in North American technology and consulting verticals where IT asset depreciation schedules favor 18-24 month replacement cycles over repair investment.
Laser Page-Turning Pen Market Segmentation
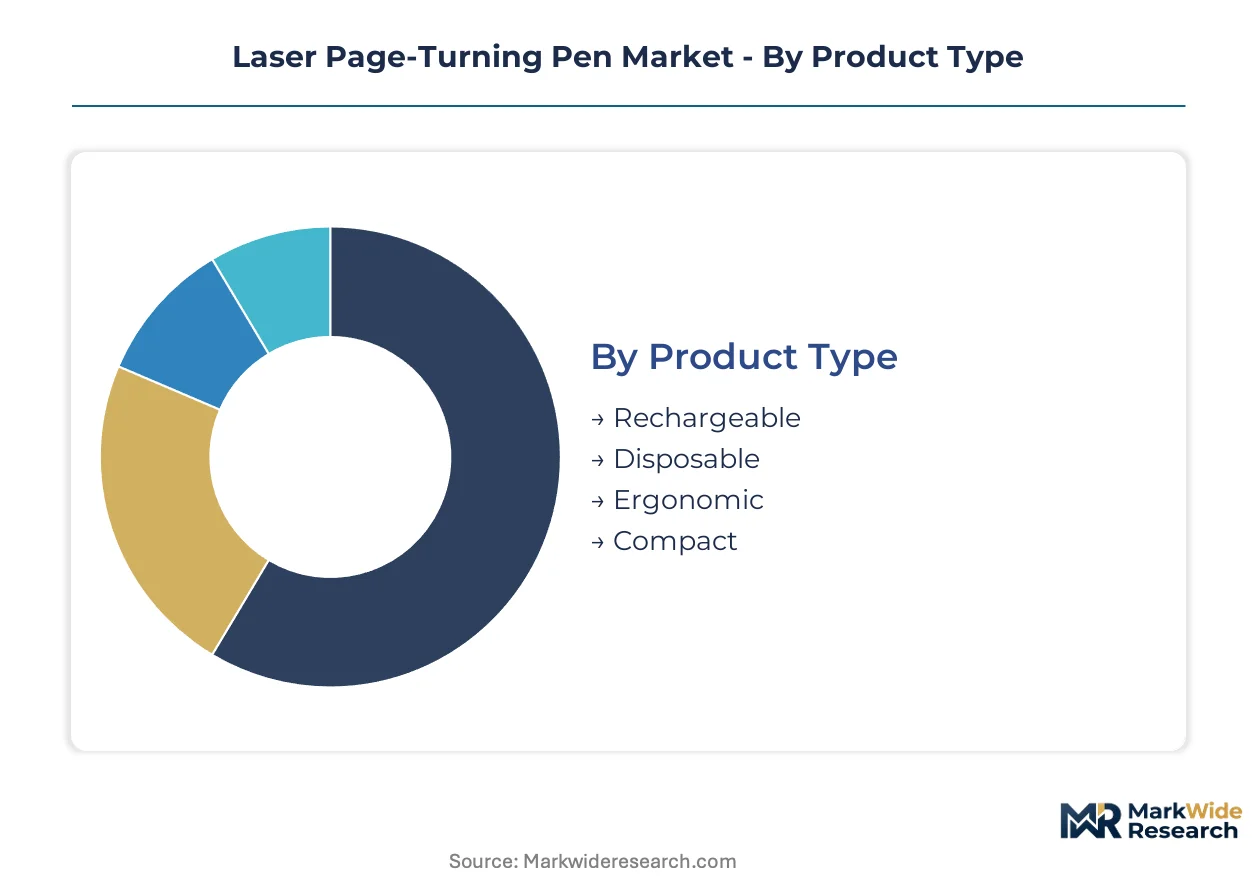
Segmentation in the Laser Page-Turning Pen Market reveals distinct service and support requirements across user profiles. Rechargeable variants demand battery lifecycle management programs, while institutional buyers prioritize warranty terms over replacement cycles. Understanding these divergent after-sales intensity patterns shapes channel strategy and margin architecture.
Product Type:
After-sales-service intensity varies sharply across product type, with rechargeable units requiring firmware update support and battery replacement programs that disposable variants eliminate entirely.
- Rechargeable:Lithium-polymer cells with USB-C or proprietary dock charging enable 200-500 cycle lifespans. Demand concentrates in corporate procurement channels where IT departments mandate standardized charging infrastructure and depreciate peripherals over 24-36 month horizons. Battery replacement programs and firmware update subscriptions generate recurring service revenue streams that offset hardware margin compression.
- Disposable:AAA or coin-cell battery architectures eliminate charging infrastructure dependencies. Artists and mobile performers in touring configurations favor these for field reliability without power access. The absence of battery management software reduces support ticket volume to near-zero, enabling distributor self-service models.
- Ergonomic:Contoured grips and weight-balanced chassis designs reduce repetitive strain injury risk during extended use sessions.
- Compact:Pocket-form factor devices prioritize portability over battery capacity, targeting educators with mobile classroom workflows.
By volume, Disposable leads. By growth pace, Rechargeable is ahead.
Technology:
Cost tier stratification in technology segments separates dongle-dependent legacy architectures from integrated SoC solutions that command premium positioning.
- Bluetooth:BLE 5.0+ protocols with HID profile standardization eliminate USB receiver dependencies. Corporate and academic IT environments in the United States and Germany mandate these for security compliance, as Bluetooth stacks integrate with enterprise device management platforms. Shenzhen's SoC suppliers have collapsed module costs, compressing the premium over infrared to under 15% at volume.
- Infrared:Line-of-sight transmission with dedicated USB receivers persists in price-sensitive consumer segments. Legacy institutional deployments in Japan and South Korea retain these for compatibility with locked-down computing environments where Bluetooth radio activation requires administrative override.
- Touch Sensitive:Capacitive surface integration enables gesture augmentation beyond basic page advancement.
- Optical:Image-sensor-based page detection operates without host device pairing for standalone accessibility applications.
Bluetooth captures the majority of new procurement decisions. Optical exhibits the steepest expansion trajectory in accessibility-focused funding streams.
End User:
Customer type segmentation maps directly to purchasing authority structures, with institutional buyers consolidating volume through educational supply contracts versus individual professionals selecting on feature-specific criteria.
- Professionals:Consultants, legal practitioners, and financial analysts require multi-device pairing and presentation software integration. Demand clusters in tier-1 metropolitan areas across the United States, United Kingdom, and Australia where hybrid work formats sustain conference room utilization rates. These users absorb premium pricing for cross-platform compatibility and dedicated technical support hotlines.
- Educators:K-12 and higher education instructors drive institutional procurement through district-level technology refresh programs. India's central and state government digital classroom initiatives under the PLI scheme specify presentation hardware for tier-2 and tier-3 city deployments, creating volume concentration with extended payment terms.
- Students:Individual purchasers prioritize entry-tier pricing with minimal feature sets for occasional presentation requirements.
- Artists:Musicians and stage performers demand extended-range reliability and physical durability for touring environments.
Educators generate the largest absolute unit volumes. Professionals deliver the highest revenue per transaction.
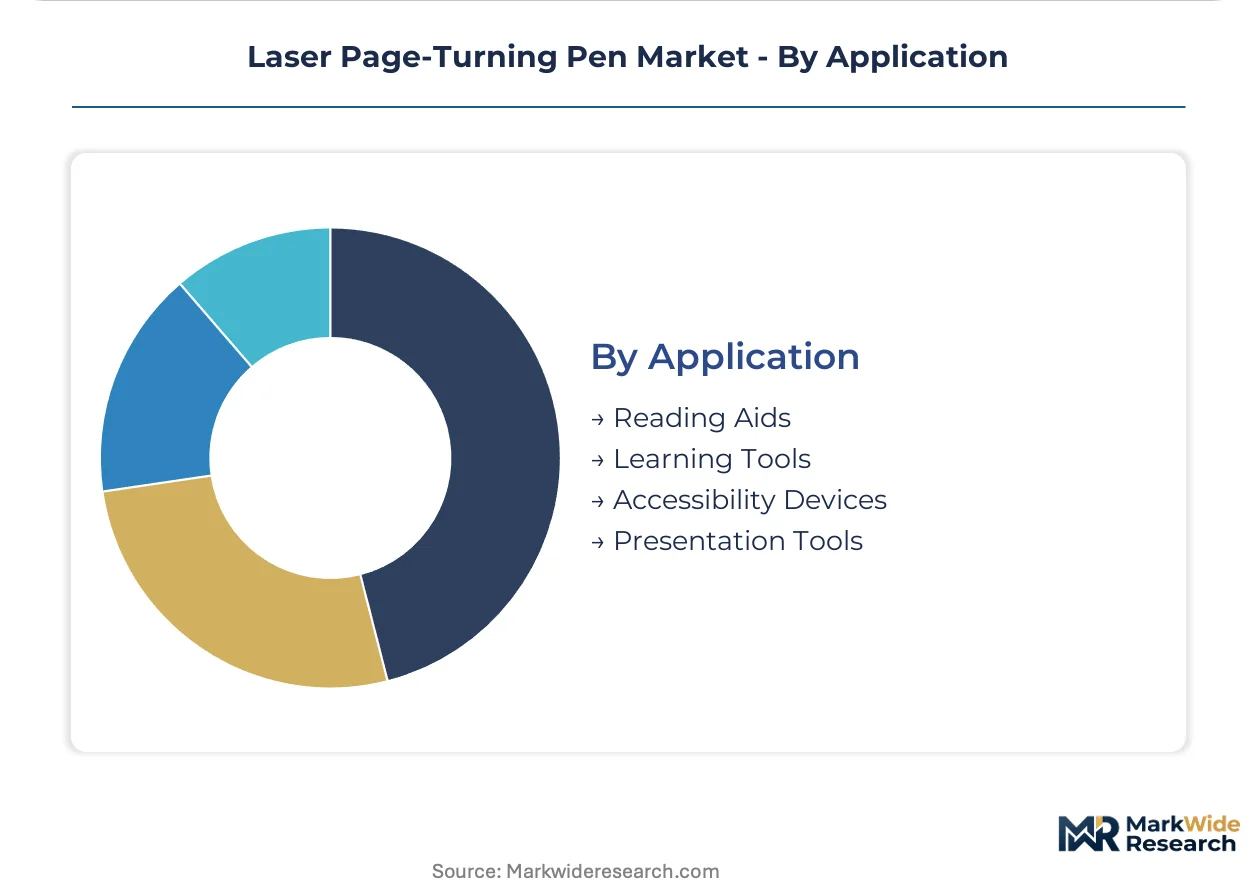
Application:
Volume concentration in application segments follows funding authorization patterns, with accessibility mandates creating specified demand separate from discretionary corporate technology budgets.
- Presentation Tools:Corporate and academic conference room deployments absorb the majority of hardware volume. Hybrid work persistence across technology and consulting verticals in North America sustains 18-24 month replacement cycles as IT asset depreciation schedules favor refresh over repair investment.
- Accessibility Devices:Section 508 compliance in US federal contracting and equivalent mandates in European public procurement create non-discretionary demand. Hands-free document navigation tools serve mobility-impaired users in government, educational, and healthcare settings where regulatory liability drives specification rigor.
- Reading Aids:Individual consumers with low vision or motor control limitations utilize these for independent document consumption.
- Learning Tools:Early childhood and special education applications integrate page-turning functionality into adaptive curriculum delivery.
Presentation Tools dominates current installed base. Accessibility Devices is climbing the fastest as regulatory compliance timelines tighten across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement teams in the United States absorb the largest volume of rechargeable Bluetooth variants, while musicians and stage performers in Germany and China drive demand for extended-range hardware. Educational supply contracts in India and institutional accessibility mandates across European jurisdictions create parallel demand streams with distinct certification requirements.
United States
Federal contractors under Section 508 compliance specifications procure hands-free document navigation tools for government and educational deployments. The FCC governs 2.4 GHz transmission power limits for unlicensed Bluetooth peripherals sold across state lines. IT asset depreciation schedules in North American technology and consulting verticals favor 18-24 month hardware replacement cycles over repair investment.
China
Shenzhen's electronics manufacturing clusters fabricate over 70% of RF module components for global supply, concentrating component sourcing risk in a single metropolitan area. The MIIT enforces SRRC certification for wireless transmitters, extending product launch schedules by 8-14 weeks for 2.4 GHz devices. Component suppliers in the Pearl River Delta are retooling fabrication lines for integrated SoC modules that eliminate physical USB receivers.
Germany
Corporate and academic IT environments mandate Bluetooth HID profile standardization for security compliance, eliminating dongle-dependent legacy architectures. The EU Radio Equipment Directive mandates CE marking and spectrum harmonization for peripherals marketed across member states. Industrial procurement channels in Baden-Württemberg and Bavaria prioritize cross-platform compatibility and dedicated technical support infrastructure.
India
Central and state government digital classroom initiatives under the PLI scheme specify presentation hardware for tier-2 and tier-3 city deployments, creating volume concentration with extended payment terms. The BIS certification framework governs electronics imports and domestic manufacturing quality standards. Educational supply distributors in Maharashtra and Karnataka face margin compression from direct-to-institution B2B marketplace entrants.
Japan
Legacy institutional deployments retain infrared-dongle architectures for compatibility with locked-down computing environments where Bluetooth radio activation requires administrative override. METI oversees industrial standards coordination for wireless peripherals in enterprise and educational settings. Locked-down IT environments in Tokyo and Osaka metropolitan areas fragment software development resources with custom firmware requirements for enterprise security protocols.
Laser Page-Turning Pen Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered pricing bands that separate premium multi-device ecosystems from cost-engineered single-function units. The vendor base stratifies into three archetypes: diversified peripherals conglomerates with Harmony-legacy presentation ecosystems, educational supply incumbents with institutional procurement lock-in, and Shenzhen-based cost-engineered specialists. Dominant competitive moves include strategic partnerships with enterprise device management platforms and geographic expansion through regional certification acquisition.
Within the diversified peripherals tier, Logitech International S.A. and ACCO Brands Corporation exemplify contrasting channel strategies. Logitech leverages multi-device presentation environment expertise to sustain premium positioning across corporate and academic settings. ACCO anchors institutional procurement through established educational supply contracts with district-level technology refresh programs. DinoFire Industrial Co., Ltd. represents the Shenzhen-based cost-engineering archetype, competing aggressively on Bluetooth variants for price-sensitive consumer segments. These three players illustrate the market's structural segmentation between ecosystem breadth, channel control, and manufacturing cost position.
| Leading Market Players |
|---|
| Logitech International S.A. |
| ACCO Brands Corporation |
| Amazon.com, Inc. |
| Targus Group International LLC |
| Koolike Co., Ltd. |
| DinoFire Industrial Co., Ltd. |
| Satechi Design & Electronics |
| Griffin Technology, Inc. |
| Insten LLC |
| Others |
Pricing and Supply Chain Analysis
The Shenzhen-Hong Kong logistics corridor carries lithium-polymer cells and BLE SoC modules at freight rates that compress margins for rechargeable variants while enabling aggressive pricing in disposable battery tiers. This corridor's cost dynamics amplify the pricing power concentrated in Pearl River Delta component suppliers and force downstream differentiation through certification bundling rather than hardware specification alone.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate procurement between Shenzhen SoC fabricators and downstream OEMs. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked Bluetooth units from uncertified infrared legacy stock and disposable AAA-powered field units. Pricing pressure stems from smartphone gesture apps eroding dedicated hardware utility in consumer segments. Educators exhibit highest price sensitivity due to district-level bulk procurement with extended payment terms, while federal contractors under Section 508 mandates absorb premium positioning for accessibility compliance.
Supply Chain Analysis
Upstream feedstock for RF modules draws from gallium arsenide wafer fabrication in Taiwan, lithium mining operations in Australia, and rare earth processing in China. Shenzhen's electronics clusters consume over 70% of global BLE SoC output for peripheral manufacturing. Single-source vulnerability concentrates in MIIT SRRC certification bottlenecks that extend launch timelines. Distribution runs through educational supply distributors in North America and direct-to-institution B2B marketplaces in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against native smartphone gesture controls that eliminate dedicated peripheral need for occasional presenters. Incumbents must navigate this erosion while extracting value from regulatory-mandated accessibility segments.
For Market Incumbents: Harden enterprise device management platform integrations to lock IT departments into firmware-update ecosystems that smartphone apps cannot replicate. Deepen backward integration into Shenzhen SoC supply through exclusive module allocations that constrain cost-engineered competitor access. Defend against DinoFire-tier price aggression by bundling Section 508 compliance documentation with hardware sales to federal contractors. For New Entrants and Emerging Players: Pursue India's tier-2 and tier-3 city digital classroom deployments under PLI scheme specifications where established distributor relationships remain unformed. Target musicians and stage performers in Germany's theater districts with extended-range BLE 5.3 variants that justify premium positioning through reliability guarantees. Deploy direct-to-institution e-commerce with volume-tiered pricing to bypass margin-extracting educational supply channels. For Investors and Strategic Acquirers: Shenzhen-based cost-engineered specialists with captive MIIT certification relationships and established OEM white-label contracts represent priority acquisition targets. Long-term viability hinges on regulatory compliance depth rather than hardware innovation velocity as smartphone substitution accelerates. Watch for inflection in India's BIS enforcement stringency that would elevate compliance costs for unbranded imports.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT SRRC Certification Pre-Positioning | Accelerates product launch timelines by 8-14 weeks against competitors awaiting approval. |
| Enterprise Device Management Platform Integration | Locks IT departments into firmware ecosystems that smartphone gesture apps cannot penetrate. |
| Direct-to-Institution B2B Marketplace Entry | Bypasses margin-extracting educational supply distributors in India's tier-2 city expansion. |
| Gesture-Voice Convergence R&D Investment | Captures Section 508-mandated accessibility demand through MEMS accelerometer edge AI integration. |
| PLI Scheme Contract Pursuit | Secures volume concentration with extended payment terms in India's government digital classroom initiatives. |
Research Methodology
Initial hypotheses were tested against primary input from corporate IT procurement officers, educational technology directors, accessibility compliance consultants, and Shenzhen-based component suppliers and refined through secondary validation against FCC equipment authorization databases, MIIT SRRC certification registries, EU Radio Equipment Directive compliance listings, and customs import records for 2.4 GHz peripherals. Bottom-up volume estimates from institutional procurement channels triangulated against top-down market sizing from electronics manufacturing cluster output data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type architecture, wireless protocol generation, end-user purchasing authority structure, and application funding authorization pattern. CAGRs derived from shipment volume trajectories by segment, adjusted for replacement cycle compression in North American technology verticals and regulatory compliance timeline acceleration in European accessibility mandates.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, freight rates on the Shenzhen-Hong Kong corridor, or INR/USD exchange rates affecting Indian PLI scheme implementation would shift the trajectory. Cross-checking against BIS import license issuance rates and MIIT SRRC approval queue lengths is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Trade Management Software Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
Mobile Marketing Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
France ICT Market
Digital Solutions
India ICT Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
AI Powered Home Solution Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Mobile Dating Apps Market