
 Global Procurement-As-A-Service (PAAS) Market | 2026-2036
Global Procurement-As-A-Service (PAAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Procurement-As-A-Service (PAAS) Market Foresight
Modular service bundling is consolidating buyer preferences across the PAAS landscape. GEP leverages deep category expertise in direct materials sourcing to anchor enterprise relationships. SAP SE competes through native ERP integration that extends procurement workflows into finance and supply chain modules. WNS (Holdings) Limited specializes in managed analytics for spend visibility, occupying a distinct niche in the mid-market segment.
Procurement-As-A-Service denotes the outsourcing of sourcing, supplier management, and spend optimization to third-party providers operating on cloud-native or hybrid infrastructure with API-based ERP connectivity. The model automates purchase-to-pay cycles, enforces compliance rules, and generates predictive analytics for cost reduction. Strategic sourcing and supplier management command the largest service revenue pools due to enterprise complexity in direct materials procurement. Cloud-based deployment shows the fastest expansion trajectory as CIOs prioritize scalable infrastructure over capital-intensive on-premises installations.
ISO standards for information security management, the EU AI Act for automated procurement decision systems, and India's BIS cloud service guidelines collectively shape vendor qualification and data residency requirements. The EU AI Act specifically mandates human oversight for high-risk automated supplier selection algorithms, creating compliance costs for European deployments. Stakeholders must monitor regulatory divergence between data sovereignty regimes and AI governance frameworks when designing multi-country PAAS architectures.
Market Dynamics
Cloud migration mandates from CIOs are compressing procurement technology refresh cycles, forcing enterprises to retire legacy on-premises sourcing platforms in favor of API-native PAAS architectures with embedded compliance automation.
Growth Catalysts
- ISO 27001 certification mandates:Enterprise buyers now disqualify vendors lacking accredited information security management systems, elevating certified providers above uncertified competitors in RFP evaluations.
- India's BIS cloud service guidelines:Data localization requirements for government and BFSI procurement are channeling public sector spend toward domestic PAAS operators with in-country infrastructure.
- Direct materials sourcing complexity:Automotive and industrial manufacturers are outsourcing category management for engineered components to specialists with embedded commodity intelligence.
Market Restraints
- EU AI Act compliance costs:Human oversight requirements for automated supplier selection algorithms impose architectural redesign burdens on European deployments.
- Mid-market talent scarcity:Procurement technology architects with ERP integration expertise command premium compensation, constraining provider scaling velocity.
- Hybrid infrastructure complexity:Enterprises with fragmented legacy systems face extended migration timelines that delay PAAS contract commencements.
Strategic Opportunities
- German Mittelstand segment:Family-owned manufacturers with $50-500M revenue represent an underserved cohort with limited in-house sourcing capabilities.
- Spend analytics-AI convergence:Predictive cost modeling fused with natural language query interfaces creates differentiated positioning against rules-based competitors.
- US Inflation Reduction Act incentives:Domestic content requirements for clean energy procurement are generating demand for traceability modules within PAAS platforms.
Industry Challenges
- API standardization gaps:Inconsistent data exchange protocols between ERP vendors and PAAS platforms force costly custom integration development.
- ISO 27001 certification timelines:Eighteen-month audit cycles delay market entry for emerging providers targeting regulated industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Procurement-As-A-Service (PAAS) Market |
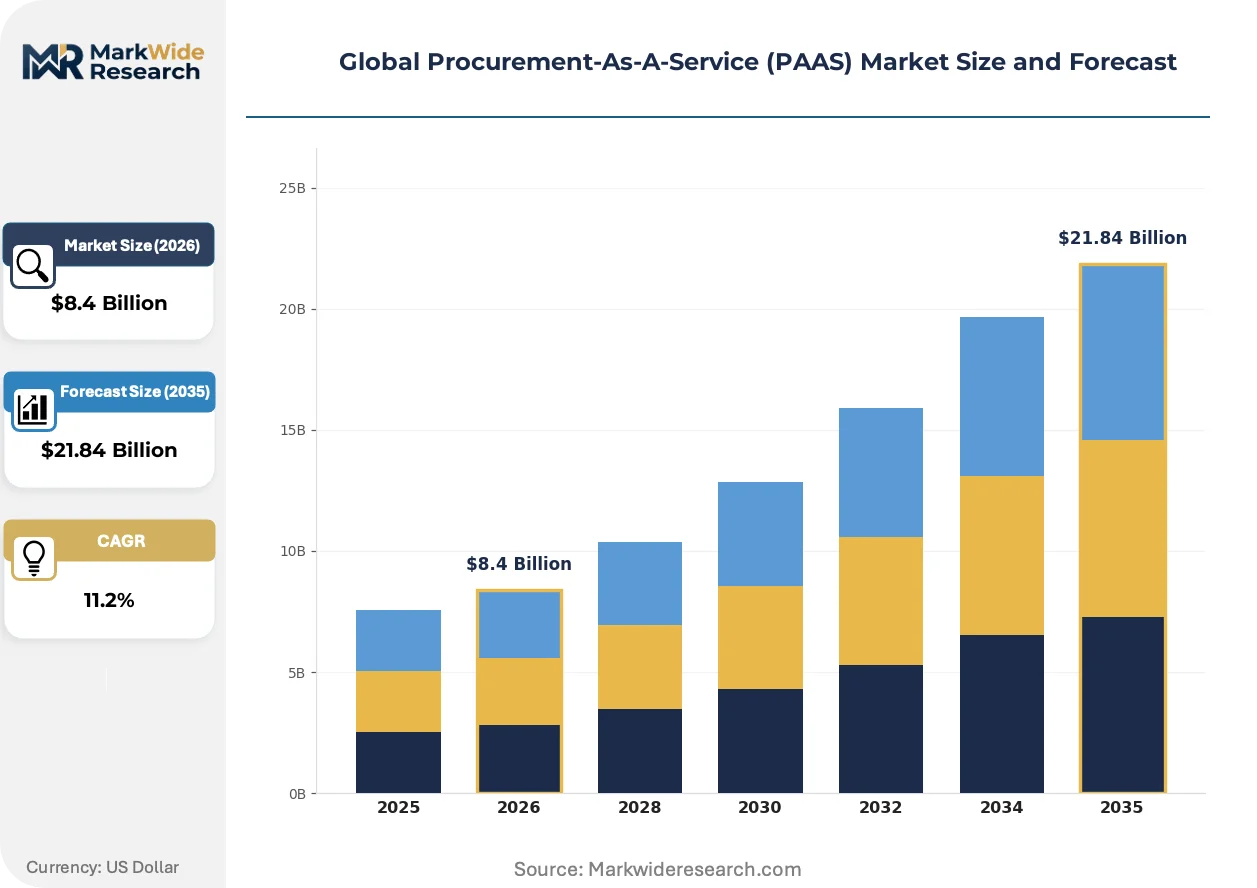
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $21.84 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategic Sourcing, Supplier Management, Contract Management, Spend Analysis, Compliance Monitoring Application: Manufacturing, Financial Institutions, Telecommunications, Energy Providers, Consumer Goods Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services, Virtual Private Network End User: Original Equipment Manufacturers, Tier-1 Suppliers, Government Agencies, Educational Institutions, Non-Profit Organizations |
| Companies Covered | Accenture, GEP, IBM Corporation, Genpact, Infosys Limited, SAP SE, Coupa Software, WNS (Holdings) Limited, Capgemini, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Procurement-As-A-Service (PAAS) Market Shifts & Advancements
Intelligent process automation and embedded compliance engines are redefining competitive differentiation in procurement outsourcing. Providers now compete on the depth of their pre-built connector libraries and the sophistication of their predictive spend models.
Machine learning-powered contract extraction is automating clause identification and obligation tracking across multi-jurisdictional supplier agreements. Fortune 500 legal and procurement teams are deploying these tools at scale to compress contract review cycles from weeks to days. The technology is automating compliance surveillance that previously required dedicated analyst teams.
The EU AI Act's risk classification framework for automated decision systems is forcing architectural changes in European PAAS deployments. Providers must now engineer human-in-the-loop checkpoints for high-risk supplier selection workflows. German automotive and French aerospace procurement functions are prioritizing vendors with pre-validated compliance architectures.
Enterprise buyers are consolidating vendor relationships around bundled source-to-pay suites rather than point solutions for individual procurement functions. Mid-market manufacturers in particular are abandoning best-of-breed strategies in favor of integrated platforms with unified data models. This concentration pattern is most pronounced among US industrial distributors and Indian pharmaceutical contract manufacturers.
Global Procurement-As-A-Service (PAAS) Market Segmentation
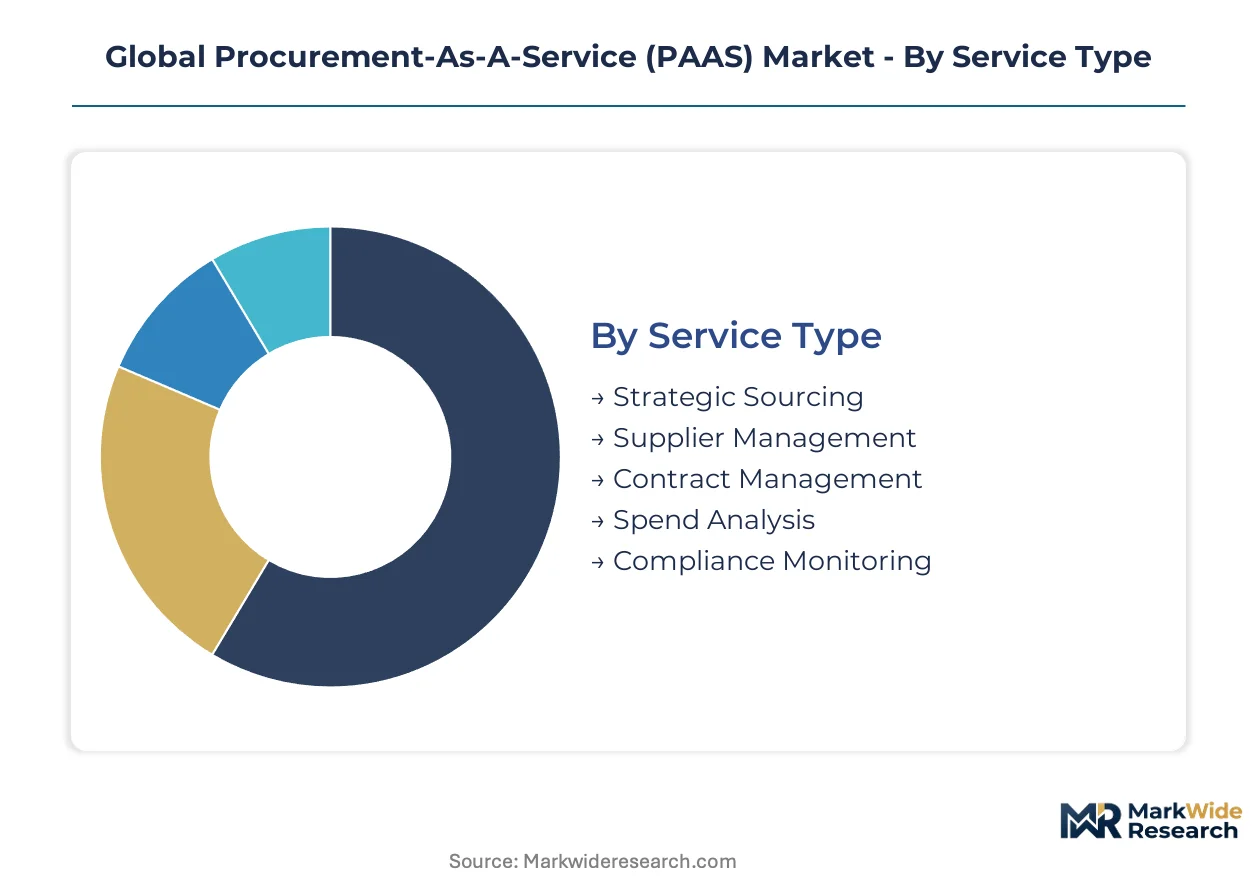
PAAS segmentation reveals how procurement complexity fragments across service modalities, buyer maturity, and infrastructure requirements. Distinct deployment archetypes and end-user categories demand tailored vendor capabilities and pricing architectures.
Service Type:
Buyer sophistication and category complexity determine which service modules command premium engagement.
- Strategic Sourcing:Direct materials category management with embedded commodity intelligence and supplier negotiation protocols. Automotive and industrial manufacturers in Germany and the United States outsource engineered component sourcing to specialists with vertical expertise.
- Supplier Management:Onboarding, performance scorecarding, and risk monitoring across multi-tier supply networks. ISO 27001 certification requirements are disqualifying uncertified providers from regulated industry RFPs.
- Contract Management:Lifecycle administration from drafting through renewal with clause extraction automation.
- Spend Analysis:Data aggregation and visualization for procurement cost transparency and benchmarking.
- Compliance Monitoring:Regulatory surveillance and audit trail maintenance for EU AI Act and BIS guideline adherence.
Volume sits with Strategic Sourcing; growth tilts toward Supplier Management.
Application:
Industry-specific procurement regulations and supply chain architectures shape solution customization requirements.
- Manufacturing:Direct materials procurement with bill-of-materials integration and supplier quality management. India's pharmaceutical contract manufacturers and German Mittelstand automotive suppliers drive demand for traceability modules.
- Financial Institutions:BFSI procurement governed by RBI data localization and stringent vendor due diligence protocols.
- Telecommunications:Network equipment and service sourcing with TRAI compliance and spectrum-related procurement workflows.
- Energy Providers:Capital project procurement and maintenance contracting with FERC and state utility commission oversight.
- Consumer Goods:Indirect spend optimization and retail supplier collaboration platforms.
Manufacturing captures the largest contract values; Financial Institutions show the steepest expansion trajectory.
Deployment Model:
Infrastructure maturity and data sovereignty mandates fragment buyer preferences across hosting architectures.
- Cloud-Based:API-native platforms with elastic scaling and embedded compliance automation. CIO migration mandates in the United States and Germany are compressing technology refresh cycles toward this model.
- On-Premises:Legacy installations in defense and classified government procurement with air-gapped security requirements.
- Hybrid:Split architectures for sensitive spend categories with cloud analytics and on-premises transaction processing.
- Managed Services:Fully outsourced procurement operations with dedicated staff augmentation.
- Virtual Private Network:Isolated network segments for multi-national enterprises with strict data residency requirements.
Cloud-Based deployments dominate new contract signings; Hybrid configurations persist in regulated European installations.
End User:
Procurement centralization and outsourcing appetite vary sharply by organizational scale and funding source.
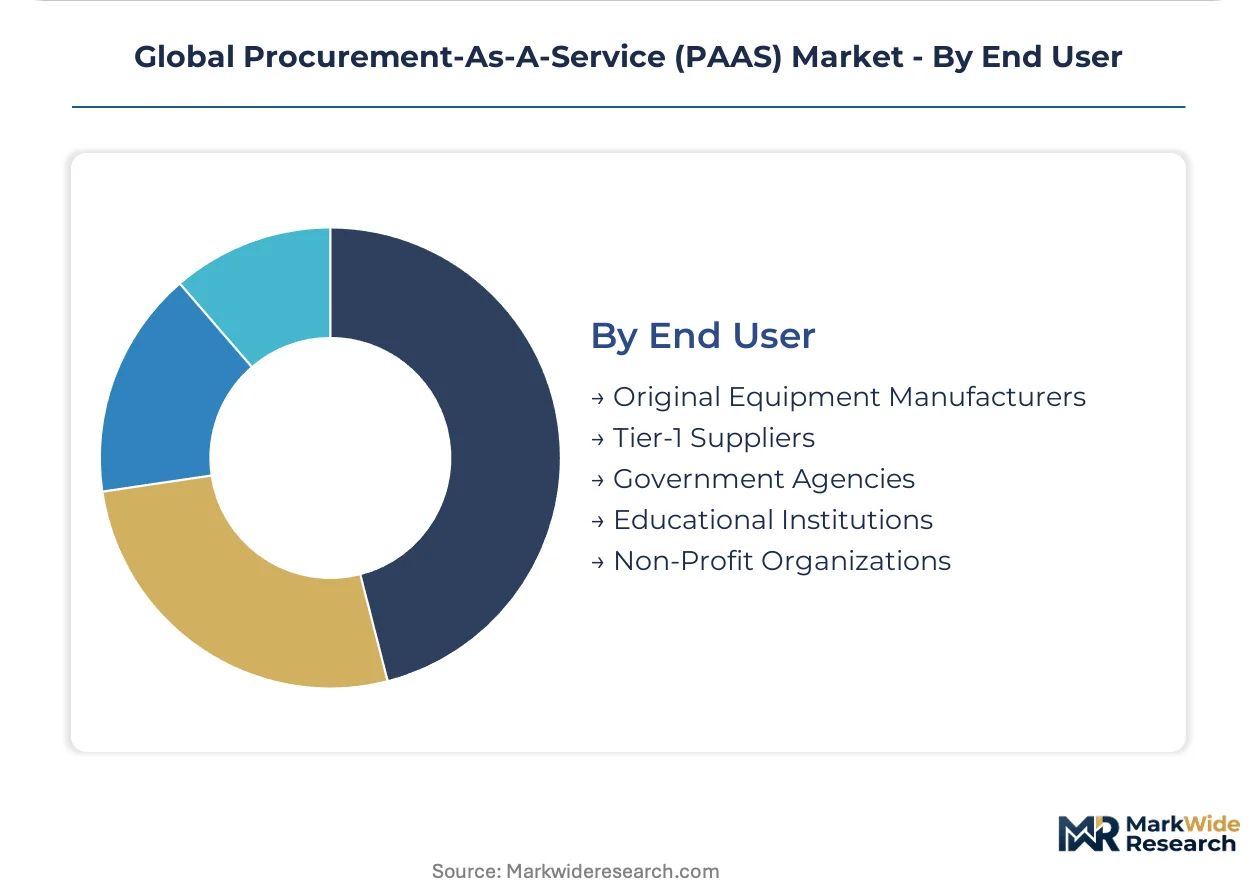
- Original Equipment Manufacturers:Complex direct materials sourcing with global supplier networks and tier-n visibility requirements. Automotive OEMs in Germany and industrial equipment makers in the United States anchor enterprise PAAS relationships.
- Tier-1 Suppliers:Mid-market manufacturers with limited in-house sourcing capabilities seeking category management support.
- Government Agencies:Public sector procurement with BIS cloud guidelines in India and federal acquisition regulations in the United States.
- Educational Institutions:Research university procurement with grant compliance and diverse supplier diversity mandates.
- Non-Profit Organizations:Donor-funded operations with cost transparency and audit requirements.
Original Equipment Manufacturers generate the highest per-contract revenue; Tier-1 Suppliers offer the deepest untapped penetration opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PAAS consumption concentrates in enterprise hubs with complex procurement operations, while production gravity sits with cloud infrastructure providers in technology corridors. The United States, Germany, and India anchor demand through manufacturing scale and outsourcing appetite. Regulatory fragmentation across data sovereignty and AI governance regimes shapes vendor qualification requirements.
United States
Automotive OEMs and industrial distributors in Detroit and the Midwest drive strategic sourcing module adoption. The Inflation Reduction Act mandates domestic content traceability for clean energy procurement, forcing platform upgrades. Silicon Valley cloud providers and Chicago-based consultancies compete for federal acquisition contracts with FERC-compliant architectures.
Germany
Mittelstand automotive suppliers in Baden-Württemberg and Bavaria outsource direct materials category management to specialists. The EU AI Act imposes human-in-the-loop checkpoints for automated supplier selection algorithms. Stuttgart's industrial cluster prioritizes vendors with pre-validated compliance architectures for engineered component sourcing.
India
Pharmaceutical contract manufacturers in Maharashtra and Gujarat demand traceability modules for export compliance. BIS cloud service guidelines mandate data localization for government and BFSI procurement, channeling public sector spend toward domestic operators. Bangalore's technology corridor hosts API-native platform development for mid-market manufacturers.
United Kingdom
London-based financial institutions and professional services firms drive spend analytics adoption for indirect cost optimization. GDPR and emerging AI governance frameworks constrain automated decision system deployments. The Southeast corridor concentrates procurement outsourcing relationships with ERP-integrated service providers.
Japan
Automotive and electronics manufacturers in the Chubu region around Nagoya seek tier-n supplier visibility for risk mitigation. METI guidelines on supply chain resilience encourage platform investments. The Kanto corridor around Tokyo hosts regional headquarters for global PAAS vendors targeting enterprise accounts.
Global Procurement-As-A-Service (PAAS) Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with ERP integration capabilities. Tier-one consultancies and enterprise software vendors anchor relationships through bundled source-to-pay suites. Three archetypes dominate: ERP-native platforms with finance module extensions, managed analytics specialists with spend visibility tools, and pure-play sourcing consultancies with category expertise. Competitive moves concentrate on API connector library expansion and ISO 27001 certification acceleration.
Within the ERP-native tier, SAP SE exemplifies platform consolidation through native integration into finance and supply chain workflows. GEP anchors the pure-play sourcing consultancy archetype with embedded commodity intelligence for direct materials. WNS (Holdings) Limited occupies a distinct position in managed analytics for spend visibility, targeting mid-market manufacturers with limited in-house procurement technology capabilities.
| Leading Market Players |
|---|
| Accenture |
| GEP |
| IBM Corporation |
| Genpact |
| Infosys Limited |
| SAP SE |
| Coupa Software |
| WNS (Holdings) Limited |
| Capgemini |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs cascade through PAAS pricing tiers, with hyperscale data center investments in the United States and Germany filtering into subscription rates for enterprise buyers while mid-market manufacturers absorb higher per-seat costs from fragmented hosting architectures.
Pricing Analysis
Margin tightening in the mid-market tier reflects talent scarcity for ERP integration specialists commanding premium compensation. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 27001 certification status and API connector library depth. Price differentiation separates certified providers with embedded compliance automation from uncertified competitors facing RFP disqualification. Cost-down pressure on economy-tier offerings accelerates because Indian domestic operators leverage in-country infrastructure to undercut multinational hosting costs. Government agencies and BFSI procurement teams in India show highest price sensitivity due to budget constraints, while German automotive OEMs prioritize compliance-validated architectures over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for strategic sourcing modules, while value-added resellers and systems integrators serve mid-market manufacturers with limited procurement technology capabilities. Cloud infrastructure supply concentrates in the United States, Germany, and India, with hyperscale providers anchoring capacity expansion in Silicon Valley, Frankfurt, and Mumbai corridors. Raw material dependencies include semiconductor components for AI-enabled spend analytics, specialized labor for ERP integration architecture, and certified audit capacity for ISO 27001 compliance. Single-source vulnerability sits with concentrated API gateway providers whose outages disrupt multi-tenant platform operations. Distribution runs through partner networks embedding PAAS modules into broader enterprise transformation engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 27001 certification mandates are forcing architectural consolidation, eliminating uncertified providers from regulated industry procurement and compressing vendor diversity into a smaller pool of accredited operators.
For Market Incumbents: Hedge against margin erosion by accelerating API connector library expansion into SAP and Oracle ERP ecosystems while embedding EU AI Act compliance architectures as a defensive moat against pure-play sourcing consultancies. Capacity addition in Bangalore and Pune addresses India's BIS cloud localization requirements. Certification investment in ISO 27001 and emerging AI governance standards protects position in European automotive and aerospace procurement. For New Entrants and Emerging Players: Enter via the German Mittelstand segment where family-owned manufacturers with limited in-house sourcing capabilities remain underserved by enterprise-focused incumbents. White-space targets include spend analytics-AI convergence with natural language interfaces for mid-market manufacturers and traceability modules for US clean energy procurement under Inflation Reduction Act incentives. Channel partnership with regional ERP implementers offers the most penetrable go-to-market angle against direct sales forces. For Investors and Strategic Acquirers: Accelerating RFP disqualification of uncertified providers is the leading indicator that acquisition premiums will concentrate among ISO 27001-accredited operators with validated compliance architectures. Long-term viability favors platforms with embedded commodity intelligence for direct materials sourcing and pre-built ERP connectors. Vertically integrated mid-cap specialists with category expertise in automotive or pharmaceutical procurement represent the target acquisition archetype. Watch for EU AI Act enforcement actions as the inflection signal for compliance-validated platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acceleration | Eighteen-month audit cycles lock out uncertified competitors from BFSI and government RFPs in India and Europe. |
| API Connector Library Expansion | Pre-built SAP and Oracle integrations compress implementation timelines for German automotive OEM procurement teams. |
| EU AI Act Compliance Architecture | Human-in-the-loop engineering creates mandatory differentiation for European deployments in aerospace and automotive. |
| India Data Localization Investment | In-country infrastructure captures public sector spend channeled by BIS cloud service guidelines. |
| Spend Analytics-AI Convergence | Predictive cost modeling with natural language interfaces targets mid-market manufacturers abandoning rules-based tools. |
Research Methodology
Multi-period observation of cloud migration mandates, ISO 27001 certification timelines, and API standardization gaps anchored the trend analysis, supplemented by interviews with CIOs, procurement technology architects, ERP integration specialists, and category management directors at automotive and pharmaceutical manufacturers. Secondary validation drew from SEC filings of enterprise software vendors, EU AI Act implementation guidance, BIS cloud service guidelines, and customs data on enterprise technology imports. Bottom-up contract value aggregation across deployment models and service types triangulated against top-down market sizing from technology spend surveys.
Input-output matrices modeled relationships between infrastructure investment, certification penetration, and buyer adoption rates across the projection horizon. Segmentation dimensions included service type, deployment architecture, end-user scale, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year contract values, with cross-validation against vendor revenue disclosures and IT services trade data. Industry-specific forecast inputs incorporated CIO migration timeline surveys and EU AI Act compliance cost estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory fragmentation scenarios or accelerated cloud consolidation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Life Science Multichannel Campaign Management Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
Online Dating Market
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
Global Smart Lecture Capture System Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Global Application Container Market
Digital Solutions
Enterprise Application Integration (EAI) Market