
 Asia Pacific Pregnancy and Ovulation Testing Market | 2026-2036
Asia Pacific Pregnancy and Ovulation Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Pregnancy and Ovulation Testing Market Outlook
India's CDSCO medical device rules is recalibrating the cost-of-entry calculus for imported lateral-flow diagnostics, forcing foreign manufacturers to establish local testing infrastructure or partner with domestic license-holders. Abbott Laboratories leverages its established clinical channel presence to sustain volume leadership across hospital and laboratory segments. Wondfo Biotech anchors its competitive position through manufacturing scale and captive production of nitrocellulose membranes. Piramal Enterprises differentiates via backward integration into active reagent sourcing, reducing import dependency for enzyme conjugates.
Asia Pacific pregnancy and ovulation testing encompasses lateral-flow immunoassay devices, digital hormone monitors, and bench-top chemiluminescence systems that detect human chorionic gonadotropin or luteinizing hormone in urine or serum specimens, typically achieving sensitivity thresholds of 20-25 mIU/mL for home-use strips and sub-5 mIU/mL for clinical-grade analyzers. Urine Tests occupy the dominant volume position due to low unit cost and minimal user training, while Digital Monitors capture disproportionate margin pools through recurring consumable attachments and app-sync subscription features. Online Retail channels are expanding fastest, though Pharmacies retain structural importance in markets where physician referral norms still govern purchase behavior.
China's NMPA enforces GB standard compliance for in-vitro diagnostic reagents, while Australia's TGA maintains parallel conformity assessment pathways that delay multi-country launches. Japan's PMDA requires localized clinical validation for hormone-monitoring devices, creating additional registration timelines for non-domestic manufacturers. Stakeholders must monitor evolving digital-health classification debates, as regulators weigh whether app-connected fertility trackers fall under medical device or consumer-electronics frameworks.
Market Dynamics
The Asia Pacific pregnancy and ovulation testing market is experiencing a structural compression between rising regulatory stringency and the proliferation of connected fertility-tracking ecosystems that demand simultaneous hardware and software compliance.
Growth Catalysts
- Urban Fertility Awareness:Millennials in Chinese tier-one cities and Southeast Asian metropolises are integrating hormone-monitoring apps with e-pharmacy purchase behavior, creating recurring consumable demand for digital-compatible test strips.
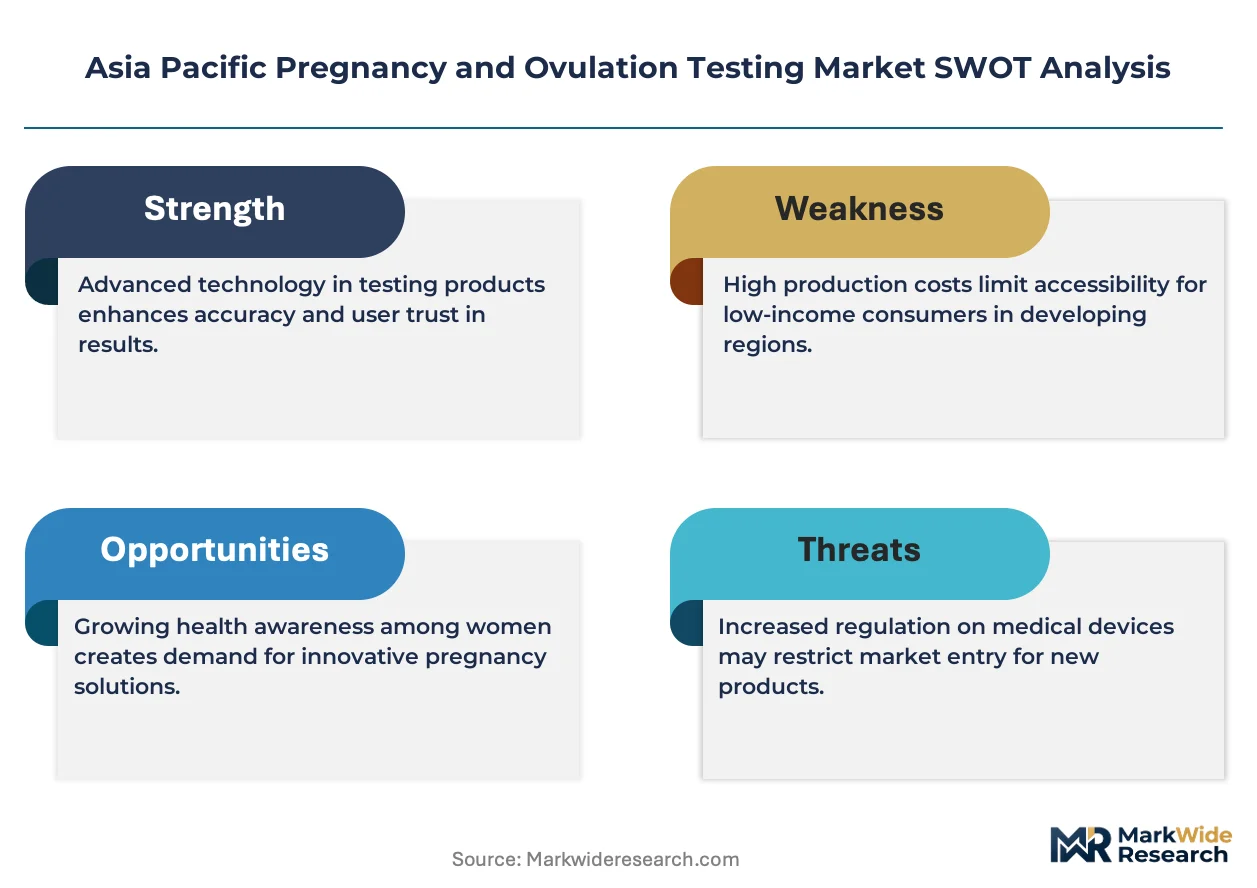
- CDSCO Rule Harmonization:India's tightened quality norms for imported lateral-flow diagnostics, while elevating compliance costs, are simultaneously clearing substandard competitors and rewarding manufacturers with established local testing infrastructure.
- Dual-Channel Convergence:The intersection of hospital laboratory procurement and direct-to-consumer online retail is expanding addressable volume for manufacturers capable of serving both specimen types—urine and serum—under unified brand architectures.
Market Restraints
- Nitrocellulose Membrane Concentration:Captive production of this critical substrate remains concentrated among a handful of East Asian suppliers, exposing manufacturers to input cost volatility and supply rationing during demand surges.
- PMDA Localization Timelines:Japan's pharmaceutical and medical device agency requires extended clinical validation cycles for hormone-monitoring devices, delaying multi-country product launches and compressing effective patent life.
- Serum-Based Substitution:Bench-top chemiluminescence analyzers in tertiary hospitals are displacing lateral-flow methods for early-pregnancy confirmation, constraining volume growth in the clinical-grade strip segment.
Strategic Opportunities
- Indonesian Archipelago Penetration:Low diagnostic access across Indonesia's 17,000 islands presents white space for community health worker-deployable digital monitors with offline data storage and intermittent sync capability.
- App-Connected Ecosystems:Convergence of fertility-tracking software with subscription-based consumable replenishment is unifying hardware margins with recurring revenue streams, particularly in Australia's high-disposable-income households.
- NMPA Digital Health Classification:China's ongoing deliberation over whether connected fertility trackers qualify as medical devices or consumer electronics creates a temporary regulatory arbitrage window for positioning products under lower-compliance frameworks.
Industry Challenges
- Multimodal Certification Complexity:Manufacturers pursuing simultaneous NMPA, TGA, and PMDA approvals face divergent clinical evidence requirements for hormone threshold validation, stretching regulatory affairs teams across incompatible study designs.
- Enzyme Conjugate Sourcing Fragility:Backward integration into active reagent production requires substantial capital deployment for fermentation capacity, creating a barrier for mid-scale entrants dependent on imported enzyme conjugates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Pregnancy and Ovulation Testing Market |
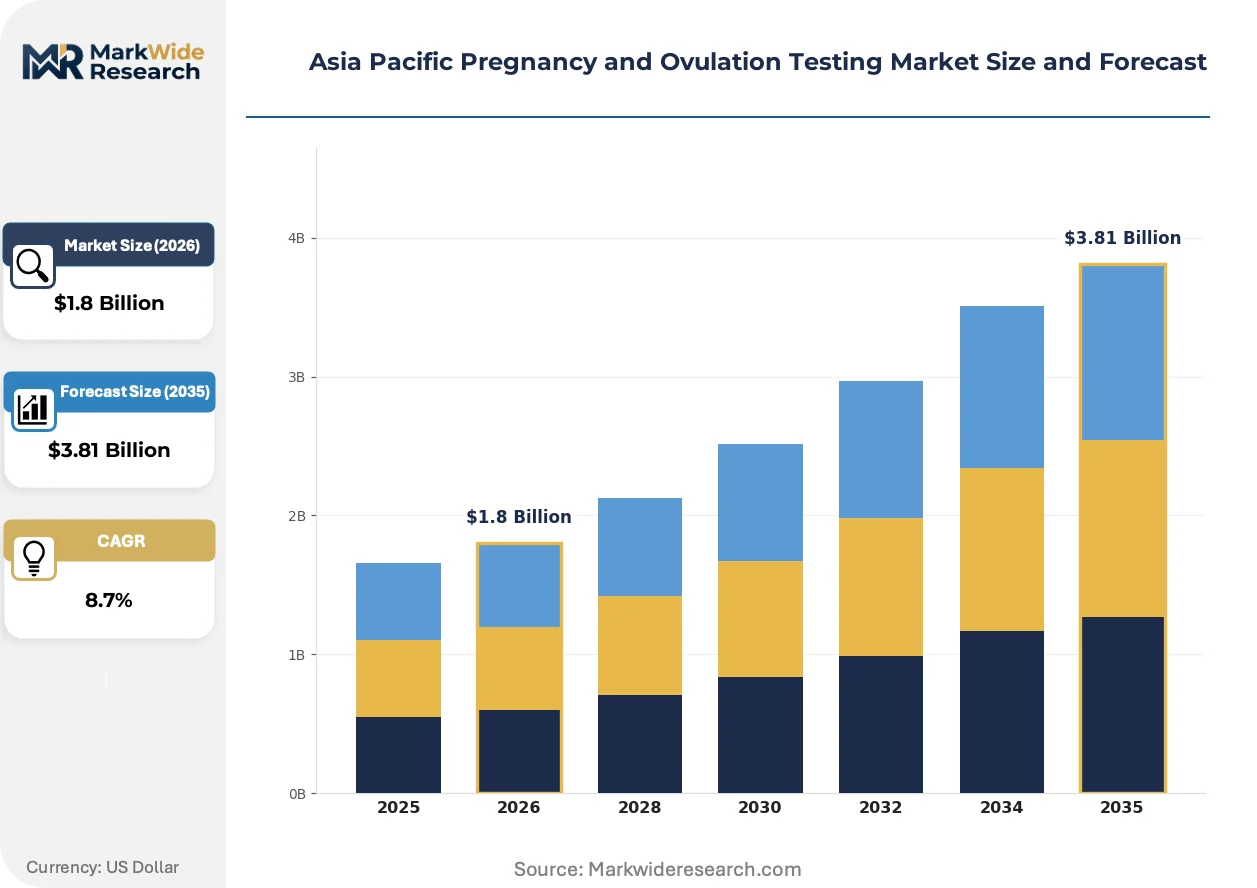
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Tests, Blood Tests, Digital Monitors, Ovulation Kits Application: Home Use, Clinical Use, Laboratory Use, Over-the-Counter Distribution Channel: Online Retail, Pharmacies, Hospitals, Supermarkets End User: Women, Healthcare Providers, Clinics, Retailers |
| Companies Covered | Quidel Corporation, Piramal Enterprises, Abbott Laboratories, Bayer, Wondfo Biotech Co. Ltd., Church & Dwight, SPD Swiss Precision Diagnostics, Roche, Procter & Gamble Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Pregnancy and Ovulation Testing Market Strategic Shifts
Hardware-software integration is redefining competitive moats in Asia Pacific fertility diagnostics, with differentiation migrating from test sensitivity specifications to data continuity and predictive algorithm accuracy.
Bluetooth-enabled lateral-flow readers are unifying physical specimen collection with cloud-based cycle analytics, allowing urban Chinese consumers to archive longitudinal hormone patterns. Adoption concentrates among dual-income households in Shanghai and Beijing seeking conception optimization. This unification is compressing standalone strip margins while expanding total addressable revenue per user through app subscription attach rates.
Australia's TGA maintains parallel conformity assessment pathways that delay synchronized regional launches, forcing manufacturers to sequence market entry around divergent evidence standards. The industrial consequence is fragmented inventory management and duplicated clinical study costs. Hospital and laboratory segments absorb these delays through extended tender cycles, while direct-to-consumer channels face compressed product refresh timelines.
Subscription-based consumable replenishment is displacing pharmacy-led episodic purchasing among Southeast Asian urban millennials, with automated reorder triggers embedded in fertility-tracking applications. E-pharmacy platforms in Vietnam and Thailand are capturing this behavioral shift through bundled hardware-plus-consumable offerings. The Philippines exhibits the most pronounced channel rotation, where mobile wallet penetration enables seamless recurring payment authorization for hormone monitoring supplies.
Asia Pacific Pregnancy and Ovulation Testing Market Segmentation
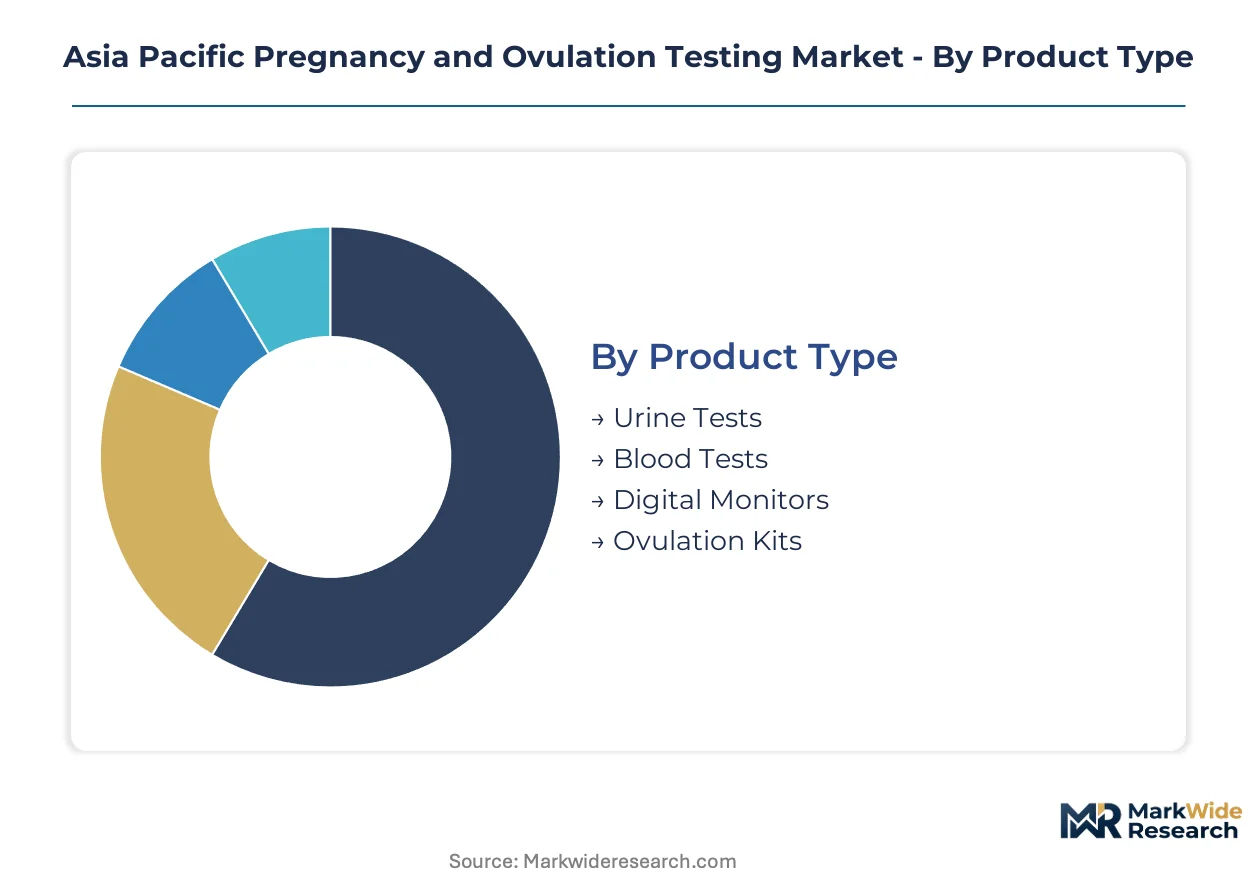
Product architecture and distribution pathways in Asia Pacific fertility diagnostics diverge sharply across certification tiers, with home-use strips facing lighter NMPA scrutiny than clinical-grade analyzers. Segment boundaries blur where digital monitors sync with hospital information systems, triggering dual classification debates.
Product Type:
Certification burden stratifies sharply: urine strips qualify under simplified IVD pathways in China and India, while digital monitors and blood-based systems trigger PMDA-level clinical validation cycles in Japan.
- Urine Tests:Lateral-flow immunoassay strips detecting hCG or LH at 20-25 mIU/mL sensitivity thresholds. Demand concentrates in Southeast Asian urban centers where pharmacy-led distribution still governs purchase behavior, though e-pharmacy encroachment accelerates in Vietnamese and Thai metros.
- Digital Monitors:Bluetooth-enabled hormone readers with cloud-sync capabilities and subscription-based consumable replenishment. Shanghai and Beijing dual-income households absorb premium pricing for conception-optimization features, compressing standalone strip margins through app attach rates.
- Blood Tests:Serum-based quantitative hCG assays requiring venipuncture collection and laboratory processing.
- Ovulation Kits:LH surge detection systems packaged for multi-cycle use with calendar-tracking accessories.
Leading the category by volume: Urine Tests. Growing fastest: Digital Monitors.
Application:
End-use setting determines reimbursement eligibility and regulatory surveillance intensity, with hospital laboratory procurement subject to tender cycles that elongate product refresh timelines.
- Home Use:Self-administered specimen collection with minimal user training requirements. Tier-one Chinese cities and Australian high-disposable-income households drive hardware-plus-consumable bundling through fertility-tracking app ecosystems.
- Clinical Use:Point-of-care deployment in obstetric clinics and community health centers requiring operator certification. Indonesia's 17,000-island geography creates white space for offline-data-capable monitors deployable by community health workers.
- Laboratory Use:Bench-top chemiluminescence analyzers in tertiary hospitals displacing lateral-flow methods for early-pregnancy confirmation.
- Over-the-Counter:Pharmacy-shelf availability without prescription requirements, dominant in India's fragmented retail landscape.
Home Use commands absolute volume. Clinical Use climbs fastest on archipelago penetration.
Distribution Channel:
Channel selection locks in margin structure and customer acquisition economics, with online retail capturing recurring revenue through subscription triggers embedded in fertility apps.
- Online Retail:E-pharmacy platforms and direct-to-consumer storefronts with automated replenishment algorithms. Mobile wallet penetration in the Philippines enables seamless recurring payment authorization for hormone monitoring supplies.
- Pharmacies:Brick-and-mortar dispensaries retaining structural importance where physician referral norms govern purchase behavior, particularly in Japanese and South Korean markets.
- Hospitals:Institutional procurement through centralized tender processes with extended qualification timelines.
- Supermarkets:Mass retail placement for economy-tier strip products with minimal brand differentiation.
Pharmacies still lead by transaction volume. Online Retail expands most quickly on subscription attach rates.
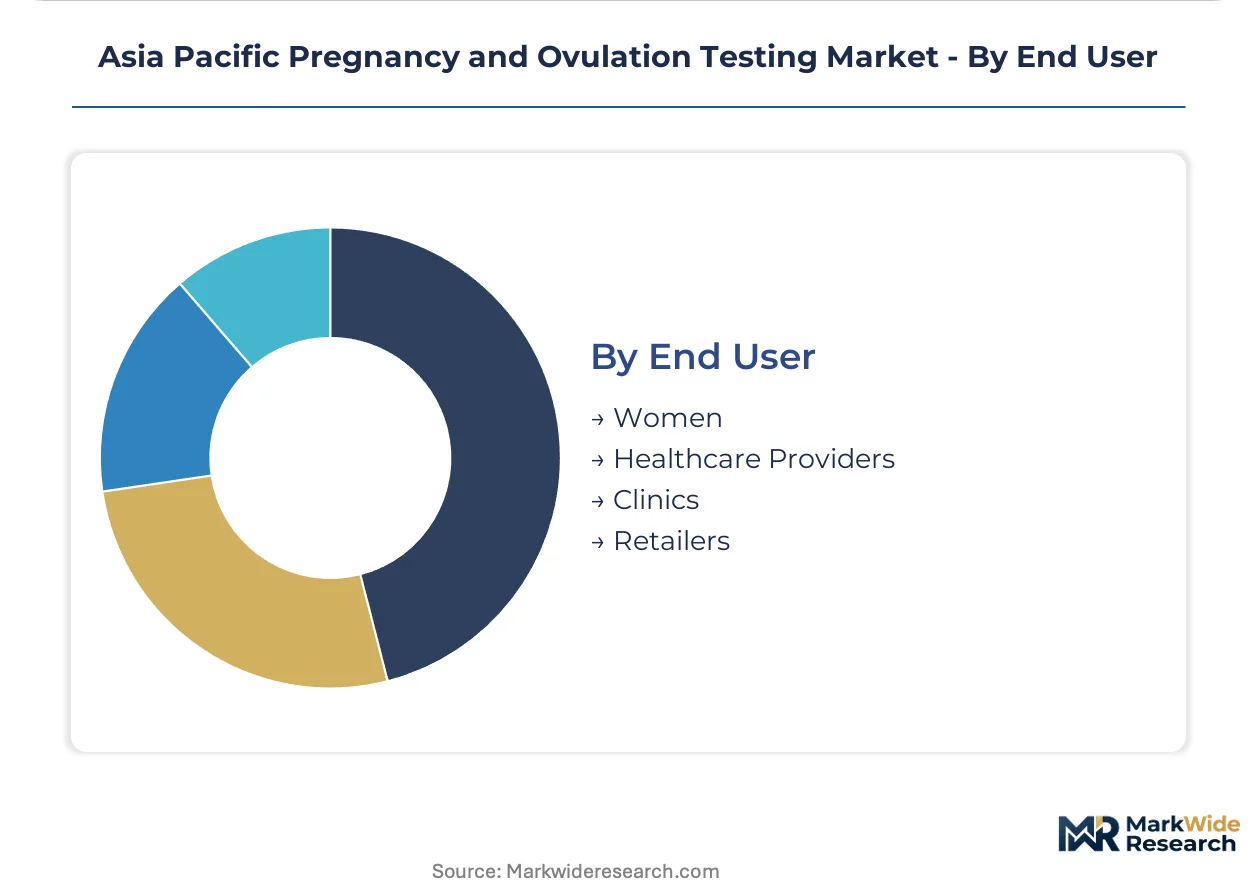
End User:
User identity shapes product specification priorities, with healthcare provider segments demanding traceability and calibration documentation absent from consumer-oriented offerings.
- Women:Individual consumers making autonomous purchase decisions based on app-integrated cycle analytics and peer recommendation networks. Urban millennials across Southeast Asia integrate hormone-monitoring apps with e-pharmacy behavior.
- Healthcare Providers:Physicians and nurse practitioners requiring quantitative results with audit trails for clinical documentation. Australia's TGA conformity assessment pathways impose documentation burdens that filter supplier pools.
- Clinics:Small-scale diagnostic facilities balancing equipment cost against test menu breadth.
- Retailers:Pharmacy chains and e-commerce platforms acting as intermediaries with private-label sourcing strategies.
Women constitute the dominant user base. Healthcare Providers show steepest expansion trajectory on clinical-grade digital adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's Yangtze River Delta and India's pharmaceutical clusters concentrate manufacturing capacity for lateral-flow diagnostics. These tax-advantaged enclaves attract foreign direct investment through streamlined customs procedures and duty exemptions on imported reagents.
China
Shanghai and Beijing dual-income households drive premium digital monitor adoption through app-integrated fertility tracking. NMPA enforces GB standard compliance for in-vitro diagnostic reagents, extending registration timelines for hardware-software combinations. The Yangtze River Delta industrial corridor hosts captive nitrocellulose membrane production facilities serving domestic and export markets.
India
Urban millennials in Mumbai and Bangalore integrate ovulation tracking with e-pharmacy purchase behavior. CDSCO tightened quality norms for imported lateral-flow diagnostics, elevating compliance costs for new entrants. The pharmaceutical manufacturing belt around Ahmedabad and Hyderabad anchors contract testing infrastructure for foreign license-holders.
Japan
PMDA requires localized clinical validation for hormone-monitoring devices, delaying multi-country product launches. Tokyo and Osaka metropolitan areas concentrate specialist fertility clinic networks demanding quantitative hCG assays with audit trails. The Kansai region hosts precision electronics fabricators supplying Bluetooth-enabled reader components.
Australia
TGA maintains parallel conformity assessment pathways that fragment regional launch sequencing. Sydney and Melbourne households absorb premium pricing for subscription-based consumable replenishment. The domestic market's high disposable income supports early adoption of app-connected fertility ecosystems.
Indonesia
Archipelago geography creates white space for community health worker-deployable digital monitors with offline data storage. Jakarta and Surabaya urban centers concentrate pharmacy-led distribution networks. The 17,000-island nation exhibits the widest diagnostic access gaps in Southeast Asia.
Asia Pacific Pregnancy and Ovulation Testing Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers and distribution channels. Market structure stratifies between multinational clinical diagnostics divisions, regional manufacturing-scale players, and domestic license-holders leveraging regulatory arbitrage. Three archetypes dominate: captive substrate producers, backward-integrated reagent formulators, and app-ecosystem orchestrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers navigate divergent NMPA, TGA, and PMDA evidence requirements.
Among diversified healthcare conglomerates, Abbott Laboratories and Roche occupy positions spanning hospital laboratory and direct-to-consumer segments. Piramal Enterprises exemplifies the backward-integrated archetype through active reagent sourcing capabilities. Wondfo Biotech Co. Ltd. represents manufacturing-scale specialization with Zhengzhou-based production infrastructure. Quidel Corporation and SPD Swiss Precision Diagnostics sit within the premium-tier certification bracket serving clinical-grade demand. Church & Dwight, Bayer, and Procter & Gamble Co. anchor mass-market consumer positioning through pharmacy and supermarket channels.
| Leading Market Players |
|---|
| Quidel Corporation |
| Piramal Enterprises |
| Abbott Laboratories |
| Bayer |
| Wondfo Biotech Co. Ltd. |
| Church & Dwight |
| SPD Swiss Precision Diagnostics |
| Roche |
| Procter & Gamble Co. |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals gate qualified nitrocellulose membrane supply and premium-tier digital monitor pricing access, as carbon-intensive substrate production faces emission quota constraints that concentrate compliant capacity among Yangtze River Delta fabricators serving NMPA-certified manufacturers.
Pricing Analysis
Lead-time-driven pricing stratifies procurement economics, with hospital tenders commanding 15-20% premiums for 30-day delivery guarantees while spot inventory in Southeast Asian e-pharmacies trades at discounted clearance levels. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled app-sync monitors from basic lateral-flow strips and bulk unbranded cassettes. Cost compression in economy-tier strips is intensifying because Indonesian and Vietnamese contract manufacturers are absorbing margin erosion to secure volume commitments from supermarket private-label buyers. Price-sensitive archipelago community health workers drive demand for economy-tier ovulation cassettes, while Australian dual-income households exhibit minimal sensitivity to subscription pricing for conception-optimization ecosystems.
Supply Chain Analysis
Certification gating through NMPA, PMDA, and TGA pathways fragments qualified supplier pools, with only Zhengzhou-based membrane fabricators and Kansai-region electronics assemblers holding concurrent multi-regulatory approvals. Geographic supply concentration centers on China for nitrocellulose substrates and antibody conjugates, Japan for precision Bluetooth components, and India for contract fermentation of enzyme reagents. Raw material dependencies rest on East Asian nitrocellulose membrane production, imported colloidal gold nanoparticles, and fermentation-derived monoclonal antibodies. Single-source vulnerability in membrane supply exposes manufacturers to allocation rationing during demand surges. Distribution runs through hospital procurement consortia in Japan and Australia, pharmacy-led networks in India and Indonesia, and direct-to-consumer e-pharmacy platforms in China and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive nitrocellulose membrane production and backward integration into enzyme conjugate fermentation determine margin sustainability against import-dependent competitors.
For Market Incumbents: To counter CDSCO compliance cost escalation for imported lateral-flow diagnostics, Abbott Laboratories and Wondfo Biotech should deepen captive membrane production in Yangtze River Delta tax-advantaged zones while securing dual-source antibody conjugate supply from Ahmedabad and Hyderabad fermentation clusters. For New Entrants and Emerging Players: Enter via Indonesia's 17,000-island diagnostic access gap with offline-data-capable digital monitors deployable by community health workers, leveraging mobile wallet penetration in the Philippines for subscription-based consumable replenishment through bundled hardware-plus-app offerings. For Investors and Strategic Acquirers: PMDA localization timeline compression for hormone-monitoring devices is the leading indicator that Japanese clinical validation capabilities will command acquisition premiums; target backward-integrated reagent formulators with established CDSCO testing infrastructure and NMPA dual-registration pathways for 5-10 year viability in converging hardware-software fertility ecosystems.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Nitrocellulose Membrane Production | Zhengzhou and Yangtze Delta fabricators secure supply allocation priority during demand surges. |
| CDSCO Local Testing Infrastructure | Ahmedabad and Hyderabad contract labs reduce compliance timelines for imported lateral-flow diagnostics. |
| PMDA Clinical Validation Partnership | Tokyo and Osaka fertility clinic networks accelerate hormone-threshold evidence generation. |
| App-Connected Ecosystem Development | Shanghai and Beijing dual-income households generate recurring subscription revenue through fertility-tracking software. |
| Indonesian Archipelago Distribution | Offline-data-capable monitors address diagnostic access gaps across 17,000 islands via community health worker deployment. |
Study Parameters
Independent corroboration across NMPA registration filings, CDSCO import quality audits, and PMDA clinical validation summaries underwrites the qualitative findings, combining primary interviews with hospital procurement managers, biomedical engineers at tertiary fertility clinics, GPO contracts managers, and e-pharmacy platform executives with secondary validation from customs trade data, hospital tender databases, and GPO contract repositories. Bottom-up demand modeling across urine test strip volumes, digital monitor hardware shipments, and subscription attach rates triangulates against top-down market sizing.
Comparable-period anchoring to historical NMPA approval cycles, CDSCO rule harmonization phases, and PMDA localization timelines structures the projection horizon. Segmentation dimensions modeled include product architecture tier, end-use setting, distribution channel economics, and regulatory certification cluster. CAGRs derive from volume trajectory analysis calibrated to e-pharmacy penetration curves and fertility-app adoption patterns, with sensitivity testing against nitrocellulose membrane supply constraints and enzyme conjugate import dependency.
Revisions become necessary when NMPA digital health classification rulings reclassify app-connected fertility trackers, CDSCO tightens lateral-flow diagnostic quality norms beyond current testing infrastructure capacity, or PMDA accelerates hormone-monitoring device validation timelines. A model refresh is warranted upon material change in nitrocellulose membrane supply allocation protocols or carbon emission quota enforcement intensity in Yangtze River Delta manufacturing zones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Drug Testing Equipment Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Testing and Analysis Services Market
Testing Services
Over-The-Counter Tests Market
Testing Services
Biomarker Testing Services Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Point of Care Testing Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Antimicrobial Susceptibility Testing Market