
 Ferritin Testing Market | 2026-2036
Ferritin Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Ferritin Testing Market Analysis
The capital-intensity divergence between automated platform vendors and niche assay developers is rotating competitive investment toward integrated chemistry-immunoassay systems. Roche Diagnostics leverages its cobas platform ecosystem to sustain installed-base loyalty across high-throughput hospital laboratories. Siemens Healthineers anchors its position through Atellica solution scalability, while Thermo Fisher Scientific competes via reagent flexibility and open-architecture compatibility with third-party analyzers.
Ferritin testing quantifies iron storage protein concentration in biological specimens, typically via immunochemical detection with functional sensitivity thresholds of 0.5–1.0 ng/mL for clinical-grade assays. The primary commercial purpose centers on diagnosing iron deficiency anemia, monitoring iron overload disorders such as hemochromatosis, and assessing nutritional status in chronic inflammatory conditions. Chemiluminescence immunoassay technology dominates routine diagnostic workflows due to throughput advantages and precision, while point-of-care ferritin tests represent the fastest-expanding segment as decentralized care models gain structural traction. Hospitals and diagnostic laboratories remain the most concentrated margin pools, though home healthcare channels are emerging as volume growth frontiers.
FDA 510(k) clearance requirements and CLIA laboratory certification standards shape product development timelines and market access barriers for ferritin assay manufacturers. The EU In Vitro Diagnostic Regulation imposes strengthened clinical evidence and post-market surveillance obligations on European market entrants. Stakeholders must monitor evolving payer coverage determinations for point-of-care ferritin testing and the trajectory of laboratory consolidation on procurement centralization.
Market Dynamics
Platform consolidation among hospital laboratories is compressing procurement cycles and privileging vendors with integrated chemistry-immunoassay ecosystems over standalone ferritin assay suppliers.
Growth Catalysts
- CLIA laboratory certification standards:The Centers for Medicare & Medicaid Services mandates quality systems for moderate-complexity testing, expanding the addressable base for certified ferritin assays in US hospital networks.
- Chronic disease protocols:Hematology and nephrology departments now embed iron status panels into routine monitoring workflows for dialysis and inflammatory bowel disease populations.
- Point-of-care lateral flow technology:Capillary blood collection methods enable ferritin quantification in physician office laboratories without phlebotomy infrastructure.
Market Restraints
- Reagent cost volatility:Monoclonal antibody conjugates and chemiluminescent substrates face price instability from mammalian cell culture supply constraints.
- Reference material concentration:The Joint Committee for Traceability in Laboratory Medicine and WHO standards dominate calibrator sourcing, creating single-source dependency for assay harmonization.
- Interference limitations:Heterophile antibodies and rheumatoid factor generate false elevation in immunochemical ferritin measurements, necessitating costly confirmatory testing.
Strategic Opportunities
- Home healthcare channels:Direct-to-consumer laboratory testing platforms are incorporating ferritin into wellness subscription panels for nutritional optimization.
- EU In Vitro Diagnostic Regulation:MDR clinical evidence requirements for Class C devices create first-mover advantage for manufacturers with established performance studies.
- Digital health convergence:Integration of ferritin results with electronic health record analytics and patient-facing applications enables longitudinal iron status monitoring.
Industry Challenges
- Assay harmonization complexity:Standardization across Abbott, Roche, and Siemens platforms requires extensive commutability studies and reference interval validation.
- Legacy analyzer integration:Hospital laboratories demand backward compatibility with installed-base instruments, constraining novel assay format development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferritin Testing Market |
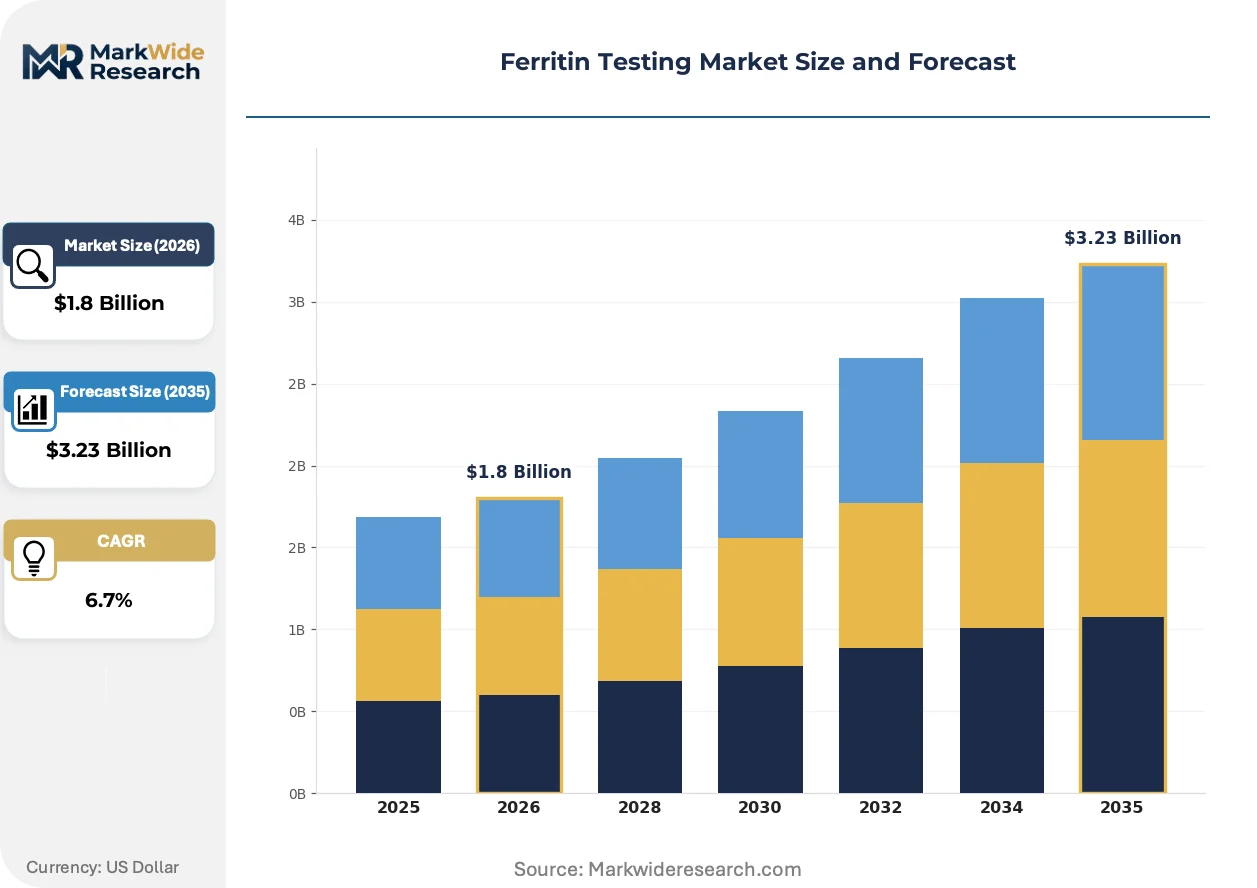
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum Ferritin, Plasma Ferritin, Ferritin Assays, Point-of-Care Ferritin Tests End User: Hospitals, Diagnostic Laboratories, Home Healthcare, Research Institutes Technology: Immunoassay, Chemiluminescence, ELISA, Mass Spectrometry Application: Iron Deficiency Diagnosis, Chronic Disease Monitoring, Anemia Assessment, Nutritional Status Evaluation |
| Companies Covered | Roche Diagnostics, Siemens Healthineers, Thermo Fisher Scientific, Abbott Laboratories, bioMérieux, Eurolyser Diagnostica GmbH, Cortez Diagnostics Inc, Aviva Systems Biology Corporation, Abnova Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferritin Testing Market Emerging Trajectories
Multiplexed biomarker panels and decentralized testing infrastructure are restructuring how iron status assessments reach patients, compressing the traditional centralized laboratory model.
Photonic biosensors employing surface plasmon resonance detection are displacing conventional enzyme-linked immunosorbent assays in research and specialized clinical settings. Academic medical centers and reference laboratories in Germany and Japan are piloting label-free ferritin quantification for research use. This displacement is compressing reagent consumption per test and enabling real-time kinetic binding analysis previously unavailable in clinical ferritin testing.
The FDA's ongoing IVD regulatory modernization initiative is streamlining 510(k) clearance pathways for novel biomarker formats while tightening predicate device equivalence standards. Manufacturers must now demonstrate analytical performance against recognized reference methods rather than legacy comparator assays. High-throughput hospital laboratories in the United States are responding by consolidating validation studies and prioritizing assays with established traceability to WHO reference materials.
Health system procurement departments are unbundling reagent contracts from analyzer placement agreements, shifting toward volume-commitment pricing independent of capital equipment subsidies. Integrated delivery networks in Texas and California are negotiating directly with assay manufacturers for ferritin and iron panel reagents. This unbundling is most visible in multi-hospital systems seeking operational flexibility amid laboratory consolidation.
Ferritin Testing Market Segmentation
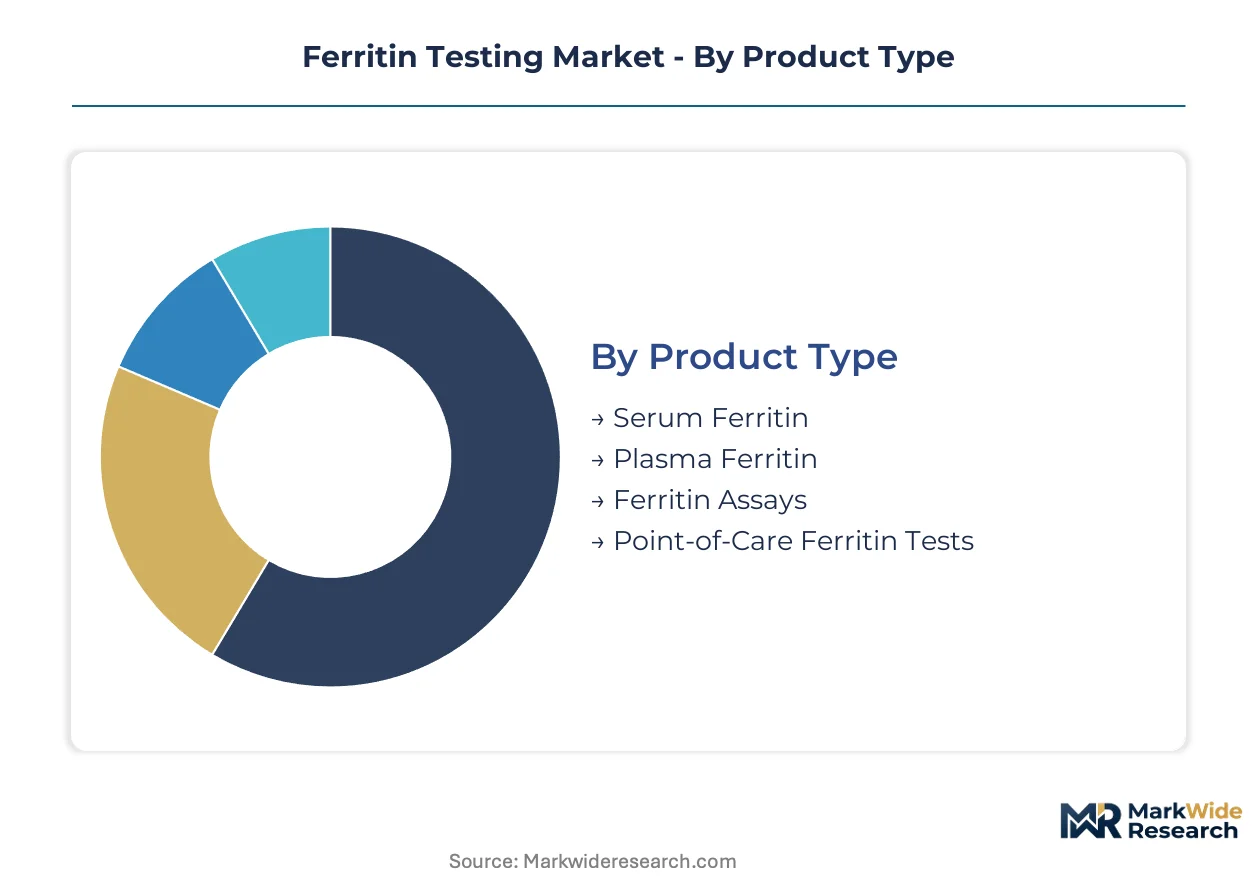
Ferritin testing segments diverge sharply by regulatory pathway complexity, with CLIA-waived point-of-care formats facing distinct FDA scrutiny compared to high-complexity laboratory assays. Procurement concentration in integrated delivery networks rewards vendors who harmonize product portfolios across multiple segment boundaries.
Product Type:
Regulatory differentiation separates laboratory-developed tests from commercially distributed kits, with FDA 510(k) clearance requirements varying by specimen matrix and intended use setting.
- Serum Ferritin:Gold-standard specimen type collected via venipuncture and processed on automated chemistry-immunoassay platforms. Hospital laboratories in the United States standardize procurement around serum-based workflows for iron deficiency and hemochromatosis screening.
- Plasma Ferritin:Anticoagulated specimen alternative enabling rapid processing without clotting delays. Emergency departments and STAT laboratories favor plasma protocols for accelerated turnaround in acute anemia assessments.
- Ferritin Assays:Reagent kits and calibrator materials sold to laboratories with existing analyzer infrastructure.
- Point-of-Care Ferritin Tests:CLIA-waived lateral flow devices for capillary blood collection in physician office laboratories.
Serum ferritin handles the majority of throughput; point-of-care ferritin tests are expanding most quickly on share.
End User:
Cost tier differentiation structures procurement authority, with capital-intensive hospital systems negotiating enterprise contracts while home healthcare channels fragment purchasing across direct-to-consumer platforms.
- Hospitals:High-throughput inpatient and outpatient departments integrating ferritin into chronic disease order sets. Integrated delivery networks in Texas and California centralize reagent procurement across multi-facility footprints.
- Diagnostic Laboratories:Reference laboratories and regional testing facilities processing specimens from affiliated physician networks.
- Home Healthcare:Direct-to-consumer wellness platforms and remote patient monitoring services incorporating ferritin into subscription nutritional panels.
- Research Institutes:Academic medical centers and pharmaceutical sponsors utilizing ferritin as biomarker endpoints in clinical trials.
Hospital laboratories concentrate the highest test volumes; home healthcare channels are climbing the fastest on patient-access expansion.
Technology:
Application specificity determines technology selection, with routine diagnostic workflows prioritizing throughput and precision while specialized settings demand analytical sensitivity or multiplexing capability.
- Immunoassay:Broad category encompassing sandwich and competitive binding formats for ferritin quantification.
- Chemiluminescence:Dominant routine diagnostic modality combining functional sensitivity of 0.5–1.0 ng/mL with throughput exceeding hundreds of tests hourly. Siemens Healthineers and Roche Diagnostics anchor installed-base loyalty through proprietary chemiluminescence ecosystems.
- ELISA:Enzyme-linked format retaining relevance in research settings and resource-limited environments lacking automated platform infrastructure.
- Mass Spectrometry:Reference method for assay standardization and harmonization studies traceable to WHO materials.
Chemiluminescence commands the dominant installed base; mass spectrometry is gaining methodological authority fastest on reference standardization mandates.
Application:
Volume concentration aligns with chronic disease prevalence and reimbursement policy, with iron deficiency screening sustaining baseline demand while nutritional optimization emerges as a discretionary growth frontier.
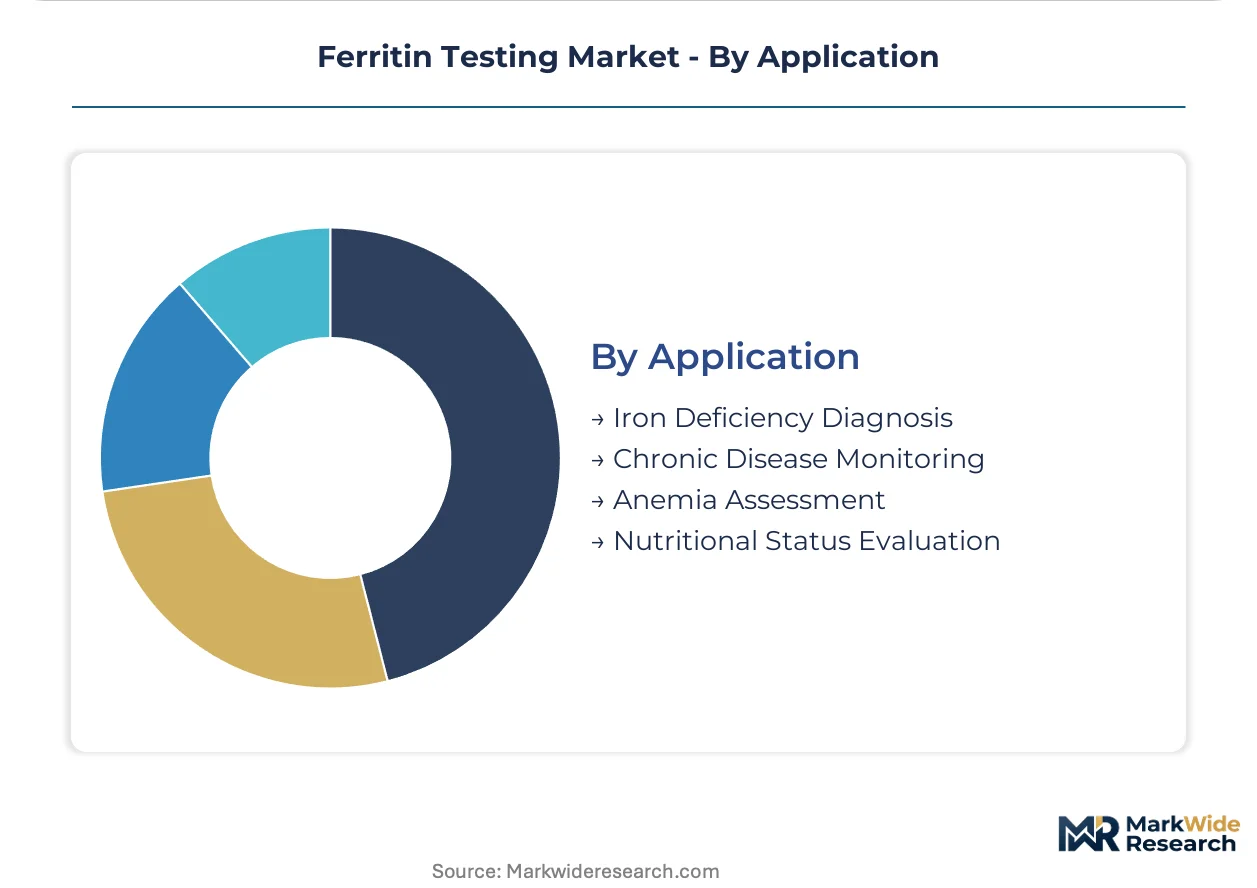
- Iron Deficiency Diagnosis:Primary clinical indication for ferritin testing in symptomatic patients and preoperative screening protocols. Hematology departments in the United States embed ferritin into routine anemia workups per CMS quality metrics.
- Chronic Disease Monitoring:Longitudinal iron status assessment in dialysis populations and inflammatory bowel disease cohorts.
- Anemia Assessment:Differential diagnosis of microcytic versus normocytic anemia patterns in primary care and specialty referrals.
- Nutritional Status Evaluation:Wellness and sports medicine applications tracking iron stores in asymptomatic populations.
Iron deficiency diagnosis absorbs the greatest test volume; nutritional status evaluation is the steepest expansion trajectory on consumer wellness platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while procurement fragmentation characterizes European hospital networks. Germany and Japan command premium positions through reference laboratory consolidation. Emerging volume growth clusters in India and Brazil operate on compressed margin structures.
United States
Hospital laboratory consolidation across Texas and California integrated delivery networks centralizes ferritin reagent procurement at scale. FDA 510(k) clearance pathways and CLIA certification standards shape product development timelines for domestic manufacturers. The Mayo Clinic and Cleveland Clinic reference laboratories anchor harmonization studies traceable to WHO standards.
Germany
Academic medical centers in Munich and Heidelberg pilot photonic biosensor platforms for label-free ferritin quantification in research settings. The EU In Vitro Diagnostic Regulation imposes strengthened clinical evidence obligations on Class C device manufacturers. The Rhine-Main cluster concentrates diagnostic platform development alongside Frankfurt's laboratory infrastructure.
Japan
Aging demographics and elevated anemia prevalence in hospitalized populations sustain high test utilization rates across Tokyo and Osaka metropolitan areas. PMDA regulatory frameworks align with international harmonization initiatives for IVD performance standards. The Kansai region hosts specialized reference laboratories advancing mass spectrometry-based assay standardization.
India
Diagnostic laboratory chains in Maharashtra and Karnataka expand ferritin test volumes as chronic disease protocols penetrate tier-2 cities. CDSCO regulatory pathways for IVD imports create market access considerations for multinational assay suppliers. The Delhi-NCR corridor concentrates reference testing capacity serving northern hospital networks.
Brazil
Hemodialysis population growth in São Paulo and Rio de Janeiro drives iron status panel integration into nephrology monitoring workflows. ANVISA regulatory requirements shape import registration timelines for European and North American assay manufacturers. The Southeast region anchors diagnostic laboratory consolidation amid private health system expansion.
Ferritin Testing Market Vendor Landscape
Concentration sits with integrated diagnostic platform vendors commanding installed-base loyalty through chemistry-immunoassay ecosystems. The vendor structure tiers between multinational conglomerates with proprietary analyzer ecosystems and specialized reagent suppliers competing on open-architecture compatibility. Two strategic archetypes dominate: scale-driven platform vendors leveraging throughput advantages and niche assay developers targeting decentralized testing channels. Competitive moves center on reagent contract unbundling from analyzer placement agreements and backward integration into monoclonal antibody production.
Among Swiss and German diagnostic conglomerates, Roche Diagnostics and Siemens Healthineers occupy positions exemplifying the integrated platform archetype through cobas and Atellica ecosystem dominance. Thermo Fisher Scientific represents the reagent-flexibility vector competing via open-architecture compatibility with third-party analyzers. These three anchors illustrate the capital-intensity divergence rotating competitive investment toward automated systems over standalone ferritin assay formats.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| bioMérieux |
| Eurolyser Diagnostica GmbH |
| Cortez Diagnostics Inc |
| Aviva Systems Biology Corporation |
| Abnova Corporation |
| Others |
Supply Flow & Price Mechanics
Monoclonal antibody conjugate substitution for polyclonal reagents in chemiluminescence ferritin assays simultaneously redraws supplier geography toward mammalian cell culture hubs in Switzerland and Germany while compressing per-test reagent economics across hospital laboratory networks.
Pricing Analysis
The customization-premium spread between analyzer-locked reagent contracts and open-architecture assay kits structures procurement negotiations across integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels separates Roche and Siemens ecosystem bundles from Thermo Fisher flexible reagents and niche ELISA suppliers. Cost compression in the point-of-care segment is intensifying because CLIA-waived lateral flow manufacturers compete on capillary collection simplicity. Research institutes exhibit the least price sensitivity due to grant-funded biomarker validation requirements, while diagnostic laboratory chains in tier-2 Indian cities demonstrate acute sensitivity to per-test reagent costs.
Supply Chain Analysis
Inbound logistics costs for temperature-sensitive chemiluminescent substrates face periodic disruption along the Shanghai-Rotterdam and Busan-Los Angeles trade lanes, particularly during peak cold-chain pharmaceutical shipping seasons. Mammalian cell culture facilities in Switzerland, Germany, and Massachusetts anchor monoclonal antibody production for ferritin assay conjugates. Raw material dependencies center on fetal bovine serum, acridinium ester chemiluminescent labels, and WHO-traceable calibrator materials. Single-source vulnerability concentrates around the Joint Committee for Traceability in Laboratory Medicine reference standards. Distribution runs through diagnostic platform vendors with direct hospital laboratory contracts, supplemented by specialized reagent distributors serving open-architecture analyzer installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ferritin testing market is approaching a platform-economics inflection where installed-base loyalty in automated chemistry-immunoassay ecosystems determines reattach rates and multi-year contract renewals.
For Market Incumbents: Shield analyzer-installed-base positions by deepening backward integration into monoclonal antibody production facilities in Switzerland and Germany, reducing exposure to fetal bovine serum price volatility. Accelerate FDA 510(k) clearance pipelines for multiplexed iron panel formats to preempt point-of-care lateral flow encroachment on routine screening volumes.
For New Entrants and Emerging Players: EU MDR Class C device certification fast-tracks create first-mover positioning for manufacturers with established clinical performance studies against WHO reference materials. Target home healthcare channels in the United States and Germany where direct-to-consumer wellness platforms fragment purchasing authority and reward assay flexibility over throughput scale. Pursue open-architecture compatibility certifications with third-party analyzer manufacturers to bypass capital-intensive platform development.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic reagent specialists possessing established CLIA-waived point-of-care portfolios and European MDR technical documentation. Long-term viability hinges on defensible positions in reference material traceability and photonic biosensor research partnerships. The signal to watch is unbundling velocity in Texas and California integrated delivery networks, where volume-commitment pricing independent of analyzer placement indicates procurement department maturation and vendor switching elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined pathways for novel ferritin biomarker formats tighten predicate equivalence standards against reference methods. |
| EU MDR Class C Certification | Strengthened clinical evidence requirements create barriers for manufacturers lacking WHO-traceable performance studies. |
| Hospital System Partnership | Integrated delivery networks in Texas and California centralize reagent procurement across multi-facility footprints. |
| Software Companion Development | Electronic health record analytics integration enables longitudinal iron status monitoring for chronic disease populations. |
| Reimbursement Strategy | Payer coverage determinations for point-of-care ferritin testing shape decentralized care model economics. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hospital laboratory directors, diagnostic platform procurement managers, CLIA compliance officers, and reference laboratory scientific directors; and secondary validation against FDA 510(k) filings, CMS CLIA certification databases, EU MDR technical documentation, and hospital GPO contract disclosures. Bottom-up triangulation across assay volume estimates and top-down reconciliation against installed-base analyzer counts ensured cross-verification.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning specimen matrix type, technology modality, end-user setting, and geographic regulatory cluster. CAGRs were derived from test volume trajectories weighted by reimbursement policy evolution and laboratory consolidation patterns. Industry-specific inputs included dialysis population growth projections and point-of-care CLIA waiver expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA regulatory modernization momentum or accelerated EU MDR enforcement would require recalibration. Forecasts reflect embedded assumptions regarding reference material harmonization progress and monoclonal antibody supply chain stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Bioprocess Integrity Testing Systems Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Pneumococcal Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Mono Rapid Testing Market
Testing Services
At-Home Testing Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Home Menopause Testing Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Urine Sediment Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Biological Indicator Incubators Market