
 Europe Medical Device Testing Market | 2026-2036
Europe Medical Device Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Device Testing Market Foresight
Biostatistician and regulatory toxicologist talent is rotating toward European notified bodies and contract laboratories faster than universities can replenish pipelines. TÜV SÜD leverages its Munich headquarters to dominate MDR conformity assessment backlogs across Class III devices. SGS SA anchors its European network with expanded biocompatibility screening capacity in Switzerland and France. Bureau Veritas competes aggressively on turnaround time for active implantable electrical safety testing.
Europe medical device testing encompasses the analytical and clinical validation services required to demonstrate safety, performance, and quality management compliance for devices sold in EU member states, including biocompatibility screening per ISO 10993, electrical safety verification against IEC 60601, and sterilization validation. Its primary commercial purpose is to secure CE marking and maintain technical documentation under the EU Medical Device Regulation. In Vitro Diagnostics commands disproportionate laboratory capacity due to complex analytical sensitivity requirements and post-market surveillance obligations. Electromedical Equipment testing is expanding fastest as wearable diagnostics and AI-integrated monitors multiply RF emissions and software validation workloads. Remote Testing delivery modes are capturing margin pools by reducing logistics costs for distributed device portfolios.
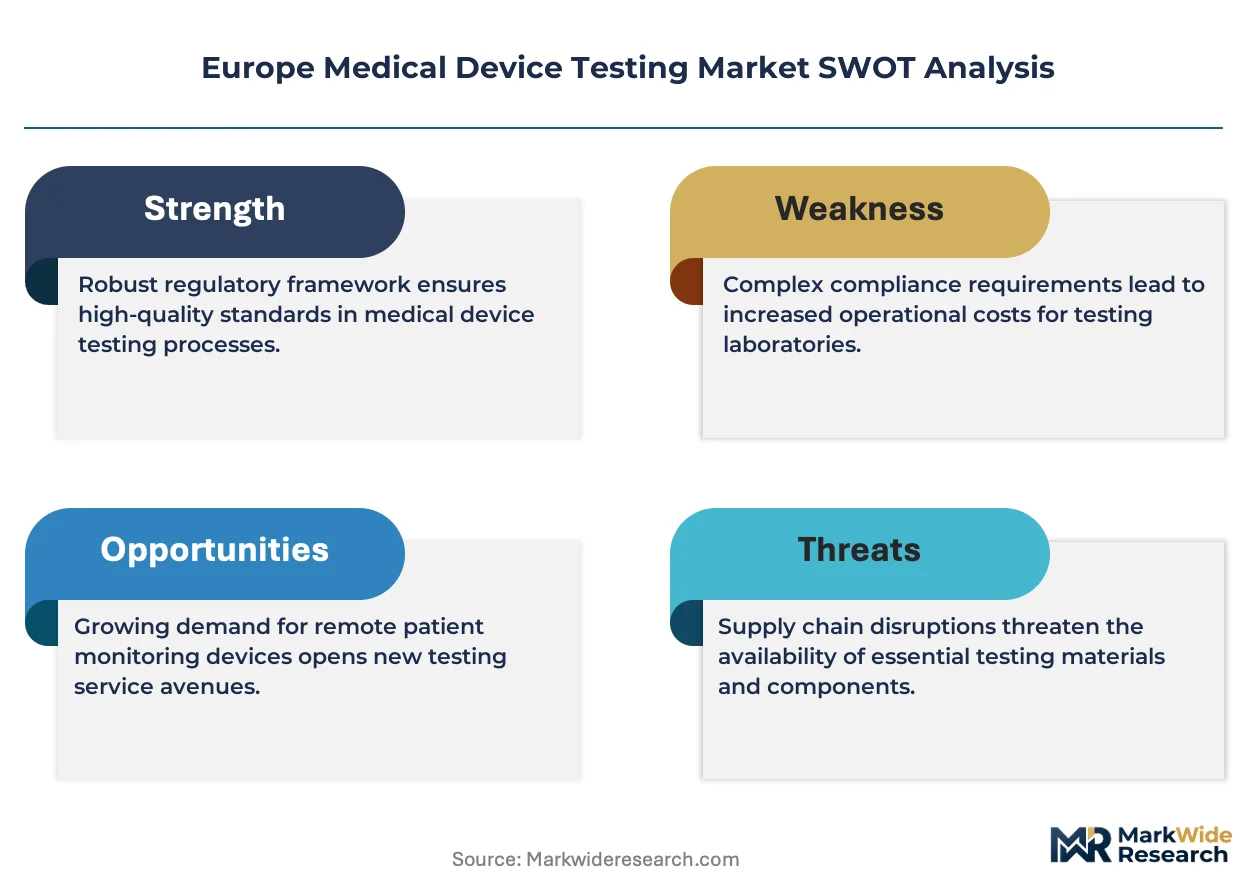
The EU Medical Device Regulation and CE marking framework, enforced by national competent authorities and EMA for borderline devices, mandate updated clinical evidence and quality management audits that lengthen testing timelines and expand scope. REACH and RoHS directives from ECHA constrain material selection for implantable devices, pushing manufacturers toward extractables and leachables screening. IEC 60601 and ISO 13485 standards shape electrical safety and quality system expectations that laboratories must embed in their accreditation scopes. Stakeholders must decide whether to build captive testing infrastructure or deepen partnerships with notified bodies before MDR transition deadlines fully close.
Market Dynamics
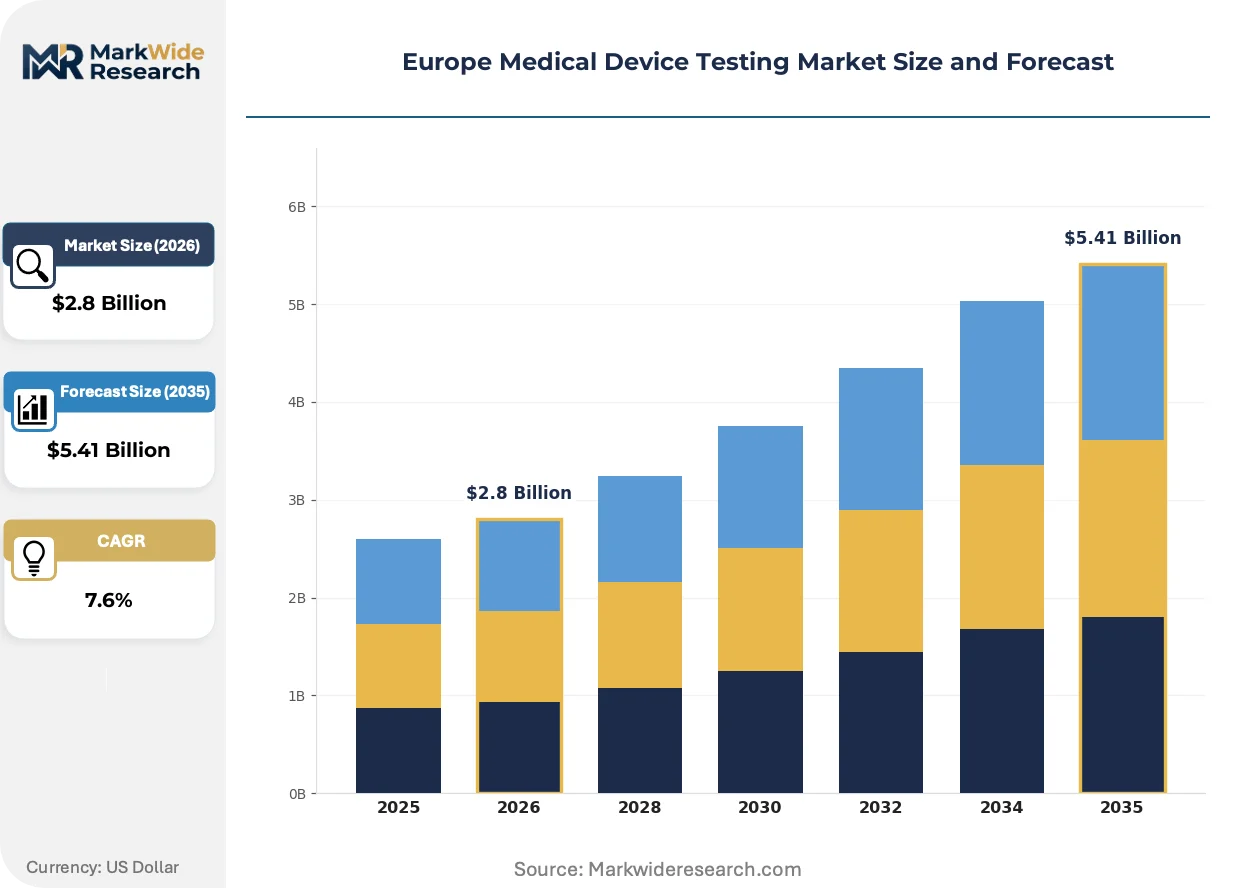
The EU Medical Device Regulation's tightened clinical evidence requirements are compressing testing timelines while simultaneously expanding protocol scope, forcing laboratories to reconfigure capacity allocation across biocompatibility, electrical safety, and software validation workstreams.
Growth Catalysts
- MDR Transition Deadlines:The EU Medical Device Regulation mandates updated technical documentation and quality management audits for legacy devices, expanding testing volumes for notified bodies and contract laboratories across Germany and the Netherlands.
- Wearable Diagnostics Proliferation:AI-integrated monitors and continuous glucose sensors multiply RF emissions testing workloads and software validation requirements for electromedical equipment categories.
- German Orthopedic Clusters:Implant manufacturers concentrated in Bavaria and Baden-Württemberg are expanding testing budgets to secure CE marking ahead of MDR certification cutoffs.
Market Restraints
- Notified Body Bottlenecks:EMA-designated conformity assessment bodies face capacity constraints, creating queue delays that extend device time-to-market for Class III active implantables.
- Biostatistician Scarcity:Universities cannot replenish pipelines fast enough to meet demand from European laboratories competing for regulatory toxicology and clinical data analysis talent.
- REACH Material Constraints:ECHA restrictions on phthalates and heavy metals in implantable devices force manufacturers toward costly extractables and leachables screening protocols.
Strategic Opportunities
- Remote Testing Infrastructure:Distributed device portfolios from mid-cap manufacturers create margin pools for laboratories offering virtual protocol review and reduced logistics cost structures.
- In Vitro Diagnostics Expansion:Complex analytical sensitivity requirements and post-market surveillance obligations for companion diagnostics command disproportionate laboratory capacity allocation.
- Switzerland-Neutral Positioning:Swissmedic alignment with MDR frameworks allows Swiss laboratories to capture overflow demand from EU manufacturers seeking alternative conformity assessment pathways.
Industry Challenges
- Accreditation Scope Expansion:ISO 17025 and ISO 13485 compliance requires capital-intensive equipment upgrades for electrical safety verification against IEC 60601-1 third edition amendments.
- Legacy System Integration:Laboratory information management systems must interface with manufacturer quality management databases while maintaining audit trail integrity for notified body review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Device Testing Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Vitro Diagnostics, Surgical Instruments, Implantable Devices, Electromedical Equipment Delivery Mode: On-site Testing, Laboratory Testing, Remote Testing, Mobile Testing End User: Hospitals, Clinics, Research Laboratories, Quality Control Centers Compliance Standard: ISO 13485, CE Marking, FDA Compliance, IEC 60601 |
| Companies Covered | TÜV SÜD, BSI, Intertek Group plc, SGS SA, Bureau Veritas, TÜV Rheinland, Element Materials Technology, Charles River Laboratories, EndoLab Mechanical Engineering GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Device Testing Market Shifts & Advancements
Computational toxicology and in silico biocompatibility modeling are compressing traditional animal study timelines while regulatory frameworks scramble to validate alternative methods for ISO 10993 compliance.
Artificial intelligence-driven predictive biocompatibility screening is supplanting conventional cytotoxicity and sensitization assays for polymer-based implants. German orthopedic manufacturers are piloting these platforms to accelerate MDR submission packages. The shift is compressing preclinical study durations from months to weeks while demanding new validation protocols from notified bodies.
REACH and RoHS directives from ECHA are tightening material composition disclosure requirements for implantable devices containing metal alloys or polymer additives. Manufacturers must now document full supply chain chemical footprints to demonstrate compliance. French and Italian laboratories are expanding extractables and leachables capacity to capture this compliance-driven testing volume.
Certification-driven procurement preferences are consolidating buyer relationships around notified bodies with established MDR track records. Mid-cap device manufacturers are abandoning fragmented multi-laboratory strategies in favor of single-source partnerships with TÜV SÜD or SGS SA networks. This concentration is most visible in Germany's Baden-Württemberg medical technology corridor, where procurement committees prioritize CE marking speed over unit cost minimization.
Europe Medical Device Testing Market Segmentation
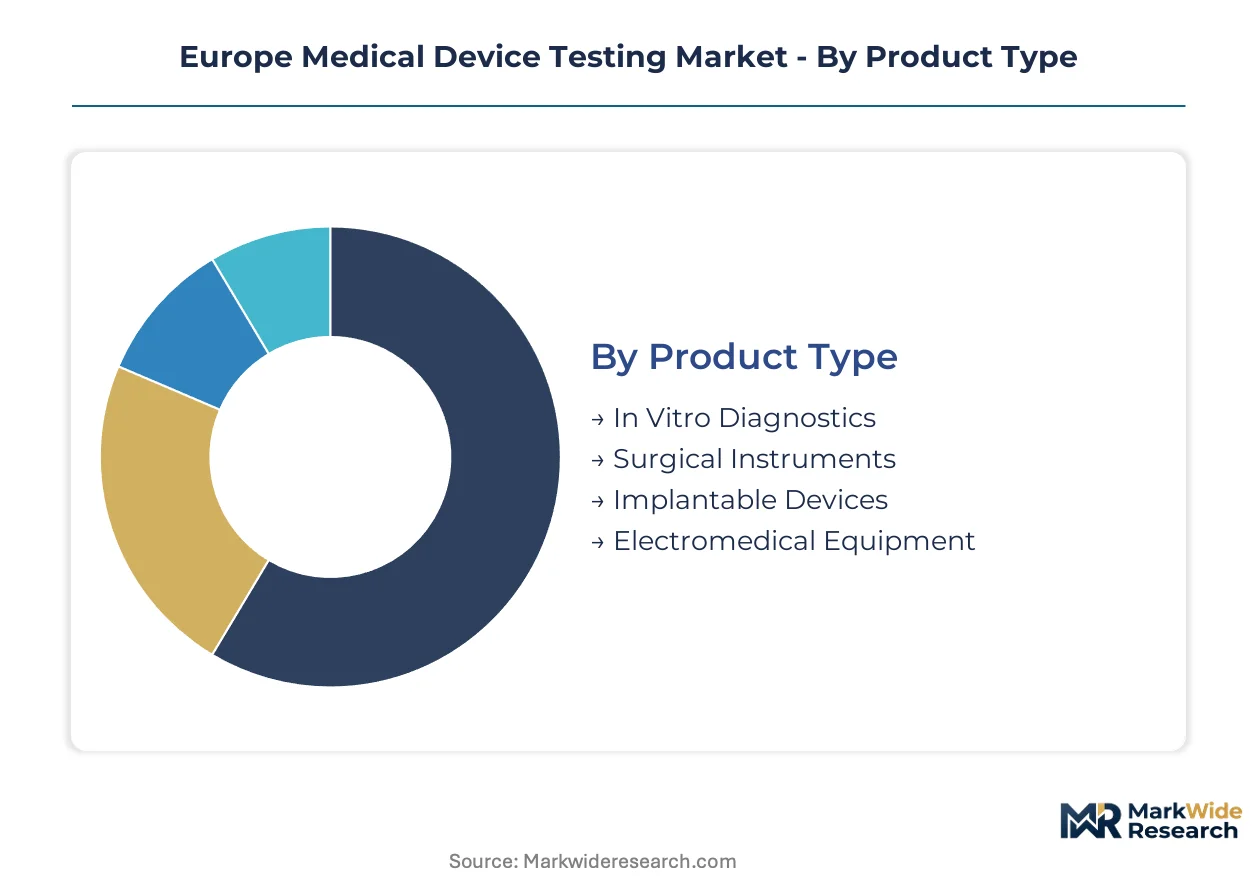
Testing demand fragments across device categories with divergent regulatory pathways. MDR transition timelines and CE marking complexity concentrate procurement decisions around specific segment combinations.
Product Type:
German and Dutch laboratories dominate export-led segments serving pan-European device manufacturers, while domestic-focused testing clusters concentrate in Switzerland and France for local implant producers.
- In Vitro Diagnostics:Analytical sensitivity validation for companion diagnostics and molecular assays demands specialized immunoassay and PCR verification infrastructure. Bavarian research laboratories and Swiss contract testing facilities absorb disproportionate capacity for post-market surveillance obligations under EMA guidelines.
- Electromedical Equipment:RF emissions testing and IEC 60601-1 third edition electrical safety verification for wearable monitors and AI-integrated devices. Baden-Württemberg manufacturers of continuous glucose sensors and cardiac monitors are expanding validation budgets fastest.
- Implantable Devices:Biocompatibility screening per ISO 10993 for orthopedic and cardiovascular implants, concentrated in German notified body networks.
- Surgical Instruments:Sterilization validation and material compliance testing against REACH directives, serving mid-volume instrument clusters in Italy and Spain.
In Vitro Diagnostics holds the largest share; momentum sits with Electromedical Equipment.
Delivery Mode:
Cost tier differentiation separates premium on-site validation from economy remote protocols, with mid-market laboratories competing on hybrid service bundles.
- Laboratory Testing:Centralized biocompatibility and electrical safety verification at ISO 17025-accredited facilities. TÜV SÜD's Munich headquarters and SGS SA's Swiss-French network anchor capacity for Class III device submissions.
- Remote Testing:Virtual protocol review and distributed sample logistics for mid-cap manufacturers with fragmented device portfolios. Reduces transport costs for Netherlands-based orthopedic suppliers serving German notified bodies.
- On-site Testing:Embedded quality engineers at manufacturer facilities for active implantable production lines, concentrated in German medical technology corridors.
- Mobile Testing:Deployable electrical safety and sterilization verification units for clinical trial sites and distributed manufacturing.
Laboratory Testing commands the revenue base; Remote Testing is gaining share fastest.
End User:
Volume concentration tracks MDR certification urgency, with notified body partnerships determining procurement priority across user categories.
- Research Laboratories:Preclinical biocompatibility and analytical validation for investigational devices. German Fraunhofer institutes and Dutch university medical centers drive early-stage testing demand.
- Quality Control Centers:Batch release testing and post-market surveillance for commercialized devices. French and Italian manufacturers maintain captive QC facilities for implantable device production.
- Hospitals:Incoming inspection and sterilization validation for reusable surgical instruments, concentrated in centralized procurement networks.
- Clinics:Point-of-care device verification and maintenance testing for electromedical equipment in distributed care settings.
Research Laboratories anchor current volume; Quality Control Centers show the steepest expansion trajectory.
Compliance Standard:
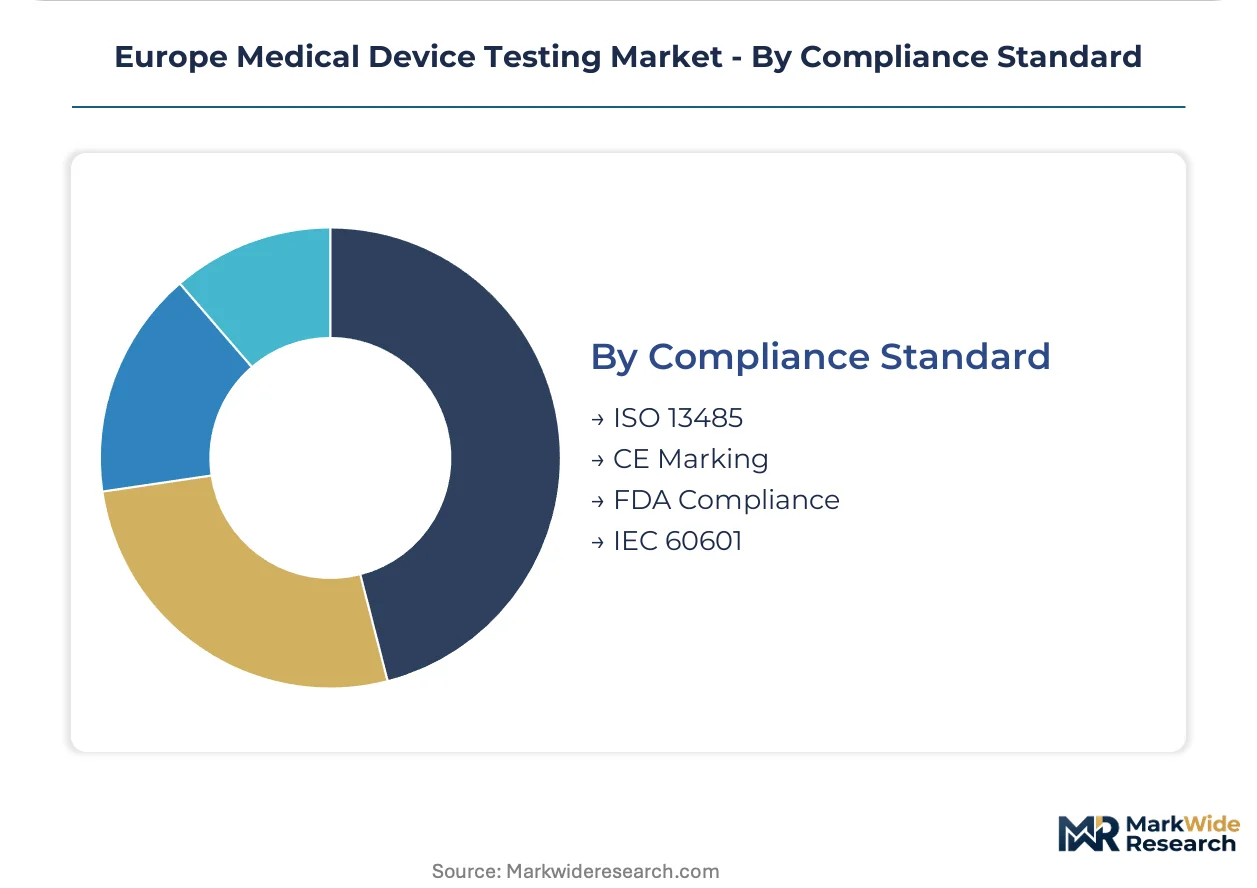
Maturity differentiation separates established CE marking pathways from emerging MDR technical documentation requirements, with accreditation scope determining laboratory competitiveness.
- CE Marking:EU MDR conformity assessment and technical documentation review for market authorization. German notified bodies face capacity bottlenecks extending queue times for Class III active implantables.
- ISO 13485:Quality management system audits embedded in manufacturer certification maintenance. Swissmedic-aligned laboratories capture overflow demand from EU manufacturers seeking alternative assessment pathways.
- IEC 60601:Electrical safety and electromagnetic compatibility verification for electromedical equipment, requiring capital-intensive test chamber investments.
- FDA Compliance:Parallel 510(k) and PMA pathway support for European manufacturers accessing US markets, concentrated in laboratories with dual accreditation scope.
CE Marking represents the dominant compliance burden; ISO 13485 audit volume is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German orthopedic clusters consume disproportionate laboratory capacity for MDR certification timelines, while Swiss and Dutch facilities capture overflow demand through alternative conformity pathways.
Germany
Bavarian implant manufacturers and Baden-Württemberg cardiac device producers drive concentrated demand for biocompatibility and electrical safety validation. EMA-designated notified bodies face capacity constraints extending queue times for Class III active implantables. Munich anchors TÜV SÜD's dominance in MDR conformity assessment backlogs.
Switzerland
Swissmedic alignment with EU MDR frameworks positions Swiss laboratories as alternative assessment destinations for manufacturers bypassing German bottlenecks. REACH and RoHS compliance screening for metal alloys and polymer additives expands extractables capacity in Basel-Zurich corridor laboratories.
Netherlands
Dutch orthopedic suppliers serving German notified bodies leverage remote testing infrastructure to reduce logistics costs for distributed device portfolios. EMA guidelines for companion diagnostics post-market surveillance concentrate immunoassay verification demand in Utrecht-Leiden research clusters.
France
French laboratories expand extractables and leachables screening capacity to capture REACH-driven compliance volume from implantable device manufacturers. ANSM oversight of borderline devices creates specialized validation pathways for software-integrated diagnostics in Paris-Saclay research corridor.
United Kingdom
Post-Brexit regulatory divergence pressures UK laboratories to maintain dual CE marking and UKCA compliance capabilities. MHRA transitional arrangements for legacy devices sustain testing demand in Cambridge-Oxford medical technology corridor despite reduced EU market access.
Europe Medical Device Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with notified bodies commanding premium positioning through MDR accreditation scarcity. Three archetypes populate the landscape: full-service conformity assessment organizations with pan-European laboratory networks; specialized biocompatibility and toxicology contract research organizations; and captive testing divisions of major device manufacturers. Competitive moves concentrate on capacity expansion for electrical safety verification and strategic partnerships to secure notified body designation.
Within the integrated leader tier, TÜV SÜD and SGS SA exemplify archetypes of scale-driven conformity assessment dominance. TÜV SÜD occupies a position representing German-engineered regulatory depth through Munich-headquartered MDR certification authority. SGS SA anchors Swiss-neutral positioning with expanded biocompatibility screening capacity across Switzerland and France. Bureau Veritas sits within the aggressive turnaround-time competitive vector for active implantable electrical safety testing.
| Leading Market Players |
|---|
| TÜV SÜD |
| BSI |
| Intertek Group plc |
| SGS SA |
| Bureau Veritas |
| TÜV Rheinland |
| Element Materials Technology |
| Charles River Laboratories |
| EndoLab Mechanical Engineering GmbH |
| Others |
Supply & Pricing Matrix
Alternative biocompatibility screening methods displacing traditional animal studies simultaneously redraw laboratory capacity geography across the German-Swiss corridor and compress pricing premiums for ISO 10993 validation services. REACH-driven extractables testing for implantable devices concentrates procurement decisions around laboratories with ECHA-compliant chemical disclosure infrastructure, tightening margins for mid-tier competitors lacking accredited capacity.
Pricing Analysis
Long-term service contracts dominate procurement relationships between orthopedic manufacturers and notified bodies, with TÜV SÜD and SGS SA locking in multi-year MDR conformity assessment agreements that insulate premium pricing tiers. Certification grade and turnaround speed differentiate pricing bands, with Class III active implantable submissions commanding substantial premiums over Class IIa surgical instruments. Pricing pressure stems from notified body capacity bottlenecks extending queue times and forcing manufacturers toward Swissmedic-aligned alternatives. Mid-cap device producers exhibit highest price sensitivity, while German orthopedic clusters prioritize CE marking velocity over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor European medical device testing capacity, with Bavarian laboratories producing biocompatibility validation services and Basel-Zurich corridor facilities specializing in extractables and leachables screening. Raw material dependencies center on reference standards for ISO 10993 cytotoxicity assays, IEC 60601 electrical safety test equipment, and specialized reagents for immunoassay verification. Single-source vulnerability concentrates around EMA-designated notified bodies facing MDR transition backlogs. Distribution runs through embedded quality engineer deployments at manufacturer facilities and centralized ISO 17025-accredited laboratory networks serving pan-European device portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in remote testing infrastructure and AI-integrated biocompatibility modeling, as MDR deadline compression and wearable diagnostics proliferation fragment demand across specialized validation niches.
For Market Incumbents: Shield market position through captive capacity expansion in Swissmedic-aligned jurisdictions and accelerated accreditation scope for IEC 60601-1 third edition electrical safety verification. Vertical integration into computational toxicology platforms addresses emerging substitute threats from in silico biocompatibility screening. Deepen notified body partnerships with Baden-Württemberg cardiac device manufacturers before MDR transition deadlines fully close. For New Entrants and Emerging Players: Differentiate on remote testing delivery models targeting Netherlands-based orthopedic suppliers with distributed device portfolios and fragmented logistics needs. White-space opportunity sits with mid-cap electromedical equipment manufacturers seeking alternative conformity assessment pathways outside German bottleneck queues. Go-to-market leverage centers on virtual protocol review capabilities reducing transport costs and compressing validation timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract research organizations possessing ISO 17025 accreditation and established EMA relationships but lacking MDR transition readiness. Long-term viability over a five-to-ten-year horizon hinges on notified body designation scarcity and consolidation-resistant specialized testing niches. Signal to monitor: Swissmedic-EU MDR alignment durability and overflow demand sustainability from German capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR conformity assessment backlog at TÜV SÜD Munich headquarters commands premium positioning. |
| Biocompatibility Platform Investment | AI-driven predictive screening compresses ISO 10993 study timelines for German orthopedic manufacturers. |
| Swiss Laboratory Expansion | Swissmedic alignment captures overflow demand from EU manufacturers bypassing German notified body queues. |
| Remote Testing Infrastructure | Virtual protocol review reduces logistics costs for Netherlands-based suppliers serving German clusters. |
| Extractables Capacity Buildout | REACH compliance screening for metal alloys and polymer additives anchors French and Italian laboratory growth. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory directors at notified bodies, regulatory affairs managers at orthopedic and cardiac device manufacturers, biomedical engineers at German Fraunhofer institutes, and procurement leads at hospital GPOs. Secondary validation drew from EMA MDR guidance documents, Swissmedic conformity assessment bulletins, ISO 10993 and IEC 60601 standard revisions, and customs data on medical device testing equipment imports. Bottom-up capacity estimates at individual laboratory facilities were triangulated against top-down market sizing derived from notified body revenue disclosures and manufacturer R&D expenditure patterns.
Across the analysis window, forecasts were constructed through segmentation modeling across device category, delivery mode, end-user institution type, and compliance standard tier. CAGRs were derived from regression analysis of historical testing volume trends against MDR transition timeline milestones and wearable diagnostics adoption curves. Industry-specific inputs incorporated biocompatibility study duration compression rates from computational toxicology adoption and electrical safety verification workload expansion from AI-integrated monitor proliferation.
Material uncertainties — regulatory timeline revisions, notified body designation withdrawals, and alternative method validation delays — sit outside the modeled envelope. Forecasts reflect assumptions about MDR enforcement consistency and Swissmedic-EU alignment durability. Recalibration cycles align with material shifts in EMA guidance publication and REACH restriction expansion schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Addison Disease Testing Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Syphilis Testing Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Nipah Virus Testing Market
Testing Services
Arbovirus Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Over-The-Counter Tests Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
Lab Screening Test Kit Market
Testing Services
IVD Quality Control Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market