
 US Acoustic Sensors Market | 2026-2036
US Acoustic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
US Acoustic Sensors Market Analytics
Market Context
Domestic MEMS foundry capacity is broadening across Arizona and New Mexico fabs, lowering lead times for precision acoustic components. Honeywell International leverages its aerospace heritage to anchor defense-grade sensor supply chains. Microchip Technology sustains R&D intensity in ultrasonic signal processing architectures. Siemens AG competes through industrial automation channel control, embedding acoustic diagnostics into predictive maintenance platforms.
Technical Definition and Segment Structure
Acoustic sensors are transducers that convert mechanical sound waves into electrical signals, typically operating across frequency ranges from infrasonic (<20 Hz) to ultrasonic (>20 kHz) with sensitivity thresholds measured in millivolts per pascal. These devices serve industrial, medical, and military applications requiring non-contact measurement, structural health monitoring, or environmental sound detection. Ultrasonic sensors and MEMS-based microphones capture expanding margin pools as miniaturization drives adoption in wearable diagnostics and autonomous systems. Industrial automation and underwater communication applications lead volume absorption, while smart home systems represent the fastest-growing demand vector as voice-interface penetration deepens.
Regulatory Environment
FAA certification requirements govern acoustic emission sensors deployed in aircraft structural monitoring, mandating traceable calibration protocols. FDA Class II device pathways regulate diagnostic ultrasound transducers, constraining market entry to validated manufacturing processes. NHTSA crash-safety standards drive automotive cabin noise sensor integration, compelling tier-one suppliers to maintain ISO 26262 functional safety compliance. Stakeholders must monitor evolving DoD microelectronics security standards and state-level data privacy frameworks affecting voice-capture deployments in connected environments.
Market Dynamics
Defense procurement expansion for perimeter security and underwater surveillance is compressing supplier qualification timelines while elevating performance thresholds for acoustic sensor manufacturers serving federal contracts.
Growth Catalysts
- DoD Trusted Foundry Program:Secure domestic fabrication mandates are channeling defense acoustic sensor contracts toward qualified US semiconductor facilities, insulating qualified suppliers from offshore competition.
- MEMS miniaturization:Shrinking form factors for ultrasonic transducers are unlocking wearable diagnostic applications previously inaccessible to conventional piezoelectric architectures.
- California sensor cluster concentration:Silicon Valley's dense ecosystem of MEMS design houses and precision foundries accelerates prototype-to-production cycles for next-generation acoustic devices.
Market Restraints
- Specialized substrate scarcity:Limited domestic supply of lithium niobate and PZT ceramics constrains piezoelectric sensor output and inflates input costs for high-sensitivity applications.
- FDA Class II pathway friction:Diagnostic ultrasound transducer approvals require extensive clinical validation, extending time-to-revenue for medical device entrants by multiple years.
- Optical sensing substitution:Fiber-optic acoustic emission sensors are displacing electrical transducers in high-EMI environments, eroding share in industrial monitoring segments.
Strategic Opportunities
- Texas defense corridor expansion:Austin-San Antonio metroplex is attracting acoustic sensor R&D facilities seeking proximity to Army Futures Command and Space Force installations.
- AI-driven predictive maintenance:Machine learning integration with industrial acoustic diagnostics creates recurring software revenue streams atop hardware sensor sales.
- IRA clean energy incentives:Tax credits for domestic manufacturing equipment are lowering capital barriers for US-based MEMS foundry expansion.
Industry Challenges
- ISO 26262 functional safety certification:Automotive cabin noise sensor suppliers face 18-24 month validation cycles to meet NHTSA-linked safety standards.
- Phased-array integration complexity:Legacy industrial monitoring systems require extensive retrofit engineering to accommodate beam-steering ultrasonic architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Acoustic Sensors Market |
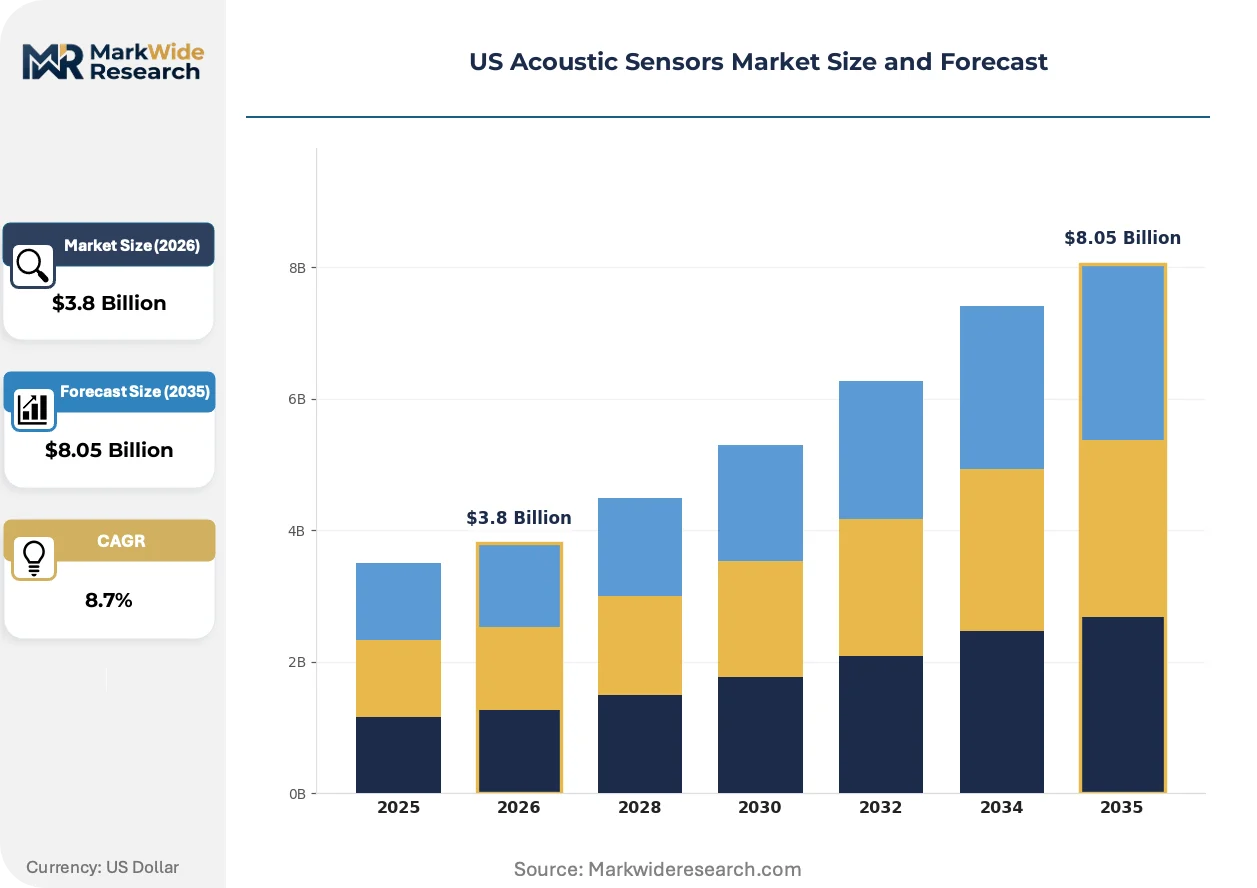
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphones, Hydrophones, Ultrasonic Sensors, Piezoelectric Sensors Application: Noise Monitoring, Industrial Automation, Underwater Communication, Smart Home Systems Technology: Analog, Digital, MEMS, Wireless End User: Healthcare, Automotive, Defense, Consumer Electronics |
| Companies Covered | Microchip Technology, Transense Technologies plc, Honeywell International, Dytran Instruments, Inc., ifm efector, inc., Siemens AG, Broadcom Inc., Campbell Scientific, Inc., Murata Manufacturing Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Acoustic Sensors Market Evolving Landscape
Acoustic sensor architectures are converging with edge computing and artificial intelligence, transforming standalone transducers into intelligent diagnostic nodes capable of autonomous signal interpretation.
MEMS-based ultrasonic transducers are unifying multiple sensing modalities into single-chip platforms, combining time-of-flight measurement with Doppler shift detection for fluid dynamics characterization. Automotive tier-one suppliers are adopting these unified sensors for fuel tank level monitoring and cabin occupancy detection. This convergence is unifying previously separate component supply chains, pressuring discrete piezoelectric manufacturers to diversify or exit mainstream industrial applications.
FAA's updated airworthiness directive on structural health monitoring mandates traceable calibration protocols for acoustic emission sensors installed in commercial aircraft fuselage and wing assemblies. Manufacturers must maintain NIST-traceable standards and document drift characteristics across operational temperature ranges. Aerospace sensor suppliers in Wichita and Seattle are responding by integrating self-calibration firmware that automates compliance documentation.
Defense prime contractors are consolidating acoustic sensor procurement under long-term performance-based agreements, shifting risk from government buyers to suppliers for field reliability and maintenance costs. This contractual evolution is displacing traditional unit-price purchasing in Navy underwater surveillance programs. The shift is most visible in the Virginia-class submarine supply chain, where sensor vendors now guarantee mean-time-between-failure rates rather than delivering discrete hardware lots.
US Acoustic Sensors Market Segmentation
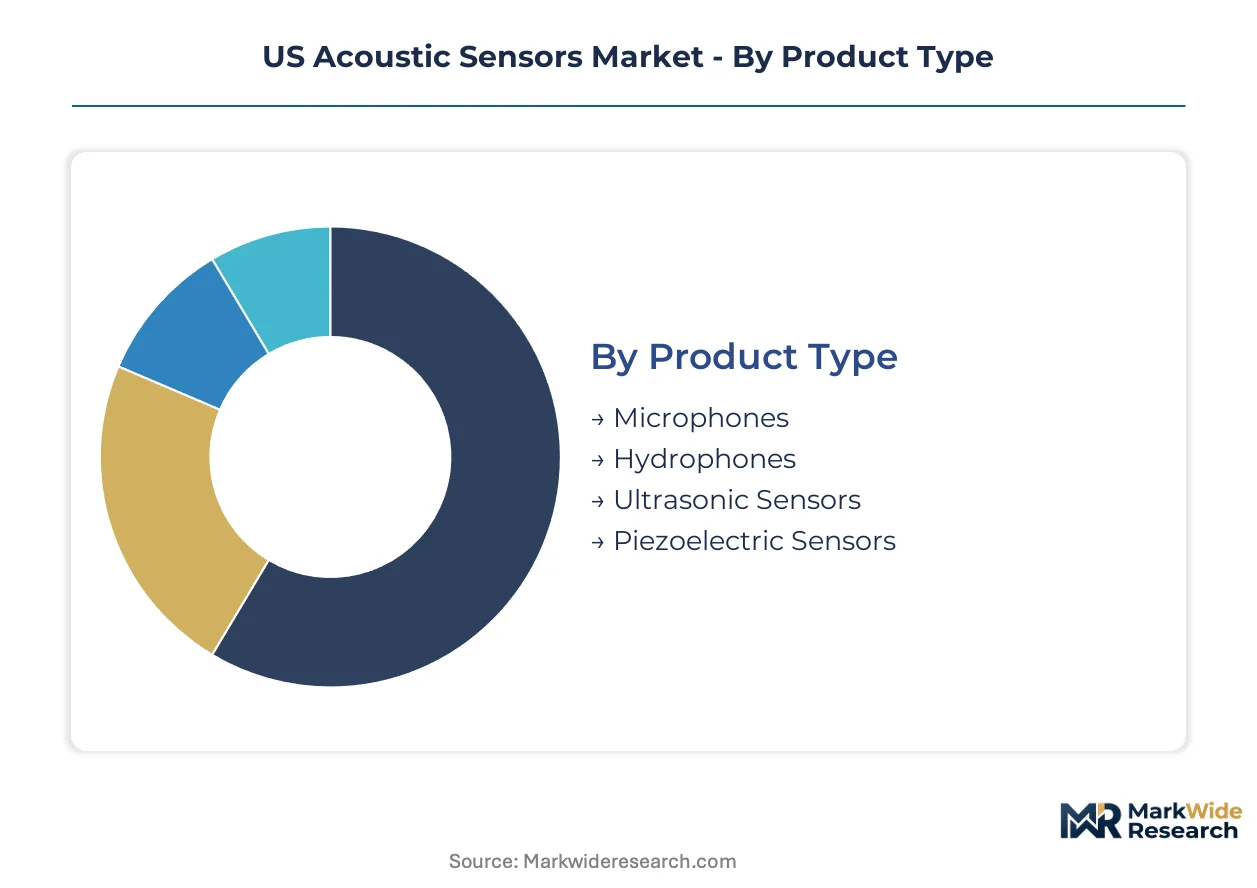
Acoustic sensor buyers exhibit sharply divergent technical requirements across defense, medical, and consumer verticals, necessitating purpose-built architectures rather than adaptable general-purpose platforms. Segmentation reveals how procurement patterns cluster around performance thresholds, regulatory pathways, and integration complexity rather than unit economics alone.
Product Type:
Cost tier differentiation separates commodity audio capture from precision measurement applications requiring calibrated sensitivity and environmental hardening.
- Microphones:MEMS-based silicon microphones dominate consumer electronics and voice-interface deployments with surface-mount packaging enabling automated assembly. Demand concentrates in California's Silicon Valley sensor cluster where fabless design houses prototype next-generation beamforming arrays for smart speaker OEMs. FDA Class II pathway requirements for diagnostic stethoscope applications constrain medical-grade entrants to validated manufacturing processes.
- Ultrasonic Sensors:Time-of-flight and Doppler architectures enable non-contact distance measurement and fluid dynamics characterization with operating frequencies typically spanning 40 kHz to 400 kHz. Automotive tier-one suppliers in Michigan and Ohio integrate these devices for parking assistance and cabin occupancy detection where NHTSA crash-safety standards mandate ISO 26262 functional safety compliance. MEMS miniaturization is unlocking wearable diagnostic applications previously inaccessible to conventional piezoelectric form factors.
- Hydrophones:Piezoelectric ceramic transducers optimized for underwater pressure wave detection serve Navy surveillance programs and offshore energy exploration. Texas defense corridor facilities anchor domestic production for Virginia-class submarine sensor suites.
- Piezoelectric Sensors:Ceramic and crystal-based transducers deliver high-sensitivity acoustic emission monitoring for structural health diagnostics in aerospace and civil infrastructure applications.
Volume sits with Microphones; growth tilts toward Ultrasonic Sensors.
Application:
Customer integration maturity determines whether acoustic sensors deploy as standalone instruments or embedded subsystems within larger platform architectures.
- Industrial Automation:Predictive maintenance platforms embed acoustic diagnostics for bearing fault detection and pump cavitation monitoring, with machine learning integration creating recurring software revenue streams atop hardware sales. Siemens AG competes through channel control, bundling sensors with industrial automation software in manufacturing hubs across Ohio and Illinois. Phased-array integration complexity forces extensive retrofit engineering for legacy monitoring system upgrades.
- Smart Home Systems:Voice-interface penetration drives demand for far-field microphone arrays and acoustic event detection in security and environmental monitoring devices. Amazon and Google hardware ecosystems in Seattle and Mountain View anchor design specifications for low-power, always-on audio processing. This segment is expanding most quickly as ambient computing architectures proliferate through residential and commercial building automation.
- Noise Monitoring:Environmental compliance and occupational safety applications require calibrated sound level measurement with NIST-traceable certification for EPA and OSHA reporting.
- Underwater Communication:Defense and scientific research programs deploy acoustic modems for subsea data transmission where radio frequency propagation fails.
Revenue concentrates in Industrial Automation; share gains accrue fastest to Smart Home Systems.
Technology:
Signal processing architecture selection hinges on power budget, latency tolerance, and electromagnetic interference exposure at the deployment site.
- MEMS:Micro-electromechanical systems integrate mechanical sensing elements with CMOS electronics on silicon substrates, enabling batch fabrication at semiconductor foundries. Domestic MEMS foundry capacity in Arizona and New Mexico is broadening, lowering lead times for precision acoustic components serving defense and medical device manufacturers. DoD Trusted Foundry Program mandates channel contracts toward qualified US semiconductor facilities.
- Digital:Integrated analog-to-digital conversion and preprocessing reduce host processor burden for complex multi-sensor arrays in automotive and industrial applications.
- Analog:Raw voltage output transducers persist in high-fidelity audio and specialized measurement equipment where signal chain customization outweighs integration convenience.
- Wireless:Battery-powered acoustic nodes with embedded radio frequency communication enable distributed sensing networks without cabling infrastructure.
Shipment volume favors MEMS; technology investment flows toward Digital.
End User:
Procurement authority structures separate centralized defense acquisition from fragmented commercial purchasing with divergent qualification timelines.
- Defense:DoD procurement programs for perimeter security and underwater surveillance compress supplier qualification timelines while elevating performance thresholds. Honeywell International leverages aerospace heritage to anchor defense-grade sensor supply chains with long-term performance-based agreements replacing unit-price purchasing. Army Futures Command and Space Force installations in the Austin-San Antonio metroplex are attracting acoustic sensor R&D facilities seeking program proximity.
- Healthcare:Diagnostic ultrasound transducer and implantable hearing device applications require FDA Class II device pathway compliance with extensive clinical validation extending time-to-revenue by multiple years.
- Automotive:Cabin noise monitoring and advanced driver assistance systems drive integration of acoustic sensors with functional safety certification under NHTSA-linked standards.
- Consumer Electronics:High-volume, short-lifecycle product ramps demand rapid prototype-to-production cycles served by California's dense ecosystem of MEMS design houses.
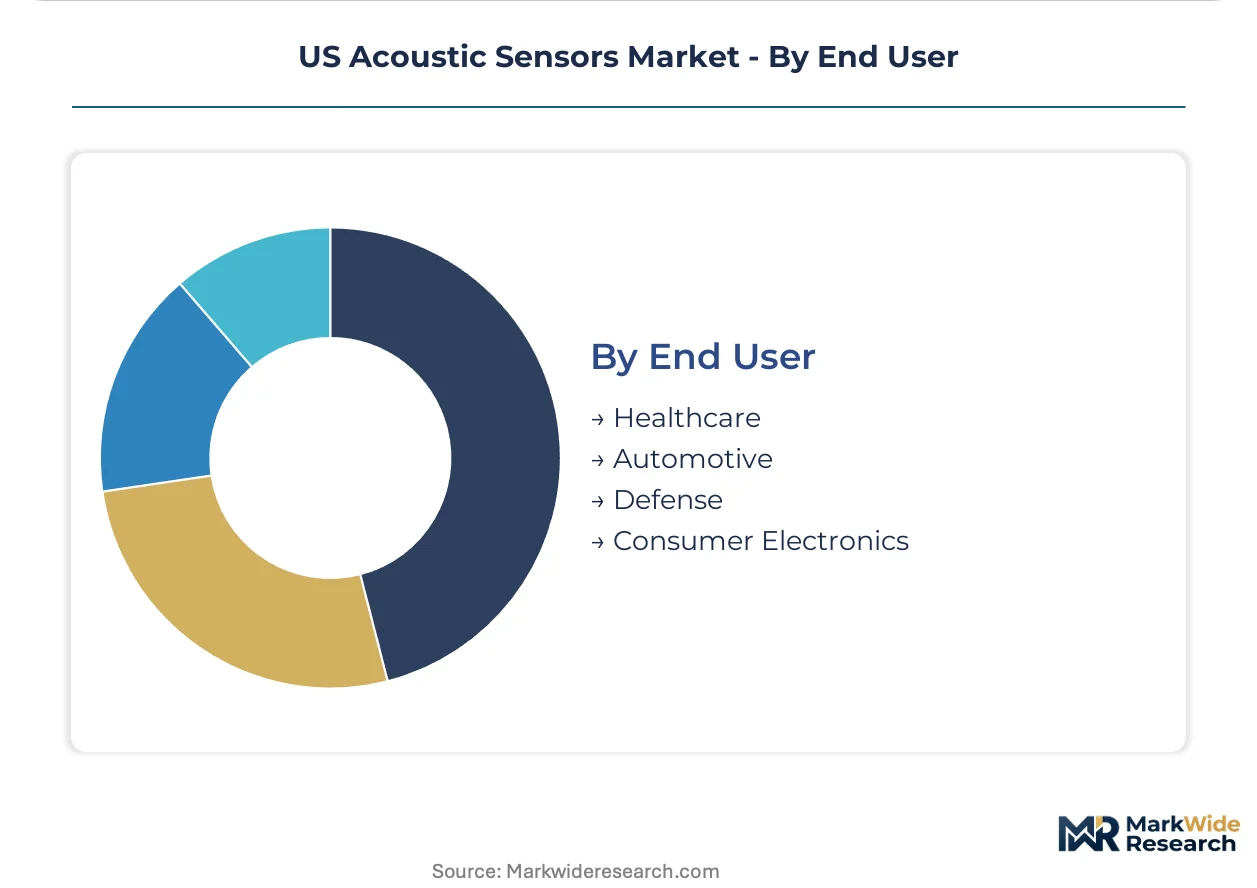
Contract value aggregates in Defense; volume scales through Consumer Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium niobate and PZT ceramic feedstock availability concentrates domestic sensor manufacturing capacity in southwestern fabrication corridors. Defense procurement programs and medical device qualification pathways reshape regional supplier distribution across distinct state-level industrial clusters.
California
Silicon Valley's dense ecosystem of MEMS design houses and precision foundries accelerates prototype-to-production cycles for next-generation acoustic devices. FDA Class II device pathways regulate diagnostic ultrasound transducer manufacturing in San Diego medical device corridors. Fabless sensor startups cluster around Stanford and Berkeley research partnerships, feeding contract flows to Arizona and New Mexico foundry partners.
Texas
The Austin-San Antonio metroplex attracts acoustic sensor R&D facilities seeking proximity to Army Futures Command and Space Force installations. DoD Trusted Foundry Program mandates channel defense contracts toward qualified semiconductor facilities in the Dallas-Fort Worth corridor. Honeywell International anchors defense-grade supply chains through long-term performance-based agreements with Navy underwater surveillance programs.
Arizona
Domestic MEMS foundry capacity expansion in Phoenix-Tucson fabs lowers lead times for precision acoustic components serving defense and medical device manufacturers. IRA clean energy tax credits reduce capital barriers for manufacturing equipment upgrades in semiconductor fabrication facilities. The state's microelectronics cluster feeds substrate supply chains for piezoelectric sensor production.
Massachusetts
Greater Boston's acoustic emission monitoring specialists serve FAA-certified aerospace structural health applications in Wichita and Seattle supply chains. MIT and Harvard research partnerships drive ultrasonic signal processing architecture development for industrial automation integration. NIST-traceable calibration protocol expertise concentrates in national laboratory partnerships throughout the Northeast Corridor.
Michigan
Automotive tier-one suppliers integrate acoustic sensors for cabin noise monitoring and advanced driver assistance systems under NHTSA-linked ISO 26262 functional safety standards. Detroit-area engineering centers prototype MEMS-based ultrasonic transducers for fuel tank level monitoring and occupancy detection. The state's industrial automation heritage supports predictive maintenance platform integration with acoustic diagnostics.
US Acoustic Sensors Market Competitive Landscape
Global majors compete with regional champions across defense qualification timelines and medical device certification pathways. The vendor base separates into three tiers: aerospace-defense conglomerates with Trusted Foundry access, industrial automation specialists with channel control, and fabless MEMS design houses with rapid prototyping capabilities. Dominant competitive moves include strategic partnerships with domestic foundry operators and portfolio diversification into AI-driven predictive maintenance software layers.
Within the defense-aerospace tier, Honeywell International and Microchip Technology exemplify suppliers leveraging long-term performance-based agreements to displace unit-price purchasing in federal procurement. Siemens AG occupies a position among industrial automation integrators bundling acoustic diagnostics with manufacturing software platforms. Murata Manufacturing Co., Ltd. represents the precision component archetype, supplying substrate-level transducer elements to downstream system integrators across multiple end-use verticals.
| Leading Market Players |
|---|
| Microchip Technology |
| Transense Technologies plc |
| Honeywell International |
| Dytran Instruments, Inc. |
| ifm efector, inc. |
| Siemens AG |
| Broadcom Inc. |
| Campbell Scientific, Inc. |
| Murata Manufacturing Co., Ltd. |
| Others |
Value Network & Pricing Analysis
MEMS fabrication specialists in Arizona and New Mexico fabs command wage premiums that compress margins on standard-grade acoustic components while sustaining pricing power in defense-qualified tiers. Labor-cost differentials between these southwestern foundry corridors and California design houses propagate three-tier spreads across procurement contracts.
Pricing Analysis
Warranty and field-service bundling separate defense-grade hydrophone suppliers from commodity microphone vendors, with performance-based maintenance agreements now standard in Navy underwater surveillance programs. Three-tier pricing structure across premium, standard, and economy levels reflects FDA Class II certification status, DoD Trusted Foundry qualification, and volume scale. Cost compression in standard-grade MEMS microphones intensifies because Arizona foundry capacity expansion outpaces design house differentiation. Automotive tier-one suppliers exhibit least price sensitivity due to ISO 26262 functional safety liability exposure, while consumer electronics OEMs drive hardest unit-cost negotiations.
Supply Chain Analysis
Workforce availability for precision lithography and piezoelectric ceramic processing concentrates manufacturing gravity in Arizona, New Mexico, and Texas corridors. Domestic supply chains draw from lithium niobate substrate suppliers, PZT ceramic foundries, and CMOS wafer fabrication facilities. Single-source vulnerability persists for high-purity piezoelectric ceramics lacking qualified secondary vendors. Distribution runs through defense prime contractor procurement offices, industrial automation system integrators, and medical device OEM supply chain managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where lithium niobate and PZT ceramic scarcity props pricing across high-sensitivity sensor tiers.
For Market Incumbents: Deploy Trusted Foundry qualification as a competitive moat by accelerating certification timelines for Arizona and New Mexico fab expansions. Secure long-term offtake agreements with domestic piezoelectric ceramic suppliers before capacity constraints harden. Optical sensing substitution in industrial monitoring segments threatens electrical transducer margins; counter through AI-driven predictive maintenance software bundling. For New Entrants and Emerging Players: Mid-tier automotive suppliers underserved by established MEMS vendors present viable entry points for ultrasonic cabin occupancy sensors lacking ISO 26262 legacy certification burdens. Texas defense corridor R&D facilities seeking proximity to Army Futures Command offer geographic white space absent incumbent facility density. Pursue foundry partnership models rather than capital-intensive fab construction. For Investors and Strategic Acquirers: Re-rating potential sits with fabless MEMS design houses possessing FDA Class II pathway expertise given diagnostic ultrasound transducer approval backlogs extending commercialization timelines for competitors. Long-term viability favors suppliers with dual-use defense-medical certification capabilities. Watch Virginia-class submarine sensor procurement contract awards as inflection indicator for performance-based agreement adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Foundry Qualification Acceleration | DoD procurement mandates channel defense contracts toward qualified domestic semiconductor facilities. |
| AI-Driven Predictive Maintenance Platform Launch | Siemens AG and industrial automation integrators bundle acoustic diagnostics with recurring software revenue streams. |
| MEMS Foundry Capacity Expansion | IRA clean energy tax credits lower capital barriers for Arizona and New Mexico fabrication facility upgrades. |
| FDA Class II Pathway Investment | Diagnostic ultrasound transducer approvals require validated manufacturing processes extending time-to-revenue. |
| Texas Defense Corridor R&D Facility Establishment | Army Futures Command and Space Force installations attract acoustic sensor development proximity. |
Research Methodology
Multi-period observation of MEMS foundry utilization rates, defense procurement contract awards, and FDA Class II approval timelines anchored the trend analysis, supplemented by interviews with acoustic sensor design engineers, defense procurement officers, medical device regulatory affairs specialists, and industrial automation system integrators. Secondary validation drew from DoD Trusted Foundry Program announcements, FAA airworthiness directives, NHTSA functional safety guidance, SEC filings of listed sensor manufacturers, and foundry capacity expansion disclosures. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across product type, application, technology, and end-user dimensions structured the analytical framework over the projection horizon. Modeled dimensions included MEMS versus piezoelectric architectures, defense versus medical versus automotive versus consumer electronics verticals, and domestic versus import supply sourcing. CAGRs derived from regression analysis of historical procurement patterns and capacity expansion pipelines. Industry-specific forecast inputs incorporated Virginia-class submarine sensor suite deployment schedules and IRA clean energy tax credit qualification timelines.
Revisions become necessary when lithium niobate or PZT ceramic supply disruptions materialize, DoD procurement priorities shift toward optical sensing alternatives, or FDA Class II pathway timelines extend beyond historical baselines. Forecasts reflect assumptions regarding sustained defense spending authorization and continued MEMS miniaturization feasibility. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Vibration Sensor Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
Smart Haptic Devices Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Global Wireless Sensors Network Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Ozone Meter Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market