
 Oxycodone Market | 2026-2036
Oxycodone Market Size, Share, and Industry Trends Forecast 2026-2036
Oxycodone Market Outlook
Hospital procurement is consolidating under larger integrated delivery networks and group purchasing organizations, concentrating buying power among fewer decision-makers. Teva Pharmaceutical Industries leverages its generic manufacturing scale to compete on cost across immediate-release and extended-release portfolios. Mallinckrodt Pharmaceuticals anchors its position through specialized controlled-substance distribution infrastructure that satisfies Drug Enforcement Administration track-and-trace mandates. Collegium Pharmaceutical differentiates via abuse-deterrent formulation technology that addresses prescriber liability concerns.
Oxycodone is a semisynthetic opioid analgesic derived from thebaine, classified as a Schedule II controlled substance with potency approximately 1.5 times that of oral morphine, and it functions primarily as a mu-opioid receptor agonist for moderate-to-severe pain management in clinical and post-surgical settings. Extended-release formulations command margin premiums due to manufacturing complexity and patent-protected delivery mechanisms, while immediate-release tablets face commoditization from generic competition. Pain management centers represent a concentrated demand node where reimbursement policies and state-level prescription monitoring programs direct volume toward compliant, auditable supply chains.
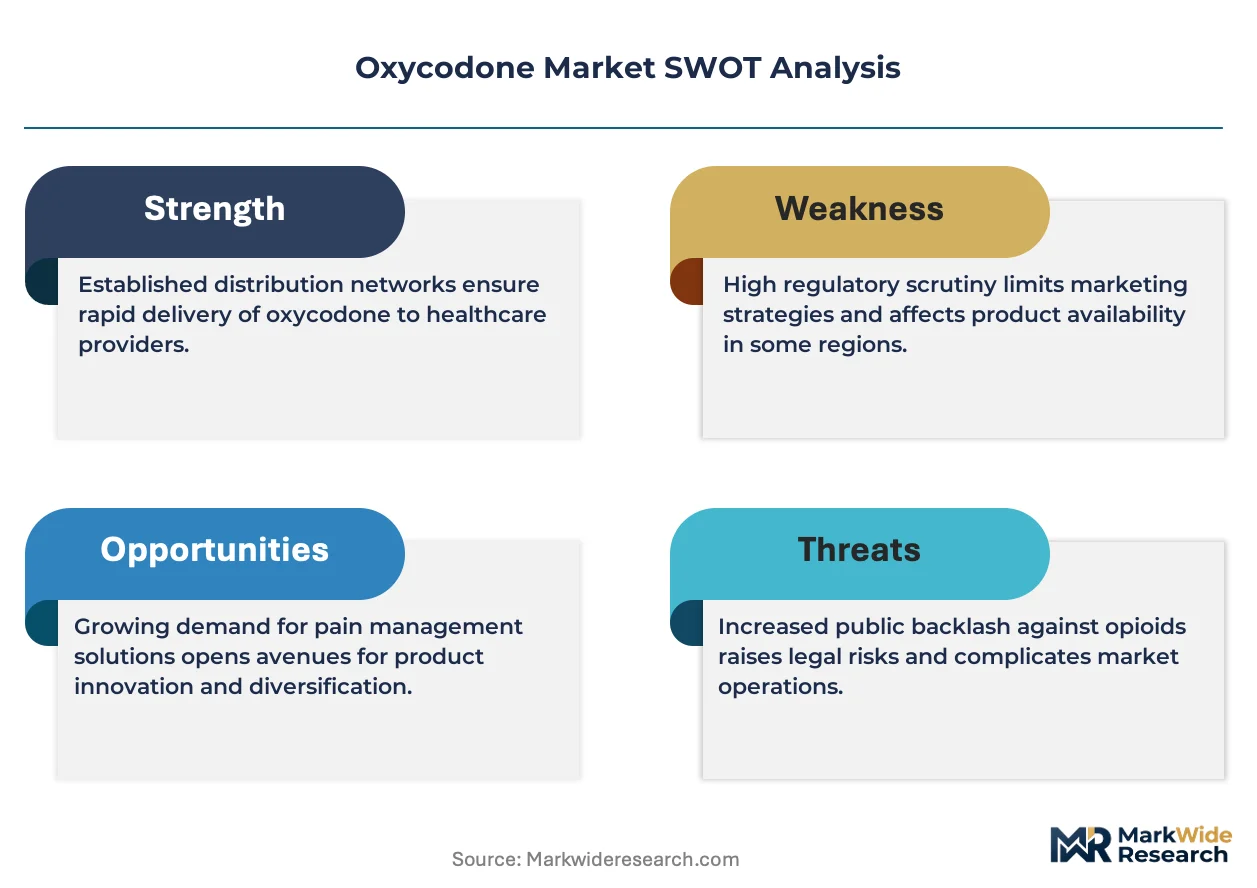
The FDA's REMS program for extended-release and long-acting opioids mandates prescriber training and patient counseling, directly constraining market access and shaping product-launch requirements. The DEA's aggregate production quota system for Schedule II substances controls total domestic manufacturing volume, creating supply planning rigidity for manufacturers. State-level prescription drug monitoring programs, administered by boards of pharmacy across all fifty states, generate real-time data that influences prescriber behavior and detects diversion patterns. Stakeholders must monitor evolving litigation settlements and their structural impact on distribution channel economics and manufacturer liability exposure.
Market Dynamics
Hospital procurement consolidation under integrated delivery networks concentrates buying power while the FDA's REMS program for opioid analgesics tightens prescribing protocols and distribution controls.
Growth Catalysts
- Palliative care expansion:Medicare hospice benefit growth drives sustained demand for extended-release formulations in terminal pain management across United States health systems.
- REMS prescriber certification:Mandatory FDA training programs create compliant prescriber pools that stabilize legitimate prescription volumes for approved indications.
- Abuse-deterrent formulation patents:Proprietary delivery mechanisms protect margin premiums and extend product lifecycles beyond generic immediate-release commoditization.
Market Restraints
- DEA aggregate production quotas:Annual Schedule II manufacturing caps constrain supply planning flexibility and create inventory volatility for manufacturers.
- State prescription monitoring programs:Real-time tracking databases in all fifty states detect diversion patterns and reduce prescriber willingness to initiate opioid therapy.
- Litigation liability exposure:Settlement obligations and ongoing lawsuits compress distribution channel economics and raise manufacturer insurance costs.
Strategic Opportunities
- Specialty pharmacy channels:Direct-to-patient distribution models bypass traditional wholesale markups and capture margin through controlled-substance home delivery.
- Biosimilar opioid alternatives:Adjunct non-opioid analgesic portfolios reduce payer scrutiny while maintaining prescriber relationships within pain management protocols.
- International controlled-substance markets:Regulatory harmonization efforts in Canada and Australia open export pathways for DEA-compliant manufacturers with track-and-trace infrastructure.
Industry Challenges
- Controlled-substance logistics talent:DEA registration compliance and chain-of-custody expertise scarcity limits operational scaling for distribution partners.
- Legacy IT integration:State prescription monitoring program data feeds require expensive EHR system modifications for real-time reporting compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxycodone Market |
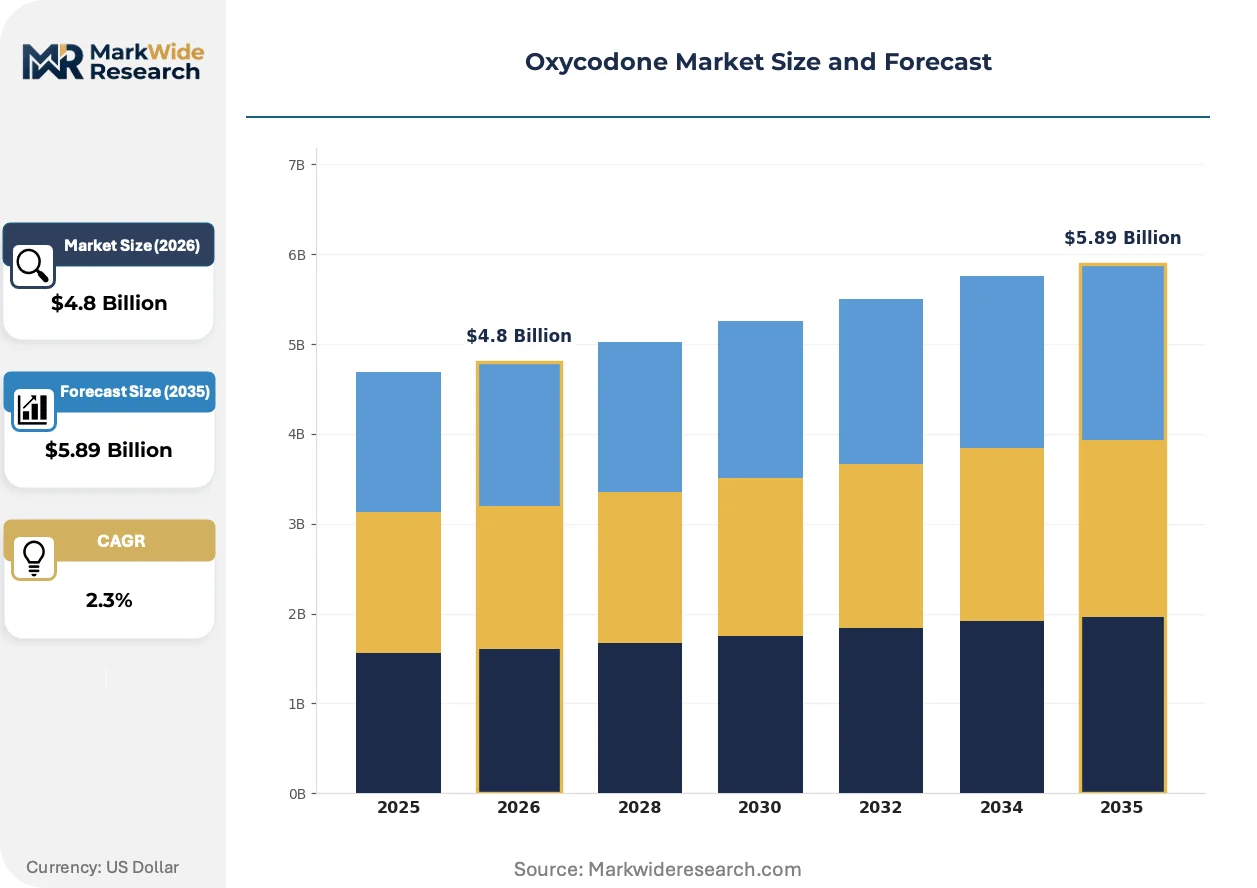
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 2.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immediate Release, Extended Release, Combination Products, Injectable Solutions End User: Hospitals, Clinics, Home Care, Pain Management Centers Formulation: Tablets, Capsules, Liquid Solutions, Patch Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Mallinckrodt Pharmaceuticals, Sun Pharmaceutical Industries Ltd, Endo Pharmaceuticals Inc, Johnson & Johnson, Pfizer Inc, Amneal Pharmaceuticals LLC, Noramco, Collegium Pharmaceutical Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxycodone Market Strategic Shifts
Formulation technology advances and regulatory compliance automation are reshaping competitive positioning in controlled-substance manufacturing and distribution.
Abuse-deterrent polymer matrix technology is expanding into extended-release oxycodone portfolios by creating physical and chemical barriers to crushing, snorting, or injection. Pain management centers and hospital formularies are adopting these formulations as standard-of-care for moderate-to-severe chronic pain. The technology is expanding into prescriber liability protection strategies that reduce malpractice exposure while maintaining therapeutic access.
The FDA's REMS program for extended-release and long-acting opioids mandates prescriber training, patient counseling documentation, and pharmacy verification protocols. Manufacturers must fund and administer these education programs as a condition of market access. Extended-release formulations face the strictest compliance requirements, creating a structural barrier that immediate-release generics bypass but cannot match for chronic pain indications.
Hospital procurement through group purchasing organizations now dominates extended-release volume, with three-year sole-source contracts replacing fragmented purchasing across individual facilities. Integrated delivery networks negotiate directly with manufacturers for system-wide formulary placement, displacing independent pharmacy benefit managers. This concentration is most visible in United States metropolitan hospital systems where vertical integration of acute and post-acute care creates single-point buying authority.
Oxycodone Market Segmentation
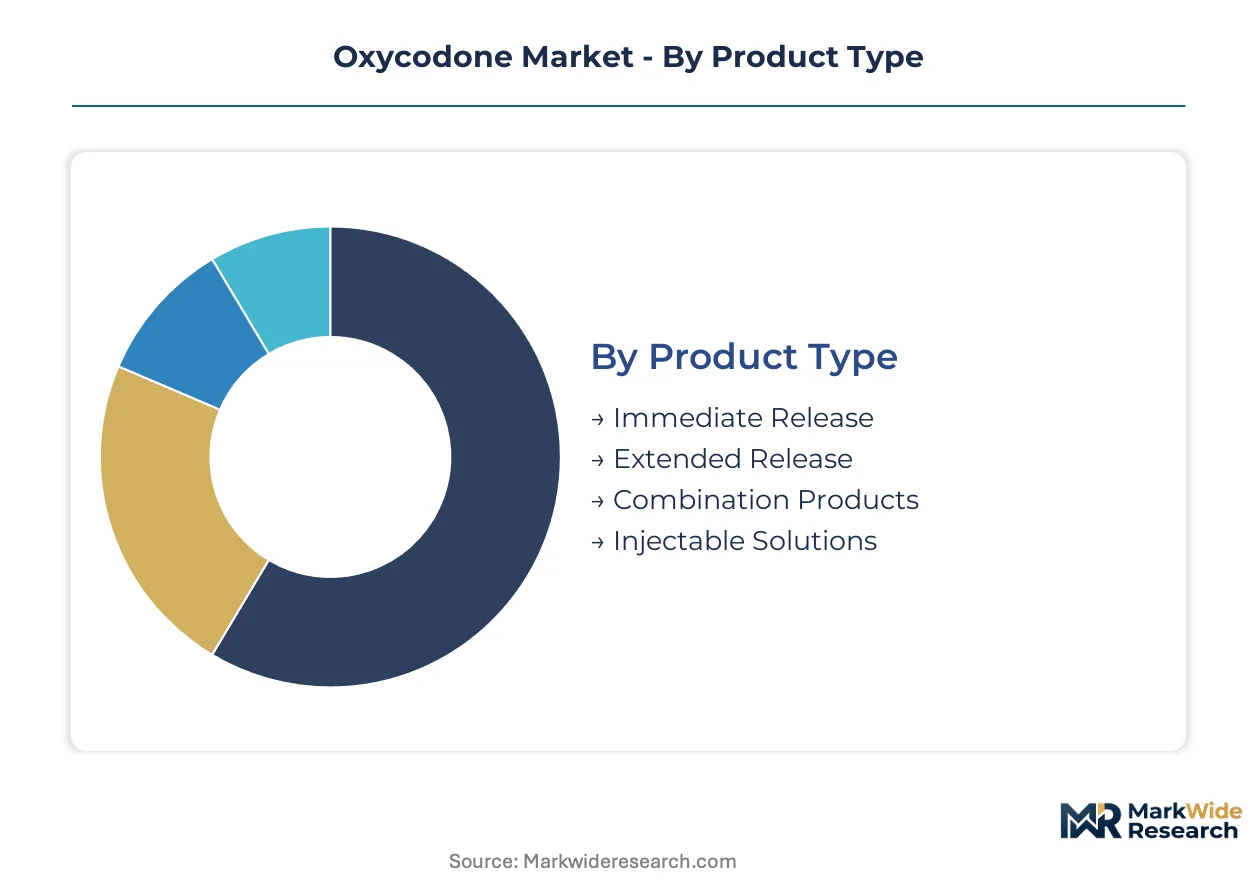
Segmentation in the oxycodone market reveals how regulatory pressure and clinical utility reshape procurement patterns across formulations and channels. Understanding these divisions exposes where margin protection survives generic commoditization and where compliance costs concentrate.
Product Type:
Replacement cycles differ sharply across release mechanisms, with extended-release patents outlasting immediate-release commoditization by years.
- Immediate Release:Rapid-onset tablets and capsules deliver analgesic effects within 30 minutes for acute pain episodes. Demand clusters in United States emergency departments and post-surgical discharge protocols where short-duration therapy limits diversion risk.
- Extended Release:Polymer-matrix and osmotic-pump formulations maintain plasma concentrations over 12 hours through controlled dissolution mechanisms. Hospice benefit expansion in United States Medicare drives volume toward tamper-resistant variants that satisfy FDA Risk Evaluation and Mitigation Strategy training mandates.
- Combination Products:Fixed-dose oxycodone-acetaminophen and oxycodone-aspirin formulations leverage non-opioid adjuvants to enhance analgesia at lower opioid doses.
- Injectable Solutions:Parenteral formulations for intraoperative and intensive care settings where oral absorption is compromised.
Volume placements concentrate in Immediate Release; the faster expansion belongs to Extended Release.
End User:
Customer concentration patterns reflect reimbursement structure and controlled-substance security requirements.
- Hospitals:Acute care facilities with closed formulary systems and 24-hour pharmacy coverage. Integrated delivery network consolidation in United States metropolitan markets concentrates procurement authority under centralized pharmacy and therapeutics committees.
- Pain Management Centers:Specialty clinics with board-certified practitioners maintaining DEA registration and state prescription monitoring program integration. These facilities generate extended-release prescriptions for chronic non-cancer pain while navigating malpractice liability exposure.
- Clinics:Outpatient settings including orthopedic, oncology, and primary care practices with varying controlled-substance prescribing privileges.
- Home Care:Hospice agencies and home infusion services managing terminal pain with direct-to-patient delivery models.
Procurement authority clusters in Hospitals; Pain Management Centers capture the steepest expansion trajectory for extended-release volume.
Formulation:
Physical delivery mechanisms determine stability, abuse liability, and manufacturing complexity.
- Tablets:Compressed solid dosage forms dominating immediate-release and extended-release portfolios. Abuse-deterrent tablet technologies incorporating physical barriers and aversive agents command formulary preference in United States hospital systems seeking liability reduction.
- Liquid Solutions:Oral concentrates and suspensions enabling dose titration for patients with dysphagia or enteral feeding requirements.
- Capsules:Gelatin or HPMC shells containing granules or powders with faster dissolution profiles than compressed tablets.
- Patch:Transdermal delivery systems with limited oxycodone availability compared to fentanyl and buprenorphine alternatives.
Manufacturing scale concentrates in Tablets; Liquid Solutions address the fastest-growing niche for geriatric and palliative applications.
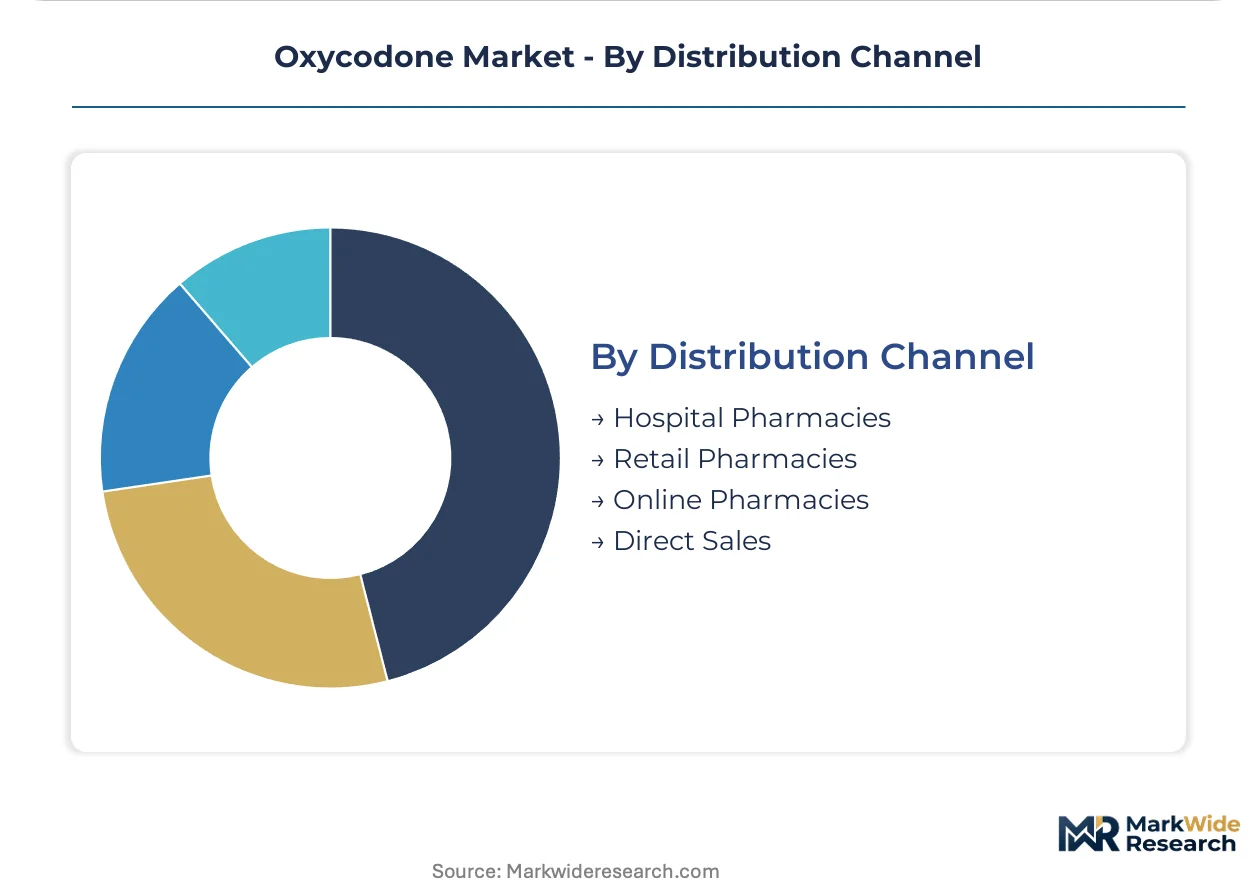
Distribution Channel:
Channel economics reflect DEA track-and-trace compliance costs and inventory security investments.
- Hospital Pharmacies:Captive dispensaries within acute care facilities with automated dispensing cabinet integration and waste reconciliation protocols. Group purchasing organization contracts now cover 90 percent of United States hospital system volume.
- Retail Pharmacies:Community chains and independents with real-time prescription monitoring program connectivity and patient counseling documentation requirements.
- Online Pharmacies:Verified internet prescription access points with controlled-substance shipping restrictions under DEA regulations.
- Direct Sales:Manufacturer-to-institution arrangements for large health systems bypassing wholesale markups.
Transaction volume concentrates in Hospital Pharmacies; specialty logistics capabilities are expanding fastest in Direct Sales channels serving integrated delivery networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems absorb the dominant share of oxycodone volume, with Medicare hospice expansion and integrated delivery network consolidation concentrating procurement authority. Pain management protocols in terminal care settings sustain extended-release demand despite prescriber training mandates.
United States
Medicare hospice benefit growth drives extended-release consumption in terminal pain management. The FDA's REMS program mandates prescriber certification and patient counseling documentation for long-acting formulations. Hospital procurement in metropolitan systems now flows through group purchasing organization contracts covering ninety percent of acute care volume.
Canada
Palliative care infrastructure expansion in provincial health systems sustains controlled-substance demand for cancer and chronic pain patients. Health Canada's controlled drugs and substances regulations align with DEA track-and-trace standards, enabling cross-border distribution partnerships. Ontario and British Columbia health authorities concentrate formulary decisions under centralized pharmacy and therapeutics committees.
Germany
Ambulatory palliative care reimbursement under statutory health insurance maintains opioid analgesic access for terminal patients. The Federal Institute for Drugs and Medical Devices enforces manufacturing quality standards for semisynthetic opioid imports. Baden-Württemberg and Bavaria host specialized pharmaceutical distributors with cold-chain and controlled-substance licensing.
Australia
Pharmaceutical Benefits Scheme listings for extended-release opioids subsidize patient access in oncology and palliative settings. The Therapeutic Goods Administration's narcotic drugs scheduling requires import permits and distribution reporting for Schedule 8 substances. Sydney and Melbourne hospital networks operate closed-formulary systems with automated dispensing cabinet integration.
United Kingdom
National Health Service palliative care pathways standardize strong opioid prescribing for cancer pain and end-of-life management. The Medicines and Healthcare products Regulatory Agency enforces import licensing and wholesale dealer authorizations for controlled drugs. London teaching hospitals and Greater Manchester health systems negotiate direct manufacturer contracts bypassing traditional wholesale channels.
Oxycodone Market Competitive Environment
United States manufacturers anchor the premium formulation tier; Israeli and Indian producers hold cost-competitive positions in immediate-release supply. The vendor structure concentrates around three strategic archetypes: generic scale operators with DEA-registered manufacturing infrastructure, specialty pharmaceutical companies with abuse-deterrent patent portfolios, and diversified healthcare conglomerates with integrated distribution networks. Competitive moves center on formulary placement negotiations with group purchasing organizations and specialty pharmacy channel expansion to capture direct-to-patient margins.
Among Israel-based manufacturers, Teva Pharmaceutical Industries Ltd exemplifies the generic scale archetype with broad immediate-release and extended-release portfolios. Mallinckrodt Pharmaceuticals occupies a position within the specialty controlled-substance distribution tier, satisfying DEA track-and-trace mandates through dedicated infrastructure. Collegium Pharmaceutical Inc represents the abuse-deterrent innovation segment, addressing prescriber liability concerns through proprietary formulation technology.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Mallinckrodt Pharmaceuticals |
| Sun Pharmaceutical Industries Ltd |
| Endo Pharmaceuticals Inc |
| Johnson & Johnson |
| Pfizer Inc |
| Amneal Pharmaceuticals LLC |
| Noramco |
| Collegium Pharmaceutical Inc |
| Others |
Value Chain & Pricing Dynamics
DEA registration compliance costs cascade through oxycodone manufacturing tiers, with immediate-release generics absorbing narrow margins while extended-release formulations capture value through abuse-deterrent patent protection and hospital formulary premiums.
Pricing Analysis
Volume concentrates in immediate-release tablets where generic competition compresses margins, while extended-release formulations sustain premium positioning through proprietary polymer-matrix technology and REMS-mandated prescriber certification requirements. Price differentiation hinges on abuse-deterrent formulation status and DEA track-and-trace infrastructure investment. Cost compression in immediate-release supply intensifies as Indian and Israeli manufacturers scale API production. Hospital procurement teams exhibit lowest price sensitivity due to liability-driven formulary standardization, while independent retail pharmacies face highest pressure from reimbursement rate compression.
Supply Chain Analysis
Specialized chemist and pharmacist scarcity in United States controlled-substance manufacturing constrains operational scaling for DEA-registered facilities. Active pharmaceutical ingredient production centers on India, Israel, and the United States, with thebaine extraction drawing from Australian and Turkish poppy straw supply. Supply chain risk rests on single-source vulnerability for tamper-resistant polymer excipients. Distribution runs through three-tier wholesale networks with specialty pharmacy direct-to-patient models gaining share in hospice and palliative care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oxycodone market consolidation accelerates as litigation liability exposure forces subscale manufacturers toward exit or acquisition, concentrating volume among DEA-compliant operators with integrated distribution infrastructure.
For Market Incumbents: Deepen abuse-deterrent formulation R&D investment to extend patent lifecycles beyond immediate-release commoditization, while acquiring specialty pharmacy distribution capabilities to capture direct-to-patient margins in hospice channels. Mallinckrodt's controlled-substance logistics infrastructure and Collegium's polymer-matrix patents demonstrate defensible positioning against generic price erosion. For New Entrants and Emerging Players: The gap between premium extended-release hospital contracts and economy-tier immediate-release retail pricing offers entry opportunity through biosimilar opioid alternatives and non-opioid analgesic adjuvants. Pain management centers in United States metropolitan markets present the most penetrable segment for compliant prescriber certification programs. Go-to-market execution should prioritize REMS-compliant educational partnerships over traditional sales force deployment. For Investors and Strategic Acquirers: DEA aggregate production quota reallocation announcements are the leading indicator that manufacturing capacity constraints will favor incumbent scale operators over emerging entrants. Long-term viability requires track-and-trace infrastructure and litigation reserve adequacy. Acquisition targets should display integrated delivery network formulary placement and abuse-deterrent patent portfolios. Watch for state prescription monitoring program data integration mandates as signal of compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Patent Extension | Proprietary polymer-matrix technology protects margin premiums against generic immediate-release erosion. |
| Specialty Pharmacy Channel Expansion | Direct-to-patient distribution bypasses wholesale markups in hospice and palliative care segments. |
| REMS Compliance Infrastructure Investment | Mandatory prescriber training programs create structural barriers to market access for undercapitalized competitors. |
| International Regulatory Harmonization | DEA-compliant track-and-trace systems enable export pathways to Health Canada and TGA-aligned markets. |
| Non-Opioid Adjuvant Portfolio Development | Biosimilar alternatives reduce payer scrutiny while maintaining prescriber relationships within pain protocols. |
Study Parameters
Independent corroboration across DEA production quota filings, FDA REMS program documentation, and Medicare hospice benefit utilization data underwrites the qualitative findings in this study. Primary interviews with controlled-substance manufacturing executives, hospital pharmacy and therapeutics committee chairs, pain management clinic directors, and specialty pharmacy operations leaders combined with secondary validation from FDA Orange Book entries, state prescription monitoring program annual reports, and litigation settlement disclosures. Bottom-up volume modeling and top-down regulatory constraint analysis triangulate market sizing across formulation and channel segments.
Comparable-period anchoring to historical DEA aggregate production quota allocations and REMS implementation timelines structured the forecast window across the analysis window. Segmentation dimensions modeled include release mechanism, end-user setting, distribution channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of Medicare hospice enrollment growth and hospital procurement consolidation patterns. Forecast inputs incorporate FDA abuse-deterrent approval pathways and state-level prescription monitoring program adoption curves.
Inputs from DEA quota publications and FDA REMS compliance reports were available through the study window; gaps in real-time diversion incident data and litigation reserve disclosures introduce uncertainty bands around manufacturer liability exposure estimates. Forecasts reflect assumptions regarding REMS program continuity and DEA scheduling stability. Material deviation in aggregate production quota allocations or state prescription monitoring program interoperability mandates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Global Anti-Fungal Drugs Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Peptide Therapeutics Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Vutrisiran Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
P2X7 Receptor Antagonists Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Ramipril Market