
 Antidepressants Market | 2026-2036
Antidepressants Market Size, Share, and Industry Trends Forecast 2026-2036
Antidepressants Market Analysis
The FDA's Breakthrough Therapy designation for psychiatric drug candidates is recalibrating how developers prioritize CNS pipeline investments. Eli Lilly and Company leverages its metabolic-psychiatry crossover research to sustain novel mechanism discovery. Pfizer Inc. anchors North American manufacturing scale for oral SSRI formulations. H. Lundbeck competes through specialized positioning in treatment-resistant depression segments.
Antidepressants comprise psychotropic compounds—primarily monoamine reuptake inhibitors, receptor modulators, and monoamine oxidase inhibitors—that regulate serotonin, norepinephrine, and dopamine neurotransmission to restore affective stability in mood disorders. These agents are manufactured through multi-step organic synthesis requiring chiral purity above 99.5%, followed by standardization against pharmacopeial reference standards for bioequivalence. Among product types, SSRIs occupy the largest installed prescription base while SNRIs capture expanding share in comorbid pain-depression indications. Oral delivery mode dominates volume economics, though intranasal formulations represent the fastest-growing administration route for acute suicidal ideation interventions.
FDA review standards under the Psychopharmacologic Drugs Advisory Committee shape evidentiary requirements for novel antidepressant submissions, while EMA's CHMP guidelines on major depressive disorder trials enforce harmonized primary endpoint definitions across European markets. The DEA's scheduling controls on esketamine and emerging psychedelic derivatives constrain distribution architecture for rapid-onset therapies. Stakeholders must monitor how FDA digital biomarker qualification pathways and EMA's adaptive licensing pilots will reshape clinical trial cost structures and competitive entry dynamics for next-generation mechanisms.
Market Dynamics
FDA's Breakthrough Therapy designation for psychiatric candidates is compressing development timelines and forcing incumbents to accelerate novel mechanism programs. This regulatory lever is reshaping capital allocation across CNS pipelines.
Growth Catalysts
- Commercial payer expansion:United States insurers have broadened behavioral health coverage, deepening prescription volumes for mood disorder therapies in hospital networks.
- Esketamine distribution architecture:The DEA's controlled substance scheduling for rapid-onset therapies is creating specialized clinic networks for treatment-resistant depression segments.
- Accelerated approval pathways:FDA's Psychopharmacologic Drugs Advisory Committee standards are compressing evidentiary review periods for novel antidepressant submissions.
Market Restraints
- Chiral synthesis cost structure:Manufacturing requires 99.5% purity through multi-step organic synthesis, elevating production costs for generic entrants.
- Distribution concentration risk:DEA scheduling controls constrain pharmacy and clinic networks for psychedelic-derived rapid-onset therapies.
- Placebo response variability:High placebo rates in major depressive disorder trials inflate sample size requirements and extend clinical development timelines.
Strategic Opportunities
- Intranasal administration route:Acute suicidal ideation interventions represent the fastest-growing delivery mode outside oral volume economics.
- Digital biomarker qualification:FDA's novel endpoint pathways enable remote monitoring integration into psychiatric trial designs.
- Metabolic-psychiatry convergence:Crossover research between diabetes and depression mechanisms opens novel target discovery vectors.
Industry Challenges
- Specialized psychiatry recruitment:Principal investigator scarcity for CNS trials extends site activation timelines and inflates per-patient costs.
- Pharmacopeial standardization:Bioequivalence testing against reference standards creates bottlenecks for abbreviated new drug applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antidepressants Market |
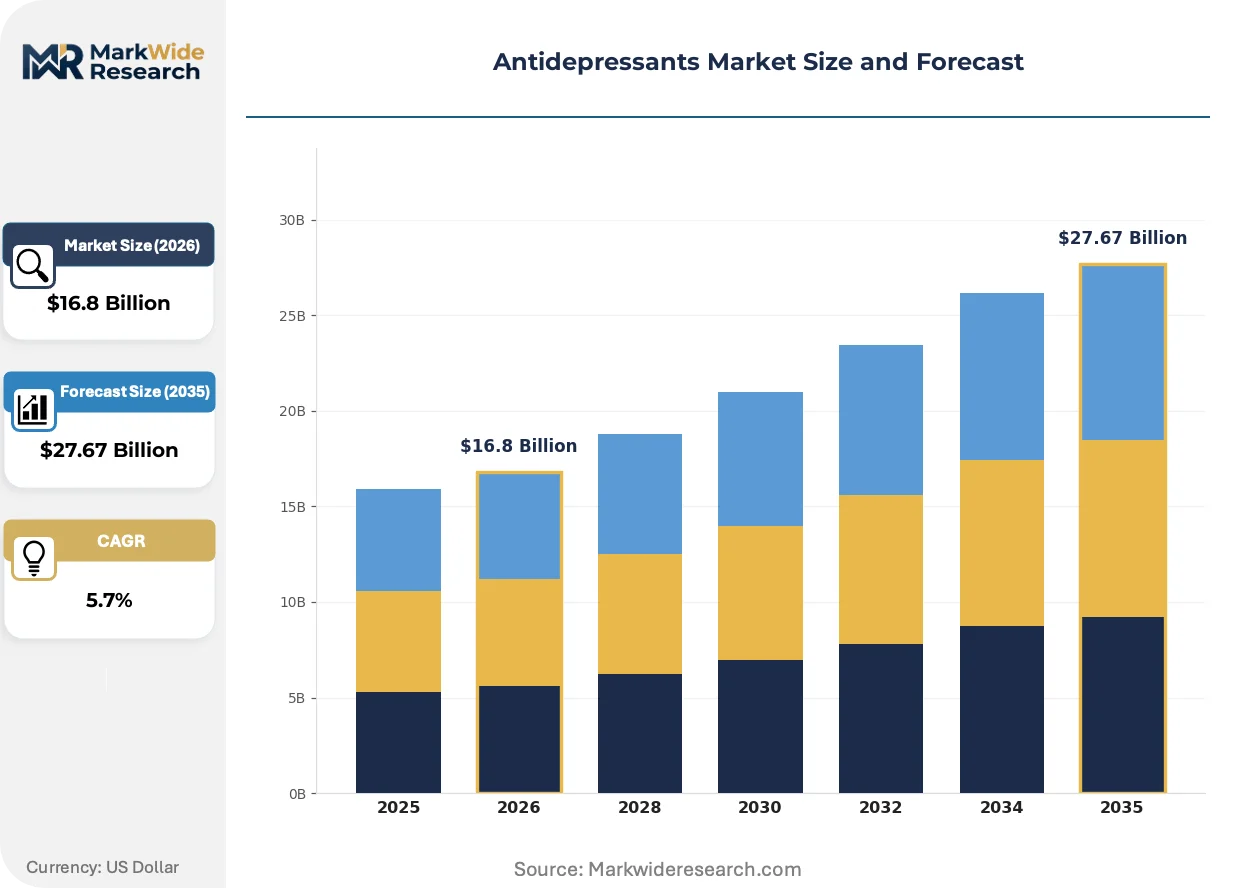
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, Tricyclics, MAOIs Delivery Mode: Oral, Injectable, Transdermal, Intranasal End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Indication: Major Depressive Disorder, Anxiety Disorders, Panic Disorders, Obsessive-Compulsive Disorder |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, GlaxoSmithKline, AstraZeneca, Johnson & Johnson, H. Lundbeck, Takeda Pharmaceutical Company, Novartis AG, Bristol Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antidepressants Market Emerging Trajectories
Psychiatric drug development is pivoting toward rapid-onset mechanisms and digital trial infrastructure. These shifts are compressing traditional SSRI dominance and enabling new competitive entry vectors.
Ketamine-derived rapid-acting antidepressants are converging with intranasal delivery technologies to enable clinic-based acute interventions. Hospital emergency departments and specialized psychiatric clinics are adopting these formulations for suicidal ideation protocols. This convergence is compressing the window between diagnosis and therapeutic response from weeks to hours.
EMA's adaptive licensing pilots for major depressive disorder are reshaping European trial cost structures. The CHMP guideline harmonization on primary endpoints reduces protocol amendment rates across multi-national studies. Developers are responding by front-loading European site activation in global Phase III programs.
Telepsychiatry platforms are unbundling traditional prescriber-patient relationships and enabling direct-to-consumer mental health channels. Employer-sponsored behavioral health benefits are replacing traditional pharmacy benefit manager formularies as the primary access point. This channel shift is most visible in United States commercial coverage expansions for virtual psychiatric consultations.
Antidepressants Market Segmentation
Antidepressant procurement decisions hinge on clinical efficacy profiles, reimbursement pathways, and administration logistics that vary sharply across patient acuity settings. Manufacturers align formulation development with the specific neuropharmacological requirements and care delivery constraints of each segment cluster.
Product Type:
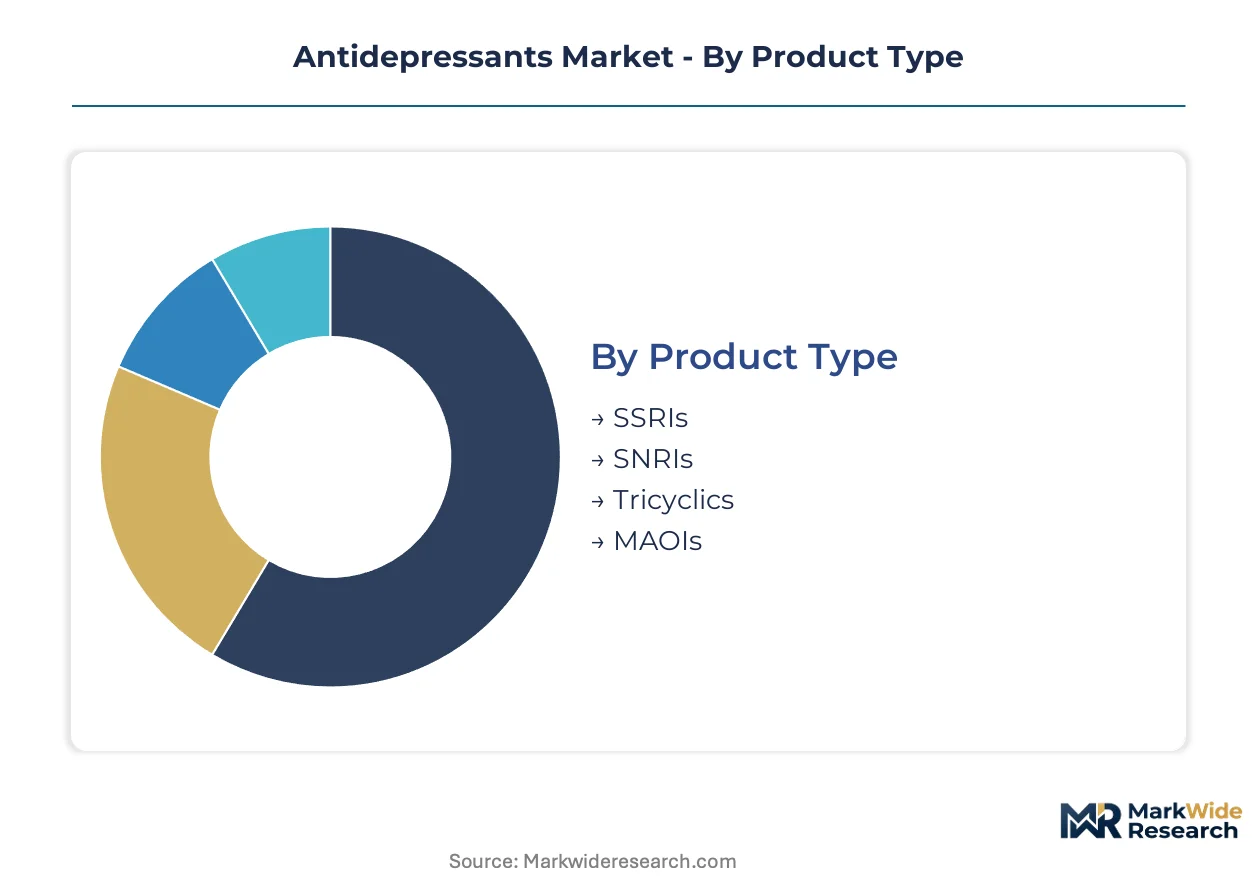
Prescribers weigh tolerability profiles against treatment-resistant depression prevalence when selecting among mechanistic classes.
- SSRIs:Selective serotonin reuptake inhibitors block presynaptic serotonin transporters to elevate synaptic 5-HT concentrations. Demand concentrates in United States primary care networks where first-line prescribing protocols favor fluoxetine and sertraline equivalents for their established safety databases.
- SNRIs:Dual serotonin-norepinephrine reuptake inhibition addresses comorbid neuropathic pain-depression presentations. United States Veterans Affairs health systems and chronic pain clinics drive volume for duloxetine and venlafaxine formulations given their dual indication coverage.
- Tricyclics:Non-selective monoamine reuptake blockers with significant anticholinergic burden, now reserved for refractory cases where newer agents fail.
- MAOIs:Irreversible monoamine oxidase inhibition requires dietary restriction protocols, limiting deployment to specialized psychiatric units with monitoring infrastructure.
SSRIs lead on scale; SNRIs lead on momentum.
Delivery Mode:
Route selection tracks patient compliance capacity, onset urgency, and care setting infrastructure availability.
- Oral:Tablet and capsule formulations dominate maintenance therapy economics through pharmacy distribution. United States retail pharmacy chains and mail-order benefit managers handle the majority of volume for escitalopram and paroxetine prescriptions.
- Injectable:Depot formulations and intramuscular delivery address adherence failure in severe recurrent depression. United States community mental health centers and Assertive Community Treatment teams utilize long-acting injectables for high-risk patient cohorts.
- Transdermal:Selegiline patches bypass first-pass hepatic metabolism for patients with gastrointestinal intolerance or cytochrome P450 polymorphisms.
- Intranasal:Esketamine and emerging rapid-onset candidates target acute suicidal ideation in emergency psychiatric settings. United States hospital emergency departments and certified treatment centers are expanding capacity for supervised administration under REMS protocols.
Oral formulations capture volume economics; intranasal delivery is climbing the fastest.
End User:
Care setting determines monitoring intensity, reimbursement tier, and formulary placement authority.
- Hospitals:Inpatient psychiatric units and general medical floors manage severe depressive episodes with comorbid medical instability. United States hospital networks with dedicated behavioral health service lines are deepening esketamine clinic investments.
- Clinics:Outpatient mental health practices and federally qualified health centers handle the majority of maintenance prescribing. United States commercial payer contracts increasingly steer patients toward clinic-based care management programs.
- Homecare:Telepsychiatry platforms and home health nursing enable remote monitoring for stable patients with transportation barriers.
- Rehabilitation Centers:Substance use disorder facilities integrate antidepressant protocols for dual-diagnosis populations requiring coordinated psychiatric and addiction services.
Hospitals lead on scale; homecare is gaining share fastest.
Indication:
Diagnostic coding specificity shapes prior authorization requirements and step-therapy sequencing in payer formularies.
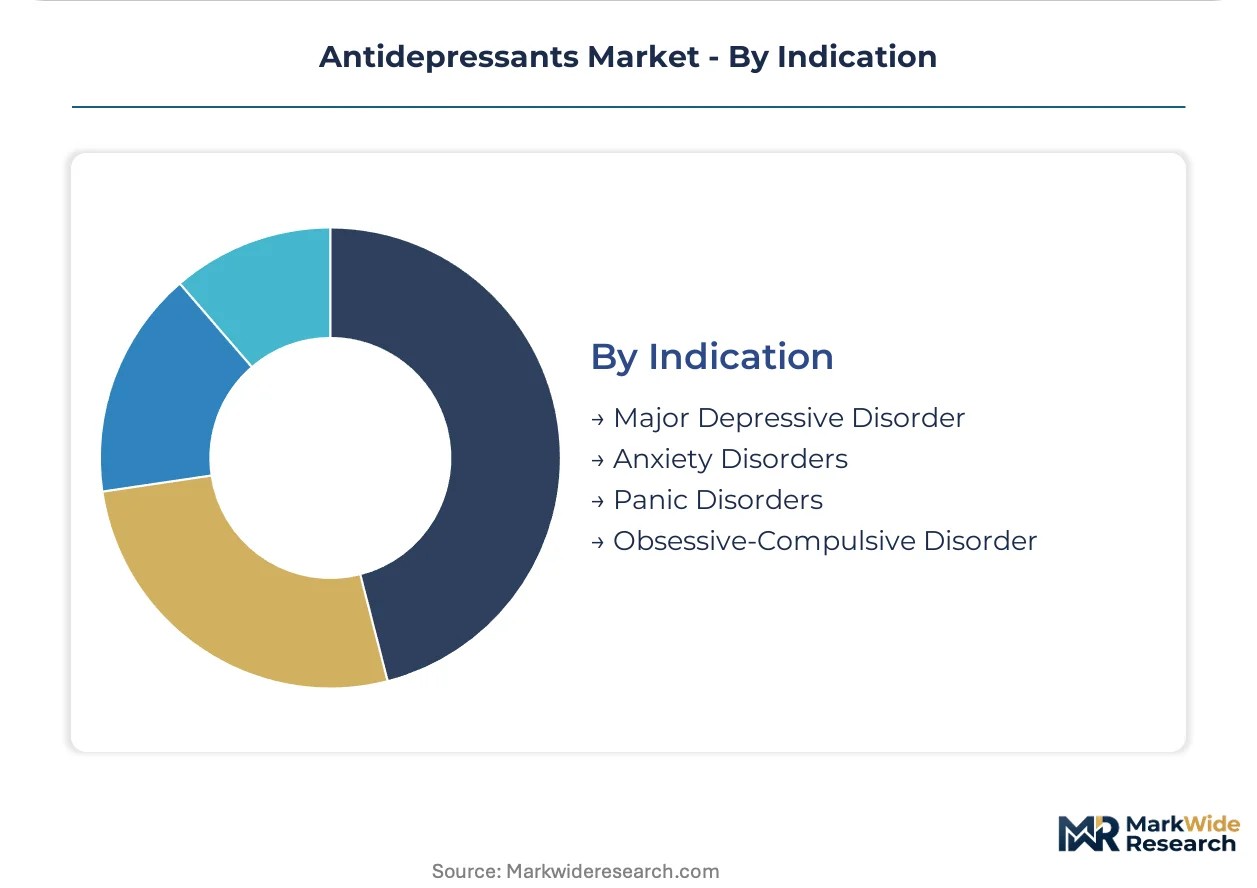
- Major Depressive Disorder:The foundational indication for virtually all approved agents, with diagnostic criteria defined by DSM-5-TR symptom thresholds. United States commercial insurers and Medicare Advantage plans apply differential coverage tiers based on episode severity documentation.
- Anxiety Disorders:Generalized anxiety and social anxiety indications extend SSRI and SNRI utility beyond mood symptoms. United States employer-sponsored behavioral health benefits are expanding coverage for anxiety-specific digital therapeutics as adjuncts to pharmacotherapy.
- Panic Disorders:Acute episodic presentations require rapid titration protocols and benzodiazepine-sparing strategies in emergency care settings.
- Obsessive-Compulsive Disorder:Higher serotonergic dose requirements and augmentation strategies differentiate OCD pharmacotherapy from standard depression protocols.
Major Depressive Disorder leads on scale; Anxiety Disorders show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The antidepressants industry traces its commercial origins to Swiss and German pharmaceutical laboratories in the mid-20th century, where imipramine and early tricyclic compounds first demonstrated mood-elevating pharmacology. United States research institutions subsequently scaled SSRI development through the 1980s and 1990s, establishing the therapeutic templates that dominate contemporary prescribing.
United States
Commercial payer networks have broadened behavioral health coverage, deepening prescription volumes through hospital-affiliated clinic systems. The FDA's Breakthrough Therapy designation pathway compresses review timelines for novel psychiatric mechanisms. Boston-Cambridge and Research Triangle Park anchor the densest concentration of CNS-focused clinical trial infrastructure.
Germany
EMA's CHMP guidelines on major depressive disorder trials enforce harmonized endpoint definitions that reduce protocol amendments across multi-national studies. The country's statutory health insurance system maintains broad reimbursement for both established and novel antidepressant formulations. Baden-Württemberg and Bavaria host specialized psychiatry research institutes that coordinate European site activation.
Japan
PMDA's psychotropic drug review standards emphasize long-term safety databases that extend development timelines for foreign entrants seeking market authorization. METI's healthcare innovation programs subsidize domestic development of rapid-onset psychiatric therapies. The Kanto region around Tokyo concentrates hospital-based psychiatric research and specialist prescriber networks.
United Kingdom
NICE technology appraisals determine formulary placement for antidepressant classes across NHS England, creating tiered access based on cost-effectiveness thresholds. MHRA post-Brexit regulatory autonomy enables accelerated national approvals that diverge from EMA timelines. London and the Southeast corridor host the majority of European headquarters for multinational psychiatric drug developers.
India
CDSCO's streamlined approval pathways for psychiatric generics expand manufacturing volume for export-oriented formulations. The country's central government includes antidepressants in essential medicines lists that mandate public sector procurement. Gujarat and Maharashtra host the largest concentration of API synthesis facilities serving global SSRI and SNRI supply chains.
Antidepressants Market Vendor Landscape
Premium-margin players sit above commodity-margin players across mechanism novelty and regulatory exclusivity dimensions. The market structure concentrates around developers with established CNS pipelines and manufacturing scale for oral formulations. Three archetypes dominate: large-cap pharmaceutical conglomerates with diversified psychiatric portfolios, mid-cap specialists in treatment-resistant depression segments, and generic manufacturers competing on chiral synthesis efficiency. Competitive moves center on metabolic-psychiatry crossover research investments and intranasal delivery technology licensing.
Within the large-cap diversified tier, Pfizer Inc. and Eli Lilly and Company occupy positions shaped by North American manufacturing infrastructure and novel mechanism discovery programs. H. Lundbeck represents the specialized positioning archetype, with corporate structure reflecting Danish origins and focused CNS development heritage. These three entities exemplify how geographic concentration of regulatory expertise and clinical trial infrastructure reinforces competitive positioning in psychiatric drug development.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| GlaxoSmithKline |
| AstraZeneca |
| Johnson & Johnson |
| H. Lundbeck |
| Takeda Pharmaceutical Company |
| Novartis AG |
| Bristol Myers Squibb |
| Others |
Supply Flow & Price Mechanics
EMA's Good Manufacturing Practice environmental sustainability mandates gate qualified supply for European market access and anchor premium-tier pricing for certified manufacturers. Chiral synthesis facilities meeting these standards command pricing premiums while generic entrants face exclusion from formulary tiers requiring carbon footprint disclosures.
Pricing Analysis
Three-tier pricing structure across originator, authorized generic, and commodity generic levels stratifies the antidepressant market by regulatory exclusivity and manufacturing pedigree. Price differentiation hinges on FDA bioequivalence certification tier and chiral purity grade above 99.5%, with originator brands maintaining margin premiums through REMS-protected distribution. Cost compression in commodity oral SSRI tiers intensifies as Indian and Chinese API manufacturers scale volume output. Hospital procurement committees exhibit highest price sensitivity, while specialized esketamine clinics accept premium pricing for rapid-onset mechanisms.
Supply Chain Analysis
Reverse-logistics flows for controlled substances like esketamine impose specialized return-to-clinic protocols and REMS-mandated waste tracking that elevate distribution costs. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with Gujarat and Zhejiang provinces anchoring global SSRI precursor supply. Finished formulation draws from specialized chiral intermediates, enteric coating polymers, and nasal delivery device components. Single-source vulnerability runs through Chinese suppliers of serotonin transporter inhibitor precursors. Distribution runs through hospital-affiliated specialty pharmacies and certified treatment centers under DEA oversight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antidepressant manufacturing arbitrage between United States and Indian production bases exploits a 40-60% cost differential in chiral synthesis labor and environmental compliance, rewarding players with dual-hemisphere facility footprints.
For Market Incumbents: Deploy metabolic-psychiatry crossover R&D to outpace FDA Breakthrough Therapy compressing development timelines for novel mechanisms. Incumbents should consolidate intranasal delivery technology licensing to defend against ketamine-derived rapid-onset entrants, while expanding backward integration into Indian API supply to offset chiral synthesis cost inflation. For New Entrants and Emerging Players: The 300-400% price-point gap between originator intranasal esketamine and oral generic SSRIs creates entry space for mid-tier rapid-onset candidates. New entrants should target United States Veterans Affairs health systems with dual pain-depression SNRI formulations, leveraging 505(b)(2) regulatory pathways to accelerate market access without full Phase III burden. For Investors and Strategic Acquirers: Roll-up economics work for specialized CNS clinical-stage developers because FDA's Psychopharmacologic Drugs Advisory Committee creates regulatory moats that large-cap pharmas will pay premiums to acquire. Investors should prioritize treatment-resistant depression platform companies with intranasal assets in Phase IIb. The signal to watch is FDA digital biomarker qualification announcements, which will compress trial costs and trigger acquisition premiums for compliant developers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy designation compresses psychiatric drug review timelines by 6-12 months versus standard submissions. |
| Manufacturing Scale-Up | Chiral synthesis capacity expansion in Gujarat and Maharashtra secures API supply for global SSRI generic volume. |
| Licensing Agreement | Intranasal delivery technology partnerships enable clinic-based esketamine administration under REMS protocols. |
| Pipeline Diversification | Metabolic-psychiatry crossover programs at Eli Lilly and Company open novel target discovery beyond monoamine mechanisms. |
| Clinical Trial Advancement | Digital biomarker integration into psychiatric trials reduces placebo response variability and site activation costs. |
Methodological Framework
Multiple input streams — executive interviews with CNS development heads, regulatory affairs specialists, and hospital formulary directors; secondary validation against FDA filings, ClinicalTrials.gov, and EMA CHMP guidelines; and trade data from API export registries — were reconciled through bottom-up prescription volume modeling and top-down market sizing across the analysis window.
Historical prescription trends were cross-referenced against expert panel inputs on pipeline progression and payer coverage shifts. The analytical framework modeled segmentation across product mechanism, delivery mode, care setting, and regional regulatory cluster throughout the forecast period. CAGRs were derived from patent expiry schedules, biosimilar entry assumptions, and intranasal formulation adoption curves.
Caveats apply where FDA digital biomarker qualification delays or DEA rescheduling actions could materially shift the outlook for rapid-onset therapy penetration. Practitioners should monitor FDA Psychopharmacologic Drugs Advisory Committee meeting calendars and EMA adaptive licensing pilot announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Naproxen Market