
 Intravenous Solution Compounders Market | 2026-2036
Intravenous Solution Compounders Market Size, Share, and Industry Trends Forecast 2026-2036
Intravenous Solution Compounders Market Foresight
Preventive maintenance contracts and software-defined compliance modules is rebalancing vendor economics toward recurring revenue streams rather than pure equipment sales. Baxter International leverages its installed base of infusion systems to extend service agreements across hospital networks. Fresenius Kabi anchors its European position through specialized compounding hardware for oncology applications. B. Braun competes on integrated sterile-to-patient workflows that reduce manual touchpoints in critical care settings.
Intravenous solution compounders are electromechanical or gravity-assisted devices that combine multiple sterile pharmaceutical ingredients into patient-specific admixtures, typically operating within ISO Class 5 environments with HEPA filtration and pressure differentials maintained at 0.01 inches of water column. These systems serve primarily to eliminate human calculation errors, ensure dose accuracy within five percent variance, and maintain sterility throughout the compounding process for parenteral administration. Automated compounders lead the product type landscape due to their error-reduction protocols and barcode verification integration, while admixture systems represent the fastest-growing configuration as hospitals seek closed-system processing for hazardous drugs. Among applications, oncology compounding commands the most stringent regulatory oversight and generates the highest per-unit margins because of cytotoxic handling requirements and specialized engineering.
The US FDA enforces current Good Manufacturing Practice standards for 503B outsourcing facilities and sterile compounding guidelines for 503A pharmacies, directly determining which device features qualify for institutional procurement. The European Medicines Agency and national competent authorities apply Annex 1 manufacturing requirements that mandate continuous viable particle monitoring during compounding operations, shaping European equipment specifications differently than American counterparts. ISO standards for cleanroom design and operation provide the baseline technical framework that manufacturers must embed into system architecture. Stakeholders must weigh capital deployment between centralized 503B-scale automation and distributed hospital-based systems as reimbursement structures for compounded medications continue to shift.
Market Dynamics
Centralized sterile compounding operations are consolidating purchasing power across large health systems, forcing device manufacturers to restructure from transactional equipment sales toward multi-year service partnerships with embedded compliance software.
Growth Catalysts
- Closed-system transfer device mandates:The US FDA's updated sterile compounding guidance requires facilities handling hazardous drugs to adopt sealed transfer mechanisms, directly accelerating replacement cycles for open-system compounders in hospital pharmacies.
- Oncology volume expansion:Rising chemotherapy administration in outpatient infusion centers generates demand for cytotoxic-capable compounders with specialized engineering for containment and decontamination protocols.
- Barcode verification integration:Automated compounders with integrated medication scanning are reducing human calculation errors to below five percent variance, satisfying Joint Commission accreditation requirements for high-alert medications.
Market Restraints
- Stainless steel and medical-grade polymer costs:Input material volatility for HEPA filtration housings and pressure-differential chambers compresses gross margins on hardware sales, particularly for mid-tier manufacturers without captive supply chains.
- European component concentration:Precision pumps and peristaltic tubing for admixture systems source predominantly from German and Swiss suppliers, exposing procurement to single-source risk during trade disruptions.
- ISO Class 5 infrastructure requirements:Cleanroom construction with continuous viable particle monitoring adds capital intensity that excludes smaller 503A pharmacies from automated system adoption.
Strategic Opportunities
- 503B outsourcing facility scale-up:The US reimbursement shift toward centralized compounding creates white space for high-throughput automation serving multiple hospital systems from single locations.
- Artificial intelligence and predictive maintenance convergence:Machine learning algorithms analyzing compounder sensor data enable preemptive servicing, reducing unplanned downtime for critical care admixture production.
- India's hospital infrastructure expansion:Private health system consolidation in Mumbai, Delhi, and Bangalore generates demand for entry-level automated compounders as these facilities build ISO-compliant cleanrooms.
Industry Challenges
- Certified pharmacy technician scarcity:Sterile compounding operations require personnel trained in aseptic technique and hazardous drug handling, with accredited programs producing insufficient graduates relative to facility expansion plans.
- Legacy HIS integration complexity:Automated compounders must interface with disparate hospital information systems, electronic health records, and pharmacy management platforms through custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intravenous Solution Compounders Market |
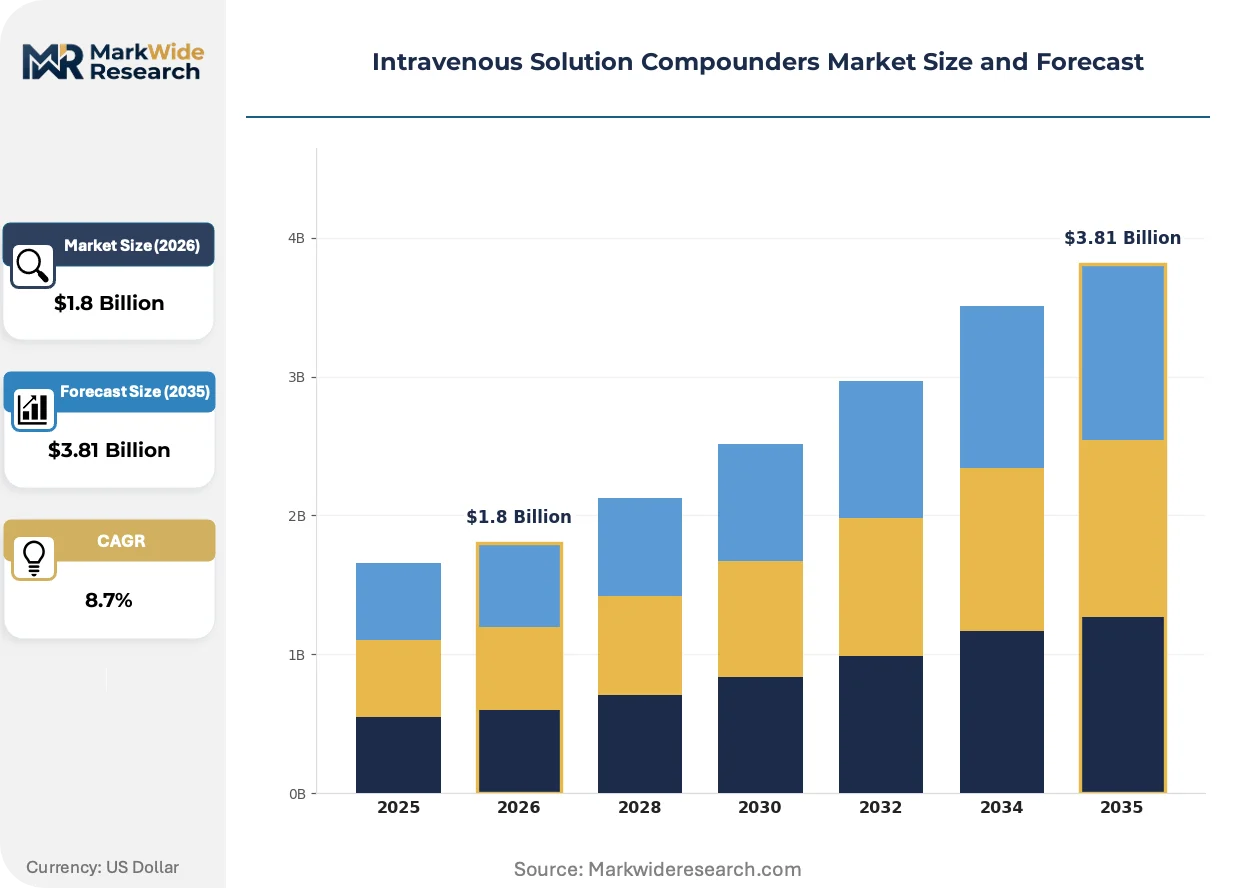
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Compounders, Manual Compounders, Batch Systems, Admixture Systems End User: Hospitals, Clinics, Homecare Providers, Ambulatory Surgery Centers Technology: Microbial Filtration, IV Pumps, Software Integration, Sterile Compounding Systems Application: Critical Care, Oncology, Pain Management, Nutritional Support |
| Companies Covered | Baxter International, Fresenius Kabi, B. Braun, Omnicell, ICU Medical, Grifols, COMECER, Becton Dickinson, Fagron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intravenous Solution Compounders Market Shifts & Advancements
Electromechanical precision and software-defined compliance are converging to transform compounder architecture from isolated hardware into networked clinical infrastructure with real-time quality assurance.
Closed-system robotic compounding is electrifying sterile-to-patient workflows by eliminating manual touchpoints during hazardous drug preparation. Large academic medical centers in the United States are deploying these systems at accelerated replacement cycles, compressing market demand toward integrated platforms that combine compounding, verification, and documentation in single footprints.
The European Medicines Agency's revised Annex 1 manufacturing requirements mandate continuous viable particle monitoring during aseptic processing, compelling compounder manufacturers to embed environmental sensors directly into system architecture. This regulatory pressure disproportionately affects admixture system configurations, which European hospital pharmacies are now specifying with built-in pressure differential logging and automated alert protocols.
Service unbundling is fragmenting traditional equipment procurement as hospital pharmacy directors separate hardware acquisition from preventive maintenance and software licensing. Third-party service providers and original equipment manufacturers now compete directly for multi-year contracts, with the United States exhibiting the most pronounced shift toward outcome-based uptime guarantees rather than break-fix arrangements.
Intravenous Solution Compounders Market Segmentation
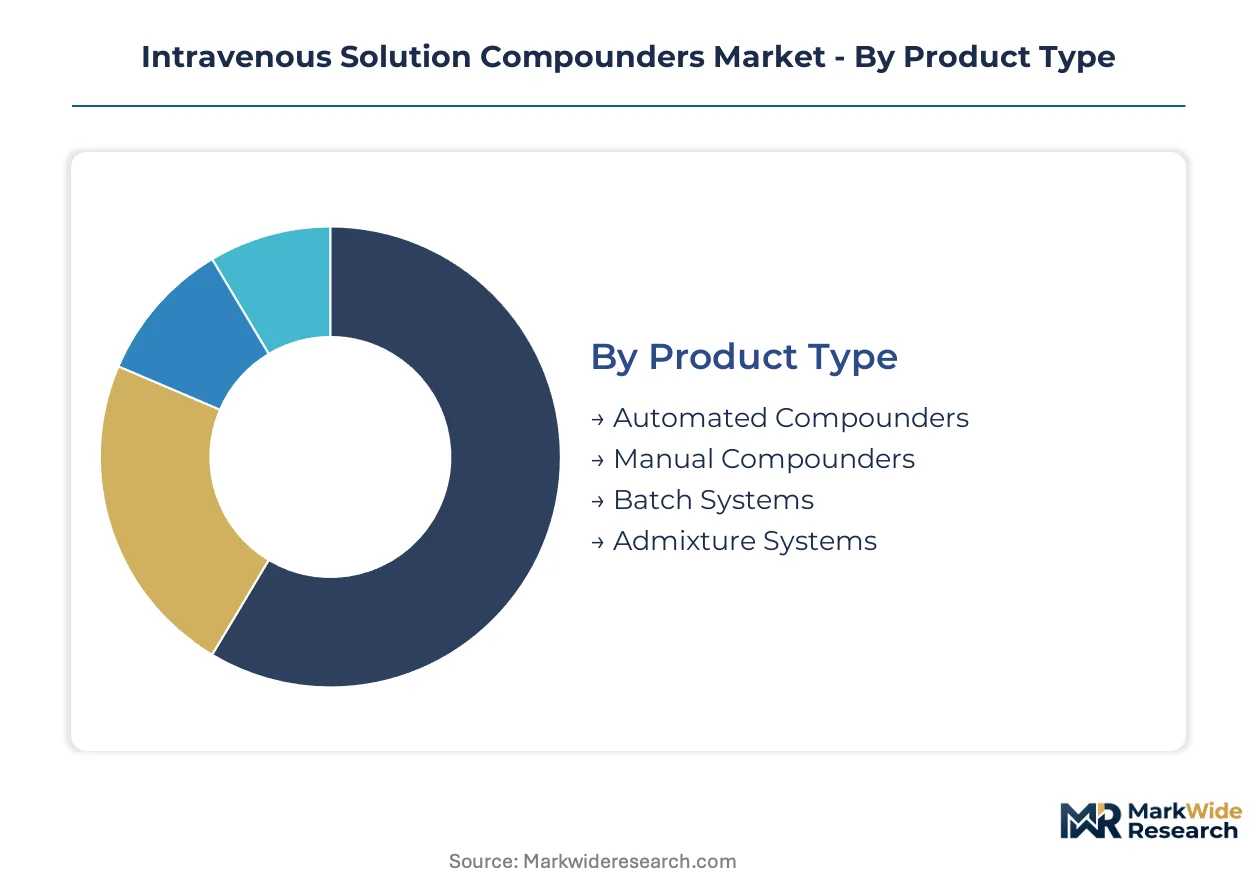
Segmentation in the intravenous solution compounders market reveals divergent technology investments across care settings. Product architecture, end-user infrastructure, and application risk profiles determine procurement specifications and margin structures.
Product Type:
Volume leadership sits with automated platforms, while premium engineering concentrates in specialized configurations for hazardous drug handling.
- Automated Compounders:Electromechanical systems integrate barcode verification, gravimetric analysis, and closed-system transfer protocols to eliminate human calculation errors. Large US health systems deploying centralized 503B facilities specify these units for high-throughput oncology admixture production, driven by Joint Commission mandates for high-alert medication accuracy.
- Admixture Systems:Closed-system configurations with integrated HEPA filtration and pressure-differential chambers enable sterile-to-patient workflows for cytotoxic compounds. Outpatient infusion centers across Germany and Switzerland are accelerating replacement cycles for these units, compelled by EMA Annex 1 requirements for continuous environmental monitoring during aseptic processing.
- Manual Compounders:Gravity-assisted devices with basic volumetric controls serve smaller 503A hospital pharmacies with limited capital budgets.
- Batch Systems:High-capacity platforms designed for 503B outsourcing facilities producing standardized admixtures across multiple hospital networks.
Today's leader: Automated Compounders. Tomorrow's challenger: Admixture Systems.
End User:
Procurement authority consolidates in integrated delivery networks, while reimbursement shifts fragment purchasing across ambulatory sites.
- Hospitals:Central pharmacy operations in academic medical centers deploy multi-station automated platforms with embedded compliance software. These facilities in the United States are consolidating sterile compounding into ISO Class 5 cleanrooms with continuous viable particle monitoring, responding to FDA guidance on hazardous drug handling.
- Ambulatory Surgery Centers:Freestanding facilities require compact, single-station compounders with rapid cycle times for same-day procedure support. ASCs in Texas, Florida, and California are expanding admixture capabilities as case migration from inpatient settings accelerates.
- Clinics:Physician-owned infusion centers with moderate throughput needs specify mid-tier automated systems.
- Homecare Providers:Mobile compounding services for parenteral nutrition demand portable, validated systems with simplified operator interfaces.
Hospital purchasing power dominates current revenue, though ambulatory sites are expanding fastest.
Technology:
Software-defined compliance is displacing hardware-centric specifications as the primary procurement criterion.
- Sterile Compounding Systems:Integrated platforms combining electromechanical precision with environmental controls and documentation automation. US facilities handling chemotherapy admixtures prioritize these systems to satisfy closed-system transfer device mandates under updated FDA sterile compounding guidance.
- Software Integration:Middleware connecting compounders to hospital information systems, electronic health records, and pharmacy management platforms enables real-time dose verification and lot tracking. European hospital pharmacies are specifying these modules to meet EMA traceability requirements for investigational medicinal products.
- Microbial Filtration:HEPA and sub-micron filtration assemblies maintaining ISO Class 5 conditions with 0.01 inches water column pressure differentials.
- IV Pumps:Precision peristaltic and syringe drive mechanisms for volumetric accuracy within five percent variance.
Sterile Compounding Systems command current premiums; Software Integration is climbing fastest as connectivity becomes mandatory.
Application:
Risk stratification and regulatory intensity create steep margin differentiation across therapeutic areas.
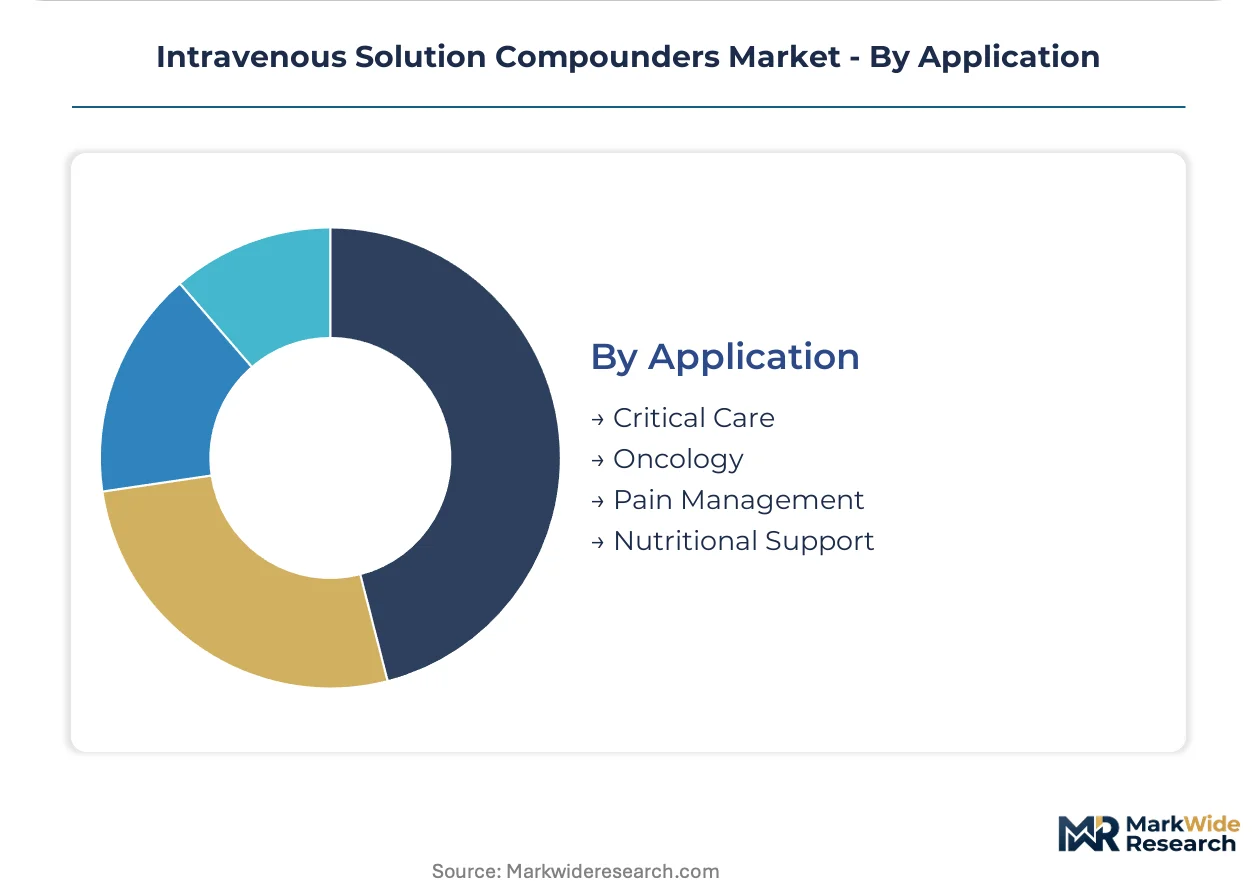
- Oncology:Cytotoxic admixture preparation demands containment engineering, decontamination protocols, and specialized operator training. Compounding facilities in the United States serving outpatient chemotherapy programs generate the highest per-unit margins due to FDA hazardous drug handling requirements and liability exposure.
- Critical Care:Time-sensitive admixtures for ICU settings require rapid-turnaround compounders with integrated quality verification. Hospital pharmacies in India expanding private health system infrastructure in Mumbai and Bangalore are prioritizing these capabilities as critical care bed capacity grows.
- Nutritional Support:Parenteral nutrition compounding for long-term care and home infusion settings.
- Pain Management:Controlled substance admixture preparation with diversion-prevention features and audit logging.
Oncology dominates premium positioning; Critical Care is expanding most quickly in emerging health system buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates automated compounding infrastructure within centralized 503B facilities, while Germany anchors European demand through specialized oncology hardware serving hospital pharmacy networks.
United States
Large health systems in Texas, Florida, and California are consolidating sterile compounding operations into ISO Class 5 cleanrooms with continuous particle monitoring. FDA's updated sterile compounding guidance mandates closed-system transfer devices for hazardous drug handling. The Mayo Clinic and Cleveland Clinic networks drive specification standards for multi-station automated platforms.
Germany
Outpatient infusion centers across Bavaria and North Rhine-Westphalia accelerate replacement cycles for cytotoxic-capable admixture systems. EMA's revised Annex 1 manufacturing requirements enforce continuous viable particle monitoring during aseptic processing. The Heidelberg and Munich hospital clusters prioritize integrated environmental sensors with automated alert protocols.
Switzerland
Swiss hospital pharmacies in Zurich and Basel specify premium admixture configurations with specialized containment engineering for oncology applications. Swissmedic applies stringent manufacturing requirements that exceed baseline EU standards. The Lausanne University Hospital cluster validates closed-system robotic compounding for sterile-to-patient workflows.
India
Private health system expansion in Mumbai, Delhi, and Bangalore generates procurement of entry-level automated compounders as facilities build ISO-compliant infrastructure. CDSCO guidance on sterile pharmaceutical manufacturing shapes equipment specifications for emerging hospital networks. The Apollo and Fortis hospital chains in Maharashtra and Karnataka prioritize critical care admixture capabilities.
Japan
Academic medical centers in Tokyo and Osaka deploy barcode-verified automated systems to eliminate calculation errors in chemotherapy preparation. PMDA enforcement of GMP standards for compounded sterile preparations determines device qualification criteria. The Keiyō industrial corridor hosts precision pump and peristaltic tubing suppliers serving regional equipment manufacturers.
Intravenous Solution Compounders Market Competitive Landscape
Top-tier vendors anchor hospital network service partnerships, while mid-tier specialists compete on regional compliance customization and entry-level automation for emerging health systems. The vendor base stratifies across three archetypes: diversified medical technology conglomerates leveraging installed infusion system bases, pure-play compounding specialists with oncology-focused engineering, and automation-integrated pharmacy workflow providers. Consolidation pressure intensifies through multi-year service contract bundling and software licensing attachment, while geographic expansion targets India's private hospital buildout and European Annex 1 compliance upgrades.
Within the diversified medical technology tier, Baxter International and Fresenius Kabi occupy positions shaped by captive distribution through hospital infusion system relationships. B. Braun exemplifies the integrated workflow archetype, with German engineering heritage visible in its corporate structure. These three anchors represent contrasting strategic positions: service agreement extension across installed bases, specialized hardware for cytotoxic applications, and sterile-to-patient workflow reduction.
| Leading Market Players |
|---|
| Baxter International |
| Fresenius Kabi |
| B. Braun |
| Omnicell |
| ICU Medical |
| Grifols |
| COMECER |
| Becton Dickinson |
| Fagron |
| Others |
Supply & Pricing Matrix
Closed-system robotic compounding architectures are compressing unit economics while simultaneously concentrating procurement leverage among large health systems with centralized 503B facilities. This dual transformation rewards vendors embedding compliance software into multi-year service agreements rather than transactional hardware sales.
Pricing Analysis
Capacity additions in India are reshaping price floors for entry-level automated compounders as Apollo and Fortis hospital chains expand ISO-compliant infrastructure. Pricing stratifies across premium configurations with integrated environmental monitoring, standard platforms with barcode verification, and economy gravity-assisted units for smaller 503A pharmacies. Price differentiation hinges on FDA 503B certification tier and after-sales service bundling. Cost compression in mid-tier hardware is intensifying because German and Swiss precision pump suppliers command single-source premiums.
Supply Chain Analysis
Freight costs for HEPA filtration housings and pressure-differential chambers from German suppliers add landed cost premiums that disadvantage mid-tier manufacturers without captive supply chains. Component manufacturing concentrates in Germany, Switzerland, and Japan, with precision peristaltic tubing and electromechanical pumps drawing from Keiyō corridor suppliers. Supply chain risk centers on single-source vulnerability for medical-grade polymers during trade disruptions. Distribution runs through hospital GPO contracts and direct OEM service partnerships with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between US reimbursement concentration favoring 503B-scale automation and India's infrastructure buildout rewarding entry-level platforms at lower regulatory compliance cost.
For Market Incumbents: Deploy outcome-based uptime guarantees to lock in multi-year service contracts across consolidating health systems. Baxter International and Fresenius Kabi anchor defensive positions through backward integration into precision pump manufacturing and software-defined compliance modules. Counter emerging automation-integrated pharmacy workflow providers by accelerating AI-powered predictive maintenance deployment. For New Entrants and Emerging Players: Begin with India's private hospital expansion in Maharashtra and Karnataka, where CDSCO guidance creates certification pathways without FDA 503B infrastructure requirements. Target ambulatory surgery centers in Texas and Florida with compact single-station compounders for same-day procedure support. Pursue white-label partnerships with third-party service providers to bypass direct GPO contract barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play compounding specialists with oncology-focused engineering but limited installed base service revenue. Long-term viability hinges on software attachment rates and recurring revenue mix rather than hardware shipment cycles. Watch FDA enforcement patterns on 503B outsourcing facility qualification as the inflection signal for centralized automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Mayo Clinic and Cleveland Clinic networks drive multi-station automated platform specifications across academic medical centers. |
| Software Companion Development | Middleware connecting compounders to Epic and Cerner EHR systems satisfies Joint Commission high-alert medication requirements. |
| CE Marking Pathway | EMA Annex 1 continuous particle monitoring mandates reshape European admixture system specifications differently than FDA guidance. |
| Reimbursement Strategy | US shift toward centralized 503B compounding creates white space for high-throughput automation serving multiple hospital networks. |
| Backward Integration | In-house production of peristaltic tubing reduces exposure to German and Swiss single-source supplier premiums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital pharmacy directors, biomedical engineers, GPO contracts managers, and sterile compounding technicians with secondary validation against FDA 503B facility registrations, EMA GMP inspection databases, hospital procurement records, and ISO cleanroom certification registries. Bottom-up equipment shipment modeling and top-down health system capital expenditure analysis provided triangulation checks.
Segment-weighting applied product type, end-user infrastructure tier, application risk profile, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from installed base expansion rates, replacement cycle compression, and reimbursement structure shifts. Forecast inputs incorporated Joint Commission accreditation requirements, EMA Annex 1 enforcement timelines, and private health system buildout patterns in India.
Several conditions sit outside the modeled scope, including potential FDA reclassification of 503B facility requirements, abrupt trade policy changes affecting German component sourcing, and pandemic-era supply chain disruptions. Forecasts reflect assumptions about regulatory enforcement continuity and health system consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Adenosine Market