
 Conduction Vaporizers Market | 2026-2036
Conduction Vaporizers Market Size, Share, and Industry Trends Forecast 2026-2036
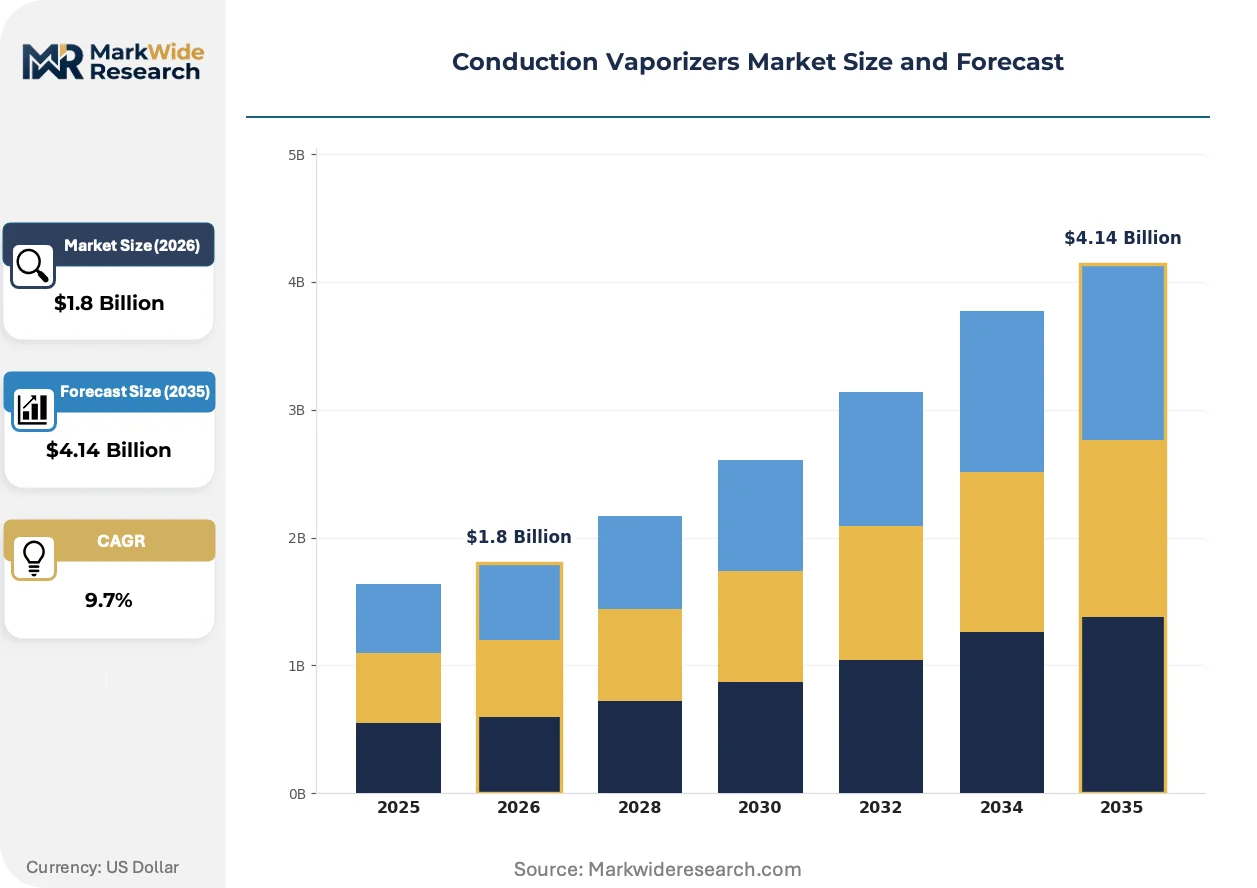
Conduction Vaporizers Market Outlook
Aftermarket accessory revenue is reconfiguring margin pools away from device sales toward replacement chambers, mouthpieces, and cleaning kits. PAX Labs leverages its proprietary pod ecosystem to sustain recurring revenue streams beyond initial hardware purchases. DaVinci Vaporizer anchors its position through precision temperature control technology that commands premium positioning. Storz & Bickel dominates the medical-grade desktop segment with German-engineered heating systems that meet stringent clinic standards.
Conduction vaporizers heat material through direct contact with a thermally conductive surface, typically reaching operating temperatures between 180°C and 220°C within 30-90 seconds via stainless steel, ceramic, or aluminum chambers. These devices serve both medical cannabis patients requiring consistent dosing and recreational consumers prioritizing rapid heat-up times. Portable vaporizers lead volume sales due to pocket-sized form factors and USB-C charging compatibility, while desktop units retain higher per-unit margins among medical users and connoisseur segments. Concentrates-compatible conduction devices represent the fastest-growing material-type configuration as wax and rosin formats expand beyond traditional flower-dominant markets.
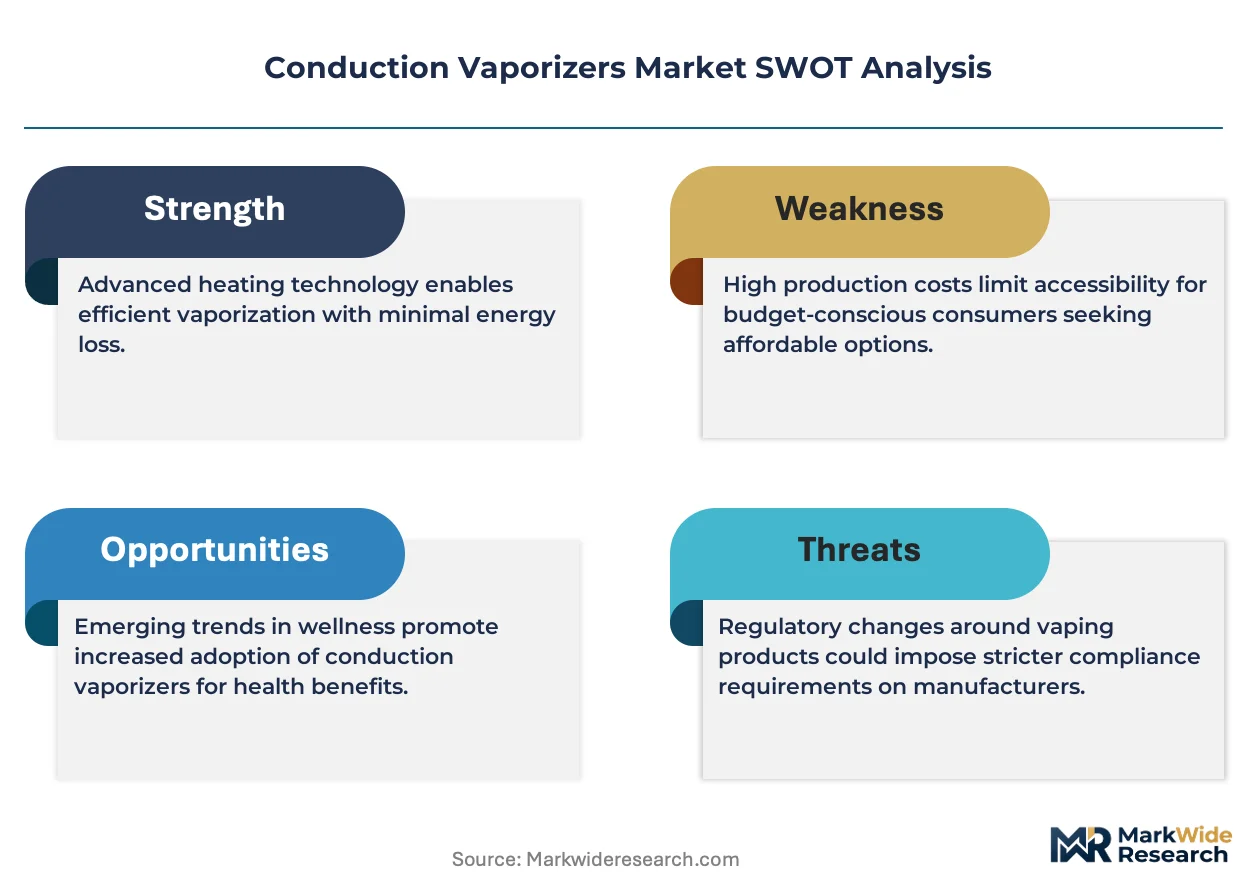
US FDA oversight of cannabis-adjacent marketing claims and EU REACH compliance for heating element materials create dual compliance burdens for manufacturers seeking transatlantic distribution. Germany's BfArM medical cannabis framework and Health Canada's Cannabis Act establish distinct product registration pathways that favor established players with regulatory affairs capacity. Stakeholders must monitor evolving state-level flavor restrictions and battery transportation rules that could disqualify entire product lines from key distribution channels.
Market Dynamics
Aftermarket accessory revenue is reconfiguring margin pools away from device sales toward replacement chambers, mouthpieces, and cleaning kits. Battery safety standards under EU REACH and US DOT regulations are forcing manufacturers to redesign heating systems and certification workflows.
Growth Catalysts
- Medical cannabis patient populations:Germany's BfArM framework and Health Canada's Cannabis Act are expanding reimbursement pathways for precision-dosed portable units prescribed through pharmacy channels.
- Concentrate-compatible hardware:Wax and rosin formats are displacing flower-dominant consumption patterns in California's regulated adult-use dispensary channel, driving hardware refresh cycles.
- USB-C charging standardization:Universal power compatibility is reducing manufacturer SKU complexity and enabling cross-border inventory pooling for portable form factors.
Market Restraints
- Lithium-ion cell supply concentration:Battery sourcing depends on a narrow supplier base in East Asian manufacturing clusters, exposing production schedules to raw material volatility and export control friction.
- Dual compliance burdens:US FDA oversight of cannabis-adjacent marketing claims and EU REACH heating element material rules create redundant testing requirements for transatlantic distribution.
- Desktop unit substitution:Medical-grade conduction desktops face displacement from convection and hybrid systems in clinic settings where odor control and extraction efficiency are prioritized.
Strategic Opportunities
- Australian medical cannabis expansion:TGA registration pathways for vaporizer hardware remain underdeveloped relative to patient growth, creating first-mover advantage for compliant device submissions.
- Subscription-based accessory replenishment:Automated chamber and mouthpiece replacement programs can capture recurring revenue streams independent of hardware replacement cycles.
- ISO 13485 medical device certification:Elevating quality management systems to medical-grade standards opens hospital and pain clinic procurement channels currently blocked to recreational-positioned brands.
Industry Challenges
- Thermal engineering talent scarcity:Precision temperature control firmware development requires specialized expertise in PID algorithm tuning and ceramic heating element characterization that sits outside traditional consumer electronics skill pools.
- State-level flavor restriction tracking:Dispensary operators in multiple US jurisdictions face inventory obsolescence risk from unpredictable additive prohibition timelines that lack federal preemption.
- Heating element material verification:Supply chain documentation for medical-grade ceramics and surgical stainless steel requires batch-level traceability systems that smaller contract manufacturers cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conduction Vaporizers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Vaporizers, Desktop Vaporizers, Hybrid Vaporizers, E-Nails End User: Individual Consumers, Medical Users, Recreational Users, Retail Distributors Material Type: Herbs, Concentrates, Oils, Blends Heating Technology: Convection, Conduction, Induction, Combined |
| Companies Covered | Storz & Bickel, PAX Labs, DaVinci Vaporizer, Arizer, Boundless Technology, Grenco Science, XMAX Vaporizers, Flowermate, Puffco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conduction Vaporizers Market Strategic Shifts
Smartphone-integrated dosing control is compressing the boundary between medical precision and recreational convenience. Manufacturers are racing to embed Bluetooth connectivity and session logging without triggering medical device classification triggers.
Silicon carbide heating chambers are virtualizing the thermal performance of medical-grade ceramic systems at consumer price points. Medical cannabis patients in Germany are adopting these units for consistent extraction profiles previously available only in clinic-grade desktops. The technology is virtualizing the premium positioning of German-engineered heating systems by democratizing precision temperature stability.
EU REACH substance restrictions on nickel and chromium compounds in heating elements are forcing material substitutions across the supply base. Manufacturers serving European distribution must validate alternative alloys and ceramic coatings through extended thermal cycling protocols. Portable concentrate-compatible devices face the steepest recertification timelines due to higher operating temperatures and accelerated material degradation.
Dispensary buyers are consolidating hardware procurement around multi-brand distributors who bundle vaporizers with complementary accessories and compliance documentation. California's regulated channel is consolidating shelf space around these bundled offerings, squeezing direct-to-retail relationships that smaller manufacturers previously maintained. The shift is most visible in Los Angeles and San Francisco metro clusters where inventory management complexity favors consolidated vendor relationships.
Conduction Vaporizers Market Segmentation
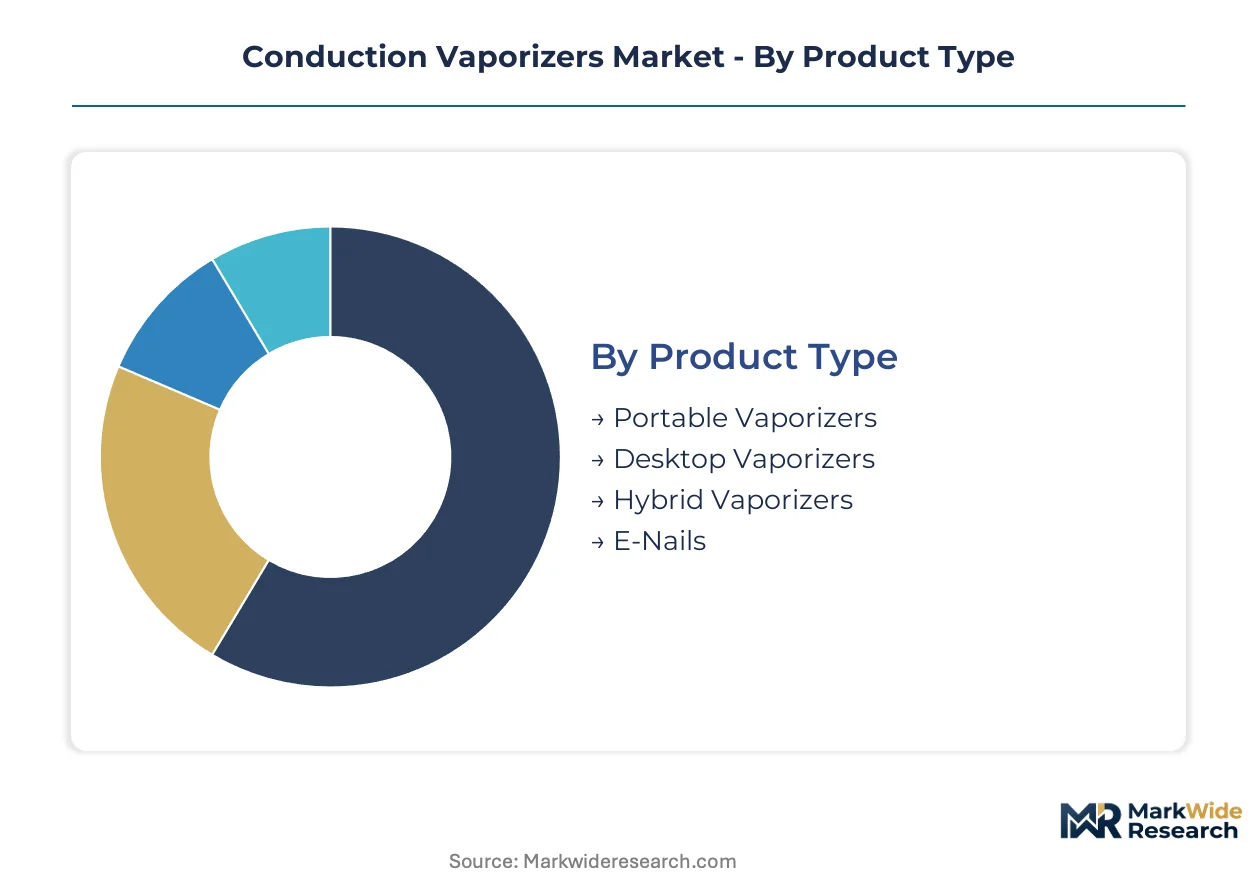
Conduction vaporizer manufacturers face divergent engineering requirements across portability, medical certification, and material compatibility. Segment boundaries determine which regulatory pathways apply and where margin pools concentrate most heavily.
Product Type:
Cost tier stratification separates pocket-sized units from clinic-grade systems with divergent BOM structures and certification burdens.
- Portable Vaporizers:Pocket-sized units with USB-C charging and ceramic or stainless steel chambers dominate California dispensary shelf space. German medical cannabis patients drive demand for precision-dosed portable units through pharmacy reimbursement channels.
- Desktop Vaporizers:Stationary units with medical-grade heating systems command premium positioning in pain clinics where extraction consistency outweighs portability. Storz & Bickel's German-engineered systems anchor this tier through ISO 13485-aligned quality management.
- Hybrid Vaporizers:Dual-mode units combining conduction speed with convection flavor preservation target connoisseur segments in Los Angeles and San Francisco metro clusters.
- E-Nails:Concentrate-specific heating attachments serve dab rig users in Colorado's regulated adult-use market with rapid temperature ramping capabilities.
Portable vaporizers hold installed capacity. Hybrid vaporizers are rotating up the share rankings.
End User:
Application context determines whether devices require medical device classification or recreational positioning.
- Individual Consumers:Personal-use buyers prioritize rapid heat-up times and smartphone connectivity for session logging without clinical oversight.
- Medical Users:Patients under Germany's BfArM framework and Health Canada's Cannabis Act require batch-level traceability and precision temperature stability for consistent dosing.
- Recreational Users:California's regulated adult-use channel concentrates demand for concentrate-compatible hardware with minimal learning curves.
- Retail Distributors:Multi-brand bundlers in Los Angeles and San Francisco consolidate procurement around vendors supplying compliance documentation alongside hardware.
Medical users anchor premium tier margins. Recreational users are expanding volume fastest through dispensary channel consolidation.
Material Type:
Customer type preferences are displacing flower-dominant consumption patterns across key distribution channels.
- Herbs:Traditional dried flower vaporization retains volume leadership among medical patients requiring whole-plant cannabinoid profiles with predictable extraction curves.
- Concentrates:Wax and rosin formats are climbing fastest in California's regulated channel, forcing hardware refresh cycles toward higher-temperature chambers with accelerated material degradation profiles.
- Oils:Pre-filled cartridge systems compete with conduction devices in convenience-oriented segments though temperature control limitations restrict medical adoption.
- Blends:Multi-material chambers accommodating both flower and concentrate serve experimental users seeking format flexibility without dedicated hardware investments.
Herb-compatible devices hold installed base concentration. Concentrate configurations are gaining share fastest through dispensary channel displacement.
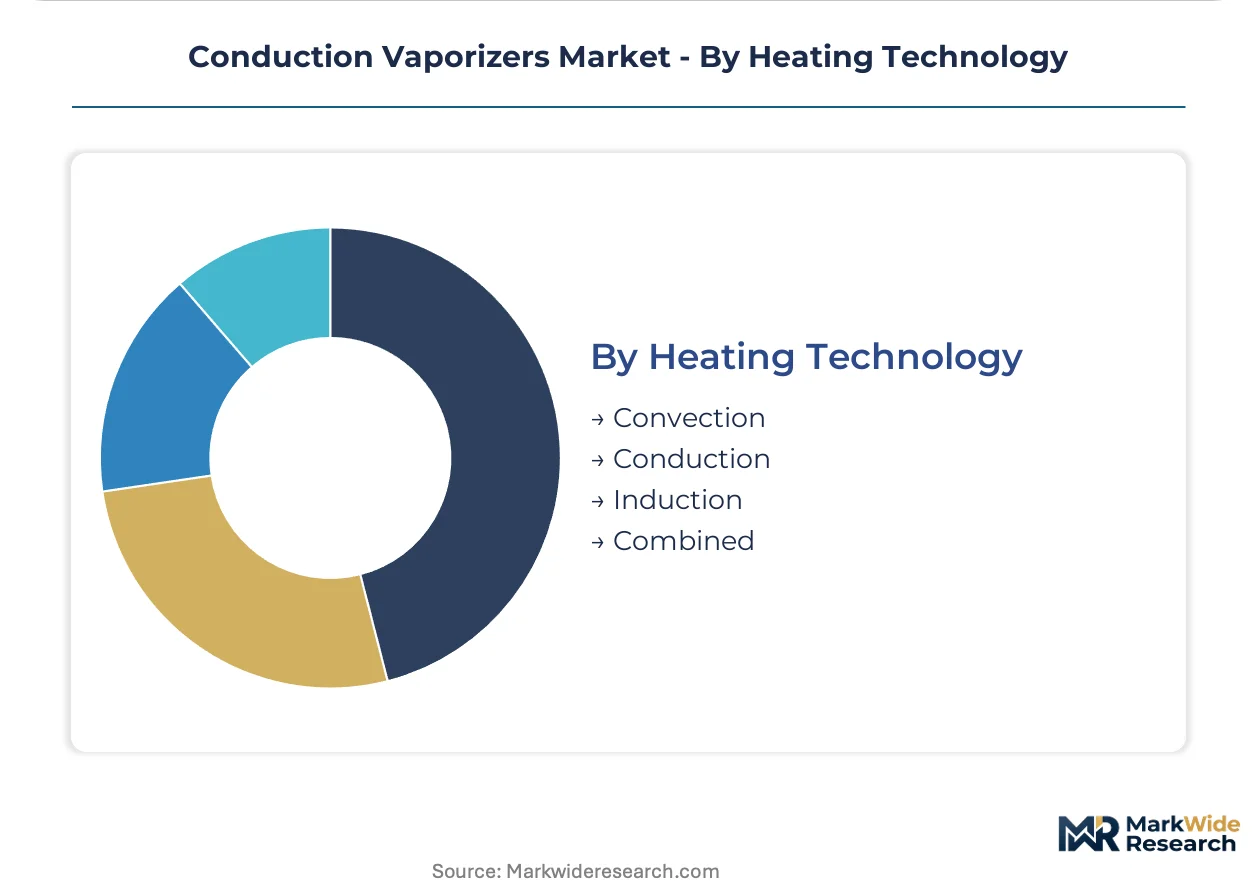
Heating Technology:
Margin concentration follows certification complexity and thermal engineering talent scarcity.
- Convection:Hot air circulation systems dominate medical clinic settings where odor control and extraction efficiency outweigh heat-up speed considerations.
- Conduction:Direct contact heating through ceramic or stainless steel chambers serves the core addressable market with 30-90 second temperature ramping and simpler firmware requirements.
- Induction:Electromagnetic heating eliminates chamber degradation but requires specialized coil engineering sitting outside traditional consumer electronics skill pools.
- Combined:Hybrid systems merging conduction speed with convection quality command premium positioning among connoisseur segments in San Francisco and Los Angeles clusters.
Conduction systems hold manufacturing scale. Combined technology variants are rotating up the premium tier rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across jurisdictions. German medical patients absorb premium pricing for certified hardware, while California recreational buyers prioritize value-tier concentrate compatibility. Australia's emerging medical channel sits between these poles.
United States
California's regulated adult-use dispensary channel concentrates shelf space for concentrate-compatible hardware. FDA oversight of cannabis-adjacent marketing claims forces redundant testing workflows for transatlantic distribution. Los Angeles and San Francisco metro clusters favor bundled procurement from multi-brand distributors.
Germany
BfArM medical cannabis framework expands reimbursement pathways for precision-dosed portable units through pharmacy channels. EU REACH substance restrictions on nickel and chromium compounds force material substitutions across heating element supply chains. Berlin and Hamburg anchor demand for ISO 13485-aligned clinic-grade desktop systems.
Canada
Health Canada's Cannabis Act establishes distinct product registration pathways favoring established players with regulatory affairs capacity. Provincial distribution monopolies concentrate procurement decisions in Ontario and British Columbia. Vancouver and Toronto metro areas drive concentrate-compatible portable adoption among dual-status medical-recreational users.
Australia
TGA registration pathways for vaporizer hardware remain underdeveloped relative to patient growth, creating first-mover advantage for compliant device submissions. Therapeutic Goods Administration batch-level traceability requirements mirror German standards. Sydney and Melbourne medical cannabis clinics drive demand for precision temperature stability.
Switzerland
Swissmedic oversight of medical device classification creates a compliance bridge between EU and non-EU regulatory frameworks. Zurich and Geneva pain clinics source German-engineered heating systems for extraction consistency. The country's pharmaceutical manufacturing base supplies precision temperature control components to adjacent markets.
Conduction Vaporizers Market Competitive Environment
Capability concentration sits with German-engineered medical-grade specialists; scale advantage sits with California-positioned recreational hardware platforms. The vendor base stratifies across three tiers: clinic-certified desktop manufacturers, pod-ecosystem platform operators, and contract-manufactured value-tier portables. Strategic archetypes include medical-device-certified specialists, proprietary-ecosystem platform builders, and white-label volume suppliers. Competitive moves center on ISO 13485 certification acquisition and subscription-based accessory replenishment programs.
Within the medical-device-certified tier, Storz & Bickel GmbH anchors German-engineered positioning. Among pod-ecosystem operators, PAX Labs Inc. exemplifies proprietary platform architecture. DaVinci Vaporizer occupies a position in precision temperature control specialization. These three entities represent divergent capability investments: clinical certification, recurring revenue infrastructure, and firmware differentiation.
| Leading Market Players |
|---|
| Storz & Bickel |
| PAX Labs |
| DaVinci Vaporizer |
| Arizer |
| Boundless Technology |
| Grenco Science |
| XMAX Vaporizers |
| Flowermate |
| Puffco |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Los Angeles container freight corridors transmit East Asian battery cell cost volatility directly into California dispensary shelf pricing, amplifying margin compression for portable unit manufacturers while enabling premium-tier German desktop systems to sustain certification-based price separation.
Pricing Analysis
Aftermarket accessory replenishment drives lifetime value capture beyond initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical units from recreational-positioned portables and white-label value alternatives. Cost compression in the standard tier intensifies because concentrate-compatible chamber degradation accelerates replacement frequency. Medical users under Germany's BfArM framework exhibit lowest price sensitivity; California recreational buyers prioritize value-tier concentrate compatibility above certification premiums.
Supply Chain Analysis
Lithium-ion cell feedstock from China, South Korea, and Japan anchors production cost structures for portable conduction devices. Ceramic heating element supply draws from German and Swiss precision manufacturing clusters, while surgical-grade stainless steel chambers source from Italian and Japanese metalworking specialists. Single-source vulnerability concentrates in East Asian battery cell supply, exposing production schedules to export control friction. Distribution runs through multi-brand bundlers in Los Angeles and San Francisco metro clusters who consolidate compliance documentation alongside hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conduction vaporizer incumbents face substitution defense against smartphone-integrated dosing platforms and convection-hybrid systems that threaten to displace direct-contact heating in premium segments.
For Market Incumbents: Pre-empt pod-ecosystem competitors by embedding proprietary chamber architectures that lock users into recurring accessory purchases. Acquire ISO 13485 certification capacity to defend clinic-grade positioning against German-engineered specialists. Deepen backward integration into ceramic heating element production to insulate margin structures from EU REACH material substitution costs.
For New Entrants and Emerging Players: Australia's TGA registration gap offers white-space entry before established players complete compliant device submissions. Target Sydney and Melbourne medical cannabis clinics with precision temperature stability specifications that match German BfArM standards. Pursue white-label manufacturing partnerships with Shenzhen-based electronics assemblers to compress time-to-market for concentrate-compatible portables.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors medical-device-certified specialists with recurring revenue infrastructure over hardware-only volume suppliers. Long-term viability hinges on subscription-based accessory replenishment programs that decouple revenue from replacement cycles. Monitor silicon carbide heating chamber adoption rates as inflection indicator for premium positioning democratization.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acquisition | Opens hospital and pain clinic procurement channels blocked to recreational brands. |
| Subscription-Based Accessory Replenishment | Captures recurring revenue independent of hardware replacement cycles. |
| Silicon Carbide Chamber Integration | Democratizes medical-grade thermal stability at consumer price points. |
| TGA Registration Submission | Secures first-mover advantage in Australia's underdeveloped medical hardware pathway. |
| EU REACH Compliance Documentation | Enables transatlantic distribution without redundant testing workflows. |
Study Parameters
Operator-level perspectives from dispensary procurement managers, medical cannabis clinic directors, ceramic heating element suppliers, and regulatory affairs specialists anchored the qualitative base. Primary interview data combined with secondary validation from Health Canada device registration databases, BfArM pharmacy reimbursement records, EU REACH substance restriction filings, and California Bureau of Cannabis Control distribution reports. Bottom-up unit volume estimates triangulated against top-down addressable market calculations across portable, desktop, and hybrid form factors.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, end user category, material compatibility, and heating technology architecture. CAGRs derived from fitted growth curves applied to patient population expansion, dispensary channel consolidation rates, and hardware refresh cycle acceleration. Industry-specific forecast inputs incorporated EU REACH recertification timelines and TGA registration pathway development.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pod-ecosystem platform builders or convection-hybrid technology specialists would shift outcomes beyond modeled ranges. Cross-checking against Health Canada and BfArM device approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Osmotic Pumps Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Baby Thermometer Market
Medical Devices
Auto-Transfusion Systems Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
AI-enabled Medical Devices Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Laser Resurfacing Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Pancreatic and Biliary Stents Market