
 Ambulatory Software Market | 2026-2036
Ambulatory Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ambulatory Software Market Analysis
Direct sales channels for enterprise ambulatory suites is tilting toward subscription and cloud-hosted arrangements, reducing upfront capital barriers for mid-sized physician practices. Epic Systems Corporation leverages its deep interoperability infrastructure to anchor academic and large-group ambulatory networks. Oracle Health sustains competitive pressure through database-centric integration with hospital ERP ecosystems. eClinicalWorks specializes in serving smaller practices with bundled EHR-practice management offerings that lower total cost of ownership.
Ambulatory software encompasses clinical, administrative, and financial applications designed for outpatient care settings, typically operating on cloud-native architectures with HL7 FHIR-compliant data exchange protocols to enable real-time patient record portability across unaffiliated providers. EHR and practice management modules occupy the core revenue pool, though telemedicine represents the fastest-expanding segment as synchronous virtual visit platforms embed into standard outpatient workflows. Cloud-based deployment leads volume uptake among new buyers, while hybrid configurations persist in larger multi-site clinics managing legacy data sovereignty requirements.
FDA oversight of clinical decision support modules, HIPAA security rule enforcement by HHS, and ONC interoperability certification requirements collectively elevate compliance costs while filtering non-compliant vendors from federal reimbursement eligibility. The 21st Century Cures Act information blocking provisions are forcing ambulatory software suppliers to open APIs or risk exclusion from provider shortlists. Stakeholders must monitor how CMS value-based payment models reshape feature requirements before committing to multi-year platform contracts.
Market Dynamics
Federal interoperability mandates and value-based reimbursement models are compressing replacement cycles for legacy on-premises systems across outpatient networks, forcing vendors to accelerate cloud-native platform development.
Growth Catalysts
- ONC Certification Requirements:The 21st Century Cures Act information blocking provisions compel ambulatory software suppliers to open APIs, disqualifying non-compliant vendors from federal reimbursement eligibility and redirecting procurement toward certified platforms.
- Specialty Clinic Expansion:Dermatology, orthopedics, and gastroenterology practices are automating revenue-cycle workflows to manage higher patient volumes with leaner administrative staff.
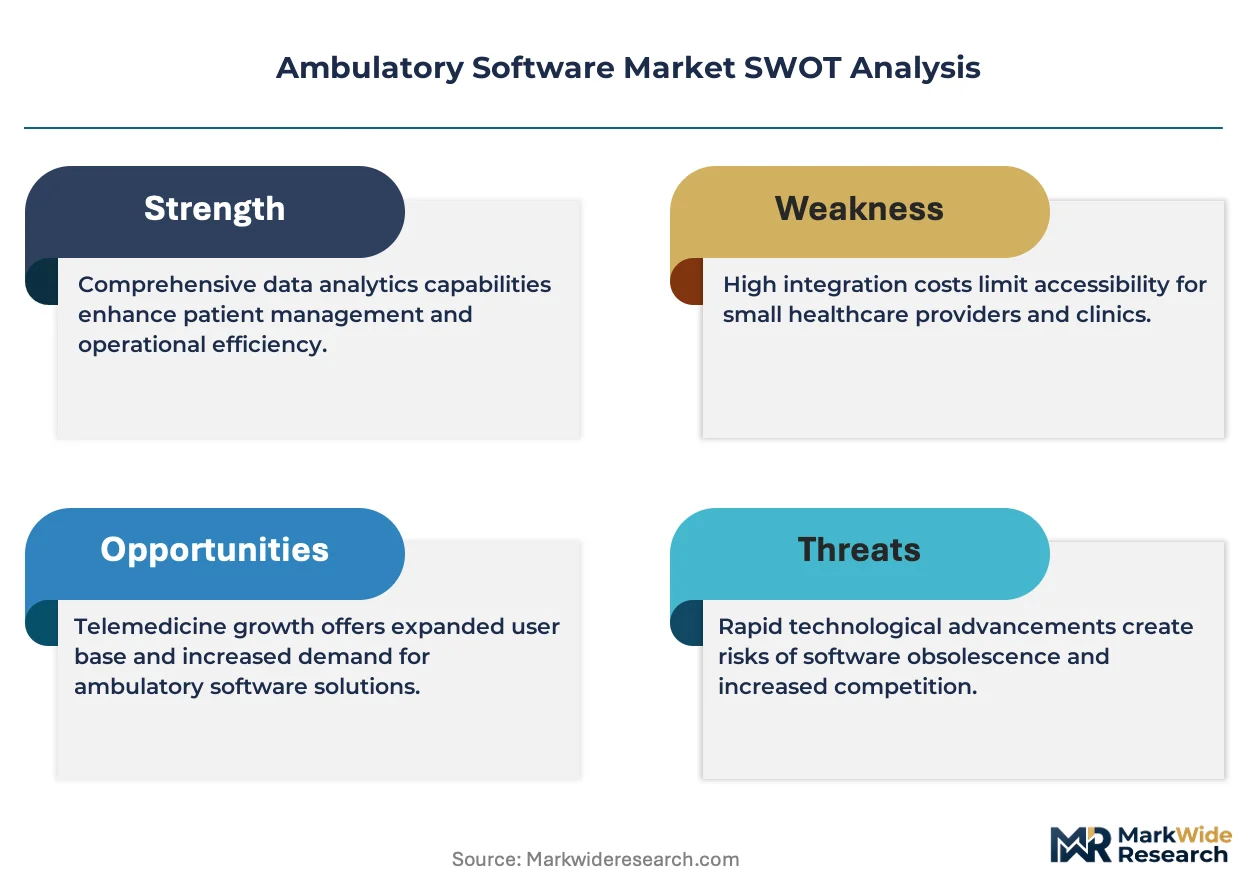
- Telemedicine Platform Embedding:Synchronous virtual visit modules are becoming standard features within outpatient EHR suites rather than standalone purchases, expanding addressable market scope.
Market Restraints
- HIPAA Security Rule Compliance:HHS enforcement of encryption, access control, and audit logging requirements elevates development and operational costs disproportionately for smaller software vendors.
- Technical Debt Burden:Multi-site clinics managing hybrid cloud-on-premises configurations face complex data sovereignty requirements that slow migration timelines.
- Substitution Risk from Hospital-Owned Platforms:Health system acquisition of independent practices transfers patients onto enterprise EHR instances, eroding standalone ambulatory software demand.
Strategic Opportunities
- Underpenetrated Rural Markets:Federally Qualified Health Centers in underserved regions lack capital for enterprise suites, creating white space for subscription-based, lightweight practice management tools.
- AI-Enabled Clinical Decision Support:Machine learning integration with diagnostic workflows offers differentiation for vendors targeting high-acuity specialty segments.
- CMS Alternative Payment Models:Medicare Shared Savings Program and bundled payment pilots reward care coordination capabilities, reshaping feature prioritization for population health modules.
Industry Challenges
- Interoperability Engineer Scarcity:HL7 FHIR implementation expertise commands premium compensation, constraining vendor scaling velocity.
- Legacy System Integration Complexity:Data migration from decades-old practice management databases risks patient record fragmentation during platform transitions.
- FDA Software-as-Medical-Device Classification:Clinical decision support modules with diagnostic recommendations face evolving regulatory boundaries, creating compliance uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambulatory Software Market |
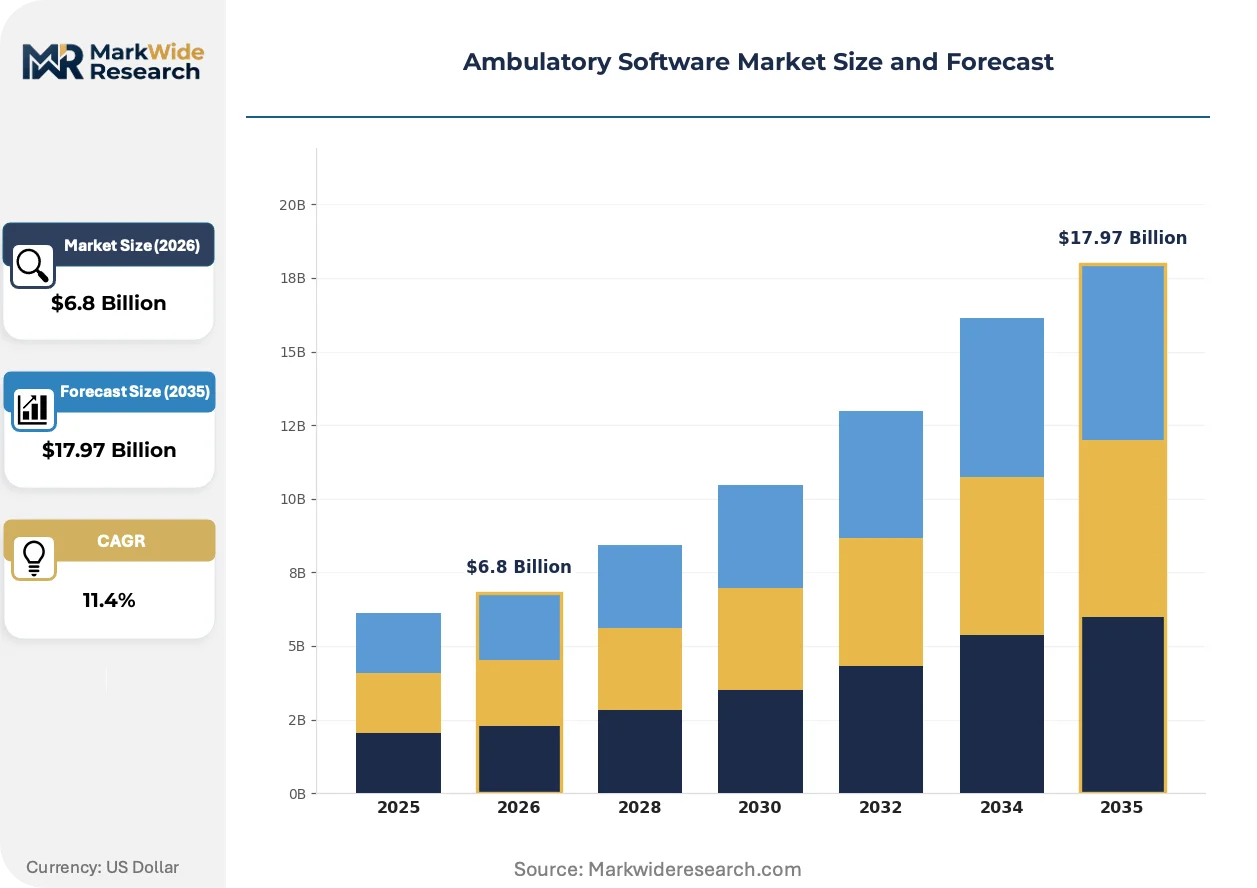
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EHR, Practice Management, Telemedicine, Billing Solutions Deployment: Cloud-based, On-premises, Hybrid, Mobile End User: Physician Practices, Outpatient Clinics, Urgent Care Centers, Specialty Clinics Integration Level: Interoperable, Standalone, Custom API, Third-party Compatible |
| Companies Covered | Epic Systems Corporation, Oracle Health, eClinicalWorks, athenahealth, NextGen Healthcare, Veradigm, AdvancedMD, Medical Information Technology, TruBridge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambulatory Software Market Emerging Trajectories
Cloud-native architectures are displacing monolithic on-premises deployments as the default infrastructure choice, while regulatory pressure on data portability accelerates API standardization across vendor ecosystems.
Artificial intelligence is digitizing clinical documentation workflows through ambient listening and automated coding suggestion engines. Primary care networks and high-volume specialty groups are piloting these tools to reduce physician administrative burden. The technology is compressing documentation time per encounter, enabling practices to expand patient panel sizes without proportional staffing increases.
HHS enforcement of the 21st Century Cures Act information blocking rule is mandating standardized API access for patient data exchange. This policy is fragmenting competitive moats previously built on proprietary data formats. Ambulatory EHR vendors serving multi-state provider groups face the most acute compliance pressure, as these networks span jurisdictions with varying state-level privacy supplements.
Subscription pricing is displacing perpetual license arrangements as the dominant commercial model for mid-sized physician practices. Vendors are unbundling implementation and training services from core platform fees, while buyers in competitive metropolitan markets negotiate shorter initial contract terms. This shift is most visible in the southwestern United States, where private equity-backed practice rollups prioritize operational flexibility over long-term capital commitments.
Ambulatory Software Market Segmentation
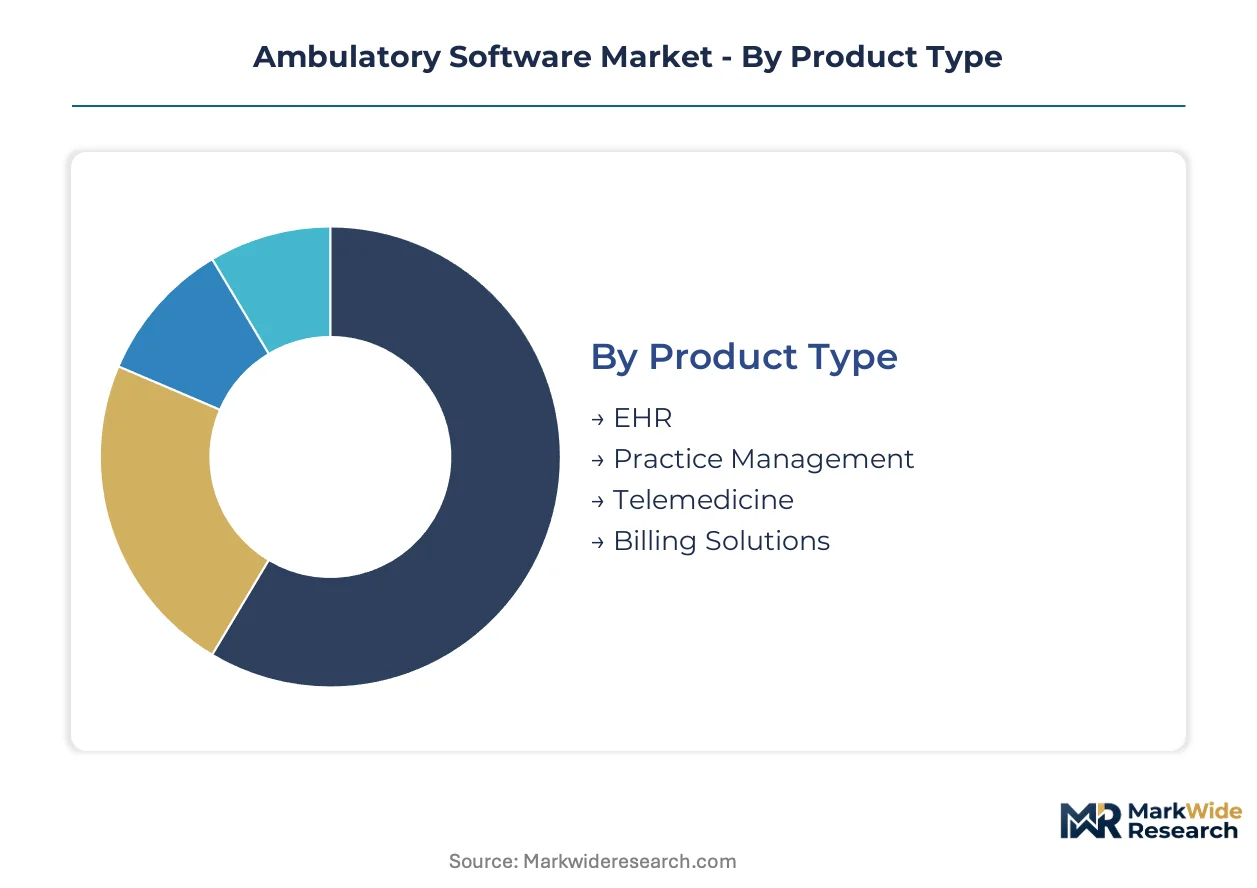
Ambulatory software procurement patterns diverge sharply across practice size, technical maturity, and regulatory exposure. Segmentation reveals how vendor portfolios must stratify to capture revenue-cycle automation demand from independent physician groups versus enterprise outpatient networks.
Product Type:
Mature EHR suites anchor procurement budgets while emerging telemedicine modules reshape feature roadmaps across vendor ecosystems.
- EHR:Core clinical documentation platforms with CPOE, e-prescribing, and patient portal functionality dominate capital allocation for mid-sized practices. Demand concentrates in multi-specialty physician groups across Texas and Florida seeking ONC certification for federal reimbursement eligibility.
- Practice Management:Scheduling, registration, and workflow orchestration tools integrate tightly with revenue-cycle operations. Urgent care chains in Arizona and Colorado prioritize these modules to manage high patient throughput with lean administrative staffing.
- Telemedicine:Synchronous virtual visit platforms with embedded billing capture.
- Billing Solutions:Claims scrubbing and denial management automation for specialty reimbursement complexity.
EHR handles the majority of throughput; Telemedicine is expanding most quickly on share as virtual visits embed into standard outpatient workflows.
Deployment:
Cost tier stratification separates capital-constrained buyers from enterprises managing legacy data sovereignty obligations.
- Cloud-based:Multi-tenant SaaS architectures with automatic updates and HIPAA-compliant hosting eliminate upfront infrastructure investment. New buyer uptake concentrates among independent practices in competitive metropolitan markets negotiating subscription terms under five years.
- On-premises:Client-server installations retaining physical data control for legacy compliance frameworks. Large multi-site clinics in California and New York maintain these configurations to satisfy state-level privacy supplements beyond federal HIPAA requirements.
- Hybrid:Split architectures with cloud-native front-ends and on-premises data repositories.
- Mobile:Native iOS and Android applications for point-of-care documentation.
Cloud-based deployment captures the volume lead among new implementations; Hybrid configurations persist where data residency requirements fragment across state jurisdictions.
End User:
Customer type determines feature prioritization, with specialty workflows demanding diagnostic content libraries distinct from primary care templates.
- Physician Practices:Small to mid-sized independent groups with 2-50 providers requiring integrated EHR-practice management bundles. Procurement in the southeastern United States favors vendors offering rapid implementation timelines to minimize revenue disruption during platform transitions.
- Outpatient Clinics:Hospital-affiliated ambulatory departments operating on enterprise EHR instances with custom outpatient modules.
- Urgent Care Centers:High-volume retail health settings with walk-in scheduling and episodic billing workflows.
- Specialty Clinics:Dermatology, orthopedics, and gastroenterology practices with procedure-heavy documentation requirements. These groups in Illinois and Ohio automate revenue-cycle workflows to manage patient volume expansion without proportional administrative hiring.
Physician Practices represent the deepest installed base; Specialty Clinics are climbing the fastest as procedure automation demand intensifies.
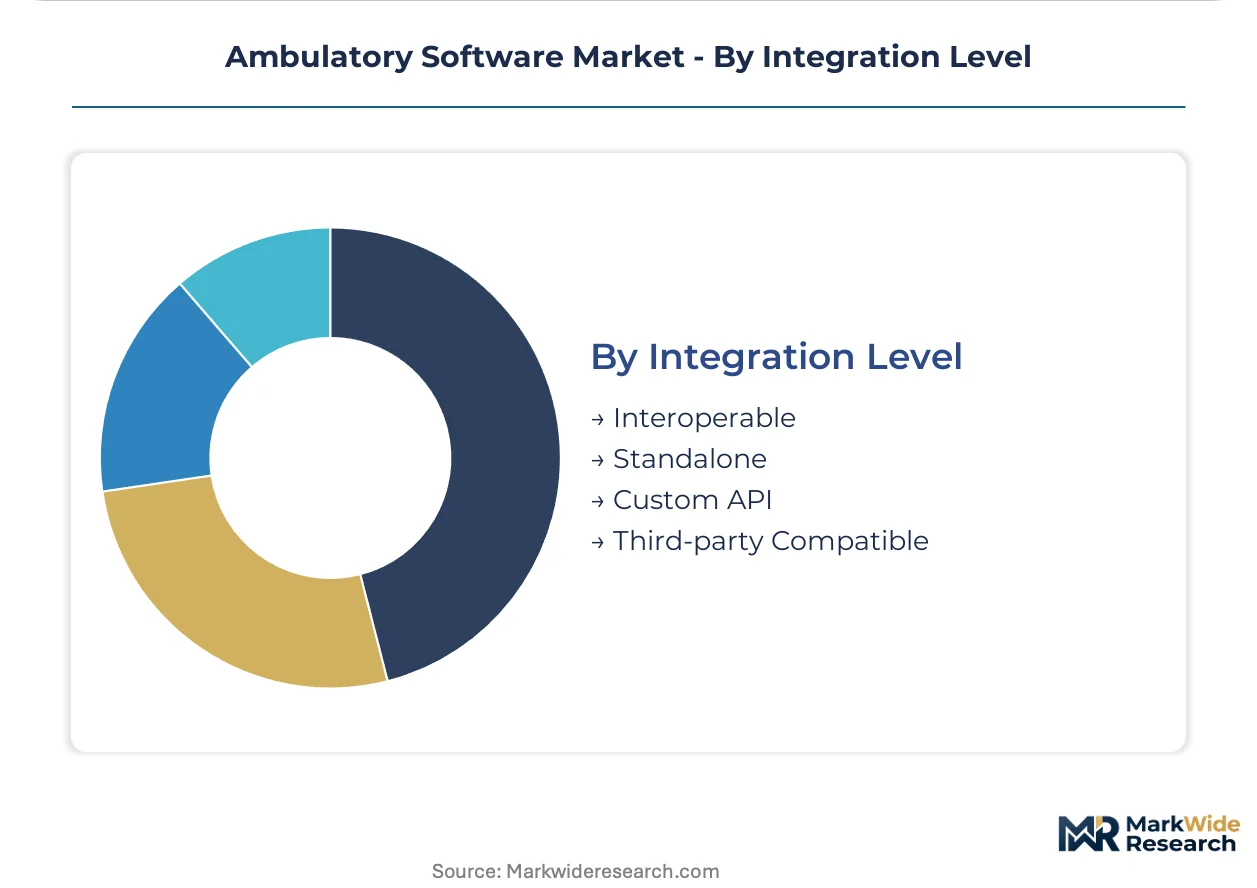
Integration Level:
Margin pressure from interoperability engineering scarcity forces vendors to tier API access and certification investment.
- Interoperable:HL7 FHIR-native platforms with real-time data exchange across unaffiliated provider networks. Academic medical centers and large-group networks in Massachusetts and Pennsylvania mandate these capabilities for care coordination across acquired practice portfolios.
- Standalone:Closed-system deployments without external data exchange functionality.
- Custom API:Bespoke integration interfaces for health system-specific workflow requirements.
- Third-party Compatible:Pre-built connectors to laboratory, imaging, and pharmacy networks. These configurations satisfy smaller practices seeking plug-and-play connectivity without dedicated integration engineering resources.
Interoperable platforms command premium positioning; Third-party Compatible solutions address the mid-market segment seeking connectivity without custom development burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates sharply in the United States, where federal interoperability mandates and value-based reimbursement models command premium software valuations, while adoption in India and Southeast Asia advances through cost-optimized cloud deployments without comparable regulatory leverage.
United States
Federal interoperability rules and HIPAA compliance mandates accelerate replacement cycles for legacy on-premises systems across outpatient networks. ONC certification requirements under the 21st Century Cures Act disqualify non-compliant vendors from Medicare reimbursement eligibility. Texas and Florida physician groups concentrate procurement demand for multi-specialty EHR suites with embedded revenue-cycle automation.
Germany
GDPR-compliant cloud architectures and the EU AI Act reshape vendor qualification criteria for ambulatory software procurement. Germany's national digital health strategy accelerates EHR adoption among independent physician practices previously reliant on paper records. Bavarian and North Rhine-Westphalian clinic networks pilot FHIR-native platforms for cross-border patient data exchange with neighboring EU member states.
United Kingdom
NHS England's digitization targets drive consolidation onto standardized ambulatory platforms across primary care networks. The country's national interoperability framework mandates API accessibility for patient record portability between unaffiliated providers. Greater London and Manchester health systems concentrate demand for cloud-hosted practice management tools serving acquired practice portfolios.
India
Cost-optimized subscription models penetrate tier-2 and tier-3 cities where capital-constrained physician practices previously avoided enterprise software investments. The country's national digital health mission establishes foundational ID infrastructure enabling interoperable patient records across state boundaries. Karnataka and Maharashtra telemedicine clusters embed virtual visit modules into standard outpatient workflows for urban specialist consultations.
Japan
Aging demographics and physician workforce shortages automate administrative workflows through AI-enabled documentation tools in Tokyo and Osaka metropolitan clinics. PMDA oversight of clinical decision support modules creates compliance complexity for foreign software vendors seeking market entry. Kansai region specialty practices concentrate demand for procedure-heavy documentation systems serving orthopedic and gastroenterology patient volumes.
Ambulatory Software Market Vendor Landscape
Enterprise-scale integrators and mid-market bundlers split the market into distinct competitive spheres with limited overlap in customer targeting. Consolidation pressure intensifies as health system acquisition of independent practices transfers patients onto hospital-owned EHR instances. Three archetypes dominate: academic medical center anchors, private equity-backed practice roll-up specialists, and lightweight subscription providers for rural markets. M&A activity and cloud-native platform development represent the dominant competitive moves as vendors race to satisfy federal interoperability deadlines.
Among enterprise-scale platforms, Epic Systems Corporation anchors academic and large-group ambulatory networks through deep interoperability infrastructure, while Oracle Health sustains competitive pressure through database-centric integration with hospital ERP ecosystems. eClinicalWorks occupies a distinct position serving smaller practices with bundled EHR-practice management offerings that reduce total cost of ownership. These three exemplify how vendor archetypes align with buyer segmentation across practice size and technical maturity tiers.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| eClinicalWorks |
| athenahealth |
| NextGen Healthcare |
| Veradigm |
| AdvancedMD |
| Medical Information Technology |
| TruBridge |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure concentration in the United States anchors margin capture for SaaS-native ambulatory vendors, while on-premises legacy providers absorb higher operational overhead from data center maintenance and compliance engineering. This upstream divergence shapes where pricing power accumulates across deployment archetypes.
Pricing Analysis
The customization-premium spread separates configured-to-order enterprise implementations from standardized SaaS tiers. Subscription pricing dominates new buyer uptake, with differentiation driven by ONC certification grade and integration complexity. Pricing pressure stems from health system acquisition of independent practices, which transfers volume onto hospital-owned EHR instances and erodes standalone vendor negotiating leverage. Federally Qualified Health Centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize interoperability capabilities over cost.
Supply Chain Analysis
Tariff exposure between the United States and China for semiconductor components creates vulnerability in server hardware procurement for on-premises deployments. Cloud-native architectures draw from hyperscaler infrastructure concentrated in the United States, Ireland, and Singapore, reducing physical hardware dependency. Single-source vulnerability persists in specialized HL7 FHIR engineering talent pools. Distribution runs through direct sales teams for enterprise accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ambulatory software market sits in early-cycle expansion as specialty clinic automation demand outpaces legacy system replacement saturation, with federal interoperability mandates sustaining procurement velocity across outpatient networks.
For Market Incumbents: Harden API infrastructure against information blocking compliance deadlines while accelerating cloud-native platform development to defend against hospital-owned platform substitution. Invest in FHIR engineering capacity through acquisition of specialized integration firms, as talent scarcity constrains scaling velocity for competitors.
For New Entrants and Emerging Players: Build out lightweight subscription offerings targeting rural Federally Qualified Health Centers where enterprise suites prove cost-prohibitive. Prioritize AI-enabled clinical decision support modules for high-acuity specialty segments seeking diagnostic workflow differentiation. Deploy through regional channel partners to minimize direct sales overhead in dispersed markets.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native platforms with established ONC certification and specialty clinic customer bases, as these assets capture the fastest-expanding end-use segment. Monitor CMS value-based payment model expansion as the inflection signal reshaping feature requirements and vendor selection criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR-native architectures satisfy ONC certification requirements for federal reimbursement eligibility. |
| Acquisition of Specialist Firm | Vertical integration of AI-enabled clinical decision support targets high-acuity specialty documentation workflows. |
| Geographic Expansion | Cloud-hosted deployments penetrate tier-2 and tier-3 Indian cities through cost-optimized subscription models. |
| Strategic Partnership | Health system alliances defend against hospital-owned platform substitution eroding standalone demand. |
| Product Launch | Ambient listening documentation tools reduce physician administrative burden in primary care networks. |
Methodological Framework
A standing panel of ambulatory EHR product directors, health system CIOs, specialty clinic practice administrators, and HL7 integration engineers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against ONC certification databases, CMS Medicare reimbursement filings, and hospital procurement contract disclosures. Bottom-up sizing of vendor-installed bases triangulated with top-down assessment of outpatient provider addressable markets.
Scenario-bracketing framed demand projections across deployment model, practice size tier, specialty vertical, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends and federal policy implementation timelines. Model inputs incorporated cloud infrastructure cost curves, interoperability engineering wage inflation, and health system acquisition velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed entrants or accelerated hospital consolidation would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
Medical Saas System Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Global Clinical EHR Systems Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
Global Computerized Physician Order Entry Market