
 Post-Marketing Pharmacovigilance and Medical Information Market | 2026-2036
Post-Marketing Pharmacovigilance and Medical Information Market Size, Share, and Industry Trends Forecast 2026-2036
Post-Marketing Pharmacovigilance and Medical Information Market Intelligence
The shift from fully in-house pharmacovigilance departments toward hybrid outsourcing arrangements is rebalancing how pharmaceutical companies manage post-marketing safety obligations. IQVIA Inc leverages its global real-world data networks to anchor multi-country signal detection programs for large sponsors. Parexel International Corporation sustains specialized risk management capabilities that differentiate its offerings in oncology and rare disease portfolios. Cognizant Technology Solutions Corporation competes through technology-led delivery models that integrate artificial intelligence into case processing workflows.
Post-marketing pharmacovigilance and medical information encompasses the systematic collection, analysis, and communication of adverse event data and product inquiries after regulatory approval, operating through structured case intake systems, MedDRA-coded terminology, and periodic safety update report cycles to protect patient populations and satisfy regulatory obligations. The service type dimension shows signal detection and risk management commanding premium pricing due to specialized expertise scarcity, while compliance management represents a mature, volume-driven segment with thinner margins. Artificial intelligence within the technology segment is attracting disproportionate investment as sponsors seek automated case triage and predictive signal generation, though cloud computing underpins most new delivery infrastructure.
The FDA, EMA, and WHO collectively shape market demand through evolving guidance on real-world evidence integration, accelerated safety reporting timelines, and international harmonization of ICH E2B(R3) electronic transmission standards. These frameworks directly determine staffing levels, technology procurement priorities, and geographic placement of pharmacovigilance operations centers. Stakeholders must monitor how the FDA's Sentinel Active Risk Identification System and EMA's DARWIN EU network reshape competitive requirements for data access and analytical capabilities.
Market Dynamics
The FDA's Sentinel Initiative and EMA's Enhanced Safety Monitoring requirements are compressing reporting timelines and forcing sponsors to rebuild case processing infrastructure around real-world data integration rather than periodic manual reviews.
Growth Catalysts
- EMA's DARWIN EU network:The distributed data access framework is creating standardized demand for cross-border signal detection capabilities among mid-sized sponsors lacking in-house European data access.
- Biotech pipeline expansion:First-time pharmacovigilance infrastructure builds for novel cell and gene therapies are generating net-new contract volume from sponsors without legacy safety departments.
- ICH E2B(R3) harmonization:Electronic transmission standard adoption across Japan's PMDA, Health Canada, and Australia's TGA is collapsing submission format fragmentation and enabling centralized processing hubs.
Market Restraints
- MedDRA coding specialist scarcity:Certified medical terminologists command compensation premiums that inflate per-case processing costs by 40-60% versus general clinical data managers.
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud dominance in pharmacovigilance platform hosting creates single-point-of-failure risk for multi-tenant safety databases.
- Periodic Safety Update Report cycle compression:EMA's shift toward continuous benefit-risk assessment is eliminating the predictable workload smoothing that justified fixed-cost offshore centers.
Strategic Opportunities
- Japan's PMDA real-world evidence pathway:The regulator's explicit acceptance of registry data for safety substantiation opens service expansion for vendors with Japanese hospital network partnerships.
- AI-augmented case narrative generation:Large language model integration with structured MedDRA coding is reducing physician reviewer time per serious adverse event from hours to minutes.
- Direct-to-patient digital reporting channels:Mobile adverse event capture bypasses healthcare provider intermediaries, expanding data volume for sponsors of self-administered biologics.
Industry Challenges
- Qualified Person for Pharmacovigilance certification bottlenecks:EU regulatory requirements for named QPPV residents in member states outstrip experienced candidate supply.
- Legacy safety database migration complexity:Oracle Argus and ARISg custom configuration histories impede cloud-native platform transitions without multi-year parallel run periods.
- Signal detection false positive management:Statistical algorithm sensitivity improvements generate disproportionate investigation workload without corresponding regulatory clarity on dismissal thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Post-Marketing Pharmacovigilance and Medical Information Market |
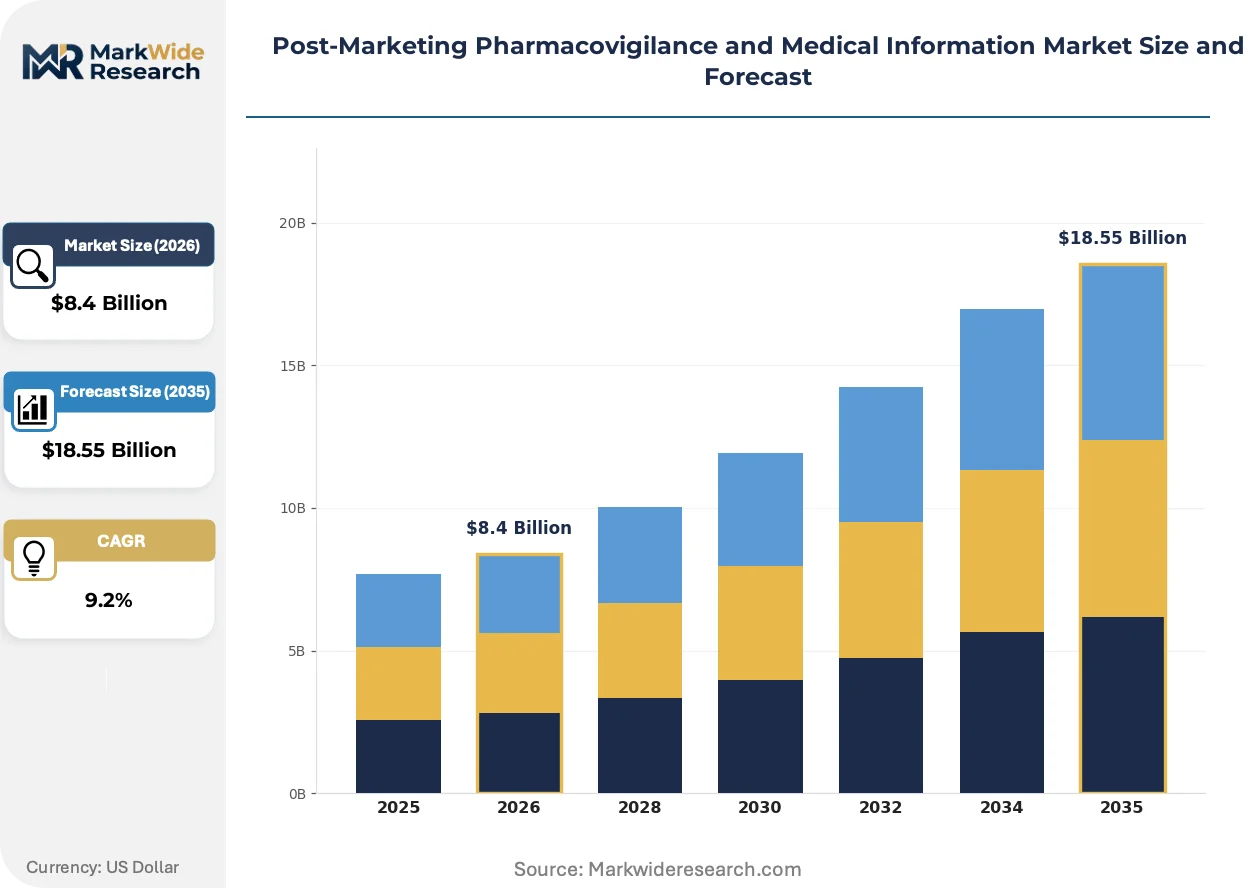
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Signal Detection, Risk Management, Data Analysis, Compliance Management Technology: Artificial Intelligence, Machine Learning, Cloud Computing, Data Mining Customer Type: Pharmaceutical Companies, Biotech Firms, Regulatory Bodies, Contract Research Organizations Delivery Model: On-premise, Cloud-based, Hybrid, Managed Services |
| Companies Covered | IQVIA Inc, Parexel International Corporation, Laboratory Corporation of America Holdings, ICON plc, Syneos Health, Accenture plc, Cognizant Technology Solutions Corporation, Ergomed Group, ArisGlobal LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Post-Marketing Pharmacovigilance and Medical Information Market Strategic Shifts & Innovations
Artificial intelligence is compressing case processing timelines while regulatory data access networks are redistributing analytical capabilities across geographies. These forces are converging to reshape vendor specialization and sponsor insourcing calculus.
Natural language processing engines trained on historical individual case safety reports are modularizing the extraction of structured data elements from unstructured source documents. Mid-sized biotechnology sponsors are adopting these tools fastest, replacing manual abstraction with automated entity recognition for medication errors and overdose cases. This technology is modularizing the traditional case processor role into exception-handling specialists rather than primary data entry operators.
The FDA's Sentinel Active Risk Identification System expansion into rare disease therapeutics is mandating distributed database query capabilities that few sponsors possess natively. Manufacturers of orphan drugs now face contractual requirements to demonstrate active surveillance infrastructure as a condition of accelerated approval maintenance. Oncology and hematology portfolios bear the steepest compliance cost increases as FDA narrows acceptable latency between signal emergence and regulatory notification.
Consolidated vendor relationships are displacing fragmented multi-provider arrangements as procurement teams prioritize accountability for end-to-end safety data lineage. Large pharmaceutical sponsors are reducing their qualified vendor panels from twelve to four or fewer strategic partners, bundling case processing, signal detection, and medical information services under unified master service agreements. This concentration is most visible among US-based headquarters clusters in Massachusetts and New Jersey, where procurement functions have centralized pharmacovigilance category management.
Post-Marketing Pharmacovigilance and Medical Information Market Segmentation
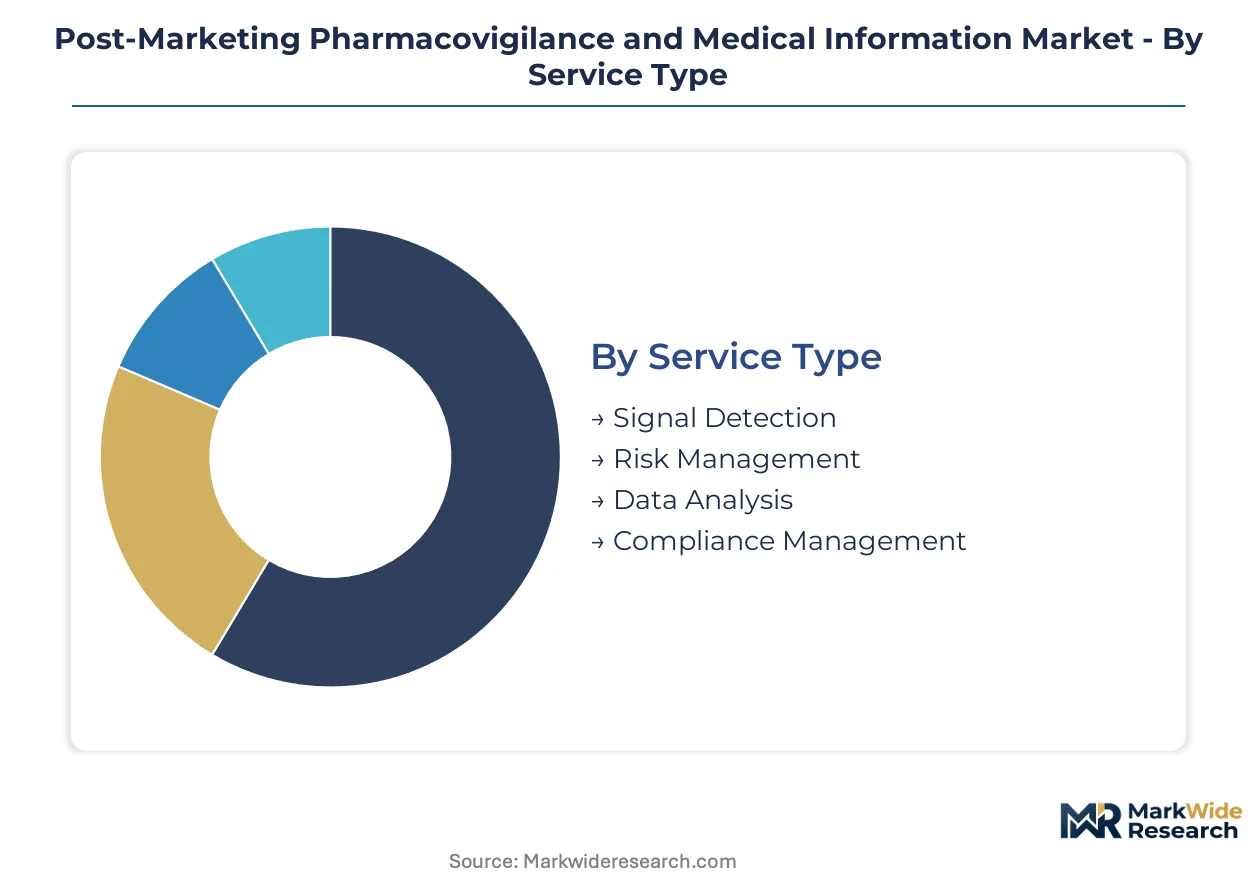
Segmentation in pharmacovigilance reveals how regulatory burden distributes across service tiers and technology maturity levels. Sponsors configure vendor portfolios differently based on whether they face first-time infrastructure builds or legacy system modernization.
Service Type:
Certification requirements intensify with clinical decision-making proximity: signal detection demands physician epidemiologists, while compliance management operates through standardized quality management system certifications.
- Signal Detection:Statistical algorithms and medical review protocols identify emerging safety patterns from spontaneous report databases and real-world evidence sources. Oncology sponsors in Massachusetts and New Jersey concentrate demand here as FDA compresses notification timelines for rare disease therapeutics.
- Risk Management:Risk Evaluation and Mitigation Strategies and Risk Management Plans structure proactive safety interventions for high-risk products. EMA's Enhanced Safety Monitoring requirements drive European contract volume for cell and gene therapy developers lacking in-house epidemiology benches.
- Data Analysis:Periodic aggregate safety reporting and benefit-risk assessment documentation support regulatory submission cycles.
- Compliance Management:Case processing, MedDRA coding, and periodic safety update report production satisfy baseline pharmacovigilance obligations.
Leading the category by volume: Compliance Management. Growing fastest: Signal Detection.
Technology:
Technology cost tiers separate experimental pilots from production infrastructure, with AI commanding premium implementation fees against cloud computing's operational expenditure model.
- Artificial Intelligence:Natural language processing engines extract structured data from unstructured adverse event narratives, compressing physician reviewer time per serious case. Biotech sponsors adopt these tools fastest, replacing manual abstraction with automated entity recognition for medication errors.
- Cloud Computing:Multi-tenant safety database hosting enables centralized processing hubs across ICH E2B(R3) harmonized jurisdictions. AWS, Azure, and Google Cloud dominance creates single-point-of-failure concentration risk for pharmacovigilance platform operators.
- Machine Learning:Predictive signal generation algorithms reduce false positive rates through historical pattern training on approved product safety profiles.
- Data Mining:Disproportionality analysis and temporal pattern recognition support hypothesis generation from large spontaneous report repositories.
Dominating procurement budgets: Cloud Computing. Expanding most quickly: Artificial Intelligence.
Customer Type:
Customer maturity determines whether engagements target full outsourcing or capability supplementation, with first-time builders purchasing integrated bundles versus established players seeking point solutions.
- Pharmaceutical Companies:Large sponsors with legacy safety departments pursue hybrid models, retaining strategic signal detection in-house while outsourcing high-volume case processing. Consolidated vendor panels have compressed from twelve to four strategic partners under unified master service agreements.
- Biotech Firms:First-time pharmacovigilance infrastructure builds for novel cell and gene therapies generate net-new contract volume from sponsors without legacy safety departments. These firms require end-to-end service bundles spanning case intake through periodic safety update report submission.
- Regulatory Bodies:National pharmacovigilance centers and WHO collaborating centers purchase signal detection and data analysis services for public health surveillance.
- Contract Research Organizations:Safety service providers themselves subcontract specialized capabilities such as MedDRA coding or Japanese QPPV representation.
Representing the largest contract value: Pharmaceutical Companies. Climbing the fastest: Biotech Firms.
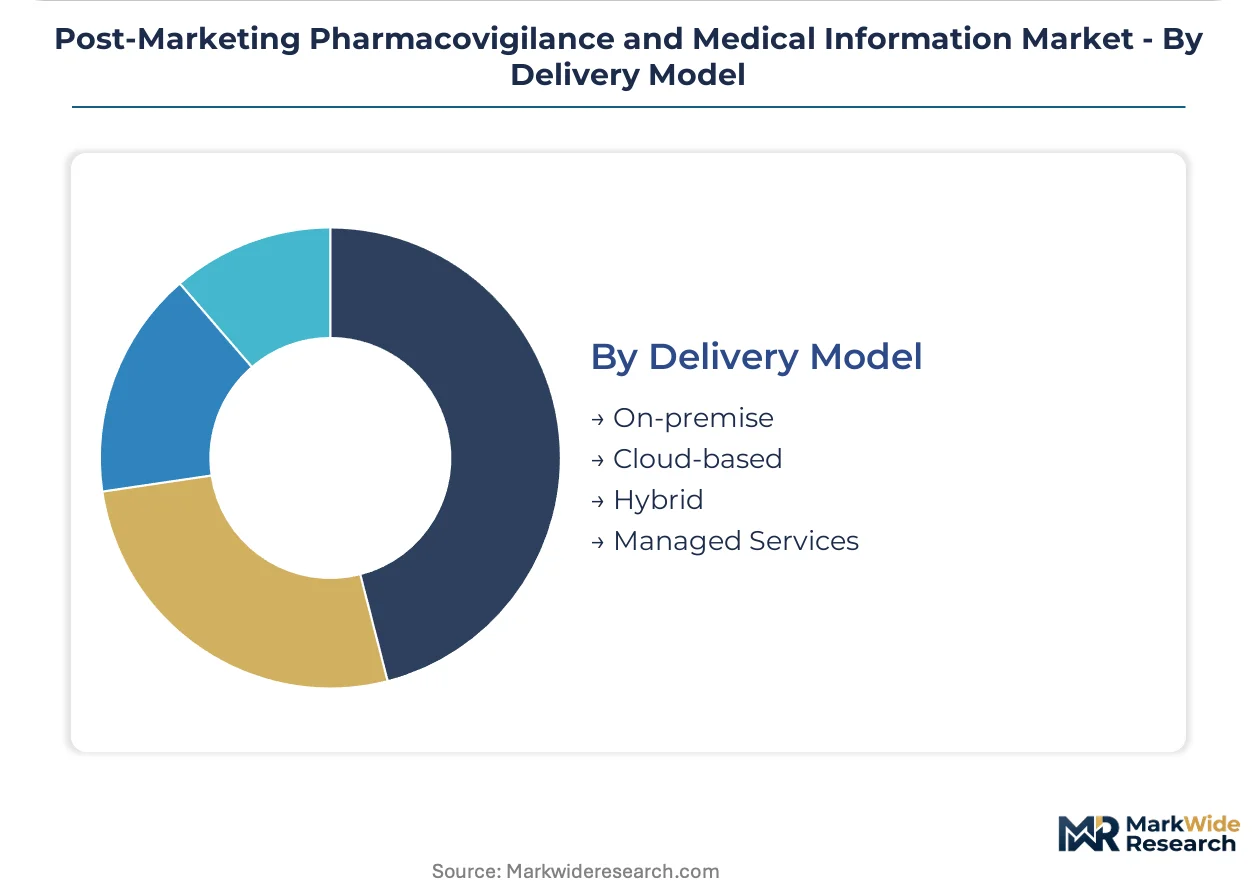
Delivery Model:
Delivery geography and control preferences shape vendor selection, with hybrid architectures dominating as sponsors balance data residency requirements against cloud scalability.
- Cloud-based:Fully managed SaaS platforms eliminate capital expenditure for safety database infrastructure while enabling rapid scaling for launch-phase product portfolios. EMA's DARWIN EU network access requirements favor cloud architectures with European data residency options.
- Hybrid:Sensitive case data remains on-premise while analytics and reporting leverage cloud elasticity. This model satisfies FDA data integrity expectations for electronic submission source data while accessing scalable signal detection compute.
- On-premise:Legacy Oracle Argus and ARISg installations persist where custom configuration histories impede migration without multi-year parallel run periods.
- Managed Services:Vendor-operated safety departments provide named QPPV representation and regulatory correspondence management for sponsors without European legal entity infrastructure.
Capturing majority deployment share: Hybrid. Gaining share fastest: Cloud-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory data infrastructure investments anchor geographic demand distribution, with sponsor headquarters clustering and national pharmacovigilance center capabilities determining contract placement patterns.
United States
FDA's Sentinel Active Risk Identification System mandates real-world data integration for rare disease therapeutics, compressing signal detection timelines for oncology and hematology portfolios. The 21st Century Cures Act provisions accelerate safety reporting requirements. Massachusetts and New Jersey pharmaceutical headquarters clusters concentrate procurement for consolidated vendor panels spanning case processing through medical information services.
Germany
EMA's DARWIN EU network access requirements drive demand for cross-border signal detection capabilities among mid-sized sponsors lacking native European data infrastructure. The country's Qualified Person for Pharmacovigilance certification framework shapes staffing models for vendor-operated safety departments. Frankfurt and Munich host pharmacovigilance operations centers serving sponsors without German legal entity presence.
Japan
PMDA's explicit acceptance of registry data for safety substantiation opens service expansion for vendors with Japanese hospital network partnerships. The ICH E2B(R3) electronic transmission standard adoption collapses submission format fragmentation. Tokyo and Osaka metropolitan areas concentrate contract research organization subcontracting for MedDRA coding and local QPPV representation.
United Kingdom
MHRA's post-Brexit independent pharmacovigilance framework maintains alignment with EMA standards while creating distinct national reporting obligations. The country's regulatory science initiatives emphasize real-world evidence integration for benefit-risk assessment. London and Cambridge biotech clusters generate first-time infrastructure builds for cell and gene therapy developers.
India
CDSCO's pharmacovigilance program expansion for marketed drugs creates compliance management demand from domestic manufacturers and multinational sponsor subsidiaries. The country's clinical data management workforce supplies MedDRA coding specialists to global processing hubs. Hyderabad and Bangalore technology corridors host cloud-based safety database operations serving ICH-harmonized jurisdictions.
Post-Marketing Pharmacovigilance and Medical Information Market Key Industry Players
Global majors compete with regional champions across service bundling and technology integration dimensions, creating a tiered structure where scale-driven consolidators vie with specialized risk management boutiques. The market exhibits concentration at the top tier alongside fragmentation among niche coding and medical information providers. Three archetypes dominate: integrated contract research organizations with safety service divisions, pure-play pharmacovigilance technology vendors, and healthcare consulting firms with regulatory capabilities. M&A activity targets AI-augmented case processing platforms, while strategic partnerships secure access to real-world data networks.
Among integrated research service providers, IQVIA Inc and Parexel International Corporation exemplify archetypes anchoring multi-country signal detection programs and specialized oncology risk management capabilities respectively. Cognizant Technology Solutions Corporation occupies a position representing technology-led delivery models that integrate artificial intelligence into case processing workflows. These three entities illustrate how vendor differentiation concentrates around data network scale, therapeutic area depth, and automation sophistication rather than geographic coverage alone.
| Leading Market Players |
|---|
| IQVIA Inc |
| Parexel International Corporation |
| Laboratory Corporation of America Holdings |
| ICON plc |
| Syneos Health |
| Accenture plc |
| Cognizant Technology Solutions Corporation |
| Ergomed Group |
| ArisGlobal LLC |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up pharmacovigilance specialists have consolidated fragmented coding boutiques across India and Eastern Europe, tightening pricing discipline through centralized vendor management while compressing margins for standalone MedDRA terminologists. This ownership concentration feeds directly into supply chain restructuring as sponsors demand bundled case-processing-to-signal-detection contracts under unified master service agreements.
Pricing Analysis
Service bundling separates comprehensive case processing from unbundled MedDRA coding-only engagements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales regulatory correspondence management. Cost compression in the economy tier is intensifying because cloud-native platform operators are automating routine case intake workflows. Biotech first-time infrastructure builders exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize accountability over unit cost.
Supply Chain Analysis
Certified medical terminologist supply rests on Indian clinical data management training institutes and Filipino nursing graduate pipelines feeding global processing hubs. AWS, Azure, and Google Cloud dominance in multi-tenant safety database hosting creates single-point-of-failure vulnerability for pharmacovigilance platform operators. Distribution runs through consolidated vendor panels reducing from twelve to four strategic partners per sponsor. Tariff exposure on cross-border data transmission services threatens cost structures for European case processing centers serving US sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Post-marketing pharmacovigilance operates as a cost-of-compliance market where EMA's DARWIN EU network requirements erect barrier-to-entry moats favoring vendors with pre-positioned European data access infrastructure.
For Market Incumbents: Acquire AI-augmented case narrative generation platforms to compress physician reviewer time per serious adverse event. Defensive consolidation must address cloud infrastructure concentration risk through multi-cloud safety database architectures. Cognizant and IQVIA exemplify the automation sophistication threatening standalone coding specialists.
For New Entrants and Emerging Players: Japan's PMDA real-world evidence pathway in Japan opens a window for vendors with Japanese hospital network partnerships to establish signal detection capabilities. White-space concentration sits with mid-sized European sponsors lacking native DARWIN EU access. Go-to-market positioning should emphasize direct-to-patient digital reporting channel development for self-administered biologics sponsors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor AI-native pharmacovigilance technology vendors in Massachusetts and New Jersey pharmaceutical headquarters clusters. Long-term viability hinges on regulatory data network access rather than labor arbitrage alone. Watch FDA Sentinel Initiative expansion into rare disease therapeutics as inflection indicator for real-world evidence integration demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Case Processing Platform | Natural language processing engines reduce physician reviewer time from hours to minutes per serious adverse event. |
| DARWIN EU Network Access Partnership | EMA's distributed data framework creates standardized demand for cross-border signal detection capabilities. |
| Japanese Hospital Network Alliance | PMDA's registry data acceptance opens service expansion for vendors with local clinical partnerships. |
| Multi-Cloud Safety Database Migration | AWS, Azure, and Google Cloud concentration risk demands redundant hosting architectures for pharmacovigilance platforms. |
| Direct-to-Patient Digital Reporting Channel | Mobile adverse event capture bypasses healthcare intermediaries for self-administered biologics sponsors. |
Research Approach
Multi-period observation of FDA Sentinel Initiative expansion patterns and EMA DARWIN EU network deployment timelines anchored the trend analysis, supplemented by interviews with drug safety officers, regulatory affairs directors, MedDRA coding specialists, and pharmacovigilance procurement managers. Secondary validation drew from FDA 483 inspection observations, EMA periodic safety update report assessment reports, ICH E2B(R3) implementation guidance documents, and pharmacovigilance master service agreement templates. Bottom-up service provider revenue aggregation triangulated against top-down sponsor pharmacovigilance budget allocation surveys.
Input-output matrices modeled demand across service type, technology deployment, customer maturity, and delivery model dimensions throughout the forecast period. CAGRs derived from regression analysis against regulatory filing volume projections and biotech pipeline expansion rates. Forecast inputs incorporated ICH E2B(R3) harmonization timelines, Qualified Person for Pharmacovigilance certification pipeline constraints, and AI case processing adoption curves.
Caveats apply where FDA Sentinel Active Risk Identification System scope expansion or EMA continuous benefit-risk assessment timeline compression could materially shift the outlook. Forecasts reflect assumptions about regulatory technology procurement cycles and cloud infrastructure migration paces. A small set of named triggers—MedDRA coding specialist wage inflation, multi-cloud platform reliability incidents, and PMDA real-world evidence pathway implementation speed—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Global Clinical Information System Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Medical Coding Market
Medical Information Systems
Global Cardiovascular Information System Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Global Healthcare Software As a Service Market