
 Urban Pharma Micro-Depot and Delivery Network Market | 2026-2036
Urban Pharma Micro-Depot and Delivery Network Market Size, Share, and Industry Trends Forecast 2026-2036
Urban Pharma Micro-Depot and Delivery Network Market Insights
Autonomous last-mile orchestration is fragmenting traditional hub-and-spoke pharmaceutical distribution into distributed micro-fulfillment nodes. DHL Supply Chain anchors European cold-chain micro-depot density through its pharma-certified warehousing network. FedEx competes in North America with temperature-validated van fleets and real-time intervention protocols. Marken specializes in clinical-trial specimen flows, sustaining premium service tiers through chain-of-custody rigor.
Urban pharma micro-depots are compact, climate-controlled storage and dispatch facilities positioned within city cores to enable sub-one-hour delivery of temperature-sensitive medications; units typically maintain validated ranges from controlled ambient through deep-frozen conditions using redundant compressor and sensor arrays. Their commercial purpose centers on reducing product excursion risk while replacing centralized distribution with proximate inventory positioning. Electric cargo bikes dominate European last-mile deployment where congestion charges and emission zones restrict van access, while drone corridors represent the fastest-growing delivery mode in Gulf state pilots and select Southeast Asian corridors. AI route optimization captures disproportionate technology investment as dispatch algorithms integrate traffic, weather, and patient-window constraints to minimize thermal exposure time.
FDA validation requirements for distributed storage sites and EMA Good Distribution Practice inspections shape capital deployment decisions for depot buildouts and monitoring infrastructure. Germany's national drug regulator, the Bundesinstitut für Arzneimittel und Medizinprodukte, enforces batch-level traceability that accelerates blockchain verification adoption across depot networks. Stakeholders must weigh refrigerated automation capex against regulatory compliance costs as urban zoning and noise ordinances tighten constraints on 24-hour micro-depot operations.
Market Dynamics
Autonomous last-mile orchestration fragments traditional hub-and-spoke pharmaceutical distribution into distributed micro-fulfillment nodes. AI route optimization and IoT-enabled cold monitoring compress thermal exposure windows while tightening FDA and EMA compliance.
Growth Catalysts
- EMA Good Distribution Practice:Batch-level traceability mandates accelerate blockchain verification adoption across depot networks. German regulators enforce strict chain-of-custody protocols that favor validated micro-depot infrastructure.
- Biologics proliferation:Specialty clinics expand reliance on decentralized temperature-controlled storage for monoclonal antibodies and cell therapies. Patient-administered injectables require sub-one-hour urban delivery windows.
- Electric cargo bike deployment:European congestion charges and emission zones restrict van access in city cores. Last-mile operators pivot to zero-emission fleets that bypass traffic bottlenecks.
Market Restraints
- Refrigerated automation capex:Redundant compressor arrays and sensor networks demand substantial upfront capital. Smaller operators face barriers to achieving FDA validation for distributed storage sites.
- Urban zoning friction:Noise ordinances and 24-hour operation restrictions in dense German and Dutch city centers constrain depot placement. Municipal permitting timelines extend facility rollout schedules.
- Deep-frozen infrastructure scarcity:Qualified technicians for ultra-low temperature systems concentrate in established pharmaceutical hubs. Rural and secondary urban markets face talent access gaps.
Strategic Opportunities
- Drone corridor pilots:Gulf state regulators approve beyond-visual-line-of-sight routes for temperature-sensitive payloads. Saudi Arabia and UAE health authorities fast-track aerial delivery for remote clinic supply.
- Clinical trial specimen flows:Decentralized depot networks capture premium service tiers through chain-of-custody rigor. CROs seek validated partners for patient-centric trial logistics.
- EU Green Deal alignment:Carbon-neutral last-mile mandates create procurement preference for electric fleets and renewable-powered depots. Sustainability scoring increasingly influences contract awards.
Industry Challenges
- Legacy WMS integration:Enterprise pharmaceutical distributors struggle to synchronize decentralized inventory with centralized ERP systems. Real-time visibility gaps persist between micro-depots and headquarters.
- Qualified personnel scarcity:Technicians certified in both cold-chain engineering and pharmaceutical handling remain concentrated in mature markets. Training programs fail to match depot network expansion pace.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urban Pharma Micro-Depot and Delivery Network Market |
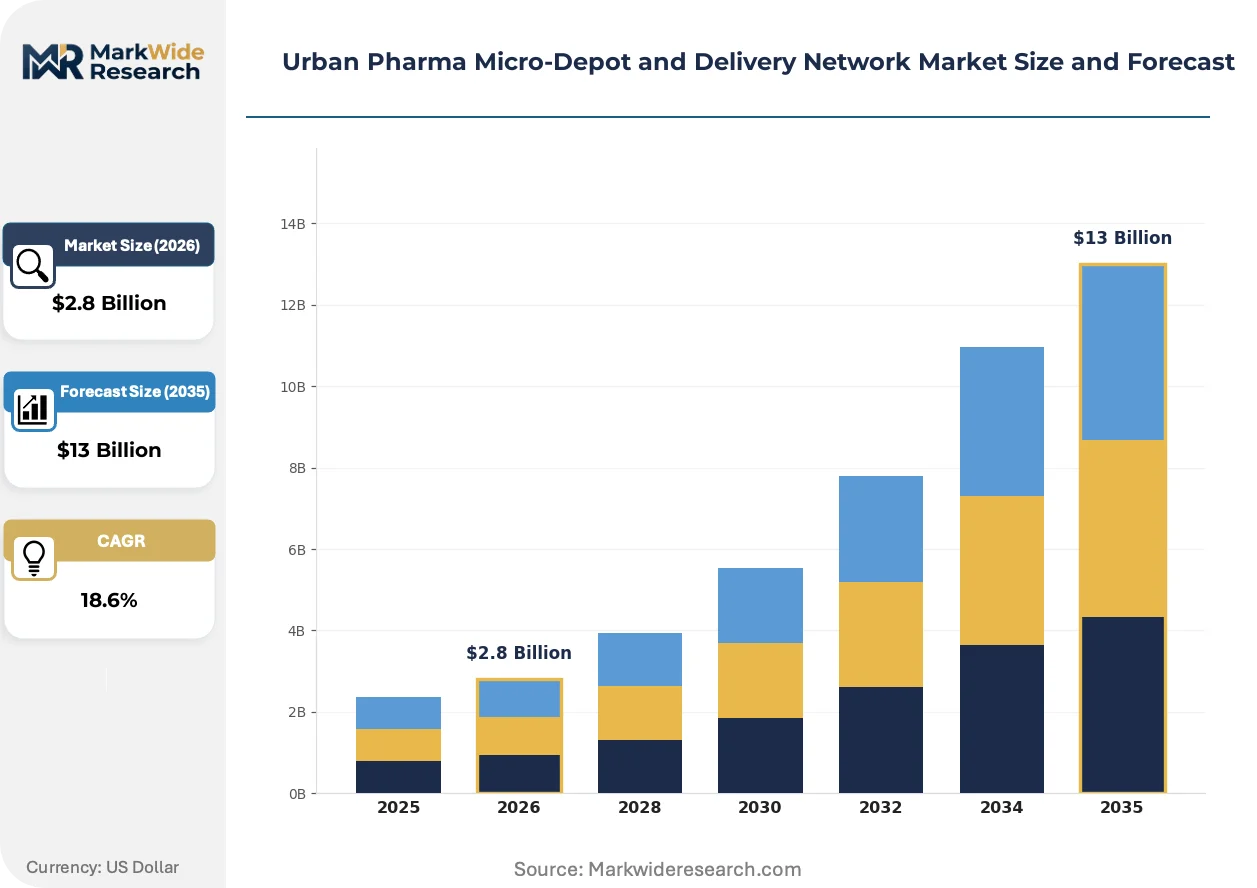
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Automated Guided Vehicles, Drones, Electric Cargo Bikes, Robot Couriers, Walk-In Pickup Kiosks, Mobile Vans End User: Community Pharmacies, Chain Dispensing Outlets, Specialty Clinics, Senior Care Facilities, Home Healthcare Providers, Diagnostic Labs Technology: Real-Time Tracking, AI Route Optimization, Temperature-Controlled Storage, Blockchain Verification, Cloud-Based Management Platforms, IoT Sensors Service Type: Last-Mile Delivery, Cold Chain Logistics, On-Demand Replenishment, Prescription Synchronization, Inventory Management, Patient Adherence Support |
| Companies Covered | United Parcel Service, FedEx, DHL Supply Chain, CEVA Logistics, DB Schenker, Marken, VersaCold Logistics Services, Agility, Air Canada Cargo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urban Pharma Micro-Depot and Delivery Network Market Trends and Innovations
Digital twin simulation and predictive thermal modeling compress validation cycles while reducing physical testing requirements. Stakeholders invest disproportionately in dispatch algorithms that integrate traffic, weather, and patient-window constraints.
AI-powered predictive maintenance is rendering obsolete scheduled compressor servicing in temperature-validated storage units. Specialty clinic networks and hospital outpatient pharmacies adopt sensor-fed analytics platforms that forecast equipment failure before excursion events occur. This shift compresses total cost of ownership curves and extends asset life cycles beyond traditional depreciation schedules.
FDA validation requirements for distributed storage sites reshape capital deployment decisions for depot buildouts and monitoring infrastructure. The agency's emphasis on continuous temperature documentation drives adoption of redundant sensor arrays and automated alert protocols. German operators face additional Bundesinstitut für Arzneimittel und Medizinprodukte batch-level traceability mandates that accelerate investment in blockchain-verified chain-of-custody systems.
Hospital procurement departments consolidate vendor relationships around integrated depot-plus-delivery contracts that bundle storage, transport, and compliance documentation. Traditional separation of warehousing and logistics procurement erodes as buyers seek single-accountability partners. German hospital networks lead this consolidation, driven by Bundesanstalt für Finanzdienstleistungsaufsicht scrutiny of subcontractor transparency in pharmaceutical supply chains.
Urban Pharma Micro-Depot and Delivery Network Market Segmentation
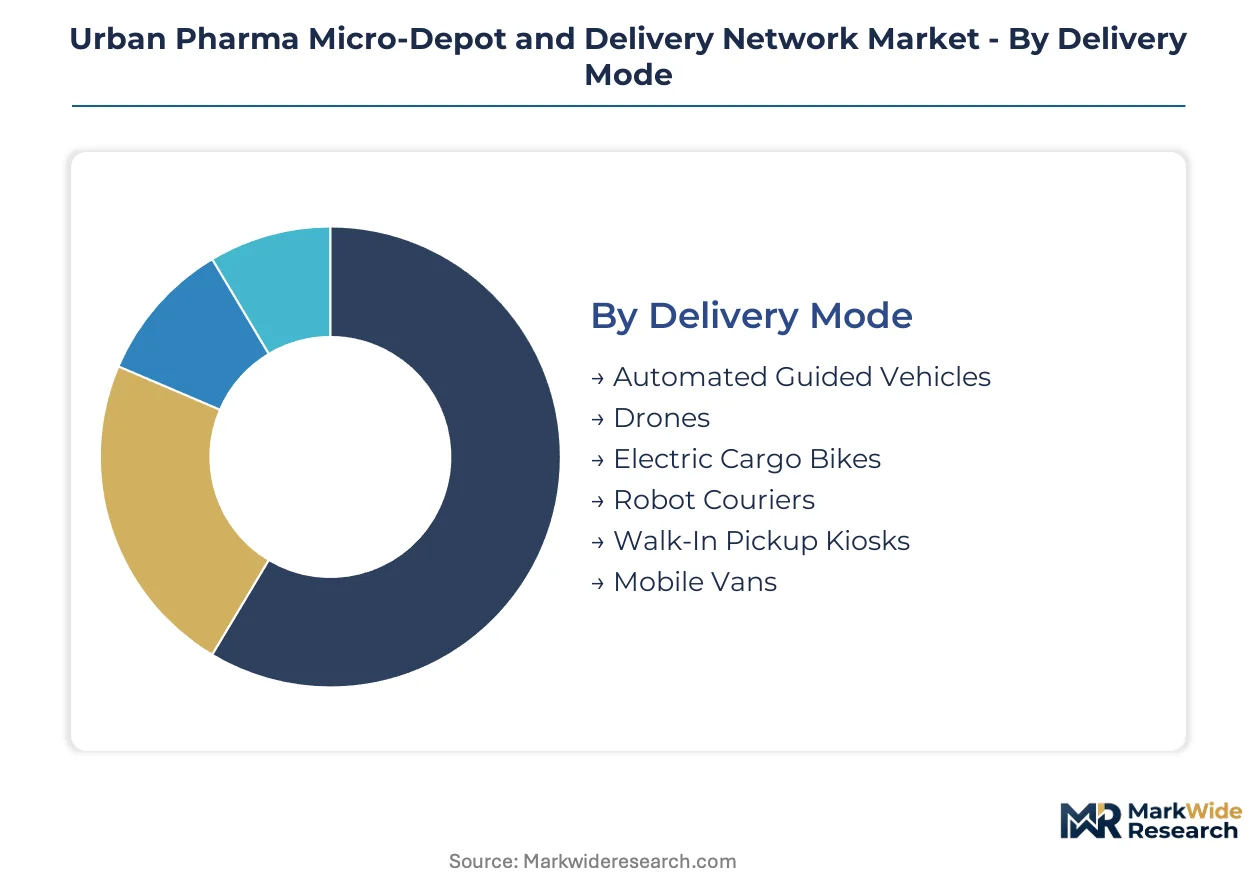
Segmentation in urban pharma micro-depot networks reveals how infrastructure investment, regulatory compliance, and patient proximity requirements fragment operational models. Delivery mode and technology choices determine capital intensity, while end-user concentration shapes depot density and service tiering across metropolitan clusters.
Delivery Mode:
Mature ground-based systems coexist with emerging aerial and autonomous modalities as congestion pricing and emission mandates reshape fleet economics.
- Automated Guided Vehicles:Campus and hospital-site AGVs operate on fixed-loop routes with validated temperature pods. German university medical centers in Heidelberg and Tübingen deploy AGVs for internal pharmacy-to-ward transfers, reducing human touchpoints in sterile supply chains.
- Drones:Beyond-visual-line-of-sight platforms carry 2-5kg payloads across 15-25km radii. Saudi Arabia and UAE health authorities fast-track aerial corridors for remote clinic supply, bypassing desert road infrastructure gaps.
- Electric Cargo Bikes:Zero-emission last-mile workhorses navigate low-emission zones in Amsterdam, Copenhagen, and Berlin city cores. Payload capacity limits restrict use to ambient and standard refrigerated products.
- Robot Couriers:Sidewalk-autonomous units handle short-radius deliveries from micro-depots to adjacent clinics. Sensor-laden compartments maintain chain-of-custody documentation for audit trails.
- Walk-In Pickup Kiosks:Temperature-validated lockers enable patient self-collection outside pharmacy hours. Berlin and Munich deployments concentrate near transit hubs for commuter convenience.
- Mobile Vans:Flexible-route vehicles with redundant compressor arrays serve variable-demand territories. FDA validation requirements for distributed mobile storage elevate compliance costs versus fixed depots.
Electric cargo bikes retain volume leadership in European urban cores; drones hold the steepest expansion curve in Gulf state pilot programs.
End User:
Customer type stratification mirrors the shift from centralized hospital pharmacy supply toward decentralized patient-centric distribution nodes.
- Community Pharmacies:Independent operators rely on micro-depot networks for same-day specialty medication access. German Apotheken leverage depot proximity to compete with mail-order dispensers.
- Chain Dispensing Outlets:Consolidated procurement functions demand integrated depot-plus-delivery contracts with single-accountability partners. Inventory synchronization across outlet networks requires real-time WMS integration.
- Specialty Clinics:Oncology and rheumatology practices drive demand for deep-frozen biologics storage within 30-minute delivery radii. Monoclonal antibody administration schedules require precise patient-window alignment.
- Senior Care Facilities:Nursing homes and assisted-living complexes need scheduled bulk replenishment with dose-level traceability. Bundesinstitut für Arzneimittel und Medizinprodukte batch-level mandates elevate documentation requirements.
- Home Healthcare Providers:Infusion and injection services depend on temperature-validated direct-to-patient delivery. Nurse scheduling constraints compress delivery window flexibility.
- Diagnostic Labs:Clinical trial specimen collection sites require chain-of-custody rigor from pickup through central lab processing. CROs pay premium service tiers for validated partner networks.
Specialty clinics command the highest service premiums; home healthcare providers are expanding most quickly as patient-administered therapies proliferate.
Technology:
Technology stack composition determines compliance posture and operational efficiency across depot networks with varying automation maturity.
- Real-Time Tracking:GPS and cellular triangulation provide location visibility with 30-second refresh intervals. Patient notification systems integrate with delivery window preferences.
- AI Route Optimization:Dispatch algorithms integrate traffic, weather, and patient-window constraints to minimize thermal exposure time. Machine learning models improve ETA accuracy through historical pattern recognition.
- Temperature-Controlled Storage:Redundant compressor arrays and sensor networks maintain validated ranges from controlled ambient through deep-frozen conditions. Physical infrastructure capex dominates network buildout economics.
- Blockchain Verification:Immutable ledger records satisfy EMA Good Distribution Practice batch-level traceability mandates. German operators accelerate adoption ahead of Bundesinstitut für Arzneimittel und Medizinprodukte inspection schedules.
- Cloud-Based Management Platforms:Centralized visibility dashboards synchronize decentralized inventory with enterprise ERP systems. Legacy WMS integration gaps persist between micro-depots and headquarters.
- IoT Sensors:Continuous temperature and humidity monitoring triggers automated alerts before excursion events occur. Predictive maintenance algorithms forecast compressor failure patterns.
Temperature-controlled storage absorbs the largest capital share; AI route optimization is gaining share fastest as dispatch sophistication becomes competitive table stakes.
Service Type:
Service bundling reflects procurement consolidation toward integrated partners capable of spanning storage, transport, and compliance documentation.
- Last-Mile Delivery:Final-segment transport from micro-depot to patient or provider with validated temperature maintenance. Congestion charges in London, Paris, and Berlin favor zero-emission fleet deployment.
- Cold Chain Logistics:End-to-end temperature-controlled handling from manufacturer through patient administration. FDA validation requirements for distributed storage sites reshape partner qualification criteria.
- On-Demand Replenishment:Emergency stock resupply for urgent patient needs outside scheduled delivery windows. Premium pricing reflects expedited dispatch and after-hours depot activation.
- Prescription Synchronization:Coordination of multi-medication refill timing to consolidate patient pickup or delivery events. Adherence programs integrate with pharmacy management systems.
- Inventory Management:Vendor-managed stock levels at micro-depots based on consumption forecasting. Consignment models transfer capital burden from provider to logistics operator.
- Patient Adherence Support:Delivery scheduling aligned with patient lifestyle patterns and medication timing requirements. Digital reminder systems reinforce compliance programs.
Last-mile delivery captures the broadest customer base; on-demand replenishment posts the steepest margin expansion as urgency premiums compound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and specialty clinics concentrate demand in dense metropolitan clusters where sub-one-hour delivery windows justify premium infrastructure investment. Regulatory fragmentation across national pharmaceutical authorities shapes depot network economics and compliance architecture.
Germany
Specialty oncology and rheumatology clinics in Berlin, Munich, and Hamburg drive demand for deep-frozen biologics storage within 30-minute delivery radii. The Bundesinstitut für Arzneimittel und Medizinprodukte enforces batch-level traceability mandates that accelerate blockchain verification adoption. Electric cargo bike fleets dominate last-mile deployment in Berlin's low-emission zone where congestion charges restrict van access.
United States
Hospital outpatient pharmacies and home healthcare providers expand patient-administered therapy distribution, compressing delivery windows for temperature-sensitive injectables. FDA validation requirements for distributed storage sites reshape capital deployment toward redundant sensor arrays and automated alert protocols. The Boston-Cambridge biotech corridor anchors clinical trial specimen flow networks serving contract research organizations.
United Arab Emirates
Remote clinic supply across desert infrastructure gaps drives aerial delivery pilot programs for temperature-sensitive payloads. The national health authority fast-tracks beyond-visual-line-of-sight drone corridors linking Dubai and Abu Dhabi medical districts. NEOM's planned healthcare zone integrates micro-depot positioning with renewable-powered cold storage.
Saudi Arabia
Government health modernization programs prioritize decentralized pharmaceutical distribution to secondary urban centers beyond Riyadh and Jeddah. The Saudi Food and Drug Authority aligns with Gulf Cooperation Council traceability standards for biologics chain-of-custody. Eastern Province oil industry settlements generate demand for urgent on-demand replenishment outside scheduled delivery windows.
Netherlands
Community pharmacy networks in Amsterdam, Rotterdam, and Utrecht leverage micro-depot proximity to compete with centralized mail-order dispensers. EU Green Deal carbon-neutral last-mile mandates create procurement preference for zero-emission electric fleets. Randstad urban density supports walk-in pickup kiosk deployment near transit hubs for commuter convenience.
Urban Pharma Micro-Depot and Delivery Network Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated logistics conglomerates anchor the premium infrastructure tier through pharma-certified warehousing networks and temperature-validated fleet deployment. Regional cold-chain specialists occupy mid-market positions with focused geographic coverage and compliance documentation bundling. Niche clinical trial logistics providers capture premium service tiers through chain-of-custody rigor and specimen handling specialization. Dominant competitive moves include strategic partnerships between depot operators and last-mile technology vendors, plus geographic expansion through regulatory validation replication across multiple national jurisdictions.
Within the integrated logistics tier, DHL Supply Chain and FedEx exemplify capital-intensive positioning through European cold-chain micro-depot density and North American temperature-validated van fleet deployment respectively. Marken occupies a specialized position representing clinical trial specimen flow expertise and chain-of-custody documentation rigor that contract research organizations prioritize for decentralized trial logistics. These three entities illustrate how service bundling and regulatory compliance depth separate scalable infrastructure players from commodity transport alternatives.
| Leading Market Players |
|---|
| United Parcel Service |
| FedEx |
| DHL Supply Chain |
| CEVA Logistics |
| DB Schenker |
| Marken |
| VersaCold Logistics Services |
| Agility |
| Air Canada Cargo |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in European cold-chain warehousing compresses per-cubic-meter storage rates while elevating service differentiation premiums. German micro-depot operators absorb fixed costs across denser node networks, passing selective savings to hospital procurement departments that consolidate vendor relationships around integrated depot-plus-delivery contracts.
Pricing Analysis
Cost-plus contracts with energy-indexed pass-through clauses dominate micro-depot service agreements, insulating operators from compressor power cost volatility. Pricing stratifies across FDA-validated premium tiers, EMA-compliant standard tiers, and non-certified economy storage, with certification level commanding the widest spreads. Cost compression in economy tiers is intensifying because redundant sensor arrays and blockchain verification infrastructure elevate baseline operating costs. Chain dispensing outlets exhibit the highest price sensitivity, while specialty clinics accept premium positioning for deep-frozen biologics access within 30-minute delivery radii.
Supply Chain Analysis
Export-control restrictions on IoT sensor arrays and AI-enabled dispatch algorithms limit technology transfer into certain jurisdictions, constraining depot automation deployment in emerging markets. Equipment manufacturing concentrates in Germany, the Netherlands, and the United States, with redundant compressor systems drawing from Danish and Japanese component suppliers. Single-source vulnerability in qualified technician pools for ultra-low temperature systems threatens network expansion timelines. Distribution runs through hub-and-spoke pharmaceutical wholesaler networks that fragment into micro-fulfillment nodes for last-mile completion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as patient-administered biologics penetration accelerates demand for sub-one-hour urban delivery infrastructure. Specialty clinic network growth represents the primary adoption tailwind justifying capacity buildout ahead of confirmed demand.
For Market Incumbents: Build regulatory certification moats through parallel FDA and EMA validation investments that emerging players cannot replicate quickly. Consolidate position by acquiring niche cold-chain specialists with established Bundesinstitut für Arzneimittel und Medizinprodukte inspection histories, while expanding electric cargo bike fleet density in Berlin and Amsterdam low-emission zones to preempt competitor node placement.
For New Entrants and Emerging Players: Pursue drone corridor partnerships with UAE and Saudi health authorities where beyond-visual-line-of-sight approvals create first-mover aerial delivery networks. Target clinical trial specimen logistics as the most penetrable segment, leveraging chain-of-custody documentation capabilities as the primary go-to-market angle against established pharmaceutical distributors.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap regional cold-chain specialists with validated German infrastructure and scalable technology stacks. Long-term viability hinges on regulatory compliance depth rather than pure asset scale, with acquisition premiums justified by EMA inspection-ready depot networks. Watch for Bundesinstitut für Arzneimittel und Medizinprodukte batch-level traceability mandate enforcement as the signal indicating accelerated blockchain verification adoption and corresponding infrastructure investment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Good Distribution Practice Certification | Accelerates blockchain verification adoption ahead of German regulator inspection schedules. |
| Electric Fleet Deployment | Captures EU Green Deal procurement preference in Amsterdam and Rotterdam pharmacy networks. |
| Drone Corridor Partnership | Establishes beyond-visual-line-of-sight routes for Saudi and UAE remote clinic supply. |
| Clinical Trial Logistics Specialization | Commands premium service tiers through chain-of-custody rigor for CRO specimen flows. |
| Predictive Maintenance Platform Integration | Compresses total cost of ownership curves for redundant compressor arrays across depot networks. |
Research Methodology
A standing panel of cold-chain operations directors, hospital pharmacy procurement managers, EMA regulatory affairs specialists, and clinical trial logistics coordinators provided ongoing calibration against secondary validation sources including FDA 483 inspection databases, EMA Good Distribution Practice audit records, Bundesinstitut für Arzneimittel und Medizinprodukte guidance documents, and pharmaceutical wholesaler financial disclosures. Bottom-up node density counts and top-down market sizing triangulated volume estimates across delivery mode, end user, and technology segmentation dimensions.
Scenario-bracketing around regulatory enforcement intensity and biologics approval velocity bounded the projection horizon. Segmentation modeling incorporated delivery mode, end user type, technology stack composition, and regional regulatory cluster. CAGRs derived from historical infrastructure deployment patterns, adjusted for patient-administered therapy penetration curves and urban zoning liberalization timelines. Forecast inputs included electric fleet adoption rates, drone corridor regulatory approval schedules, and cold-chain technician training program graduation volumes.
Macroeconomic conditions sit as an overlay; deviation in energy cost trajectories, pharmaceutical reimbursement policy, or urban congestion pricing schemes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory inspection frequency, biologics pipeline conversion rates, and municipal permitting timelines. Material shifts in FDA distributed storage site validation requirements or EMA batch-level traceability enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Placental Protein Market
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Drug Allergy Market
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Sildenafil Drug Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Compounding Chemotherapy Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
North America Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
United States Pharmaceutical 3PL Market