
 South America Offshore Helicopter Services Market | 2026-2036
South America Offshore Helicopter Services Market Size, Share, and Industry Trends Forecast 2026-2036
South America Offshore Helicopter Services Market Analytics
The South America offshore helicopter services sector is pivoting as premium long-range twin-engine fleets separate from aging single-engine commodity pools serving near-shore routes. Bristow Group leverages its contracted services footprint across Brazil's pre-salt fields. Omni Helicopters International S.A. anchors regional presence with specialized marine logistics capabilities. CHC Helicopter competes on aerial surveillance and emergency response coverage.
Offshore helicopter services encompass rotary-wing transport and support operations engineered for over-water missions beyond autorotation distance from shore, requiring twin-engine redundancy, flotation gear, and IFR-certified avionics to sustain platform-to-rig personnel movement and cargo delivery. The service type dimension shows transportation commanding stable revenue while emergency medical services and aerial surveillance represent faster-expanding margin pools. Aircraft type segmentation reveals twin-engine configurations leading value generation as operators retire single-engine units from deep-water routes.
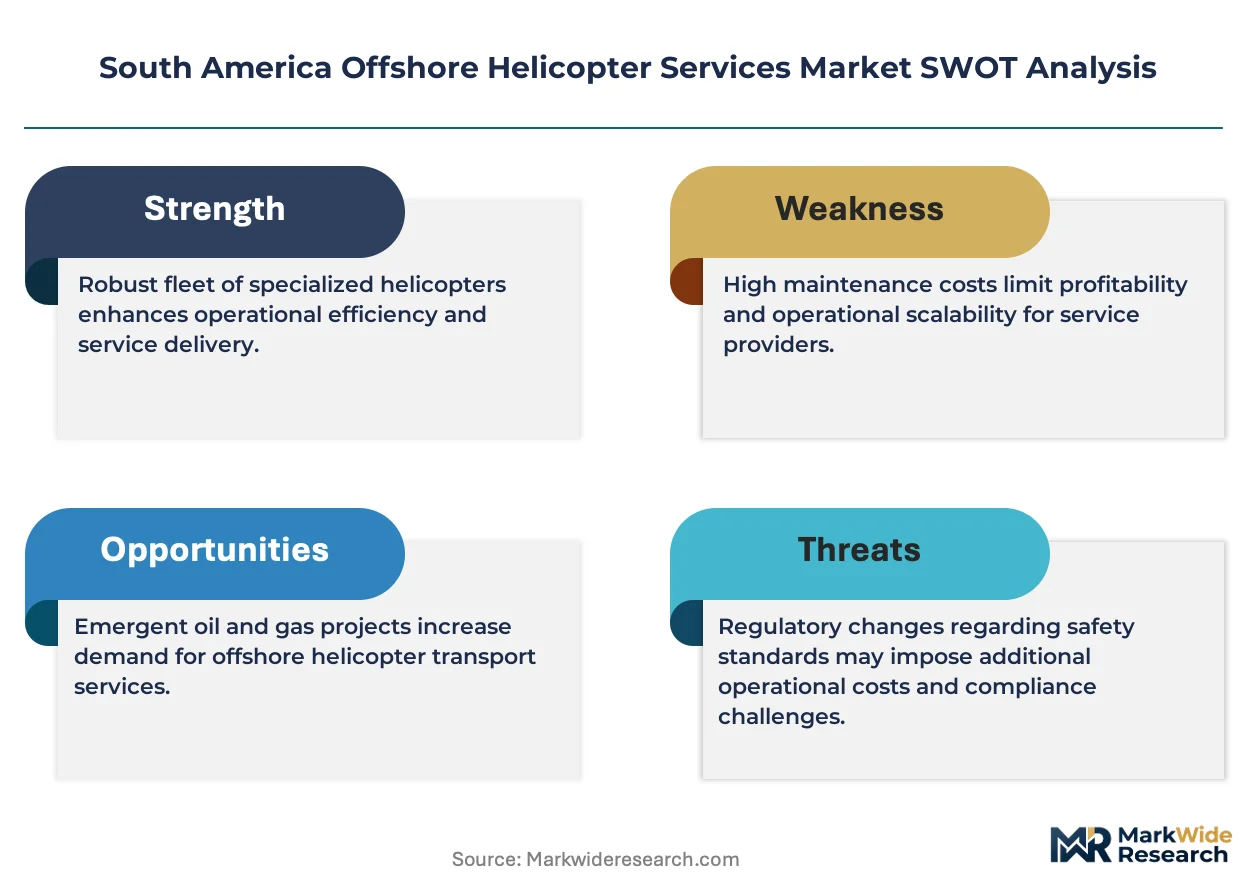
Brazil's ANAC mandates ETOPS-equivalent rules for offshore rotary operations, while Colombia's Aerocivil and Argentina's ANAC enforce parallel over-water certification standards that elevate fleet renewal requirements. These frameworks compress demand toward compliant twin-engine platforms and certified pilot training programs. Stakeholders must monitor regulatory harmonization progress and basin-specific contract tenors to align capacity commitments with enforcement timelines.
Market Dynamics
ANAC's ETOPS-equivalent mandates for offshore rotary operations are compressing fleet composition toward twin-engine platforms, forcing operators to accelerate retirement schedules for single-engine units serving Brazil's deep-water basins.
Growth Catalysts
- Pre-salt basin development:Brazil's Campos and Santos corridors sustain contracted flight hours as Petrobras and international operators expand platform staffing rotations.
- ANAC Part 121 rotary extensions:Regulatory harmonization with ICAO SARPs elevates safety margins and insurability for over-water missions beyond autorotation range.
- Twin-engine IFR avionics upgrades:Glass cockpit retrofits and synthetic vision systems extend operational weather minima for personnel transport contracts.
Market Restraints
- Airframe supply concentration:Airbus Helicopters and Leonardo dominate certified offshore configurations, limiting operator bargaining power on H175 and AW139 deliveries.
- Pilot certification bottlenecks:ANAC's instrument rating hour requirements and simulator validation queues extend crew qualification timelines.
- Jet A-1 price volatility:Fuel represents 35-40% of direct operating costs for turbine rotary fleets, compressing margin visibility on fixed-rate contracts.
Strategic Opportunities
- Guyana-Suriname basin emergence:ExxonMobil and consortium partners are activating helicopter support requirements for the Stabroek block developments.
- Search and rescue unbundling:Oil majors are separating SAR obligations from core transport contracts, creating standalone emergency response service lines.
- Simulator-based training mandates:ANAC's pending FSTD requirements for recurrent training open third-party training center investments.
Industry Challenges
- Type-rated pilot scarcity:AW139 and H175 endorsements require 500+ flight hours for insurance coverage, constraining crew availability during fleet transitions.
- Legacy single-engine phase-out coordination:Operators must synchronize retirement schedules with contract renewal windows without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Offshore Helicopter Services Market |
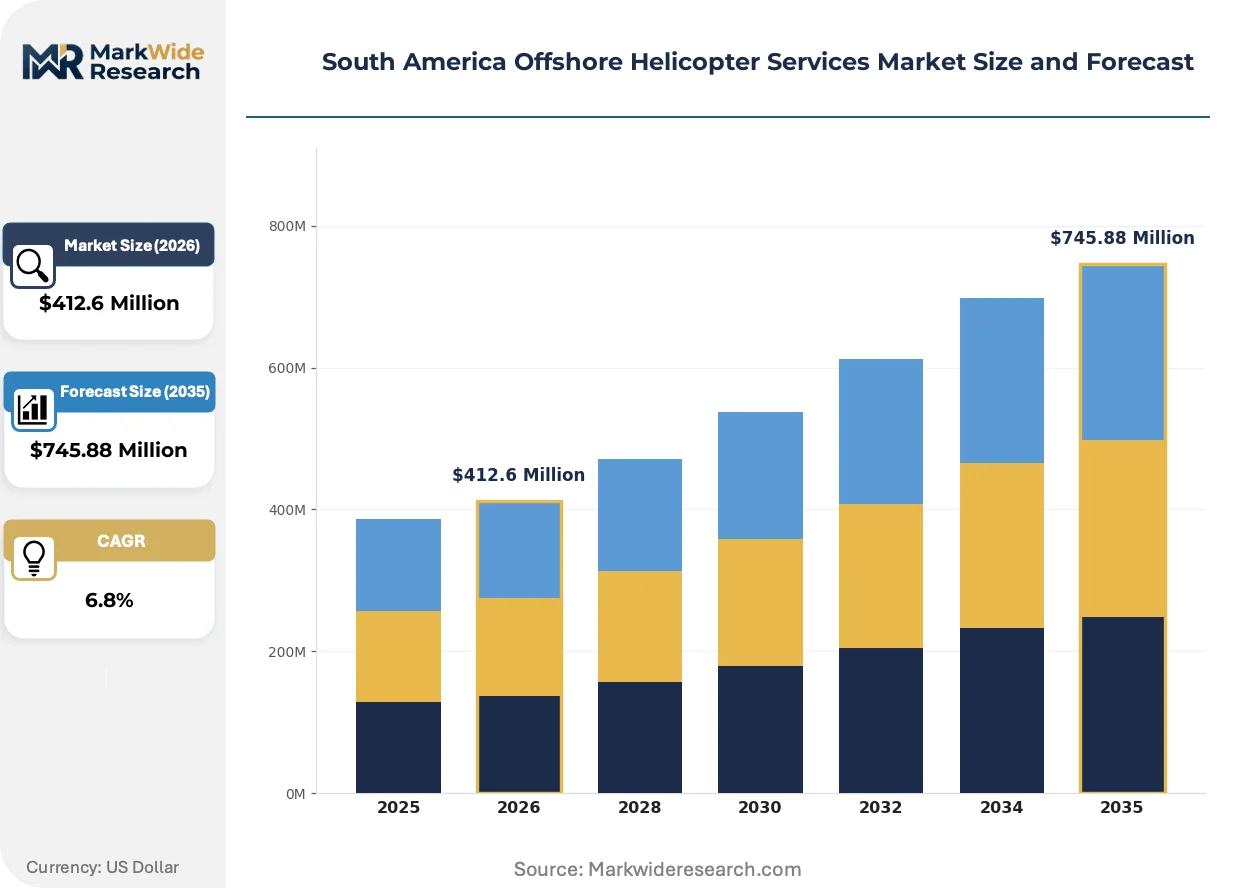
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Aerial Surveillance, Emergency Medical Services, Cargo Transport End User: Energy Sector, Marine Regulations, Government Agencies, Environmental Agencies Aircraft Type: Single Engine, Twin Engine, Heavy Lift, Light Utility Deployment Model: Chartered Services, On-Demand Services, Contracted Services, Scheduled Services |
| Companies Covered | Lockheed Martin Corporation, Omni Helicopters International S.A., Airbus Group SE, Helicópteros Marinos, Petroleum Helicopters International Inc., Leonardo SpA, CHC Helicopter, NHV Group, Bristow Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Offshore Helicopter Services Market Evolving Landscape
Digital flight data monitoring and predictive maintenance systems are reshaping how operators manage airworthiness and contract compliance across Brazil's pre-salt corridors.
Health and usage monitoring systems (HUMS) are decentralizing maintenance planning from scheduled calendar intervals toward condition-based interventions. Petrobras and international operators now mandate HUMS data sharing in tender specifications. This compression of unplanned downtime is reducing platform standby requirements and reshaping spare parts inventory positioning.
ANAC's forthcoming offshore helicopter operations rulemaking aligns with ICAO Annex 6 Part III, mandating flight data recorders and cockpit voice recorders on all passenger-carrying missions beyond 50 nautical miles from shore. Operators are retrofitting existing fleets ahead of enforcement timelines. The Santos basin corridor faces the steepest compliance curve due to higher mission density.
Contract structures are migrating from hourly availability models toward fixed monthly charges with performance penalties for dispatch reliability below 98%. This transfer of operational risk concentrates with helicopter operators while simplifying budget predictability for oil majors. The shift is most advanced in Brazil's Campos basin, where Petrobras has standardized terms across its pre-salt portfolio.
South America Offshore Helicopter Services Market Segmentation
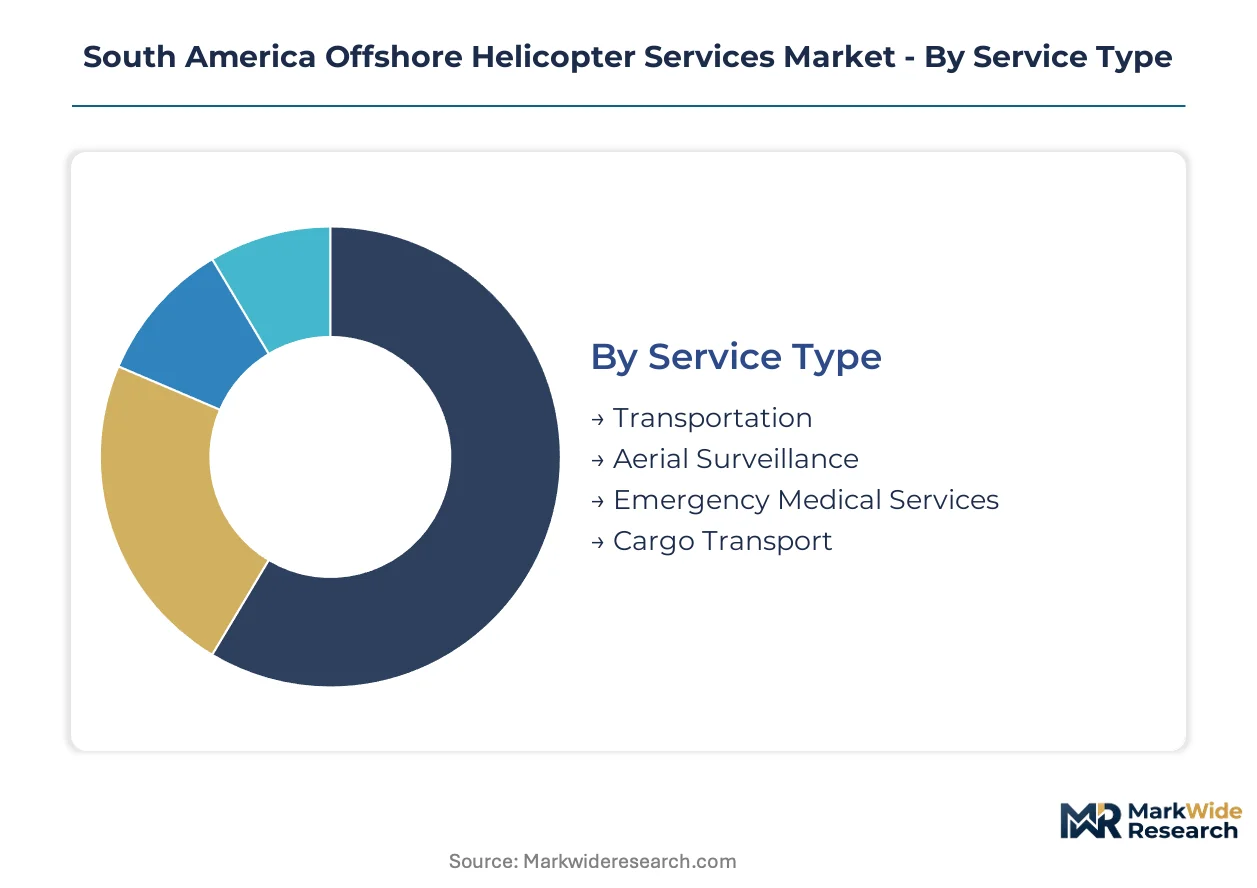
Segmentation in offshore helicopter services reveals how ANAC regulatory mandates and basin-specific operational requirements reshape buyer priorities across South America. Contract structures and airframe certification tiers determine vendor selection criteria for Petrobras and international operators.
Service Type:
Oil majors prioritize dispatch reliability and regulatory compliance when selecting service tiers, with contract penalties now tied to performance thresholds rather than hourly availability.
- Transportation:Personnel rotation flights between shore bases and offshore platforms constitute the core revenue base. Brazil's Campos and Santos basins generate concentrated flight hours as pre-salt development expands platform staffing requirements.
- Emergency Medical Services:SAR unbundling from transport contracts is creating standalone emergency response service lines. ANAC's IFR certification requirements for over-water medical evacuations are elevating equipment and crew training standards.
- Aerial Surveillance:Pipeline monitoring and environmental compliance patrols serve regulatory mandates.
- Cargo Transport:External load operations for platform resupply and equipment movement.
Volume sits with Transportation; growth tilts toward Emergency Medical Services.
End User:
Procurement authority concentrates with operators holding basin-specific production contracts and regulatory enforcement obligations.
- Energy Sector:Petrobras and international oil companies dominate contracted flight hours. Pre-salt field development in Brazil drives fleet utilization and dictates twin-engine platform requirements.
- Marine Regulations:Port authorities and maritime safety agencies mandate surveillance coverage.
- Government Agencies:Federal and state entities contract border patrol and infrastructure inspection missions.
- Environmental Agencies:IBAMA and regional regulators require spill response and ecosystem monitoring capabilities.
Revenue concentrates with Energy Sector; regulatory enforcement is expanding Government Agencies procurement.
Aircraft Type:
ANAC's ETOPS-equivalent mandates for offshore rotary operations are compressing fleet composition toward certified twin-engine configurations.
- Twin Engine:H175 and AW139 configurations dominate deep-water routes beyond autorotation range. ANAC certification requirements and insurance coverage standards are accelerating retirement of non-compliant alternatives.
- Single Engine:Near-shore and training operations retain limited deployment. Regulatory phase-out timelines in Brazil are forcing synchronized fleet transitions without service interruption.
- Heavy Lift:External cargo and construction support for platform installation.
- Light Utility:Short-range personnel transport and base support missions.
Investment flows to Twin Engine; Single Engine faces compressed replacement windows.
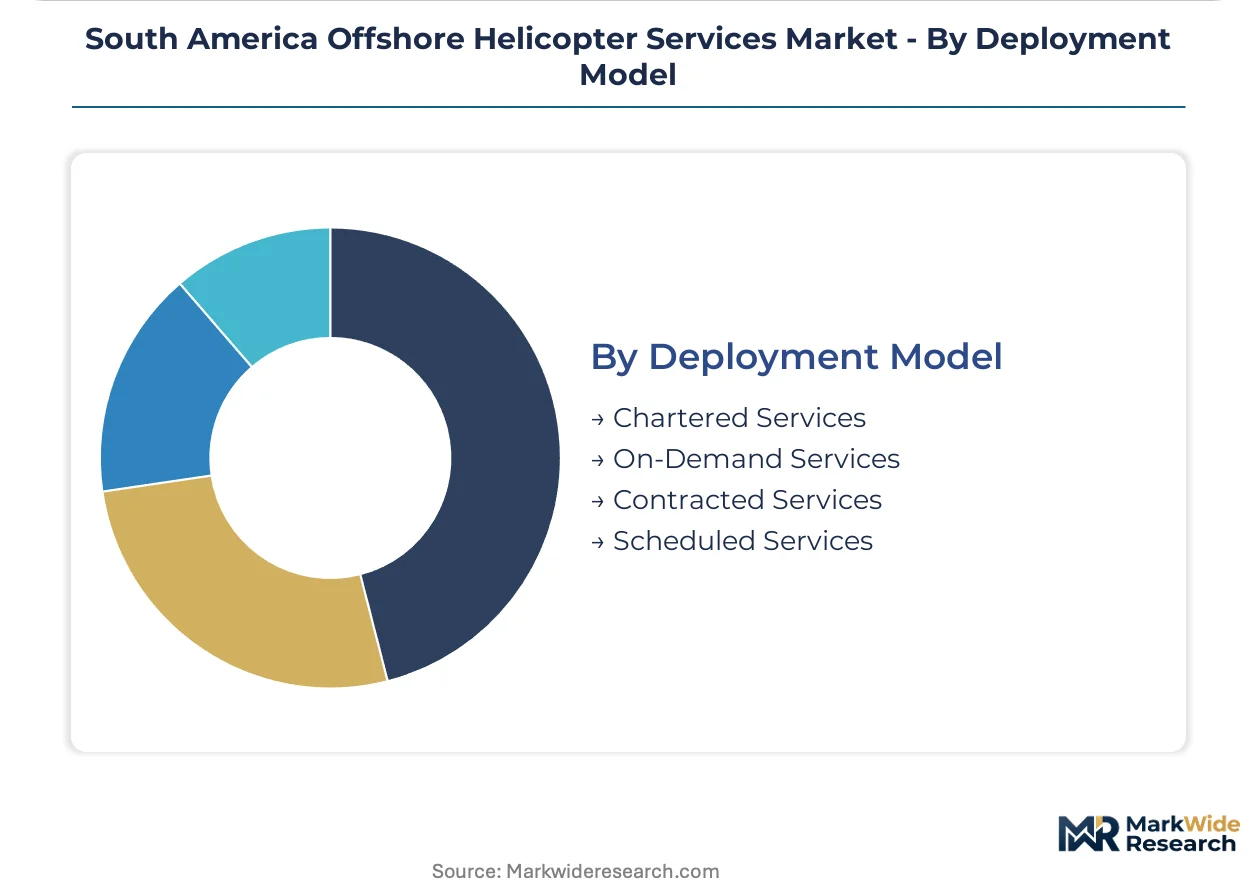
Deployment Model:
Risk allocation between operators and oil majors determines contract structure selection across Brazil's pre-salt corridors.
- Contracted Services:Long-term agreements with fixed monthly charges and 98% dispatch reliability penalties now standard for Petrobras pre-salt portfolio. Bristow Group and Omni Helicopters International anchor market presence through these structures.
- Chartered Services:Flexible capacity for exploration campaigns and non-routine operations.
- On-Demand Services:Ad-hoc missions for emergency response and unscheduled crew movements.
- Scheduled Services:Regularized shuttle routes between defined shore bases and production platforms.
Contracted Services capture volume; Chartered Services offer margin expansion during exploration cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rio de Janeiro anchors South America's offshore helicopter activity through its Macaé heliport corridor serving Brazil's pre-salt basins. The metropolitan cluster concentrates flight operations, maintenance facilities, and ANAC certification centers for deep-water rotary missions.
Brazil
Petrobras pre-salt development in the Campos and Santos basins sustains contracted flight hours for twin-engine platforms. ANAC mandates ETOPS-equivalent certification for offshore rotary operations beyond autorotation range. The Macaé-Rio corridor concentrates helicopter bases serving platform staffing rotations.
Colombia
Caribbean offshore exploration campaigns near Barranquilla generate chartered service demand for exploration drilling support. Aerocivil enforces parallel over-water certification standards to ANAC requirements. The Cartagena maritime cluster hosts helicopter logistics for offshore infrastructure projects.
Argentina
Vaca Muerta shale development in Neuquén province creates emerging demand for crew transport to remote drilling sites. ANAC Argentina maintains instrument rating requirements aligned with ICAO SARPs. The Comodoro Rivadavia corridor serves offshore Atlantic exploration near the Malvinas basin.
Guyana
ExxonMobil Stabroek block developments activate helicopter support requirements for floating production facilities. The country's civil aviation authority implements offshore rotary standards following ICAO Annex 6 frameworks. Georgetown serves as the logistics coordination point for consortium partner rotations.
Suriname
Block 58 discoveries by TotalEnergies and Apache Corporation drive preliminary helicopter service procurement for appraisal drilling. Offshore safety regulations adopt Dutch Caribbean standards with ICAO harmonization. Paramaribo coordinates shore-base operations for emerging deep-water campaigns.
South America Offshore Helicopter Services Market Competitive Landscape
Capital-heavy fleet operators compete with asset-light contract brokers for offshore logistics contracts across South America. The market structure concentrates around three ANAC-certified operators controlling pre-salt corridor capacity. Two strategic archetypes dominate: integrated fleet owners with captive maintenance capabilities and specialized marine logistics providers with SAR unbundling expertise. Competitive positioning hinges on twin-engine platform availability and 98% dispatch reliability guarantees rather than hourly rate competition.
Within the integrated fleet tier, Bristow Group and Omni Helicopters International S.A. occupy positions defined by contracted service footprints across Brazil's pre-salt fields. CHC Helicopter exemplifies the emergency response specialization archetype through aerial surveillance and SAR coverage capabilities. Leonardo SpA and Airbus Group SE anchor the airframe supply concentration as the dominant certified offshore configuration providers for H175 and AW139 platforms.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Omni Helicopters International S.A. |
| Airbus Group SE |
| Helicópteros Marinos |
| Petroleum Helicopters International Inc. |
| Leonardo SpA |
| CHC Helicopter |
| NHV Group |
| Bristow Group |
| Others |
Value Network & Pricing Analysis
Glass cockpit retrofits and synthetic vision system mandates across Brazil's pre-salt corridors are compressing operator capital cycles while concentrating bargaining power with Airbus Helicopters and Leonardo. This technology transition simultaneously elevates direct operating costs and locks fleet managers into dual-source airframe dependencies.
Pricing Analysis
Dispatch reliability guarantees now anchor contract valuation, with Petrobras and international oil majors penalizing sub-98% performance through fixed monthly charge structures. Price differentiation separates ANAC-certified twin-engine platforms from legacy single-engine units facing accelerated retirement. Pricing pressure intensifies as Jet A-1 volatility feeds through fixed-rate contracts. Exploration contractors exhibit highest price sensitivity, while pre-salt production operators prioritize uptime assurance over rate negotiation.
Supply Chain Analysis
Direct-to-operator channels handle contracted fleet procurement for Brazil's Campos and Santos basin corridors. Manufacturing concentrates in France, Italy, and Germany for H175 and AW139 airframes. Component sourcing draws from specialized avionics suppliers in the United States and United Kingdom. Single-source vulnerability sits with engine OEMs for turbine powerplant certification. Distribution runs through ANAC-certified maintenance facilities clustered in Rio de Janeiro's Macaé corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet transition bottlenecks prop pricing power for compliant twin-engine capacity, with type-rated pilot scarcity constraining rapid supply expansion.
For Market Incumbents: Cement contracted service positions through captive simulator training investments aligned with ANAC's pending FSTD mandates. Secure long-term airframe delivery slots with Leonardo and Airbus before order backlogs extend. Defend against emerging SAR unbundling specialists by integrating emergency response capabilities into core transport contracts. For New Entrants and Emerging Players: Maintenance repair and overhaul partnerships offer the fastest channel to ANAC certification without full fleet ownership burden. Target Guyana-Suriname basin developments where ExxonMobil Stabroek block requirements outstrip established operator presence. Pursue standalone training center investments as regulatory mandates force incumbent outsourcing. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic sales to integrated energy service conglomerates seeking vertical control over offshore logistics. Long-term viability hinges on exposure to pre-salt production phase rather than exploration cyclicality. Monitor ANAC enforcement timelines for flight data recorder mandates as fleet replacement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Twin-Engine Fleet Renewal | ANAC ETOPS-equivalent compliance eliminates single-engine platforms from deep-water routes. |
| Simulator Training Center Investment | Pending FSTD mandates create third-party revenue streams outside core flight operations. |
| SAR Capability Integration | Unbundling trends favor operators with standalone emergency response certification. |
| Guyana-Suriname Basin Expansion | Stabroek block developments activate greenfield contract opportunities outside Brazil. |
| Predictive Maintenance Platform Deployment | HUMS data sharing requirements in Petrobras tenders reshape spare parts inventory economics. |
Research Methodology
ANAC regulatory filings, ICAO Annex 6 implementation schedules, and Petrobras procurement disclosure documents formed the secondary backbone for demand quantification. Primary interviews with fleet operations directors, ANAC certification officers, and oil major logistics procurement managers validated capacity utilization assumptions. Bottom-up flight hour estimates across Campos and Santos basins were triangulated against top-down operator revenue disclosures.
Historical trendline analysis of contracted service tenors and fleet composition shifts informed projection modeling across the analysis window. Segmentation dimensions encompassed service type, aircraft certification tier, deployment model, and basin-specific operational requirements. CAGRs were derived from regression analysis of flight hour expansion against pre-salt platform staffing ratios. Forecast inputs incorporated ANAC rulemaking timelines and Guyana-Suriname exploration campaign schedules.
Several conditions sit outside the modeled scope, including military offshore operations, onshore rotary applications, and non-ANAC regulatory jurisdictions without ICAO harmonization. Forecasts reflect assumptions on regulatory enforcement adherence and oil price thresholds sustaining pre-salt development. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Flying Motorbikes Market
Air Mobility
Hang Glider Market
Air Mobility
Flying Taxi Market
Air Mobility
Air Transport USM Market
Air Mobility
Air Crane Helicopter Market
Air Mobility
Asia Pacific Helicopter Services Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
China Chartered Air Transport Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Advanced Aerial Mobility Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Offshore Helicopter Services Market