
 Asia Pacific Helicopter Services Market | 2026-2036
Asia Pacific Helicopter Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Helicopter Services Market Insights
India's DGCA mandates on pilot training hours and equipment certification is pivoting the cost-of-entry calculus for new operators across the subcontinent. Babcock International Group Plc leverages its vertical integration into maintenance and training to sustain contract renewals with Australian mining houses. Airbus Helicopters anchors its position through localized final assembly lines in China and Malaysia. Hindustan Aeronautics Limited dominates indigenous military and paramilitary supply.
Asia Pacific helicopter services encompass rotary-wing aircraft operations providing vertical lift capability for passenger transport, cargo delivery, and specialized mission profiles, with turbine engines typically delivering 500 to 2,000 shaft horsepower and maximum takeoff weights ranging from 1.5 to 11 metric tons depending on configuration class. These platforms serve critical functions where runway infrastructure is absent or terrain restricts fixed-wing access, including offshore crew change, emergency medical retrieval, and precision external load placement. Medical evacuation services within the End User dimension command premium rate structures due to specialized aeromedical equipment and crew certification requirements. Twin Engine configurations in the Configuration dimension are capturing expanded share as operators prioritize redundancy for over-water and high-altitude missions. Charter services in the Service Type dimension maintain the largest revenue pool across the region, though Cargo Transport shows accelerated growth tied to remote logistics demands.
Japan's METI enforces noise abatement and operational route standards around urban heliports, while Australia's Civil Aviation Safety Authority mandates fatigue management systems for offshore crews. China's CAAC aligns airworthiness certification with MIIT industrial policy to promote domestic rotorcraft manufacturing. Stakeholders must monitor how bilateral air service negotiations between Australia and Indonesia reshape cross-border charter permissions and crew licensing reciprocity.
Market Dynamics
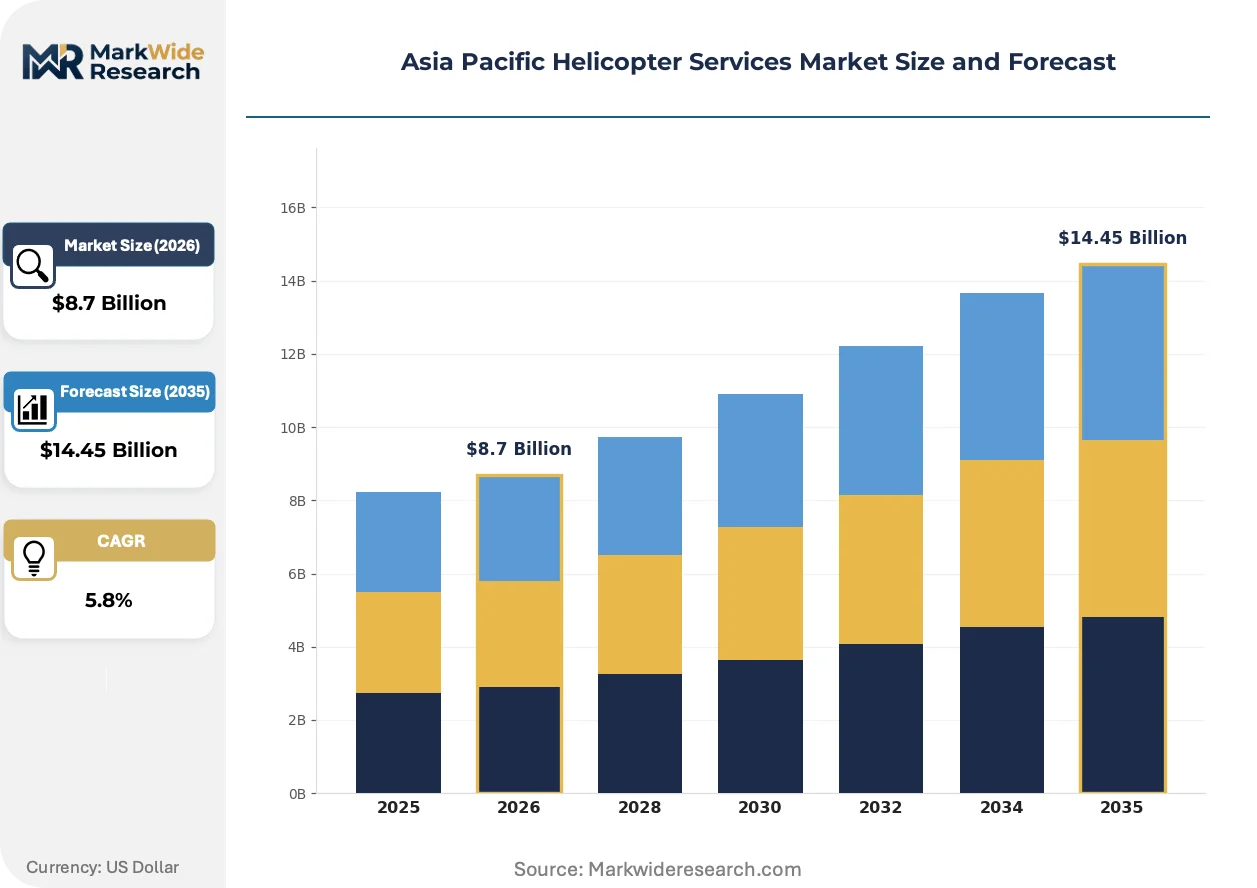
Deepwater oil and gas exploration off Malaysia and Indonesia is pulling heavy-lift helicopter capacity toward Southeast Asian basins while India's DGCA tightens pilot certification standards, creating a bifurcated market where safety compliance separates contract winners from marginal operators.
Growth Catalysts
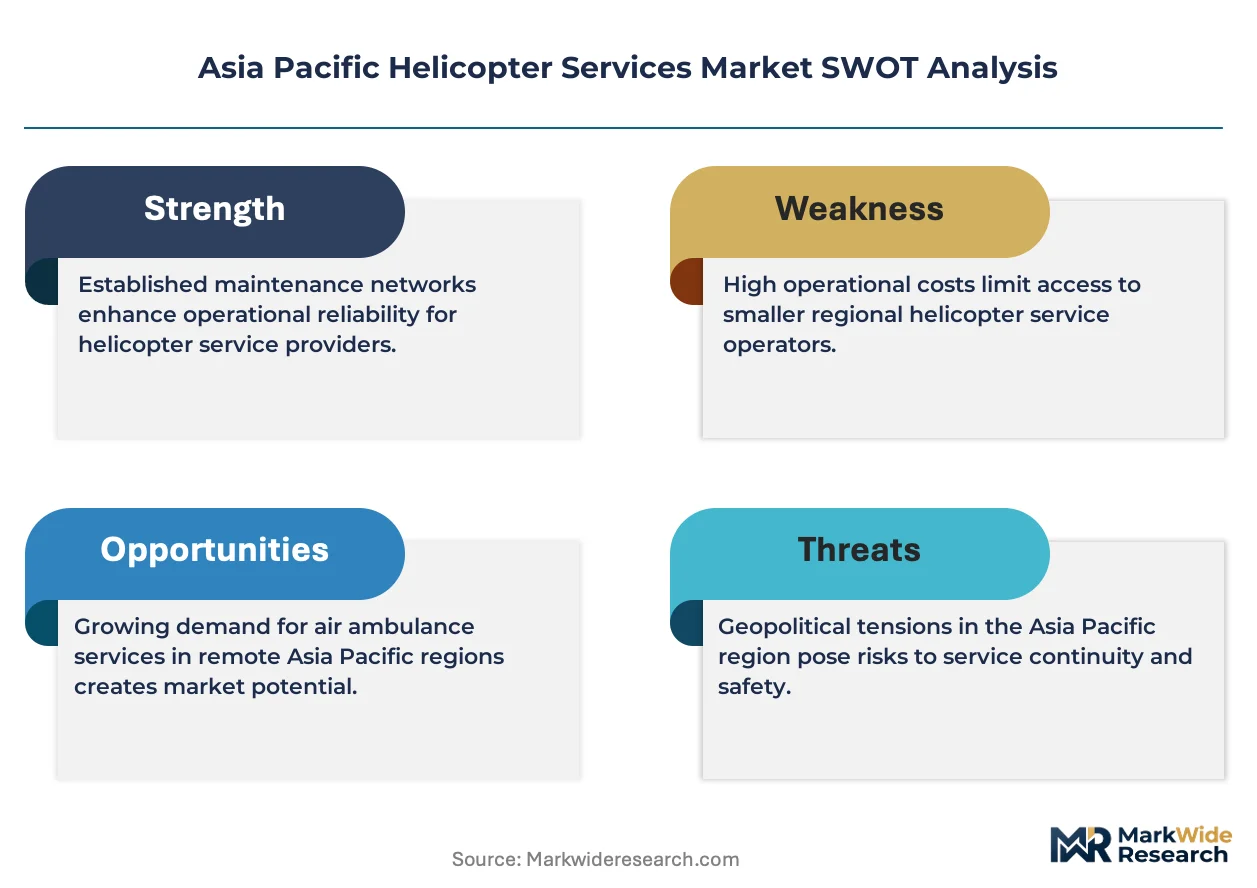
- Offshore energy expansion:Exploration blocks in the South China Sea and Bay of Bengal require crew-change logistics for platforms beyond 150 nautical miles from shore, sustaining demand for twin-engine rotorcraft with extended range tanks.
- Australia's Civil Aviation Safety Authority fatigue rules:Mandated rest-period minimums for offshore crews have professionalized workforce management, reducing accident rates and lowering insurance premiums for compliant operators.
- Island connectivity mandates:Japan's METI subsidizes essential air service routes to remote prefectures, guaranteeing revenue streams for operators serving Okinawa and Hokkaido communities lacking fixed-wing alternatives.
Market Restraints
- Jet fuel price volatility:Turboshaft engines burn 200-400 liters per hour, exposing operators to Singapore Jet Kerosene benchmark swings that compress margins on fixed-price charter contracts.
- Airframe supply concentration:Final assembly lines in France, Germany, and the United States control availability of super-medium and heavy-lift platforms, creating delivery backlogs for Asia Pacific fleet expansion.
- Substitute vessel access:Fast crew boats and accommodation ships now serve platforms within 100 nautical miles of shore at lower per-seat costs, eroding helicopter market share in shallow-water basins.
Strategic Opportunities
- Vietnam's unpenetrated offshore wind sector:Planned gigawatt-scale floating wind farms in the South China Sea will require construction-phase lift services and long-term maintenance access currently served by no established operator.
- Medical evacuation network gaps:Indonesia's archipelago geography leaves 17,000 islands without emergency aeromedical retrieval, presenting white-space for dedicated air ambulance services with IFR-certified rotorcraft.
- China's MIIT domestic manufacturing incentives:Local content requirements for rotorcraft assembly are creating partnership opportunities between foreign OEMs and state-owned aviation groups for co-produced civil models.
Industry Challenges
- Simulator-qualified pilot shortages:India's DGCA mandates 50 hours of simulator training for offshore certification, but the subcontinent hosts only three Level-D full-flight simulators, creating training bottlenecks.
- Type certification timelines:China's CAAC airworthiness validation for new rotorcraft models averages 18-24 months longer than FAA or EASA equivalents, delaying fleet modernization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Helicopter Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Charter, Cargo Transport, Medical Evacuation, Surveillance End User: Government, Oil & Gas, Emergency Services, Tourism Configuration: Single Engine, Twin Engine, Multi-Role, Heavy Lift Client Type: Corporate, Private, Military, Commercial |
| Companies Covered | Babcock International Group Plc, Airbus Helicopters, Bristow Group Inc., Hindustan Aeronautics Limited, Bell Textron, Petroleum Helicopters International Inc., CITIC Offshore Helicopter Co. Ltd., Kawasaki Heavy Industries Ltd., CHC Helicopter Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Helicopter Services Market Trends and Innovations
Digital flight data monitoring and predictive maintenance algorithms are compressing unscheduled downtime while regulatory bodies across the Asia Pacific region mandate real-time tracking for over-water operations, reshaping how operators justify fleet renewal decisions.
Health and usage monitoring systems (HUMS) installed on main gearboxes and turbine modules are rewriting maintenance economics for offshore fleet operators. Australian mining houses now require HUMS-equipped aircraft for all precision sling-load contracts, forcing charter providers to retrofit legacy airframes or exit the segment. The technology is compressing the acceptable age of competitive fleet assets from 15 years to under 8 years.
Japan's METI noise abatement standards for urban heliports now require continuous descent approaches and curfew compliance for aircraft over 6,000 kg maximum takeoff weight. Industrial consequence includes route consolidation around four approved metropolitan vertiports, concentrating traffic and favoring operators with established slot allocations. Medical evacuation providers are responding by acquiring lighter single-engine platforms exempt from the strictest decibel limits.
Resource sector buyers in Australia and Indonesia are unbundling maintenance contracts from flight-hour agreements, separately sourcing component-overhaul services from third-party MRO providers. This procurement fragmentation is disrupting the traditional bundled-service model that sustained incumbent operators for decades. The shift is most visible in Western Australia's Pilbara iron ore region, where mining houses now tender maintenance and flight operations as distinct work packages.
Asia Pacific Helicopter Services Market Segmentation
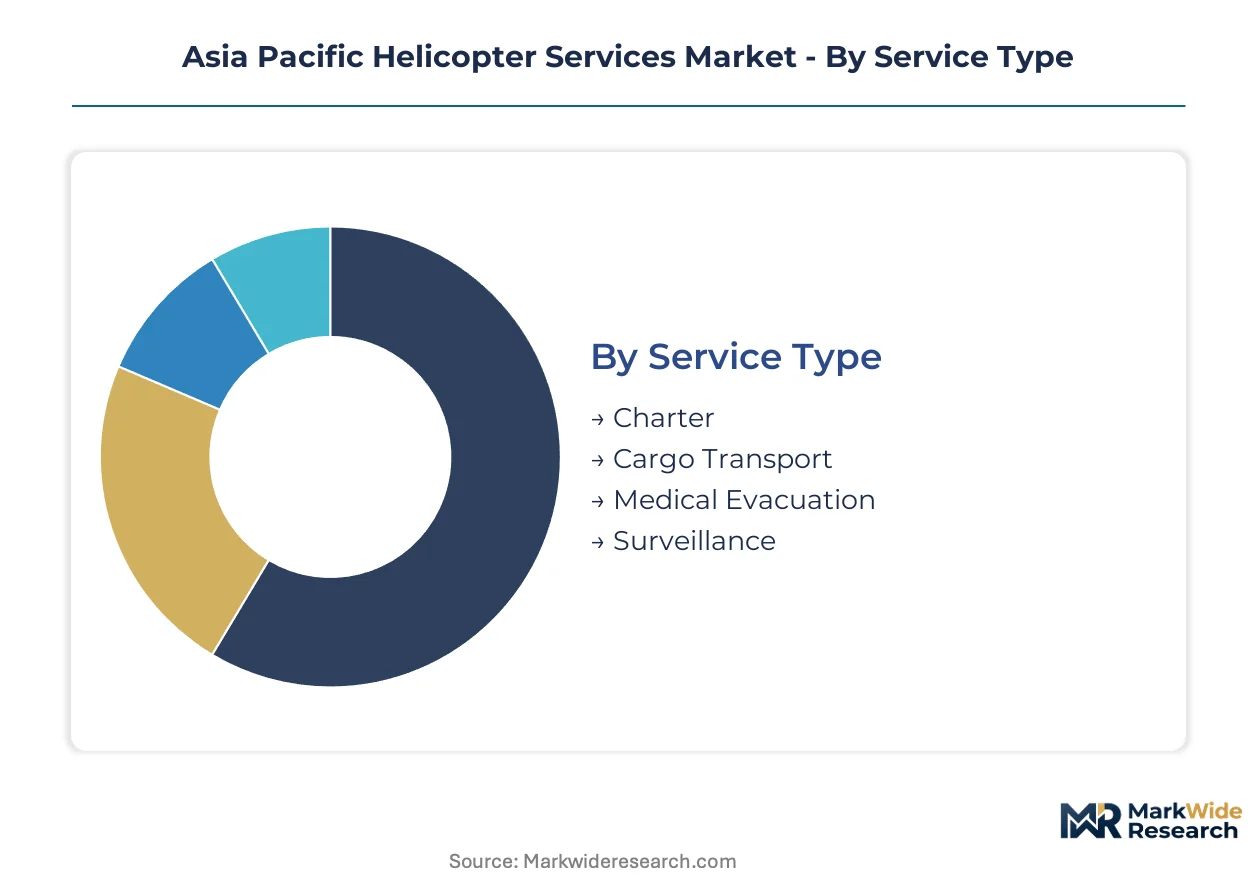
Asia Pacific helicopter services fragment across mission profiles, airframe configurations, and client procurement models. Each dimension carries distinct certification burdens from CASA, DGCA, METI, and CAAC that reshape operator economics and competitive positioning.
Service Type:
DGCA mandates 50 simulator hours for offshore certification, while METI noise abatement rules exempt lighter aircraft from urban curfews—certification density varies sharply across these service lines.
- Charter:Crew-change logistics for oil platforms and mining camps dominate revenue, with twin-engine IFR certification required for operations beyond 150 nautical miles from shore. Australian mining houses in the Pilbara and Queensland coal corridors sustain the largest contract volumes.
- Medical Evacuation:Specialized aeromedical equipment and crew certification command premium rate structures. Indonesia's 17,000-island geography concentrates demand where fixed-wing infrastructure is absent, particularly in Eastern Indonesia and Papua.
- Cargo Transport:Precision external load operations for construction and resource logistics.
- Surveillance:Border patrol and maritime monitoring missions requiring electro-optical sensor integration.
Leading the category by volume: Charter. Growing fastest: Medical Evacuation.
End User:
Procurement patterns diverge between state-backed guaranteed revenue streams and volatile commodity-linked contracts.
- Oil & Gas:Exploration blocks in Malaysia's Sarawak basin and Indonesia's Natuna Sea pull heavy-lift capacity toward Southeast Asian deepwater frontiers. CASA fatigue management mandates professionalize workforce standards, reducing insurance premiums for compliant operators.
- Government:Japan's METI subsidizes essential air service routes to Okinawa and Hokkaido prefectures, guaranteeing revenue streams regardless of passenger load factors.
- Emergency Services:State-funded aeromedical retrieval networks with dedicated aircraft and crew.
- Tourism:Scenic and adventure charter operations tied to seasonal demand fluctuations.
Highest contract security: Government. Steepest expansion trajectory: Oil & Gas.
Configuration:
Airframe selection directly determines route permissions, payload economics, and regulatory compliance tiers.
- Twin Engine:Redundancy for over-water and high-altitude missions is capturing expanded share as operators prioritize safety margins. Australia's offshore oil sector and Japan's island routes mandate twin-engine capability for extended over-water legs.
- Heavy Lift:External load capacity up to 11 metric tons maximum takeoff weight serves construction and resource logistics. Western Australia's iron ore region and Vietnam's emerging offshore wind sector concentrate demand for sling-load precision.
- Single Engine:Lower operating costs for short-haul and training missions.
- Multi-Role:Modular mission equipment enabling rapid reconfiguration between passenger and cargo duty.
Dominant by fleet value: Twin Engine. Fastest technology refresh: Heavy Lift.
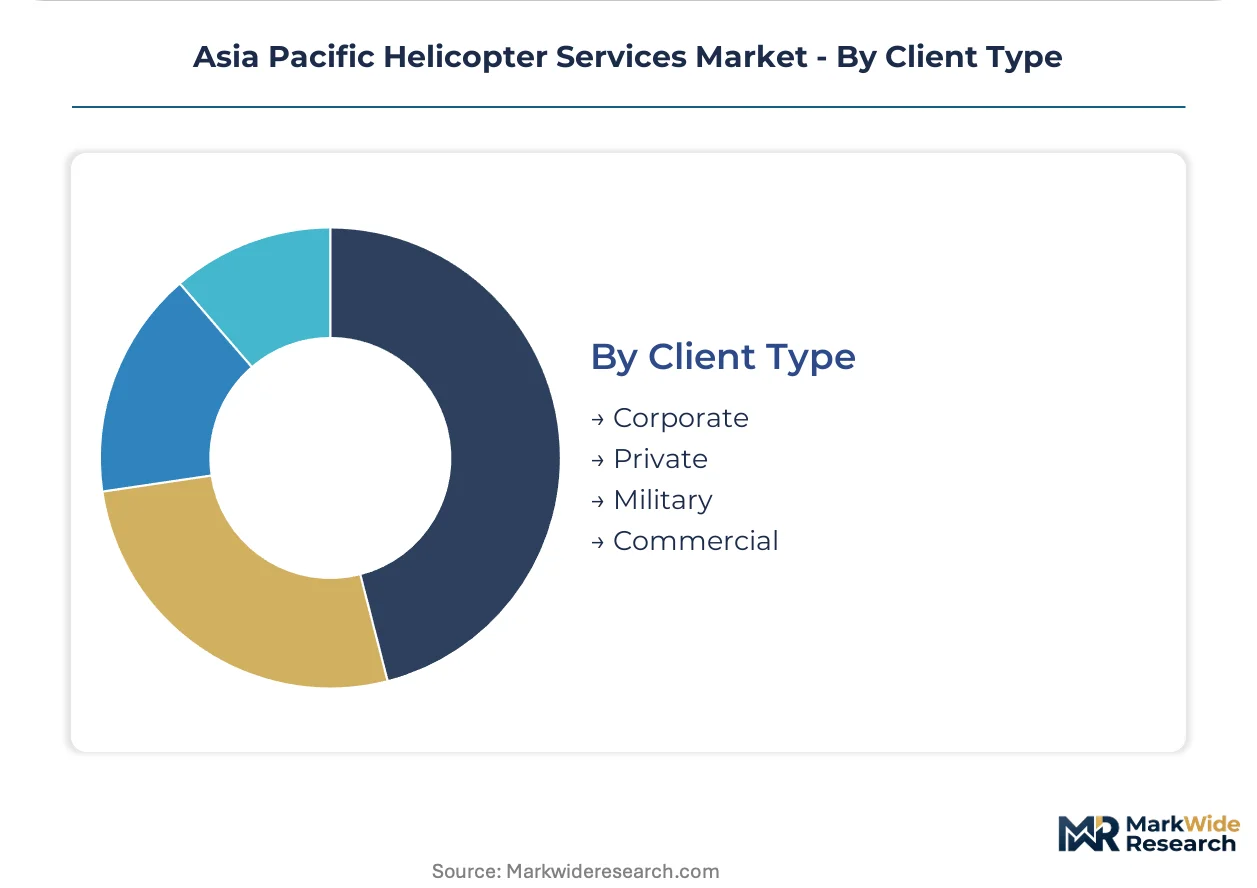
Client Type:
Contract structures and payment terms fragment across procurement sophistication levels.
- Corporate:Mining and energy majors unbundle maintenance from flight-hour agreements, separately sourcing MRO services. This procurement fragmentation disrupts traditional bundled-service models in Western Australia's Pilbara region.
- Military:Indigenous supply requirements and offset obligations shape vendor selection, with Hindustan Aeronautics Limited dominating Indian paramilitary procurement.
- Commercial:Third-party charter brokers and tourism operators on thin margin structures.
- Private:Individual ownership and fractional arrangements with limited fleet scale.
Most price-sensitive: Commercial. Longest contract tenures: Military.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's Iskandar Malaysia Special Economic Zone concentrates heavy-lift helicopter maintenance capacity near Singapore's offshore energy corridor. Australia's Pilbara region and Indonesia's Natuna Sea exploration blocks anchor twin-engine fleet deployment across Southeast Asian basins.
Australia
Western Australia's iron ore mining corridors sustain the region's largest contract volumes for precision sling-load operations. CASA mandates fatigue management systems for offshore crews, professionalizing workforce standards and reducing insurance premiums for compliant operators. The Pilbara region concentrates demand where mining houses unbundle maintenance from flight-hour agreements.
China
CAAC airworthiness validation timelines averaging 18-24 months longer than FAA equivalents delay fleet modernization programs for domestic operators. MIIT industrial policy promotes domestic rotorcraft manufacturing through local content requirements for assembly partnerships. The Yangtze River Delta hosts localized final assembly lines serving civil aviation demand.
India
DGCA mandates 50 hours of simulator training for offshore certification, creating bottlenecks with only three Level-D full-flight simulators available across the subcontinent. Tightening pilot training hours and equipment certification standards pivot the cost-of-entry calculus for new operators. Maharashtra and Gujarat coastal zones concentrate offshore oil and gas crew-change demand.
Japan
METI subsidizes essential air service routes to Okinawa and Hokkaido prefectures, guaranteeing revenue streams regardless of passenger load factors. Noise abatement standards for urban heliports require continuous descent approaches and curfew compliance for aircraft over 6,000 kg. Tokyo and Osaka metropolitan vertiports concentrate traffic around four approved metropolitan facilities.
Indonesia
The Natuna Sea exploration blocks pull heavy-lift capacity toward deepwater frontiers beyond 150 nautical miles from shore. Archipelago geography leaves 17,000 islands without emergency aeromedical retrieval, presenting white-space for dedicated air ambulance services. Eastern Indonesia and Papua concentrate demand where fixed-wing infrastructure is absent.
Asia Pacific Helicopter Services Market Competitive Landscape
European OEMs anchor one tier; Asia-Pacific state-linked specialists hold contract security through indigenous supply requirements. The vendor base fragments between vertically integrated service providers and pure-play charter operators. Three archetypes dominate: defense-industrial conglomerates with captive military demand, offshore energy specialists with bundled maintenance capabilities, and state-owned aviation groups with domestic manufacturing mandates. Competitive intensity centers on M&A consolidation of regional charter networks and strategic partnerships for localized assembly.
Within the defense-industrial tier, Hindustan Aeronautics Limited occupies a position exemplifying indigenous military and paramilitary supply dominance. Babcock International Group Plc represents the vertically integrated service archetype, leveraging in-house maintenance and training capabilities to sustain contract renewals. Airbus Helicopters anchors the OEM-localization archetype through established final assembly presence in China and Malaysia. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positions across the region's bifurcated safety-compliance market.
| Leading Market Players |
|---|
| Babcock International Group Plc |
| Airbus Helicopters |
| Bristow Group Inc. |
| Hindustan Aeronautics Limited |
| Bell Textron |
| Petroleum Helicopters International Inc. |
| CITIC Offshore Helicopter Co. Ltd. |
| Kawasaki Heavy Industries Ltd. |
| CHC Helicopter Group |
| Others |
Pricing and Supply Chain Analysis
Singapore Jet Kerosene benchmark volatility cascades through Asia Pacific helicopter services, compressing margins on fixed-price charter contracts and forcing operators toward fuel surcharge mechanisms or longer-term offtake agreements with integrated energy suppliers.
Pricing Analysis
Lead-time-driven pricing stratifies across premium, standard, and economy tiers, with spot availability commanding surcharges against contracted block-hour rates. Price differentiation hinges on airframe age brackets and HUMS equipment certification, with Australian mining houses penalizing non-compliant operators through contract exclusion. Cost compression in the single-engine segment intensifies as fast crew boats erode shallow-water market share. Commercial charter brokers exhibit acute price sensitivity, while government-subsidized island connectivity routes in Japan absorb rate premiums without volume risk.
Supply Chain Analysis
Direct-to-operator channels handle fleet procurement for Australian mining majors and Southeast Asian offshore energy contractors, bypassing distributor markups on heavy-lift platforms. Final assembly concentrates in France, Germany, and the United States, creating delivery backlogs for Asia Pacific expansion. Turboshaft engines and main gearbox assemblies draw from concentrated aerospace supplier networks in the United States and United Kingdom. Single-source vulnerability in super-medium airframe availability poses structural risk, with CAAC validation timelines extending procurement cycles. Distribution runs through OEM-owned service centers and third-party MRO facilities clustered around Singapore and Australia's Iskandar Malaysia zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific helicopter services represent a consolidation play where DGCA safety compliance mandates and CAAC certification delays are forcing marginal operators toward distressed exit or acquisition.
For Market Incumbents: Lock in contract renewals through captive maintenance capabilities and simulator training infrastructure, as India's three Level-D simulator bottleneck creates retention leverage. Babcock International Group Plc exemplifies this model through backward integration into MRO and crew certification. Prioritize HUMS retrofit programs to meet Australian mining house procurement mandates and compress competitor fleet age advantages. For New Entrants and Emerging Players: METI noise abatement exemptions for aircraft under 6,000 kg in Japan open a window for single-engine medical evacuation specialists to secure urban heliport access denied heavier competitors. Indonesia's 17,000-island aeromedical gap presents the most penetrable white-space, with IFR-certified rotorcraft and local base establishment as the critical go-to-market angle. Vietnam's unpenetrated offshore wind construction lift market offers early-mover positioning before established operators deploy capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated service providers with Australian mining contracts and simulator assets in India, as DGCA training mandates compound competitive moats. Long-term viability centers on operators with government-guaranteed revenue streams buffering commodity volatility. Watch CAAC-MIIT domestic manufacturing partnership announcements as inflection indicators for foreign OEM localization strategies and co-production joint venture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Simulator Infrastructure Investment | DGCA-mandated training hours create captive revenue streams and contract retention leverage. |
| HUMS Fleet Retrofit Program | Australian mining procurement rules now require health monitoring for precision sling-load contracts. |
| Offshore Wind Partnership | Vietnam's gigawatt-scale floating wind farms lack established construction-phase lift operators. |
| CAAC Localization Joint Venture | MIIT industrial policy incentivizes foreign OEM assembly partnerships with state aviation groups. |
| Essential Air Service Route Acquisition | METI subsidies guarantee revenue regardless of passenger load factors in Japan's remote prefectures. |
Research Methodology
Independent corroboration across CASA regulatory filings, DGCA certification databases, and METI subsidy disbursement records underwrites the qualitative findings. Primary interviews with offshore energy logistics managers, aeromedical program directors, mining house procurement leads, and helicopter OEM regional executives combined with secondary validation from CAAC airworthiness directives, IEA energy exploration databases, and customs import records for rotorcraft assemblies. Bottom-up fleet deployment tracking and top-down contract value estimation triangulate market sizing across service type, configuration, and end user dimensions.
Rate-of-change decomposition separates volume expansion from price and mix effects across the projection horizon. Segmentation modeling incorporates service type, airframe configuration, end user industry, and client procurement sophistication, with CAGRs derived from contract renewal trajectories and fleet replacement cycles. Forecast inputs include offshore energy block award timelines, CAAC type certification pipeline status, and METI essential air service route tender schedules.
The model assumes a particular technology adoption path for health and usage monitoring systems; alternative pathways for predictive maintenance algorithm integration would alter the outlook for fleet age competitiveness and MRO contract unbundling. Forecasts reflect assumptions regarding regulatory enforcement intensity and bilateral air service negotiation outcomes. Periodic stress-testing of base assumptions against fuel price volatility and airframe delivery backlog developments is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Flying Taxi Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
Asia-Pacific Charter Jet Service Market
Air Mobility
South America Offshore Helicopter Services Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Hang Glider Market
Air Mobility
Flying Motorbikes Market
Air Mobility
Asia-Pacific Military Aviation Market
Air Mobility
Urban Air Mobility (UAM) Market
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
Off-Shore Helicopters Market
Air Mobility
Global Aerodynamics Market