
 Asia-Pacific Military Aviation Market | 2026-2036
Asia-Pacific Military Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Military Aviation Market Outlook
Carbon-fiber reinforced polymer is repositioning fuselage economics across the Asia-Pacific Military Aviation Market. Aviation Industry Corporation of China leverages captive composites manufacturing to reduce airframe weight on fifth-generation platforms. Hindustan Aeronautics Limited anchors India's Tejas program through in-house superalloy casting and avionics integration. Korea Aerospace Industries competes on trainer and light-attack exports by sustaining aggressive R&D-to-production cycles.
Asia-Pacific military aviation encompasses manned and unmanned fixed-wing and rotary-wing platforms engineered for combat, transport, surveillance, and training missions, typically operating at Mach 0.8 to Mach 2.5 with service ceilings exceeding 50,000 feet and incorporating radar-absorbent materials, fly-by-wire controls, and integrated electronic warfare suites. Fighter aircraft command the largest share of procurement budgets as territorial disputes drive multirole platform acquisitions across the region. Unmanned Aerial Vehicles represent the fastest-expanding product category, with surveillance and strike missions displacing manned sorties in contested airspace. Electronic Warfare technology captures concentrated margin pools as spectral dominance becomes prerequisite for platform survivability.
China's MIIT enforces GB standards on avionics interoperability and emissions benchmarks that filter supplier participation. India's CEA and DGFT coordinate import-substitution rules through the PLI scheme, mandating local content thresholds for defense contracts. Australia's TGA-equivalent defense certification body and South Korea's DAPA procurement standards further fragment compliance requirements across national boundaries. Stakeholders must map regulatory divergence before committing to platform architectures or partnership structures.
Market Dynamics
China's dual carbon goals are redirecting propulsion system investments across the Asia-Pacific Military Aviation Market, forcing airframers to reengineer thermal management architectures and supplier qualification protocols around hybrid-electric benchmarks.
Growth Catalysts
- PLI Scheme Mandates:India's DGFT local content thresholds are forcing foreign OEMs to onshore avionics integration and superalloy casting capabilities, expanding the domestic supplier base.
- GB Standards Enforcement:China's MIIT emissions benchmarks on military propulsion systems are accelerating R&D spend on adaptive cycle engines and thermal barrier coatings.
- Carbon-Fiber Economies:Captive composites manufacturing at state-owned airframers is reducing airframe weight penalties and extending unrefueled range on multirole platforms.
Market Restraints
- Superalloy Supply Concentration:Nickel-cobalt feedstock dependence on single-source refiners in Russia creates input volatility for turbine blade foundries.
- Technical Limitation:Thermal management bottlenecks in hybrid-electric architectures cap power density gains below 12 kW/kg, constraining fighter performance envelopes.
- Regulatory Friction:Divergent DAPA and TGA-equivalent certification timelines fragment platform qualification, delaying cross-border fleet commonality.
Strategic Opportunities
- Underpenetrated Geography:Vietnam's coastal defense modernization is opening procurement channels for maritime patrol and light-attack rotary platforms.
- Technology Convergence:AI-driven predictive maintenance fused with spectral electronic warfare suites is creating integrated mission-system architectures.
- Regulatory Tailwind:Australia's sovereign guided weapons enterprise is channeling defense procurement toward domestic missile integration on manned-unmanned teaming platforms.
Industry Challenges
- Talent Scarcity:Systems engineering expertise in fly-by-wire control laws and radar-absorbent materials processing remains concentrated at legacy state enterprises.
- Capex Intensity:Cleanroom composite autoclave capacity and electron-beam welding infrastructure require decade-long depreciation cycles, freezing mid-tier supplier entry.
- Integration Complexity:Legacy analog avionics in Southeast Asian fleets resist seamless retrofit with digital mission computers, forcing costly bridge architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Military Aviation Market |
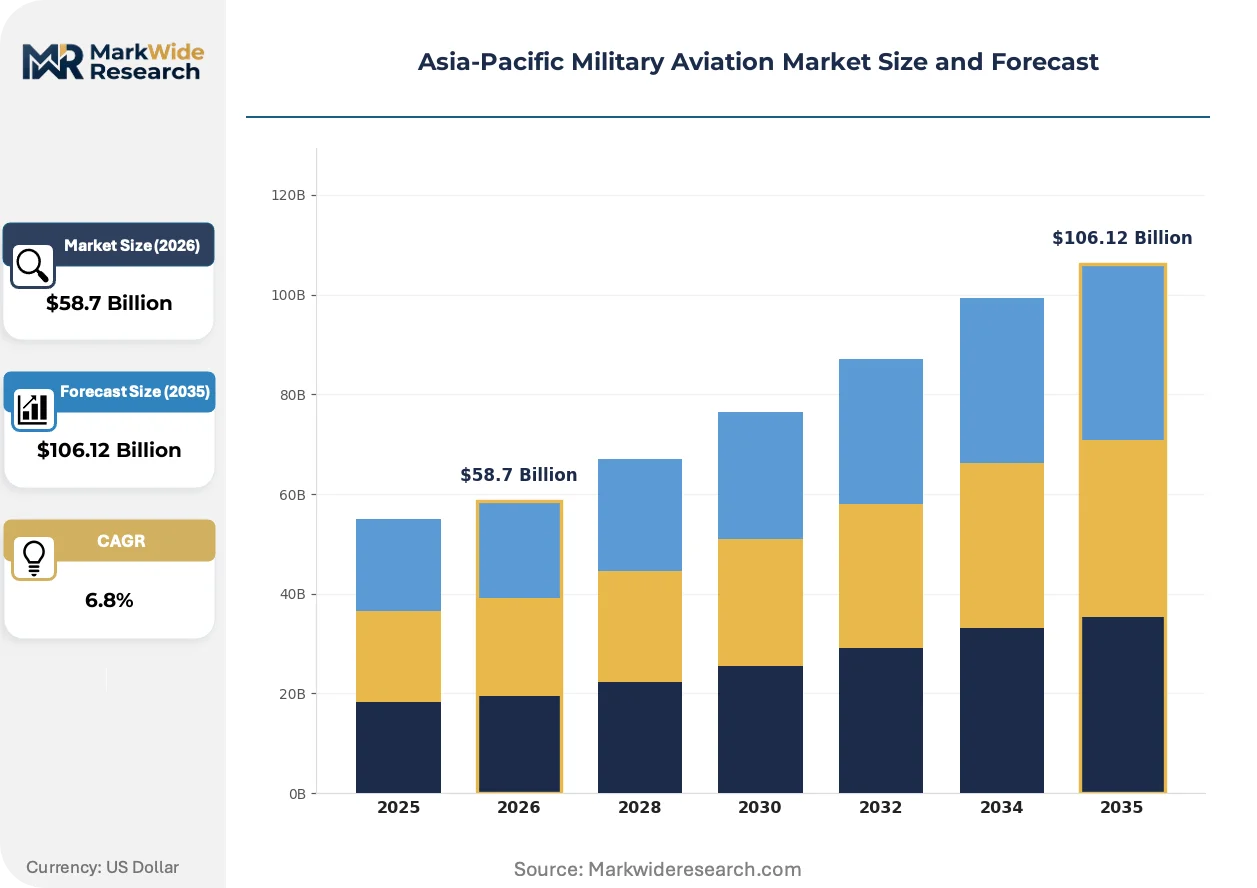
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fight Aircraft, Helicopters, Unmanned Aerial Vehicles, Transport Aircraft End User: Air Force, Navy, Army, Security Agencies Technology: Electronic Warfare, Avionics, Propulsion Systems, Surveillance Systems Application: Reconnaissance, Transport, Combat, Training |
| Companies Covered | Aviation Industry Corporation of China, Ltd, Hindustan Aeronautics Limited, Korea Aerospace Industries, Lockheed Martin Corporation, The Boeing Company, Airbus SE, Dassault Aviation, Northrop Grumman Corporation, BAE Systems plc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Military Aviation Market Strategic Shifts
Active electronically scanned array technology is compressing radar development cycles while unmanned teaming architectures rewrite pilot training and platform acquisition economics across regional air forces.
GaN-based transmit-receive modules are overtaking GaAs predecessors in fighter radar applications. Republic of Korea Air Force procurement specifications now mandate GaN for all new fire-control arrays. This semiconductor transition is enabling simultaneous multi-target tracking while reducing cooling loads and aperture size constraints on stealth airframes.
China's MIIT GB standards on avionics interoperability are mandating open-architecture bus protocols across all new military aircraft programs. Foreign subsystem suppliers must port software stacks to domestic operating environments to maintain platform integration eligibility. Korean and Australian defense primes are responding by establishing joint software verification labs in Chengdu and Xi'an.
Air forces are consolidating maintenance, repair, and overhaul contracts under long-term availability agreements rather than transactional spare-part purchases. Royal Australian Air Force F-35 sustainment contracts now embed performance-based logistics clauses tying contractor payments to fleet availability rates. This shift transfers operational risk to primes while compressing margins on traditional component aftermarket sales.
Asia-Pacific Military Aviation Market Segmentation
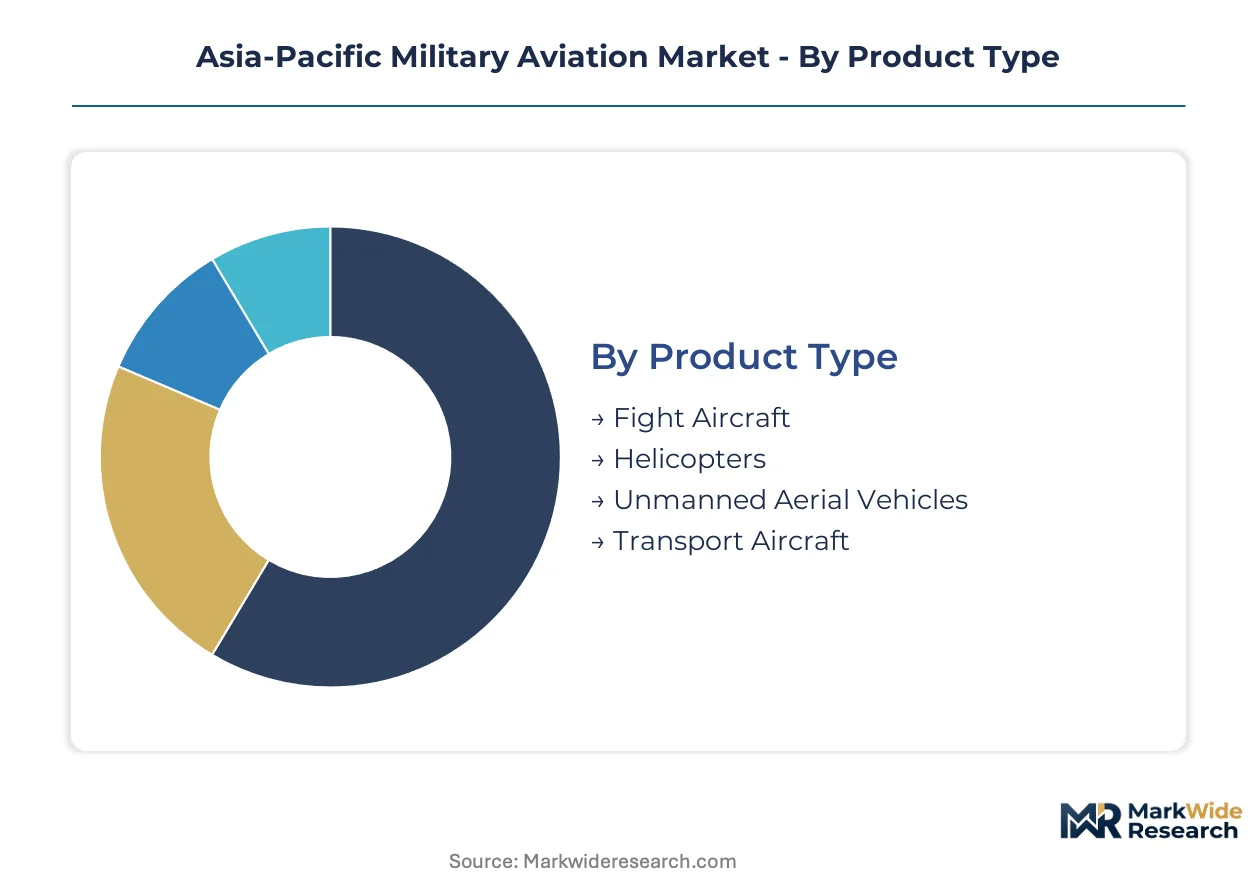
Segmentation reveals how procurement budgets fragment across mission profiles and platform generations. Understanding these splits exposes where supplier margins concentrate and where indigenization mandates reshape competitive access.
Product Type:
Acquisition priorities diverge sharply between crewed combat platforms and autonomous systems, with range-payload tradeoffs driving fleet composition decisions across regional air forces.
- Fighter Aircraft:Multirole platforms operating at Mach 0.8 to Mach 2.5 with service ceilings exceeding 50,000 feet absorb the dominant share of procurement budgets. India's Tejas program and Korea's KF-21 anchor regional indigenization drives as territorial disputes accelerate fleet modernization timelines.
- Unmanned Aerial Vehicles:Surveillance and strike missions are displacing manned sorties in contested airspace, with rotary-wing and fixed-wing variants penetrating at lower unit costs. China's captive composites manufacturing reduces airframe weight penalties on long-endurance designs.
- Helicopters:Light-attack and utility rotary platforms serve coastal defense and mountain warfare requirements.
- Transport Aircraft:Strategic and tactical airlift capabilities support expeditionary logistics across archipelagic geographies.
Volume sits with Fighter Aircraft; growth tilts toward Unmanned Aerial Vehicles.
End User:
Service branch procurement autonomy creates fragmented qualification pathways, with each operator imposing distinct interoperability standards.
- Air Force:Dominant procurement authority for multirole fighters and strategic surveillance platforms. Australia's sovereign guided weapons enterprise channels investment toward manned-unmanned teaming architectures under long-term availability agreements.
- Navy:Carrier-based fighter procurement and maritime patrol aircraft drive specialized platform requirements. India's defense corridors concentrate indigenization mandates for naval rotary-wing programs.
- Army:Tactical transport and close air support missions shape utility helicopter acquisitions.
- Security Agencies:Border surveillance and internal security applications sustain demand for light fixed-wing and unmanned platforms.
Procurement volume concentrates at Air Force; Navy spending is climbing fastest on maritime patrol modernization.
Technology:
Subsystem differentiation determines platform survivability and export competitiveness, with semiconductor transitions and thermal management architectures commanding R&D priority.
- Electronic Warfare:Spectral dominance capabilities capture concentrated margin pools as GaN-based transmit-receive modules overtake GaAs predecessors. Republic of Korea Air Force specifications now mandate GaN for all new fire-control arrays, enabling simultaneous multi-target tracking while reducing cooling loads.
- Propulsion Systems:Adaptive cycle engines and thermal barrier coatings absorb redirected investment under China's MIIT emissions benchmarks. Hybrid-electric architectures face thermal management bottlenecks capping power density gains below operational thresholds for fighter applications.
- Avionics:Open-architecture bus protocols mandated by GB standards force foreign subsystem suppliers to port software stacks to domestic operating environments.
- Surveillance Systems:Active electronically scanned array technology compresses radar development cycles across regional programs.
Revenue pools concentrate in Electronic Warfare; Propulsion Systems R&D is expanding most quickly on hybrid-electric benchmarks.
Application:
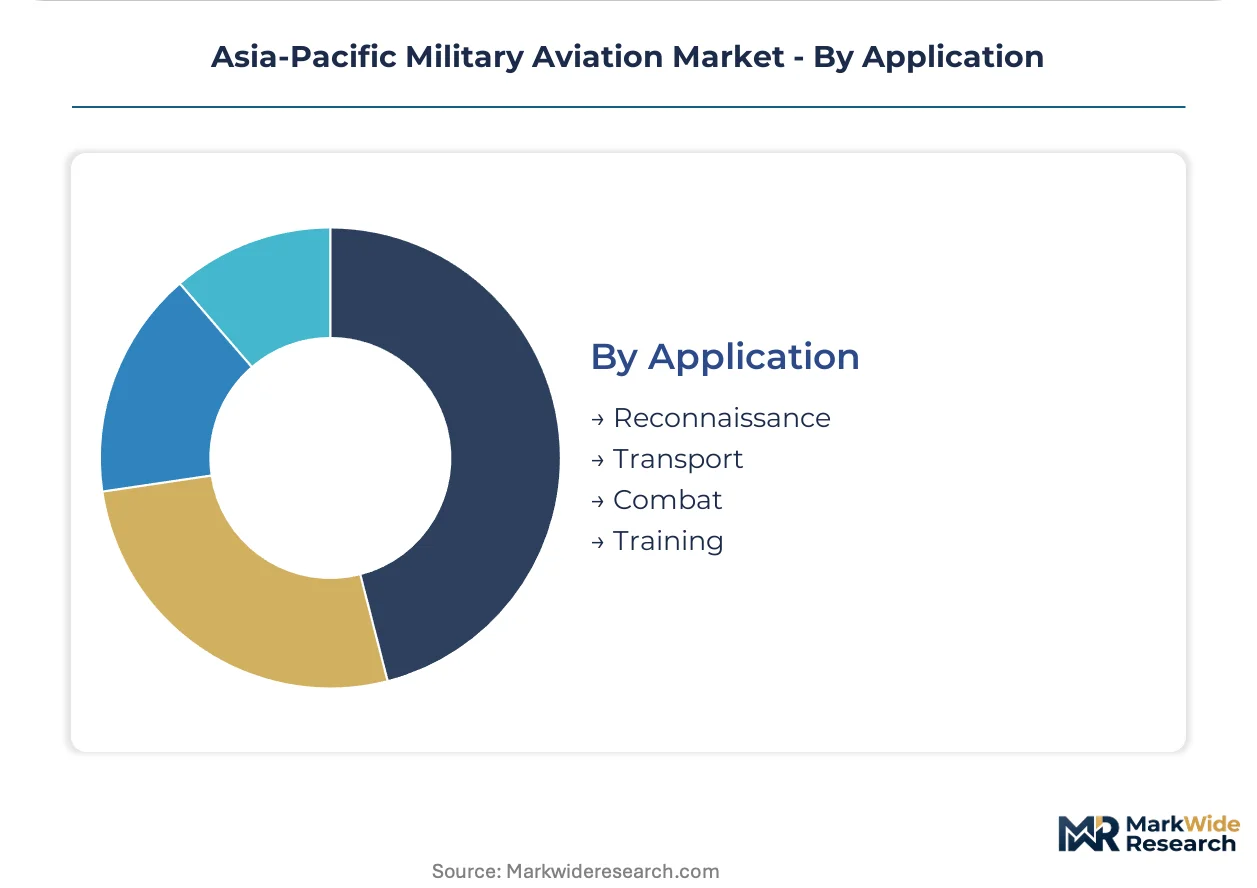
Mission type dictates platform specification intensity and through-life support economics, with training and reconnaissance segments presenting contrasting margin profiles.
- Combat:Multirole strike and air superiority missions drive specification intensity on fifth-generation platforms. Radar-absorbent materials and fly-by-wire controls anchor capability differentiation as China's dual carbon goals redirect thermal management investments.
- Training:Pilot pipeline requirements sustain demand for advanced jet trainers and light-attack derivatives. Korea Aerospace Industries competes on aggressive R&D-to-production cycles for export markets.
- Reconnaissance:Persistent surveillance missions shift toward unmanned architectures as manned sorties face contested airspace constraints.
- Transport:Strategic and tactical airlift applications support humanitarian and expeditionary operations across disaster-prone geographies.
Platform count peaks in Training; Combat applications command the steepest unit cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's defense corridors concentrate procurement authority for multirole fighters and naval rotary-wing programs, while China's captive composites manufacturing anchors fifth-generation platform development. Territorial disputes across the South China Sea and Himalayan frontier are accelerating fleet modernization timelines from Seoul to Canberra.
China
Dual carbon goals enforced by MIIT are redirecting propulsion system investments toward hybrid-electric architectures and adaptive cycle engines. GB standards on avionics interoperability mandate open-architecture bus protocols that filter foreign subsystem supplier participation. Aviation Industry Corporation of China leverages captive composites manufacturing in Chengdu and Xi'an to reduce airframe weight on stealth platforms.
India
Indigenization mandates through the PLI scheme are forcing foreign OEMs to onshore avionics integration and superalloy casting capabilities. CEA and DGFT coordinate import-substitution rules that mandate local content thresholds for defense contracts. Hindustan Aeronautics Limited anchors the Tejas program through in-house foundry and integration facilities concentrated in Bangalore and Hyderabad defense corridors.
South Korea
Republic of Korea Air Force procurement specifications now mandate GaN-based transmit-receive modules for all new fire-control arrays, enabling simultaneous multi-target tracking. DAPA procurement standards create fragmented compliance requirements that delay cross-border fleet commonality. Korea Aerospace Industries sustains aggressive R&D-to-production cycles on trainer and light-attack platforms from Sacheon.
Australia
Royal Australian Air Force F-35 sustainment contracts embed performance-based logistics clauses that transfer operational risk to primes. The sovereign guided weapons enterprise channels defense procurement toward domestic missile integration on manned-unmanned teaming platforms. TGA-equivalent defense certification timelines fragment platform qualification with regional partners.
Vietnam
Coastal defense modernization is opening procurement channels for maritime patrol and light-attack rotary platforms as territorial disputes intensify. Technical limitations in legacy analog avionics resist seamless retrofit with digital mission computers, forcing costly bridge architectures. Russian-origin fleet sustainment dependencies create procurement diversification pressure toward Western and regional suppliers.
Asia-Pacific Military Aviation Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with state-owned airframers commanding captive supply chains while foreign primes compete on subsystem integration. The vendor base concentrates around three strategic archetypes: vertically integrated national champions with in-house composites and foundry capacity; technology licensors leveraging defense offset agreements for market access; and component specialists capturing margin pools in electronic warfare and thermal management. Competitive moves center on joint software verification labs in Chinese industrial clusters and long-term availability agreements that compress traditional aftermarket margins.
Among state-owned national champions, Aviation Industry Corporation of China, Ltd. exemplifies the vertically integrated archetype through captive composites manufacturing. Hindustan Aeronautics Limited occupies a parallel position in India's defense corridors, anchoring indigenization mandates through in-house superalloy casting and avionics integration. Korea Aerospace Industries, Ltd. represents the export-oriented specialist tier, competing on aggressive R&D-to-production cycles for trainer and light-attack platforms.
| Leading Market Players |
|---|
| Aviation Industry Corporation of China, Ltd |
| Hindustan Aeronautics Limited |
| Korea Aerospace Industries |
| Lockheed Martin Corporation |
| The Boeing Company |
| Airbus SE |
| Dassault Aviation |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Others |
Value Chain & Pricing Dynamics
State-owned airframers in China and India anchor procurement volume through multi-year platform contracts, compressing supplier margins on traditional component sales while concentrating pricing power in long-term availability agreements. This buyer concentration shifts revenue recognition toward performance-based logistics clauses that tie contractor payments to fleet readiness metrics.
Pricing Analysis
Volume concentrates in fifth-generation fighter platforms while margins pool in electronic warfare subsystems and GaN-based radar components. Price differentiation rests on certification grade under GB standards and local content thresholds mandated by India's PLI scheme. Cost compression in legacy analog avionics retrofits is intensifying as Southeast Asian fleets demand digital bridge architectures. Air Force procurement programs exhibit lowest price sensitivity; security agencies and training fleet operators show highest elasticity.
Supply Chain Analysis
India's PLI scheme and China's MIIT local-content rules are forcing foreign OEMs to onshore superalloy casting and avionics integration capabilities, fragmenting supplier footprints across national boundaries. Nickel-cobalt feedstock draws from Russian refiners; carbon-fiber prepregs source from Chinese state-owned chemical complexes; GaN semiconductors hinge on Korean foundry capacity. Single-source vulnerability in nickel-cobalt supply creates input volatility for turbine blade foundries. Distribution runs through defense procurement authorities in each national market rather than commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific military aviation sector sits in a propulsion technology transition, with hybrid-electric architectures displacing conventional gas turbine development programs under China's dual carbon mandates.
For Market Incumbents: Cement captive composites manufacturing capacity in Chengdu and Xi'an industrial clusters to defend against Korean export-oriented specialists. Lock in long-term nickel-cobalt offtake agreements to hedge Russian supply concentration. Prioritize thermal management R&D to overcome power density bottlenecks capping fighter performance envelopes.
For New Entrants and Emerging Players: Enter via Vietnam's coastal defense modernization programs for maritime patrol and light-attack rotary platforms. Target software verification services for GB standards compliance as foreign subsystem suppliers port stacks to Chinese operating environments. Pursue joint venture structures with Indian defense corridor foundries to satisfy PLI local content thresholds.
For Investors and Strategic Acquirers: Distressed-cycle entries favor electronic warfare specialists with GaN module production capacity in Korean industrial parks. Long-term viability centers on spectral dominance capabilities as prerequisite for platform survivability. Watch Republic of Korea Air Force procurement specifications for GaN mandate expansion as inflection signal for semiconductor transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Software Verification Lab Establishment | Foreign subsystem suppliers gain GB standards compliance access in Chengdu and Xi'an clusters. |
| Long-Term Availability Agreement Structuring | Royal Australian Air Force F-35 sustainment contracts transfer operational risk to primes. |
| Captive Superalloy Casting Capacity Expansion | Hindustan Aeronautics Limited anchors Tejas program indigenization in Bangalore defense corridor. |
| GaN Transmit-Receive Module Production Scale-Up | Republic of Korea Air Force specifications mandate GaN for all new fire-control arrays. |
| Hybrid-Electric Thermal Management Investment | China's MIIT emissions benchmarks redirect R&D spend toward adaptive cycle engines. |
Study Parameters
Document review covered defense procurement databases, national regulatory filings under MIIT and DGFT, and platform development disclosures, complemented by interviews with airframe program managers, avionics integration leads, turbine blade foundry directors, and defense procurement officers. Secondary validation drew from customs records, DAPA procurement standards documentation, and sovereign guided weapons enterprise announcements. Bottom-up platform delivery schedules and top-down defense budget appropriations underwent cross-triangulation.
Historical delivery trajectories were cross-referenced against expert panel assessments of indigenization timeline feasibility across the projection horizon. Segmentation modeling incorporated product type, end-user service branch, technology subsystem, and application mission profile dimensions. CAGRs were derived from weighted regression of procurement budget growth against platform replacement cycles. Industry-specific inputs included thermal management architecture maturity curves and GaN semiconductor yield improvement trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel-cobalt supply disruption scenarios and Himalayan frontier escalation patterns. Forecasts reflect documented assumptions regarding PLI scheme enforcement continuity and GB standards adoption velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Mobility
Airborne Pods Market
Air Mobility
Middle East and Africa General Aviation Market
Air Mobility
Global Aerial Firefighting Market
Air Mobility
Flying Jetpacks Market
Air Mobility
Middle-East and Africa Military Aviation Market
Air Mobility
Hang Glider Market
Air Mobility
North America Offshore Helicopter Services Market
Air Mobility
Flying Taxi Market
Air Mobility
Air Transport Modifications Market
Air Mobility
Parabolic Flight Tourism Market
Air Mobility
Advanced Air Mobility Market
Air Mobility
Helicopter-Based Transportation Market
Air Mobility
Urban Autonomous Air Mobility Market
Air Mobility
North Sea Offshore Helicopter Services Market
Air Mobility
Asia-Pacific Charter Jet Service Market
Air Mobility
Urban Air Mobility (UAM) Market