
 Upstream Services Market | 2026-2036
Upstream Services Market Size, Share, and Industry Trends Forecast 2026-2036
Upstream Services Market Outlook
Market Context
The skilled petroleum engineer labor pool is collapsing across North America and the North Sea as retirements outpace university enrollments. Schlumberger Limited leverages its digital subsurface platforms to offset talent scarcity through automation. Halliburton sustains its competitive edge by anchoring manufacturing and service capacity in the Permian Basin. Baker Hughes Incorporated differentiates through proprietary drill-bit designs and integrated well-construction workflows.
Technical Definition and Segments
Upstream services encompass the technical, equipment, and labor-intensive activities required to locate, drill, complete, and produce hydrocarbons from subsurface reservoirs, typically involving pressures exceeding 10,000 psi and temperatures above 150°C in deepwater environments. Exploration services using advanced seismic imaging command premium pricing due to the capital intensity of multiclient surveys and proprietary algorithm development. Directional drilling within the technology segment is displacing conventional vertical approaches as shale operators target longer laterals to maximize recovery per wellbore. Production services remain the most mature margin pool, though enhanced oil recovery applications are gaining share as brownfield operators seek to extend plateau rates.
Regulatory Environment
The US Bureau of Safety and Environmental Enforcement mandates blowout preventer testing protocols that shape equipment procurement cycles for offshore drillers, while the EPA's methane emissions rules are forcing production service providers to retrofit pneumatic devices and flare-gas recovery systems. Brazil's ANP local-content requirements and Norway's Petroleum Safety Authority well-integrity standards create divergent compliance cost structures across Atlantic basin projects. Stakeholders must monitor how divergent decarbonization timelines between OPEC Gulf states and OECD regulators reshape capital allocation toward gas-weighted upstream portfolios.
Market Dynamics
Digital twin technology for reservoir simulation is compressing field development cycles while simultaneously reducing dependency on scarce petroleum engineering talent across mature basins.
Growth Catalysts
- Deepwater frontier expansion:Brazil's ANP production-sharing framework and Guyana's emerging basin are attracting capital commitments from international oil producers seeking reserve replacement.
- Directional drilling maturation:Extended-reach laterals in unconventional reservoirs are maximizing recovery per wellbore and reducing surface footprint requirements.
- Methane abatement mandates:EPA regulations on pneumatic device retrofits and flare-gas recovery are generating retrofit demand across Permian and Bakken production bases.
Market Restraints
- Specialized equipment supply concentration:Blowout preventer manufacturing capacity concentrates among a limited supplier base, creating procurement bottlenecks for ultra-deepwater projects.
- Steel alloy input volatility:High-grade chromium-molybdenum tubulars face price swings tied to mining output from South African and Kazakh sources.
- Local-content compliance fragmentation:Divergent ANP, NORSOK, and BSEE equipment-certification standards force operators to maintain multiple inventory pools.
Strategic Opportunities
- Pre-salt basin digitalization:Brazil's Campos and Santos basins present untapped demand for integrated subsurface-to-surface automation platforms.
- Electrification of offshore facilities:Grid-connected and floating offshore wind tie-ins are opening new power-from-shore contracting models in the North Sea.
- Carbon capture integration:Enhanced oil recovery with CO2 injection is gaining regulatory support under US IRA tax credits and EU CCS infrastructure funding.
Industry Challenges
- Petroleum engineering talent collapse:University enrollment declines in geoscience and drilling programs are outpacing retirements across Texas, Alberta, and Aberdeen clusters.
- Subsea hardware certification timelines:API and ISO 13628-7 qualification protocols for high-pressure high-temperature trees extend delivery schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Upstream Services Market |
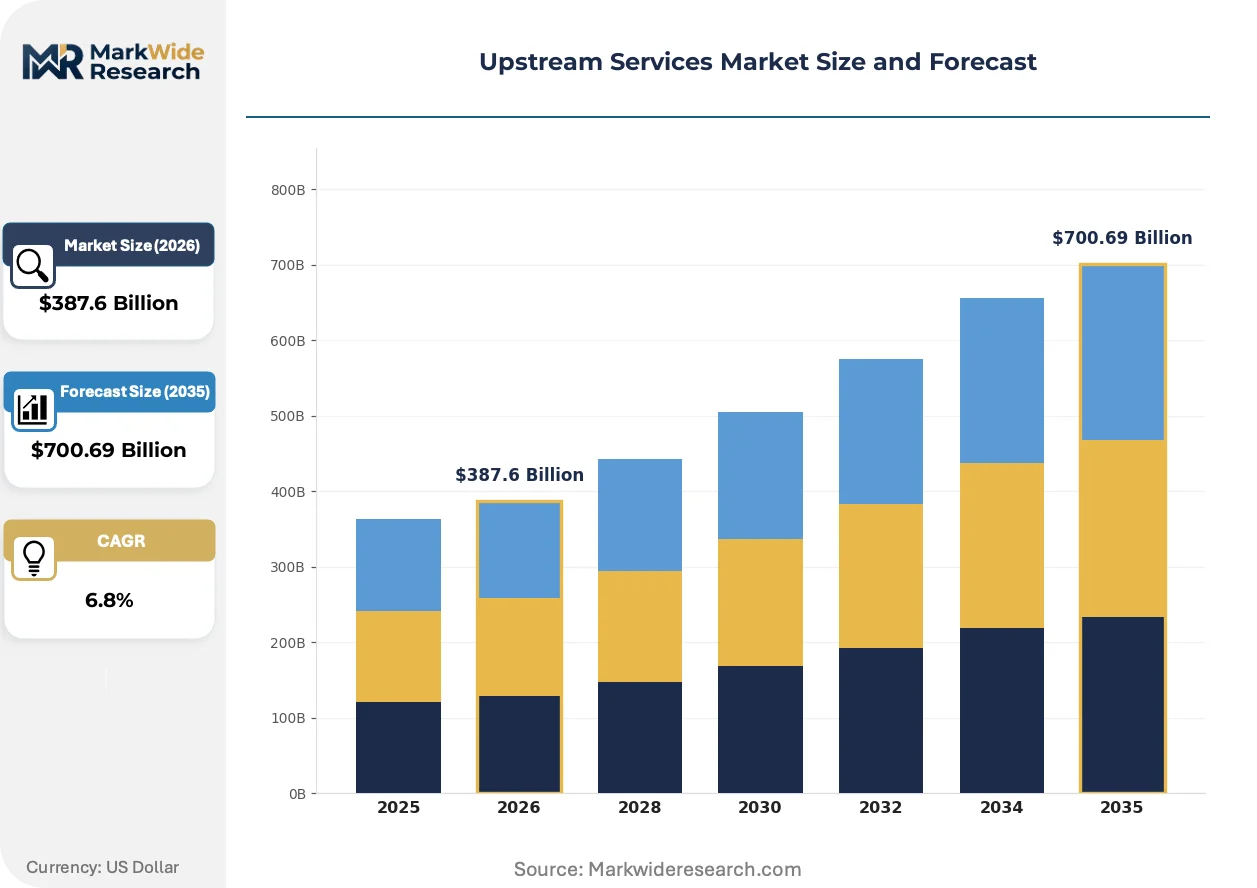
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
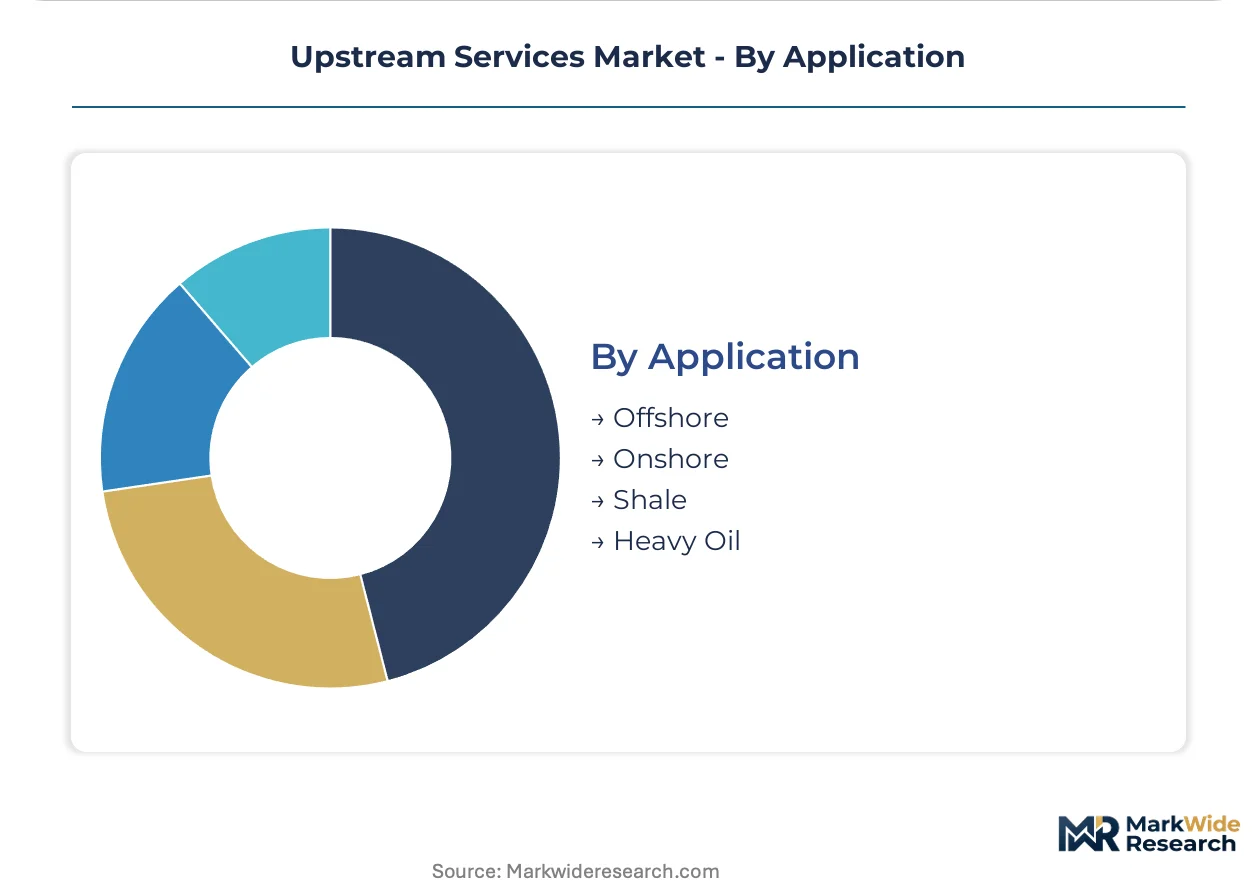
| Segmentation | Service Type: Exploration, Drilling, Production, Reservoir Management Technology: Seismic Imaging, Mud Logging, Directional Drilling, Enhanced Oil Recovery End User: Oil Producers, Gas Producers, Service Companies, Technical Consultants Application: Offshore, Onshore, Shale, Heavy Oil |
| Companies Covered | Weatherford, China Oilfield Services Limited, Schlumberger Limited, Saipem S.p.A., Transocean Ltd., Halliburton, Petrofac Limited, National Oilwell Varco, Baker Hughes Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Upstream Services Market Strategic Shifts
Upstream service delivery is pivoting from equipment-rental models toward integrated performance contracts, with digital infrastructure investments compressing the traditional separation between exploration and production workflows.
Automated directional drilling systems combining real-time telemetry with machine-learning trajectory optimization are supplanting conventional manual geosteering in shale basins. Permian and DJ Basin operators are deploying these platforms across 70% of new laterals. The shift is compressing spud-to-TD timelines and reducing the headcount required per rig.
EPA methane emissions regulations and BSEE blowout preventer testing mandates are forcing production service providers to retrofit pneumatic devices and upgrade subsea control systems. Offshore drillers in the Gulf of Mexico are absorbing compliance costs through extended procurement cycles. Equipment vendors are responding with certified low-leakage valve portfolios and integrated monitoring packages.
Integrated service contracts bundling drilling, completions, and artificial lift are displacing standalone equipment rentals among capital-constrained independents. The model transfers reservoir performance risk to service providers in exchange for volume-linked compensation. This structure is most visible among Permian and Eagle Ford operators seeking to preserve balance-sheet capacity.
Upstream Services Market Segmentation
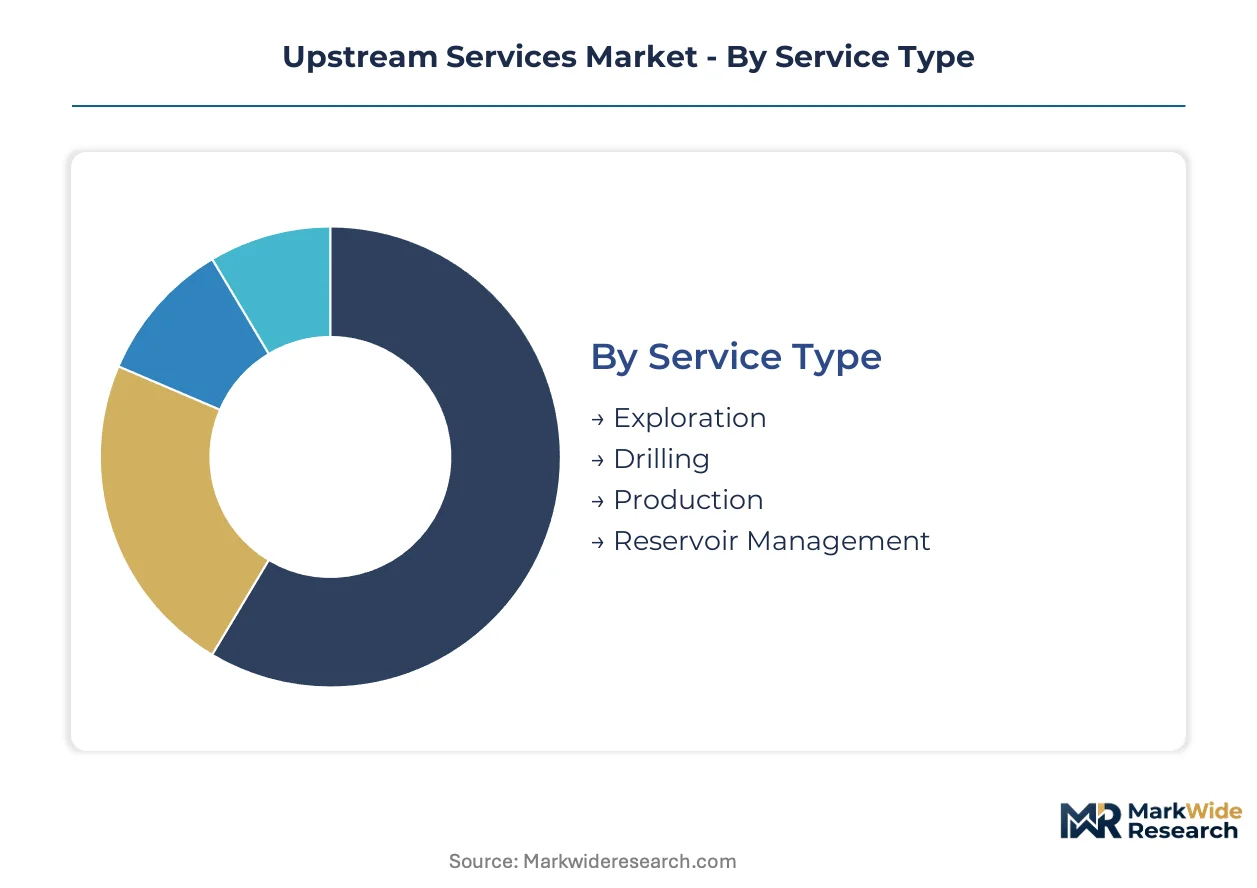
Upstream services procurement patterns diverge sharply across service types and deployment environments, with regulatory frameworks in Brazil, Norway, and the US Gulf of Mexico dictating equipment-certification requirements and compliance cost structures. Understanding these segment boundaries clarifies where capital concentrates and where margin compression threatens incumbent positioning.
Service Type:
EPA methane regulations and BSEE blowout-preventer mandates reshape procurement intensity across service categories, with offshore-focused segments absorbing disproportionate compliance investment.
- Exploration:Advanced seismic imaging platforms using proprietary algorithms process multiclient survey data under pressures exceeding 10,000 psi. Demand clusters in Brazil's pre-salt blocks and Guyana's emerging basin where ANP production-sharing frameworks require reserve replacement verification. Regulatory differentiation favors vendors with certified high-temperature sensor arrays.
- Drilling:Directional drilling services displace vertical approaches as shale operators target extended-reach laterals maximizing recovery per wellbore. Permian and DJ Basin deployments now favor automated trajectory optimization reducing petroleum engineer headcount per rig. BSEE testing protocols for subsea control systems extend procurement cycles.
- Production:Mature margin pool serving brownfield operators seeking plateau rate extension through artificial lift and surface facility optimization.
- Reservoir Management:Digital twin simulation platforms compress field development timelines while offsetting talent scarcity across North Sea and Gulf of Mexico assets.
Established volume favors Production; emerging adoption favors Reservoir Management.
Technology:
Cost tier differentiation separates premium algorithm-development investments from commoditized hardware rental, with integrated performance contracts blurring traditional procurement boundaries.
- Seismic Imaging:Multiclient survey data acquisition commands premium pricing due to capital intensity and proprietary processing algorithms. West Africa and Southeast Asia basins drive fleet deployment scheduling.
- Mud Logging:Real-time formation evaluation during drilling operations, standard across unconventional and deepwater environments.
- Directional Drilling:Machine-learning trajectory optimization now supplants manual geosteering across 70% of new Permian laterals, compressing spud-to-TD timelines while reducing rig crew requirements.
- Enhanced Oil Recovery:CO2 injection applications gain regulatory support under US IRA tax credits, with carbon capture integration opening new contracting models for depleted Permian and Bakken fields.
Technology deployment concentrates where reservoir complexity justifies algorithm investment; standardization threatens rental-model margins.
End User:
Customer-type segmentation reveals divergent procurement authority, with capital-constrained independents favoring integrated risk-transfer contracts over traditional equipment rental.
- Oil Producers:International majors anchor deepwater exploration spending in Brazil and Guyana, while Permian independents prioritize balance-sheet-preserving integrated service structures.
- Gas Producers:Appalachian and Haynesville operators face EPA pneumatic device retrofit mandates driving production service procurement.
- Service Companies:Subcontracting specialists executing directional drilling and completions work under performance-linked compensation frameworks.
- Technical Consultants:Reservoir simulation and field development planning advisors, demand contracting as petroleum engineering enrollment collapses across Texas and Alberta universities.
Procurement authority concentrates with Oil Producers; talent scarcity expands Technical Consultant engagement.
Application:
Geographic deployment determines equipment specification intensity, with deepwater environments requiring high-pressure high-temperature certification extending delivery timelines 18-24 months.
- Offshore:Gulf of Mexico, West Africa, and Southeast Asia basins concentrate demand for subsea trees and blowout preventers facing API and ISO 13628-7 qualification protocols. Brazil's ANP local-content requirements and Norway's Petroleum Safety Authority well-integrity standards create divergent inventory pools.
- Onshore:Permian and Eagle Ford development favors integrated drilling-completions-artificial lift bundles transferring reservoir performance risk to service providers.
- Shale:Extended-reach lateral development maximizing recovery per wellbore while reducing surface footprint across DJ Basin and STACK plays.
- Heavy Oil:Thermal extraction applications in Alberta and Venezuela requiring specialized artificial lift and steam generation capacity.
Offshore commands specification premium; Shale drives volume scale through standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Bureau of Safety and Environmental Enforcement anchors the regulatory framework for deepwater drilling across the Gulf of Mexico, while Brazil's ANP and Norway's Petroleum Safety Authority shape divergent compliance cost structures for Atlantic basin operators. Service procurement concentrates where frontier exploration intersects with stringent equipment-certification mandates.
United States
Permian Basin operators deploy automated directional drilling across 70% of new laterals, compressing spud-to-TD timelines. The EPA's methane emissions rules force pneumatic device retrofits and flare-gas recovery system upgrades. Houston anchors service company headquarters clusters, with Midland-Odessa field offices executing integrated drilling-completions bundles.
Brazil
Pre-salt blocks in the Campos and Santos basins drive demand for high-pressure high-temperature subsea trees and integrated subsurface automation. ANP local-content requirements mandate minimum domestic equipment sourcing percentages. Macaé and Rio de Janeiro host fabrication yards assembling blowout preventers for ultra-deepwater deployment.
Norway
North Sea electrification projects and power-from-shore contracting models reshape offshore facility engineering. The Petroleum Safety Authority enforces well-integrity standards extending subsea hardware certification timelines. Stavanger and Bergen concentrate subsea engineering consultancies addressing talent scarcity through digital twin deployment.
China
State-backed producers accelerate deepwater exploration in the South China Sea, driving fleet deployment for seismic imaging vessels. The Ministry of Ecology and Environment implements dual carbon goals pressuring methane abatement investments. Shenzhen and Shanghai house manufacturing capacity for drilling tubulars and subsea control systems.
United Kingdom
North Sea brownfield operators seek plateau rate extension through enhanced oil recovery and artificial lift retrofit. The North Sea Transition Authority imposes decommissioning security arrangements shaping capital allocation. Aberdeen maintains petroleum engineering consultancy clusters despite university enrollment collapse across geoscience programs.
Upstream Services Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated service providers bundling exploration-through-production workflows while specialized equipment vendors concentrate on certified high-pressure component manufacturing. The vendor base organizes around three strategic archetypes: full-service integrators capturing performance-linked contracts, subsea hardware specialists managing 18-24 month qualification protocols, and digital platform providers offsetting talent scarcity through automation. Competitive moves center on portfolio diversification into carbon capture integration and geographic expansion toward pre-salt basins.
Among US-based integrated service providers, Schlumberger Limited and Halliburton exemplify the full-service archetype, anchoring digital subsurface platforms and Permian Basin manufacturing capacity respectively. Baker Hughes Incorporated occupies a position within the equipment-specialist tier, differentiated through proprietary drill-bit designs. China Oilfield Services Limited represents the state-affiliated scale player, leveraging domestic fleet capacity for offshore seismic and drilling operations across Asia-Pacific basins.
| Leading Market Players |
|---|
| Weatherford |
| China Oilfield Services Limited |
| Schlumberger Limited |
| Saipem S.p.A. |
| Transocean Ltd. |
| Halliburton |
| Petrofac Limited |
| National Oilwell Varco |
| Baker Hughes Incorporated |
| Others |
Value Chain & Pricing Dynamics
Integrated performance contracts locking in multi-year drilling and completions bundles secure supply access for Permian independents while anchoring price visibility through volume-linked compensation structures. This contracting pattern concentrates procurement authority with operators seeking to preserve balance-sheet capacity.
Pricing Analysis
Brazil's ANP local-content mandates widen price spreads between certified high-pressure subsea equipment and standard onshore directional drilling services. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects divergent BSEE, NORSOK, and ISO 13628-7 qualification investments. Cost compression in the economy tier is intensifying because shale operators standardize automated trajectory platforms. Capital-constrained independents exhibit highest price sensitivity; deepwater majors absorbing extended procurement cycles show lowest.
Supply Chain Analysis
United States and China anchor manufacturing capacity for drilling tubulars and subsea control systems, while South Africa and Kazakhstan feed chromium-molybdenum alloy inputs. High-grade steel alloys, electronic control modules, and high-temperature sensor arrays draw from mining and semiconductor fabrication networks. Single-source vulnerability concentrates in blowout preventer stack assembly. Distribution runs through Houston and Singapore hub-and-spoke networks serving basin-specific inventory pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin platform subscriptions and predictive maintenance contracts expand faster than hardware rental revenue, converting capital equipment sales into recurring service-attach revenue streams.
For Market Incumbents: Secure API and ISO 13628-7 certification timelines for high-pressure high-temperature trees ahead of Brazil pre-salt and Guyana basin deployment cycles. Anchor manufacturing capacity in Midland-Odessa to offset Permian cost compression from automated directional drilling standardization. Petroleum engineering talent collapse threatens service delivery quality; vertical integration into university partnership pipelines addresses workforce pipeline risk. For New Entrants and Emerging Players: Reservoir simulation advisory gaps where Schlumberger and Halliburton under-serve mid-cap independents present white-space entry points. Target North Sea brownfield operators seeking plateau rate extension through enhanced oil recovery retrofit. Go-to-market leverage centers on carbon capture integration expertise qualifying for US IRA tax credits. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital platform providers bundling subsurface automation with performance-linked compensation structures. Long-term viability favors vendors with demonstrated pre-salt basin execution and certified subsea hardware portfolios. Watch EPA methane enforcement intensity as inflection signal for pneumatic device retrofit demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-salt Basin Digitalization | Brazil's Campos and Santos basins demand integrated subsurface-to-surface automation platforms. |
| Carbon Capture Integration | Enhanced oil recovery with CO2 injection gains US IRA tax credit support for Permian fields. |
| Electrification of Offshore Facilities | North Sea power-from-shore contracting models reshape subsea engineering procurement patterns. |
| Automated Directional Drilling Scale-Up | Machine-learning trajectory optimization now supplants manual geosteering across 70% of Permian laterals. |
| Methane Abatement Retrofit Services | EPA pneumatic device mandates generate recurring production service revenue across Bakken and Permian bases. |
Study Parameters
Desk research of regulatory filings from BSEE, EPA, ANP, and Norway's Petroleum Safety Authority preceded structured interviews with drilling operations managers, subsea procurement leads, reservoir simulation directors, and aftermarket service heads. Primary fieldwork with Permian independents and Brazil pre-salt operators combined with secondary validation through EIA production data, IEA upstream investment reports, and equipment vendor SEC disclosures. Bottom-up segment sizing triangulated against top-down basin-level expenditure aggregates.
Variance decomposition across service type, technology tier, deployment environment, and end-user archetype shaped the analytical framework over the projection horizon. Modeled dimensions included exploration versus production service intensity, digital versus conventional technology adoption, offshore versus onshore application split, and integrated versus standalone contract structure. CAGRs derived from basin-level capital commitment trajectories and equipment fleet deployment schedules, with directional drilling automation penetration and subsea tree delivery timelines as upstream-specific forecast inputs.
Underlying assumptions cover sustained deepwater frontier investment, regulatory enforcement continuity, and alloy input price stability, with deviation risk concentrated in OPEC Gulf state decarbonization timeline acceleration and petroleum engineering enrollment recovery. Recalibration cycles align with material shifts in ANP local-content thresholds and EPA methane rule implementation pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
North Sea Oil and Gas Upstream Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Natural Gas Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Drilling Services Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market