
 Drilling Services Market | 2026-2036
Drilling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Services Market Analysis
The skilled directional driller workforce is rotating toward automated rig systems, tightening labor availability for conventional operations. Schlumberger leverages its integrated drilling portfolio to anchor deepwater contracts in the Gulf of Mexico. Halliburton sustains dominance in North American hydraulic fracturing through captive pressure-pumping capacity. Baker Hughes differentiates via managed-pressure drilling technology leadership.
Drilling services encompass the planning, execution, and optimization of borehole creation using rotary, percussion, or hybrid systems, typically achieving depths from hundreds to tens of thousands of feet depending on geological target and casing program. These services enable hydrocarbon extraction, mineral recovery, and subsurface infrastructure installation across onshore and offshore environments. Directional drilling commands premium pricing due to complex wellbore geometry requirements in unconventional reservoirs. Automated technology is displacing conventional rig controls fastest in North American shale plays where labor costs and safety thresholds drive capital allocation. Offshore installation categories carry extended contract durations and higher capital intensity compared to land-based deployment.
The US EPA enforces methane emissions standards under the Clean Air Act that dictate well completion technologies and flare minimization protocols, while OSHA governs rig-floor safety equipment and personnel training mandates. BSEE oversees offshore blowout preventer certification and well control requirements in federal waters. Stakeholders must monitor regulatory fragmentation between federal and state jurisdictions as compliance costs diverge across operating basins.
Market Dynamics
The US EPA's methane emissions standards under the Clean Air Act are compressing well completion timelines and forcing capital reallocation toward flare minimization infrastructure. This regulatory pressure is reshaping contractor selection criteria across unconventional basins.
Growth Catalysts
- Geothermal expansion:Operators in Iceland and Kenya are expanding procurement of advanced directional drilling packages to access high-temperature reservoirs.
- Permian Basin concentration:Demand gravity in Texas and New Mexico is pulling service capacity from legacy conventional markets.
- OSHA rig-floor mandates:Personnel training requirements are accelerating replacement of manual controls with automated safety systems.
Market Restraints
- Steel alloy volatility:Premium drill pipe and casing material costs swing with commodity indices, compressing fixed-price contract margins.
- Gulf of Mexico supply concentration:Deepwater blowout preventer certification bottlenecks at BSEE create single-point dependency for offshore deployment.
- Directional dr labor scarcity:The skilled workforce rotating toward automated rigs leaves conventional operations understaffed.
Strategic Opportunities
- Middle East geothermal:Saudi Arabia's renewable diversification creates white space for high-temperature drilling specialists.
- Managed-pressure convergence:Integration of real-time telemetry with automated choke systems opens premium pricing in narrow-margin formations.
- US IRA hydrogen provisions:Subsurface storage well construction for hydrogen hubs qualifies for production tax credits.
Industry Challenges
- Automated rig integration:Legacy mechanical systems require expensive retrofitting to interface with digital control platforms.
- BSEE certification timelines:Offshore well control equipment approval delays compress project windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Services Market |
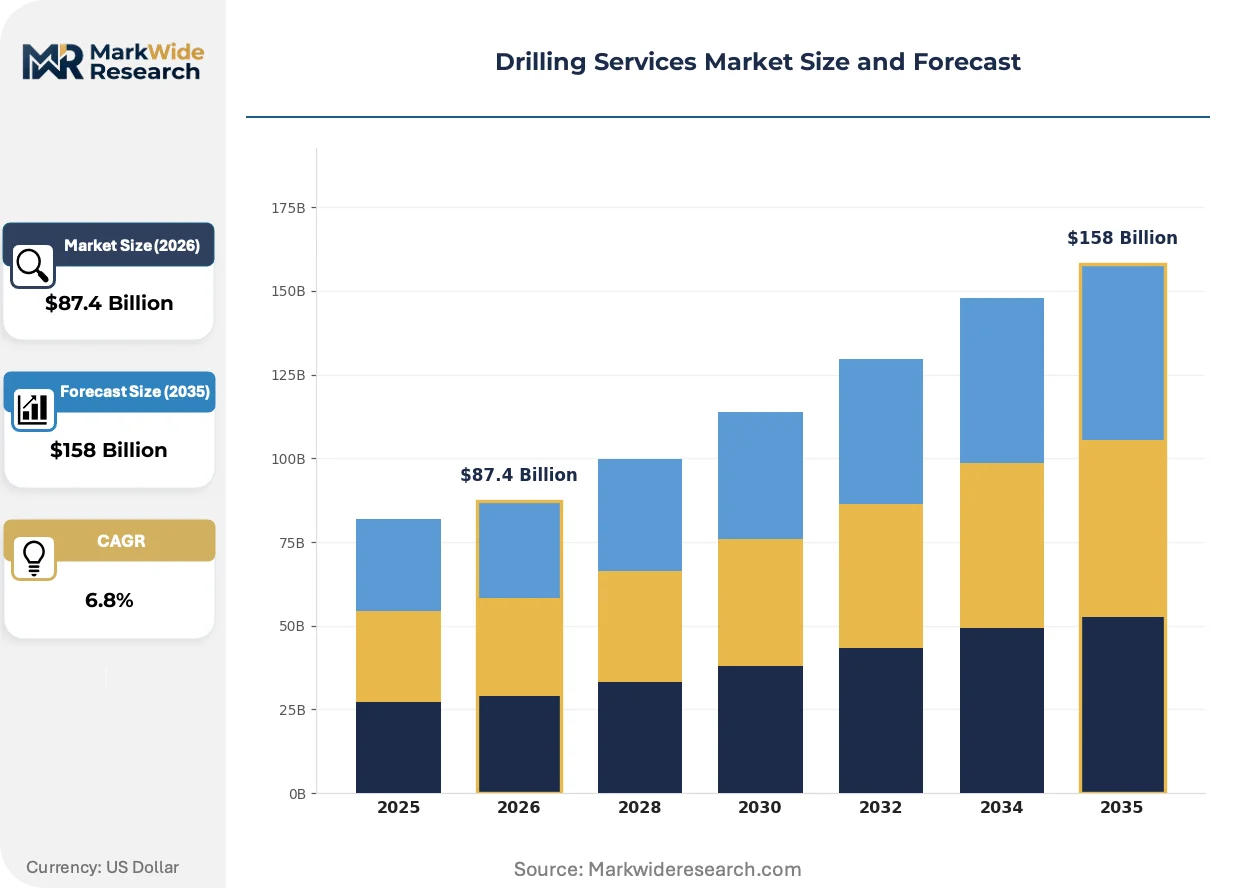
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rotary Drilling, Directional Drilling, Offshore Drilling, Hydraulic Fracturing Technology: Conventional, Managed Pressure, Underbalanced, Automated End User: Oil & Gas Companies, Mining Firms, Geothermal Operators, Construction Installation: Onshore, Offshore, Land-Based, Platform-Based |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, Weatherford International, Nabors Industries, Helmerich & Payne, Precision Drilling Corporation, Patterson-UTI, China Oilfield Services Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Services Market Emerging Trajectories
Automated drilling controls are compressing the labor-to-output ratio across North American shale operations. Three distinct shifts are redrawing competitive boundaries: technology substitution, regulatory compliance architecture, and procurement model evolution.
Rotary steerable systems integrated with real-time formation evaluation are displacing conventional mud motor assemblies in horizontal laterals. Permian Basin operators are adopting these packages at accelerated rates to reduce sliding time and improve rate of penetration. The displacement of mechanical steering is compressing day-rate premiums for standard directional services.
REACH chemical disclosure requirements in Europe are mandating detailed reporting of drilling fluid additives and their environmental fate. This regulatory architecture is forcing reformulation of synthetic-based mud systems and expanding demand for biodegradable alternatives. Offshore contractors in the North Sea are responding by qualifying new supplier portfolios ahead of enforcement deadlines.
Integrated service contracts bundling drilling, completions, and artificial lift are displacing discrete procurement of individual service lines. Supermajor operators in the Gulf of Mexico are consolidating vendor relationships to reduce interface risk and improve capital efficiency. This consolidation is most visible among deepwater projects where single-point accountability reduces insurance premiums.
Drilling Services Market Segmentation
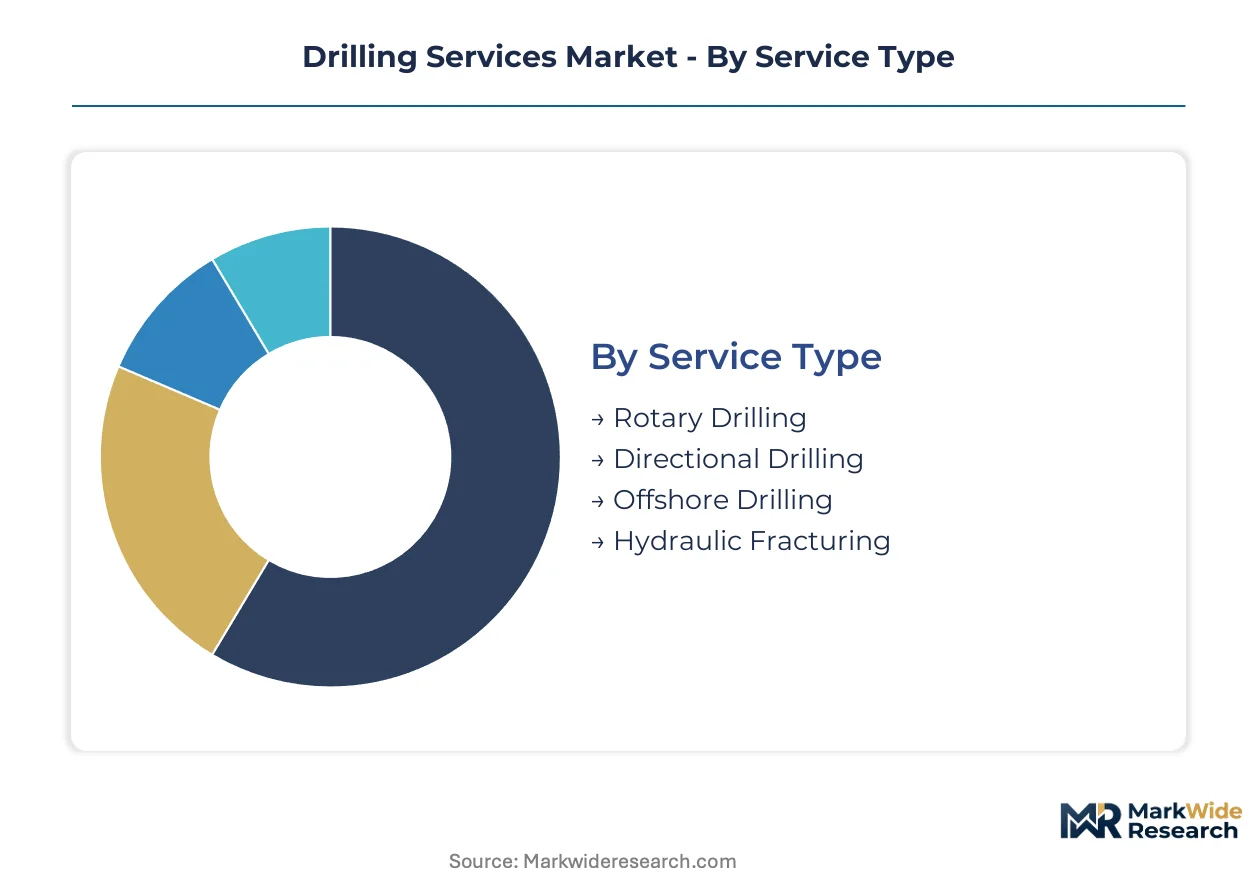
Service differentiation in drilling markets determines contract pricing, capital intensity, and regulatory exposure. Each segment category channels procurement decisions through distinct commercial pathways.
Service Type:
Rotary and directional packages flow through integrated service contracts to supermajors, while hydraulic fracturing concentrates among independent shale operators in Texas and New Mexico.
- Rotary Drilling:Conventional borehole creation using rotating drill bit and circulating fluid systems. Demand concentrates in Permian Basin primary well development where standard vertical sections dominate drilling programs. Labor scarcity and steel alloy cost volatility compress margins on fixed-price land contracts.
- Directional Drilling:Complex wellbore geometry control using steerable motors or rotary steerable systems. Geothermal operators in Iceland and Kenya are expanding procurement of advanced directional packages to access high-temperature reservoirs. Premium pricing persists despite automated technology displacement.
- Offshore Drilling:Extended-reach and deepwater borehole execution with blowout preventer integration.
- Hydraulic Fracturing:High-pressure fluid injection for reservoir stimulation in unconventional formations.
By volume, rotary drilling leads. By growth pace, directional drilling is ahead.
Technology:
Cost tiers separate legacy mechanical systems from digitally integrated platforms, with margin structures widening between retrofit-heavy and greenfield automated deployments.
- Conventional:Manual rig-floor controls with mechanical steering assemblies. Remaining demand concentrates in legacy conventional markets outside the Permian Basin where capital constraints delay automation adoption. OSHA personnel training mandates accelerate replacement timelines.
- Managed Pressure:Real-time annular pressure control using automated choke systems. Narrow-margin formations in the Gulf of Mexico drive premium pricing for integrated telemetry packages. BSEE certification bottlenecks constrain deployment velocity.
- Underbalanced:Drilling with formation pressure exceeding wellbore pressure to minimize formation damage.
- Automated:Digital control platforms replacing manual rig-floor operations.
By installed base, conventional technology dominates. By expansion trajectory, managed pressure systems are climbing the fastest.
End User:
Customer type dictates procurement sophistication, with supermajors bundling services and independents bidding discrete line items.
- Oil & Gas Companies:Hydrocarbon extraction operators spanning integrated supermajors and independent producers. Gulf of Mexico deepwater projects pull capacity through consolidated vendor relationships to reduce interface risk. US EPA methane standards compress well completion timelines.
- Mining Firms:Mineral recovery operators requiring blasthole and exploration drilling services.
- Geothermal Operators:Renewable energy developers accessing high-temperature subsurface reservoirs. Saudi Arabia's renewable diversification creates white space for high-temperature drilling specialists. Directional capability requirements match unconventional oil and gas complexity.
- Construction:Infrastructure developers requiring foundation and tunneling boreholes.
By contract value, oil and gas companies lead. By growth pace, geothermal operators are gaining share fastest.
Installation:
Geography determines capital intensity and regulatory jurisdiction, with offshore carrying extended durations and federal oversight.
- Onshore:Land-based drilling across Texas, New Mexico, and legacy conventional basins. Automated technology is displacing conventional rig controls fastest in North American shale plays where labor costs and safety thresholds drive capital allocation. Demand gravity concentrates in the Permian Basin.
- Offshore:Deepwater and shelf drilling in federal waters requiring BSEE certification. Extended contract durations and higher capital intensity differentiate economics from land-based deployment. Blowout preventer approval delays compress project windows.
- Land-Based:Surface-supported rig systems excluding floating platforms.
- Platform-Based:Fixed offshore structures with integrated drilling packages.
By active rig count, onshore installation leads. By contract duration premium, offshore is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes drilling services through unconventional shale development, while Saudi Arabia and Kenya deploy identical directional packages for geothermal reservoir access, revealing a technology-migration pattern from oil and gas to renewable subsurface applications.
United States
Permian Basin operators in Texas and New Mexico pull service capacity from legacy conventional markets through concentrated unconventional drilling programs. The EPA enforces methane emissions standards under the Clean Air Act that compress well completion timelines and mandate flare minimization infrastructure. Gulf of Mexico deepwater projects anchor integrated service contracts, with BSEE certification bottlenecks constraining blowout preventer deployment velocity.
Saudi Arabia
Renewable diversification programs are expanding procurement of advanced directional drilling packages for high-temperature geothermal reservoir access. The national energy regulator shapes procurement standards for subsurface infrastructure under the kingdom's dual carbon goals framework. Eastern Province industrial clusters host service contractor mobilization points for both hydrocarbon and emerging geothermal development.
Kenya
Rift Valley geothermal operators are expanding directional drilling procurement to access high-temperature reservoirs beneath volcanic formations. The country's national energy regulator oversees drilling permits and environmental compliance for renewable subsurface projects. Olkaria and Menengai fields concentrate drilling activity, with international contractors partnering with domestic operators on production well construction.
Norway
North Sea offshore drilling maintains extended contract durations and higher capital intensity compared to land-based deployment. The national petroleum regulator enforces well integrity standards and blowout preventer certification requirements in federal waters. Stavanger and Bergen clusters concentrate subsea drilling technology development and contractor engineering capabilities.
China
Sichuan Basin shale operators are adopting automated drilling controls to compress labor-to-output ratios in tight gas development. The Ministry of Ecology and Environment governs drilling fluid disposal and methane venting standards under national dual carbon targets. Xinjiang and Ordos basins concentrate onshore drilling programs, with state-owned operators consolidating vendor relationships for integrated service packages.
Drilling Services Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in drilling services, with tier boundaries drawn by portfolio breadth and capital intensity rather than geographic coverage alone. The upper tier anchors deepwater and integrated project contracts through bundled service offerings. The specialist tier competes on directional technology, managed-pressure systems, or regional labor arbitrage. Competitive moves center on automation platform deployment and strategic partnerships for geothermal market entry.
Among integrated service providers, Schlumberger, Halliburton, and Baker Hughes exemplify the full-portfolio archetype. Schlumberger occupies a position anchoring deepwater contracts through integrated drilling portfolios. Halliburton exemplifies North American hydraulic fracturing dominance through captive pressure-pumping capacity. Baker Hughes represents managed-pressure drilling technology leadership, differentiating through real-time telemetry integration. These three entities collectively shape pricing benchmarks and technology adoption curves across unconventional and offshore segments.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Weatherford International |
| Nabors Industries |
| Helmerich & Payne |
| Precision Drilling Corporation |
| Patterson-UTI |
| China Oilfield Services Limited |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day lead times for premium drill pipe and casing alloys concentrate pricing power among integrated service providers with captive steel procurement relationships. This inventory-to-pricing nexus compresses margins for contractors locked into fixed-price land contracts when commodity indices swing.
Pricing Analysis
Project-based integrated service contracts dominate deepwater and unconventional development, while spot-market day rates persist for legacy conventional land rigs. Price differentiation separates automated rotary steerable packages from conventional mud motor assemblies, with Gulf of Mexico managed-pressure systems commanding premiums over North American shale standard deployments. Cost compression in conventional land drilling intensifies as automated controls displace manual rig-floor operations and labor scarcity drives wage inflation. Independent shale operators in Texas and New Mexico exhibit highest price sensitivity, while supermajor Gulf of Mexico projects prioritize single-point accountability over rate minimization.
Supply Chain Analysis
Strategic stockpiling of high-grade steel alloys and blowout preventer components prevails among tier-one contractors, while smaller land operators run lean just-in-time inventories vulnerable to commodity swings. Manufacturing concentration in the United States, China, and Norway anchors global supply for advanced drilling equipment and subsea control systems. Supply chains draw from chromium-molybdenum steel alloys, synthetic-based drilling fluids, and electronic pressure sensors as critical inputs. Single-source vulnerability concentrates around BSEE-certified blowout preventer manufacturers, creating certification bottlenecks that delay offshore deployment. Distribution runs through integrated service company logistics networks and regional equipment rental hubs serving Permian Basin and Gulf of Mexico markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated drilling platforms and geothermal energy systems constitute substitution threats that incumbent service providers must navigate through capability repositioning.
For Market Incumbents: Shield core revenue streams by accelerating backward integration into automated rig control software and sensor manufacturing. Captive production of rotary steerable systems reduces dependency on third-party technology licensors. Consolidate pressure-pumping capacity in the Permian Basin to defend market position against independent frac specialists. OSHA-mandated safety system upgrades create defensive moats for contractors with pre-certified automated platforms.
For New Entrants and Emerging Players: Differentiate on high-temperature geothermal drilling specialization, where directional complexity matches unconventional oil and gas but incumbent presence remains thin. Saudi Arabia's renewable diversification and Kenya's Rift Valley expansion represent the most penetrable white-space geographies. Pursue joint-venture structures with national oil companies to secure initial contract flow and technology qualification pathways.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automated technology deployment favors scaled balance sheets capable of absorbing retrofit capital cycles. Acquisition targets should display managed-pressure drilling certification depth or geothermal directional capabilities. Watch BSEE regulatory enforcement intensity as the inflection signal for offshore contract velocity and capital allocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Rig Platform Deployment | Schlumberger and Baker Hughes anchor market positioning through integrated digital control systems. |
| Geothermal Capability Buildout | Saudi Aramco and Kenyan state operators create contract flow for high-temperature drilling specialists. |
| Managed-Pressure Technology Licensing | Baker Hughes differentiates Gulf of Mexico market share through real-time telemetry integration. |
| Backward Integration into Pressure Pumping | Halliburton sustains North American dominance through captive frac fleet ownership. |
| Long-term Integrated Service Contracts | Supermajor Gulf of Mexico projects reduce vendor count to lower insurance premiums and interface risk. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with drilling contractors, rig operators, and procurement executives at supermajor oil companies, combined with secondary validation through BSEE certification records, EPA methane compliance filings, and equipment utilization databases. Directional drillers, geothermal project developers, and steel alloy procurement managers provided operational perspective. Trade customs data, OSHA enforcement records, and international geothermal development registries supplied quantitative anchors. Bottom-up rig count modeling and top-down service revenue triangulation cross-validated segment sizing.
Across the projection horizon, the analytical framework modeled service type, technology tier, end-user category, and installation geography as core segmentation dimensions. CAGRs emerged from rig deployment trajectories, day-rate trend analysis, and capital expenditure patterns across unconventional and offshore basins. Forecast inputs incorporated EPA regulatory compliance cost estimates, geothermal capacity expansion announcements, and steel price index volatility assumptions.
The analysis sits within stated boundaries; outcomes outside sustained Permian Basin drilling intensity or accelerated BSEE certification timelines would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and commodity price ranges. Practitioners should keep alternative scenarios live as methane emission standard stringency and automated technology adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Downhole Tractor Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Brazil Oil and Gas Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market