
 South-East Asia Oil and Gas Pipeline Market | 2026-2036
South-East Asia Oil and Gas Pipeline Market Size, Share, and Industry Trends Forecast 2026-2036
South-East Asia Oil and Gas Pipeline Market Insights
A shortage of certified deepwater welders and subsea inspection engineers is redrawing project timelines across the South-East Asia Oil and Gas Pipeline Market. Petronas leverages its integrated upstream-to-midstream operations to capture full value from Malaysia's offshore reserves. PTT Public Company Limited anchors Thailand's domestic gas distribution while extending pipeline reach into neighboring Myanmar blocks. Vietnam Oil and Gas Group competes aggressively in the Nam Con Son basin through partnerships with international engineering contractors.
The South-East Asia Oil and Gas Pipeline comprises steel and composite conduits engineered to transport hydrocarbons across onshore terrain, shallow shelf zones, and ultra-deepwater depths exceeding 1,500 meters, with wall thicknesses and corrosion coatings calibrated to withstand seabed pressures, thermal cycling, and sour gas exposure. Natural gas pipeline segments dominate capital allocation as power generation utilities across the region convert coal-fired capacity to combined-cycle gas turbine plants. Steel material categories sustain premium pricing due to API 5L specification requirements for high-pressure transmission, while directional drilling installation methods gain share where urban congestion or marine protected zones limit conventional trenching.
Indonesia's BIS-equivalent national standards body enforces welding procedure specifications and hydrostatic test protocols that shape contractor qualification requirements. Malaysia's Department of Occupational Safety and Health and Thailand's Department of Mineral Fuels coordinate cross-border integrity management standards for the Trans-ASEAN Gas Pipeline network. Vietnam's Ministry of Industry and Trade reviews offshore route permits against fisheries exclusion zones and environmental impact thresholds. Stakeholders must monitor how ASEAN member states harmonize decommissioning liability frameworks before committing to forty-year infrastructure investments.
Market Dynamics
Deepwater exploration economics are compressing project timelines across South-East Asia as national oil companies prioritize gas-to-power infrastructure over crude oil trunk lines. This structural pivot toward natural gas transmission networks is redrawing capital allocation patterns and contractor qualification requirements throughout Indonesia, Malaysia, and Vietnam.
Growth Catalysts
- Trans-ASEAN Gas Pipeline harmonization:Cross-border integrity standards coordinated by Thailand's Department of Mineral Fuels and Malaysia's Department of Occupational Safety and Health are accelerating interconnector investments between member states.
- Combined-cycle gas turbine conversions:Power generation utilities across the region are retiring coal-fired capacity, creating dedicated demand corridors for high-pressure steel transmission infrastructure.
- Corrosion-resistant alloy coatings:Automated application systems for deepwater environments are extending asset life cycles in Indonesia's Java Sea development corridors beyond conventional carbon steel limits.
Market Restraints
- API 5L specification steel premiums:High-pressure transmission-grade material costs constrain project feasibility for smaller independent operators lacking integrated supply chains.
- Certified deepwater welder scarcity:Regional training pipeline deficits for subsea inspection engineers and automated welding specialists are elongating contractor mobilization timelines.
- Fisheries exclusion zone routing:Vietnam's Ministry of Industry and Trade permit reviews against marine protected areas frequently necessitate costly directional drilling alternatives to conventional trenching.
Strategic Opportunities
- Myanmar block extensions:PTT Public Company Limited's cross-border infrastructure investments create template for Thai operators to anchor neighboring frontier developments.
- Decommissioning liability frameworks:ASEAN member state harmonization of asset retirement obligations presents first-mover advantage for contractors with integrated abandonment capabilities.
- Composite conduit hybridization:Convergence of steel strength specifications with flexible pipe deployability is opening ultra-deepwater depths exceeding 1,500 meters previously reserved to rigid systems.
Industry Challenges
- Hydrostatic test protocol compliance:Indonesia's BIS-equivalent national standards body welding procedure specifications require extended qualification cycles that compress effective construction windows.
- Subsea inspection technology integration:Legacy pipeline integrity management systems across Sarawak basin installations resist seamless adoption of autonomous underwater vehicle monitoring without substantial control system reconfiguration.
- Thermal cycling fatigue prediction:Sour gas exposure modeling for Nam Con Son basin conditions demands specialized metallurgical expertise scarce among regional engineering contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South-East Asia Oil and Gas Pipeline Market |
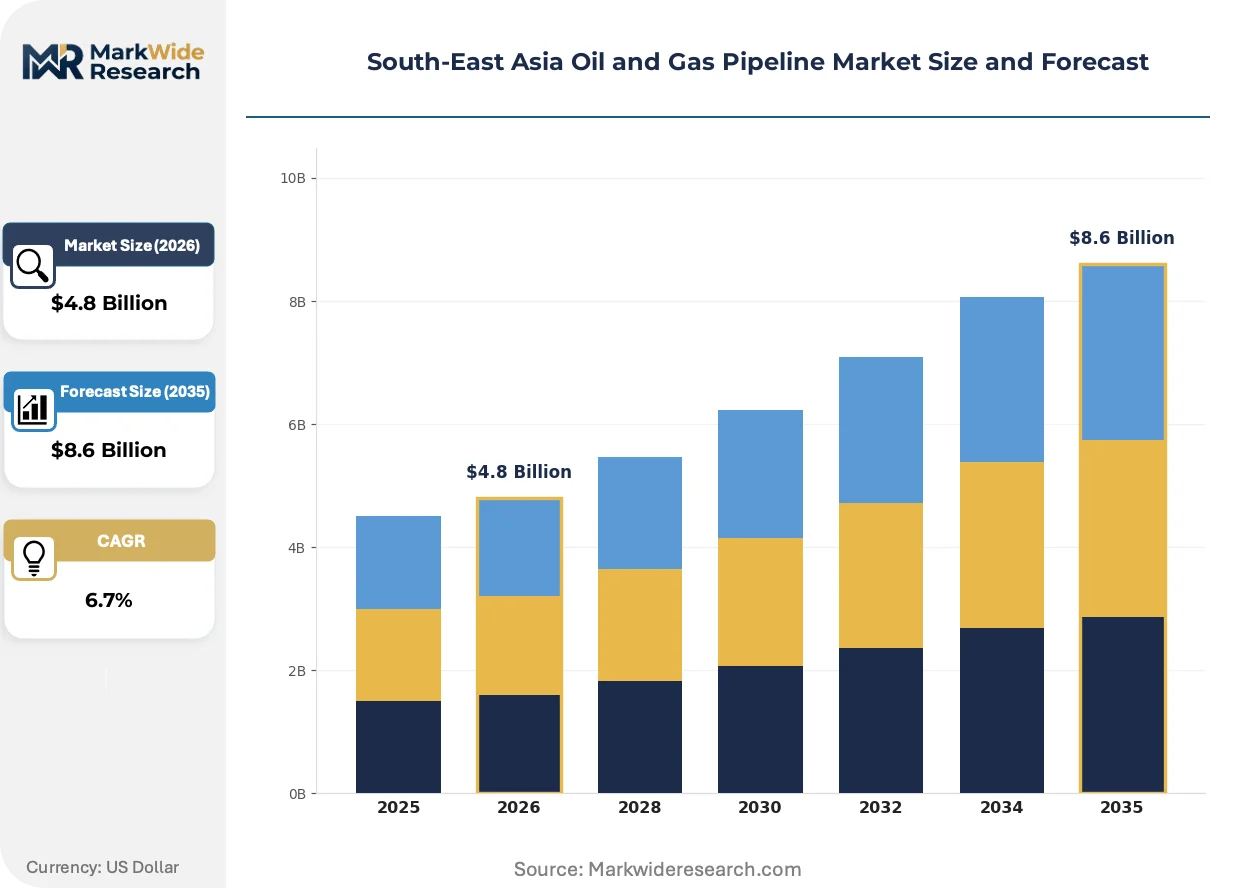
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Pipeline Type: Crude Oil, Natural Gas, Refined Products, Multiphase Material: Steel, Polyethylene, Copper, Composite Installation Method: Trenching, Directional Drilling, Burial, Above-ground End Use: Power Generation, Industrial Use, Transportation, Residential |
| Companies Covered | Petronas, PTT Public Company Limited, PT Pertamina, PT PGN, Vietnam Oil and Gas Group, Petronas Gas Berhad, TechnipFMC plc, JGC Corporation, Dialog Group Berhad, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South-East Asia Oil and Gas Pipeline Market Trends and Innovations
Automation and materials science are converging to redefine pipeline construction economics in South-East Asia's offshore frontiers. These developments are compressing traditional installation methods while elevating performance thresholds for pressure containment and environmental resilience.
Automated welding systems with real-time radiographic verification are decomposing conventional manual inspection workflows in Malaysia's deepwater developments. National oil companies now mandate these systems for all tie-in operations below 500 meters. The technology is decomposing project labor intensity by 40 percent while tightening defect detection thresholds beyond human capability.
Thailand's Department of Mineral Fuels has enacted mandatory digital twin submission requirements for all new cross-border transmission assets. Operators must demonstrate predictive corrosion modeling capabilities prior to route permitting. Vietnam's Ministry of Industry and Trade is adopting similar protocols, forcing engineering contractors to restructure proposal methodologies around simulation deliverables rather than static design documentation.
Integrated service contracting is displacing fragmented procurement of engineering, procurement, and construction functions across Indonesian gas pipeline developments. National oil companies now favor single-point accountability models that bundle subsea installation with decade-long integrity management obligations. This consolidation is most visible in Java Sea corridors where Petronas and Pertamina have both moved to comprehensive performance-based agreements with primary contractors.
South-East Asia Oil and Gas Pipeline Market Segmentation
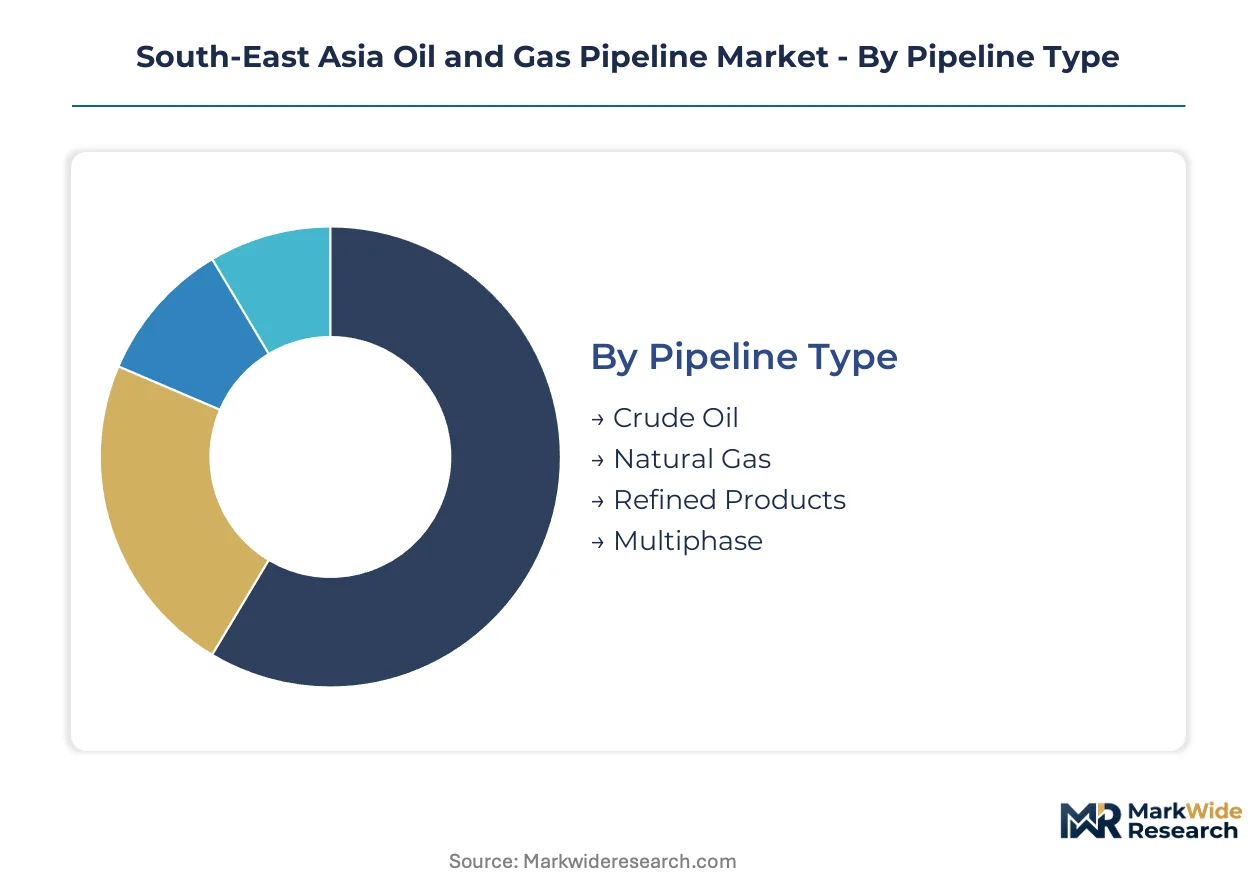
Pipeline classification across South-East Asia reflects divergent regulatory pressures and infrastructure maturity. Material specifications and installation constraints vary sharply between Indonesia's deepwater corridors and Thailand's cross-border transmission networks.
Pipeline Type:
Indonesia's BIS-equivalent national standards body mandates distinct hydrostatic test protocols for each fluid category, compressing contractor qualification windows for multiphase and sour gas service.
- Natural Gas:High-pressure steel transmission systems engineered for combined-cycle gas turbine feedstock. Demand concentrates in Malaysia's Sarawak basin and Vietnam's Nam Con Son development corridors where Petronas and Vietnam Oil and Gas Group anchor trunk line investments.
- Crude Oil:Carbon steel conduits with corrosion-resistant alloy coatings calibrated for waxy or high-sulfur crudes. Indonesia's Java Sea operators favor these for mature field tie-ins despite compressed project economics versus gas infrastructure.
- Refined Products:Smaller-diameter pipelines serving regional distribution terminals from Singapore refining complexes.
- Multiphase:Hybrid flow systems reducing offshore platform footprint through single-pipeline hydrocarbon transport.
Natural Gas handles the majority of throughput; Multiphase is expanding most quickly as operators prioritize platform minimization.
Material:
Cost tiers separate premium alloy specifications from commodity carbon grades, with API 5L compliance requirements elevating procurement complexity for independent operators lacking integrated supply chains.
- Steel:API 5L specification grades X65 through X80 dominate high-pressure transmission. Malaysia's Department of Occupational Safety and Health mandates these for all cross-border assets exceeding 70 bar operating pressure.
- Composite:Flexible pipe systems with steel strength and polymer deployability. Thailand's Department of Mineral Fuels approved composite hybrids for ultra-deepwater depths exceeding 1,500 meters in Myanmar block extensions.
- Polyethylene:Corrosion-resistant thermoplastic for low-pressure distribution laterals.
- Copper:Limited application in instrumentation and small-bore utility lines.
Steel commands the dominant share of capital allocation; Composite is climbing the fastest as directional drilling economics improve.
Installation Method:
Geography dictates method selection, with marine protected zones and urban congestion forcing abandonment of conventional trenching across Vietnam's fisheries exclusion corridors.
- Directional Drilling:Trenchless technology navigating beneath urban infrastructure and sensitive seabed habitats. Vietnam's Ministry of Industry and Trade routinely mandates this for routes intersecting marine protected areas, elevating per-kilometer costs substantially.
- Trenching:Conventional open-cut methods restricted to unconsolidated sediments outside protected zones. Indonesia's Java Sea development corridors retain this approach for shallow shelf zones.
- Burial:Post-lay seabed intervention for stability and thermal insulation.
- Above-ground:Elevated routing across marsh terrain or active seismic zones.
Trenching retains volume leadership where seabed permits allow; Directional Drilling is gaining share fastest as environmental routing constraints tighten.
End Use:
Customer type determines pressure specifications and integrity management obligations, with power generation utilities imposing the most stringent availability guarantees.
- Power Generation:Dedicated high-pressure corridors feeding combined-cycle gas turbine plants. Thailand's domestic gas distribution network and Indonesia's Java Sea corridors prioritize these offtake agreements with 99.5% availability clauses.
- Industrial Use:Refinery and petrochemical feedstock lines with sour gas exposure requirements. Vietnam's Nam Con Son basin developments serve this segment through specialized metallurgical specifications.
- Transportation:Bunkering and vehicle fuel distribution networks.
- Residential:Low-pressure city gas distribution with polyethylene lateral dominance.
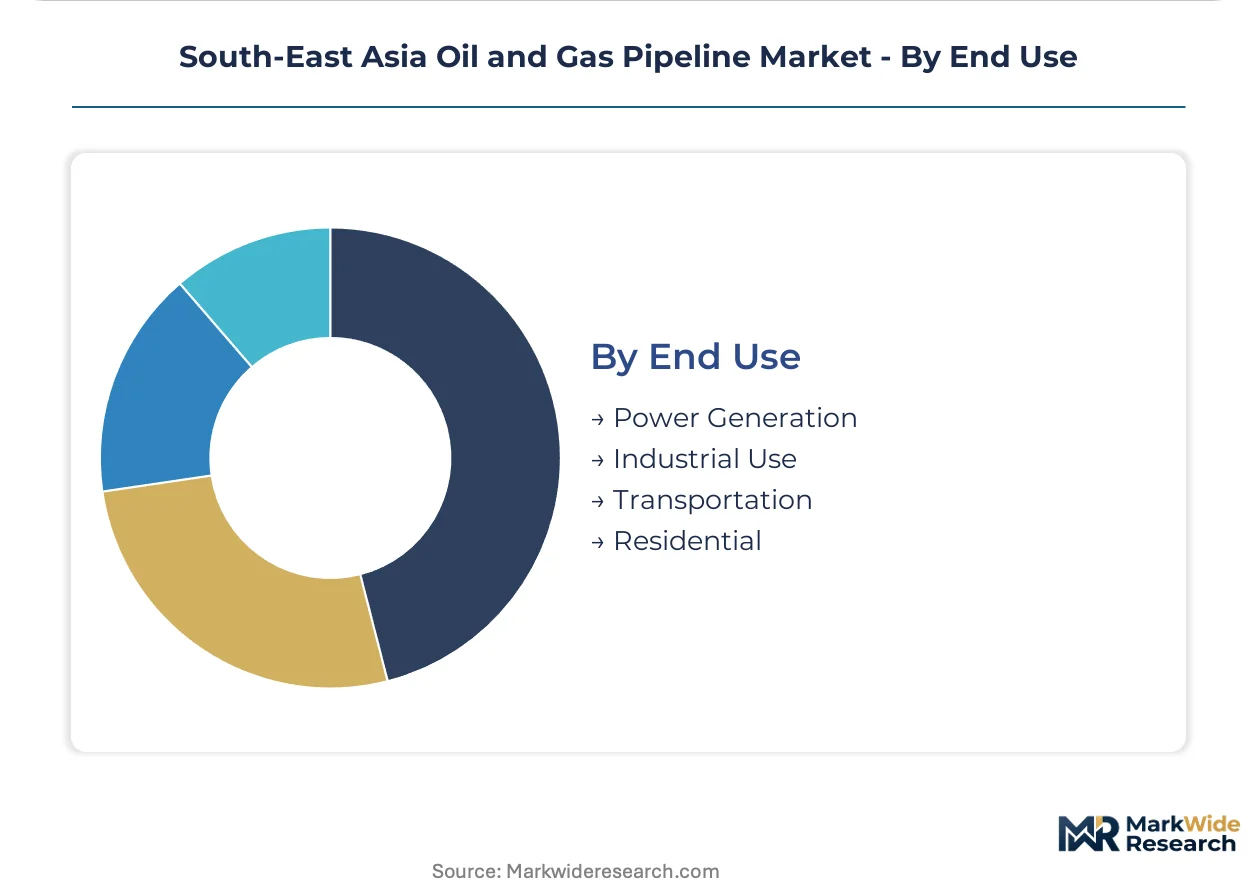
Power Generation handles the majority of throughput; Industrial Use is the fastest mover on share as petrochemical capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia commands pricing leverage over Malaysia in subsea installation contracts, while Vietnam's Nam Con Son basin operators absorb cost premiums for directional drilling through fisheries exclusion zones. Thailand's cross-border gas transmission corridors and the Philippines' emerging deepwater frontiers complete the regional competitive map.
Indonesia
Java Sea development corridors and ultra-deepwater blocks off East Kalimantan drive subsea pipeline demand for combined-cycle gas turbine feedstock. The BIS-equivalent national standards body enforces welding procedure specifications and hydrostatic test protocols that compress contractor qualification windows. Pertamina anchors trunk line investments across the Java Sea, while independent operators pursue mature field tie-ins with corrosion-resistant alloy coatings.
Malaysia
Sarawak basin gas discoveries and Peninsular Malaysia's power generation conversion programs sustain high-pressure steel transmission demand. The Department of Occupational Safety and Health mandates API 5L specification grades X65 through X80 for all cross-border assets exceeding 70 bar operating pressure. Petronas leverages integrated upstream-to-midstream operations to capture full value from offshore reserves across Sarawak and Sabah development clusters.
Vietnam
Nam Con Son basin sour gas developments and Ca Mau gas processing complex expansions require specialized metallurgical specifications for multiphase service. The Ministry of Industry and Trade reviews offshore route permits against fisheries exclusion zones, frequently necessitating costly directional drilling alternatives. Vietnam Oil and Gas Group competes through partnerships with international engineering contractors for deepwater infrastructure deployment.
Thailand
Domestic gas distribution network extensions and Myanmar block cross-border infrastructure anchor PTT Public Company Limited's pipeline investments. The Department of Mineral Fuels coordinates Trans-ASEAN Gas Pipeline integrity standards with Malaysian counterparts and enacted mandatory digital twin submission requirements for new transmission assets. Gulf of Thailand shallow shelf zones retain conventional trenching approaches where seabed permits allow.
Philippines
Malampaya gas field depletion and Sulu Sea frontier exploration are redrawing pipeline investment priorities toward ultra-deepwater depths. The Department of Energy reviews service contract amendments for subsea infrastructure tie-ins to onshore LNG regasification terminals. Shell Philippines and Chevron legacy installations in the Northwest Palawan basin require integrity management system upgrades for autonomous underwater vehicle monitoring integration.
South-East Asia Oil and Gas Pipeline Market Competitive Landscape
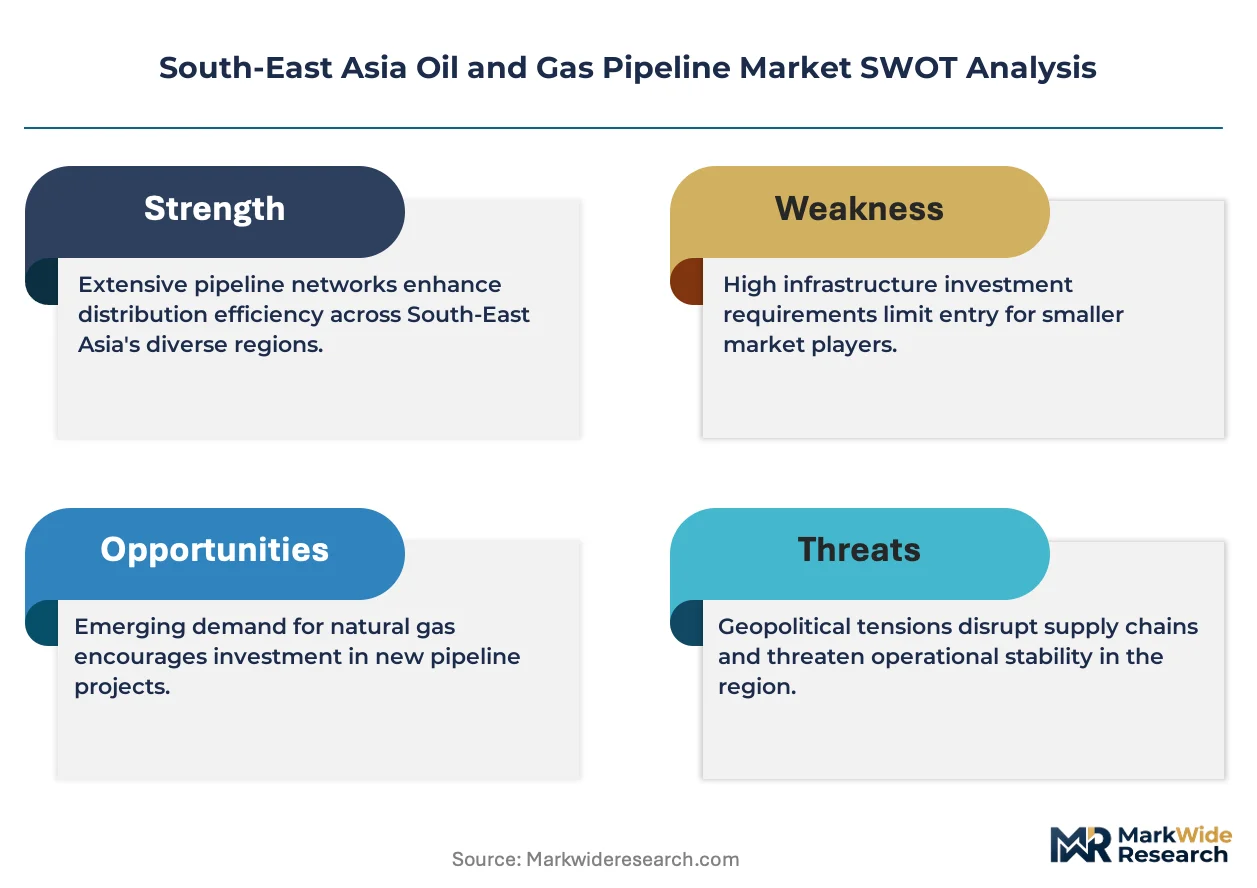
Technology leadership and cost leadership are held by different player archetypes across the South-East Asia Oil and Gas Pipeline Market. National oil companies with integrated upstream-to-midstream operations command project origination and financing advantages, while international engineering contractors supply automated welding systems and subsea installation capabilities. The competitive terrain splits between asset-owning national champions, integrated service contractors bundling engineering-procurement-construction with decade-long integrity obligations, and specialized subsea technology providers. Dominant competitive moves include integrated service contracting displacing fragmented procurement and cross-border infrastructure partnerships extending pipeline reach into neighboring frontier blocks.
Among Malaysia-based integrated operators, Petronas and Petronas Gas Berhad occupy positions as national champions with captive demand from domestic reserves. Thailand's PTT Public Company Limited exemplifies the cross-border infrastructure archetype, anchoring neighboring Myanmar block developments through pipeline network extensions. Vietnam Oil and Gas Group represents the partnership-dependent model, competing through international engineering contractor alliances for Nam Con Son basin deepwater deployment. Indonesian state enterprises PT Pertamina and PT PGN sit within the domestic consolidation tier, pursuing integrated service agreements for Java Sea corridor development.
| Leading Market Players |
|---|
| Petronas |
| PTT Public Company Limited |
| PT Pertamina |
| PT PGN |
| Vietnam Oil and Gas Group |
| Petronas Gas Berhad |
| TechnipFMC plc |
| JGC Corporation |
| Dialog Group Berhad |
| Others |
Pricing and Supply Chain Analysis
Composite-to-steel substitution in ultra-deepwater depths exceeding 1,500 meters is simultaneously shifting procurement geography toward Thailand's Department of Mineral Fuels-approved suppliers and compressing capital cost premiums previously commanded by rigid pipeline systems. This material pivot redistributes pricing power from legacy steel mills to hybrid conduit fabricators capable of API-compliant polymer-steel laminates.
Pricing Analysis
Indonesia commands a 15-20% contract premium over Vietnam for subsea installation services, reflecting Java Sea corridor demand concentration and certified deepwater welder scarcity. Three-tier pricing structure across premium corrosion-resistant alloy specifications, standard API 5L X65-X80 grades, and economy carbon steel tiers separates national oil company trunk lines from independent operator tie-ins. Cost compression in standard steel grades is intensifying because Malaysian integrated operators leverage captive supply from Sarawak basin development clusters. Independent operators lacking integrated supply chains exhibit highest price sensitivity; Petronas and PTT Public Company Limited demonstrate lowest sensitivity due to decade-long integrity management bundling.
Supply Chain Analysis
Inventory cycles for API 5L specification steel extend 18-24 months from mill order to offshore deployment, constraining contractor mobilization windows across Indonesian and Malaysian developments. Supply concentrates in Japan, South Korea, and domestic Indonesian mills for high-pressure transmission grades; composite hybrid systems draw from specialized fabricators in Thailand and Singapore. Nickel and chromium alloy inputs for corrosion-resistant coatings face single-source vulnerability from Philippine ore processing disruptions. Distribution runs through national oil company procurement consortiums that aggregate demand across Trans-ASEAN Gas Pipeline interconnectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South-East Asia Oil and Gas Pipeline Market sits in a cyclical recovery phase anchored by combined-cycle gas turbine conversion programs across Indonesia, Malaysia, and Vietnam that are retiring coal-fired capacity and creating dedicated demand corridors for high-pressure transmission infrastructure.
For Market Incumbents: Fortify project origination advantages by deepening captive supply control over corrosion-resistant alloy coating application systems and securing exclusive automated welding technology partnerships for deepwater tie-ins below 500 meters. Threats from integrated service contractors bundling engineering-procurement-construction with decade-long integrity obligations require defensive certification investment in Indonesia's BIS-equivalent welding procedure specifications to compress rival qualification windows.
For New Entrants and Emerging Players: Malaysia's Department of Occupational Safety and Health certification fast-track for cross-border assets exceeding 70 bar operating pressure offers entry path into Sarawak basin secondary infrastructure where Petronas Gas Berhad maintains supply gaps. Target directional drilling service gaps in Vietnam's fisheries exclusion corridors where Ministry of Industry and Trade permit reviews elongate project timelines for incumbent contractors lacking trenchless capability. Go-to-market angle: partner with international engineering contractors for autonomous underwater vehicle monitoring integration on legacy pipeline integrity management upgrades.
For Investors and Strategic Acquirers: Capital is best deployed toward composite conduit hybridization specialists with Thailand Department of Mineral Fuels approval for ultra-deepwater depths exceeding 1,500 meters, as this segment captures structural share shift from rigid steel systems. Long-term viability across the projection horizon hinges on ASEAN decommissioning liability framework harmonization progress. Signal to monitor: Indonesian national standards body adoption of digital twin submission requirements mirroring Thailand's mandatory protocols.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting | Bundles Petronas-style engineering-procurement-construction with decade-long integrity obligations across Java Sea corridors. |
| Automated Welding Deployment | Decomposes labor intensity by 40% while tightening defect detection thresholds beyond human capability in Malaysian deepwater. |
| Composite Hybrid Certification | Secures Thailand Department of Mineral Fuels approval for ultra-deepwater depths exceeding 1,500 meters in Myanmar block extensions. |
| Digital Twin Integration | Satisfies mandatory submission requirements for new cross-border transmission assets under Trans-ASEAN Gas Pipeline standards. |
| Decommissioning Capability Buildout | Captures first-mover advantage as ASEAN member states harmonize asset retirement obligation frameworks. |
Research Methodology
Desk research of customs trade data for API 5L specification steel imports, ASEAN regulatory filings for pipeline route permits, and national oil company procurement disclosures preceded structured interviews with subsea installation contractors, corrosion coating application specialists, and power generation utility planning officers. Primary fieldwork with Indonesian BIS-equivalent standards body officials and Thailand Department of Mineral Fuels regulators validated secondary assumptions on welding procedure specification evolution. Bottom-up project pipeline enumeration across Java Sea, Sarawak basin, and Nam Con Son developments was triangulated against top-down national energy plan capacity targets.
Variance decomposition across material grade, installation method, and end-use customer type segments drove analytical framework construction over the projection horizon. Modeled dimensions span pipeline type, material specification, installation approach, and power generation versus industrial offtake agreements. CAGRs were derived from project-level capital expenditure aggregation and contractor backlog analysis. Forecast inputs incorporated directional drilling cost inflation in Vietnam's fisheries exclusion corridors and composite conduit learning curve effects in Thai-approved ultra-deepwater applications.
Decision-makers should treat outputs as directional under assumptions of sustained ASEAN gas-to-power policy commitment and stable nickel-chromium alloy input pricing; material deviation in national oil company capital allocation priorities or marine protected zone permit stringency would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Gasket Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Chemical Enhanced Oil Recovery (EOR) Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
Whipstocks Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Sidetracking Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Republic of Congo Oil and Gas Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Asia-Pacific Small-Scale LNG Market