
 Wearable Band Market | 2026-2036
Wearable Band Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Band Market Outlook
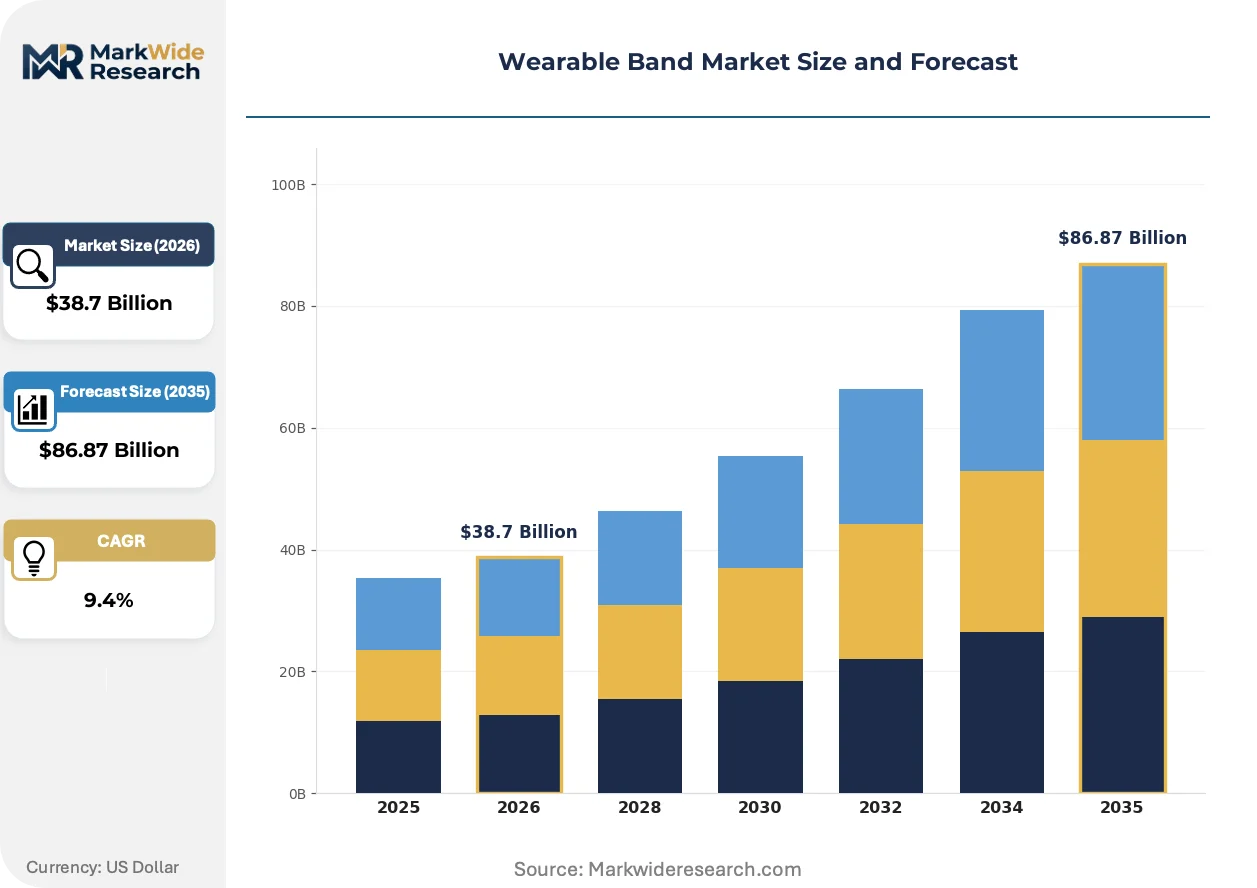
Subscription-based health analytics is recalibrating how wearable bands generate lifetime value beyond hardware margins. Apple leverages its ecosystem lock-in to sustain recurring revenue from fitness and health services. Xiaomi anchors its position through manufacturing scale that undercuts premium rivals across emerging markets. Garmin specializes in GPS precision and outdoor durability, occupying a defensible niche among athletic professionals.
A wearable band is a wrist-worn electronic device incorporating accelerometers, photoplethysmography sensors, and wireless transceivers to capture biometric and activity data, typically operating within a 20-50 gram weight envelope and IP67-or-better ingress protection. Its primary commercial purpose spans consumer fitness optimization, remote patient monitoring, and workplace safety compliance tracking. Smartwatches command the dominant revenue share by integrating cellular connectivity and app ecosystems, while health monitors represent the fastest-expanding category as pulse oximetry and blood pressure approximation gain clinical credibility. Fitness trackers retain volume leadership in price-sensitive geographies where basic step and sleep tracking suffice.
FDA 510(k) clearance pathways govern clinical-grade health monitors marketed in the United States, while the EU Medical Device Regulation imposes stricter post-market surveillance on bands claiming diagnostic utility. China's NMPA and GB standards for electromagnetic compatibility shape domestic product specifications and export eligibility. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring, as payer acceptance will determine whether health-monitor bands transition from consumer gadgets to prescribed medical devices.
Market Dynamics
Corporate wellness mandates and FDA 510(k) clearance pathways are compressing product development cycles while elevating clinical credibility requirements for wearable bands seeking reimbursement eligibility.
Growth Catalysts
- Bluetooth Low Energy 5.3:Extended range and reduced power draw enable continuous glucose monitoring integration without daily charging cycles.
- Remote Patient Monitoring reimbursement codes:CMS expansion of CPT 99453-99458 is pulling health systems toward prescribed wearable deployments.
- Workplace safety compliance:OSHA heat-illness prevention guidelines drive bulk orders from logistics and construction employers monitoring worker vitals.
Market Restraints
- Photoplethysmography accuracy limitations:Skin tone variation and motion artifacts constrain clinical-grade blood pressure approximation reliability.
- Lithium polymer supply concentration:Cell production clusters in Guangdong and Jiangsu provinces create single-source vulnerability for thin-form-factor bands.
- EU Medical Device Regulation post-market surveillance:MDR Article 83 mandates expensive clinical follow-up studies for diagnostic claim bands.
Strategic Opportunities
- India's Ayushman Bharat digital health mission:Government-subsidized wearable distribution to rural primary health centers lacks qualified suppliers.
- Photoplethysmography-electrocardiography sensor fusion:Combined PPG-ECG arrays enable arrhythmia detection without chest-worn electrodes.
- Direct-to-employer channels:Bypassing retail and insurance intermediaries cuts procurement friction for Fortune 500 wellness programs.
Industry Challenges
- FDA 510(k) predicate device matching:Novel photoplethysmography algorithms struggle to find equivalent cleared devices for streamlined review.
- Legacy hospital EHR integration:HL7 FHIR compliance gaps force expensive middleware development for health-monitor data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Band Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bands, Fitness Trackers, Health Monitors, Smartwatches Usage Scenario: Fitness Tracking, Sleep Monitoring, Heart Rate Monitoring, GPS Navigation Connectivity: Bluetooth, Wi-Fi, NFC, Cellular Target User: Fitness Enthusiasts, Health-Conscious Users, Tech Savvy Consumers, Seniors |
| Companies Covered | Fitbit, Xiaomi, Amazfit, Garmin, Apple, Samsung Electronics, Huawei Technologies, Boat, Oura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Band Market Strategic Shifts
Sensor miniaturization and algorithmic clinical validation are collapsing the boundary between consumer fitness accessories and prescribed medical devices.
Photoplethysmography signal processing is rewriting how wearable bands approximate cardiovascular metrics without invasive instrumentation. Health systems in Germany and the Netherlands are piloting pulse oximetry-enabled bands for post-surgical remote monitoring. The technology is rewriting reimbursement pathways by generating continuous data streams that satisfy payor evidence requirements for chronic condition management.
EU Medical Device Regulation Class IIa reclassification is forcing manufacturers to rebuild quality management systems around post-market clinical follow-up. Diagnostic-claim bands now face notified body scrutiny equivalent to implantable devices. The regulation is compressing startup viability timelines while advantaging incumbents with existing ISO 13485 infrastructure.
Employer-sponsored wellness programs are consolidating purchasing decisions away from individual consumers toward benefits administrators negotiating enterprise licenses. Corporate procurement teams now specify API access and data portability as standard contract terms. This concentration is most visible in US self-insured employers above five thousand lives, where wearable subsidies have replaced gym membership reimbursements as the standard preventive benefit.
Wearable Band Market Segmentation
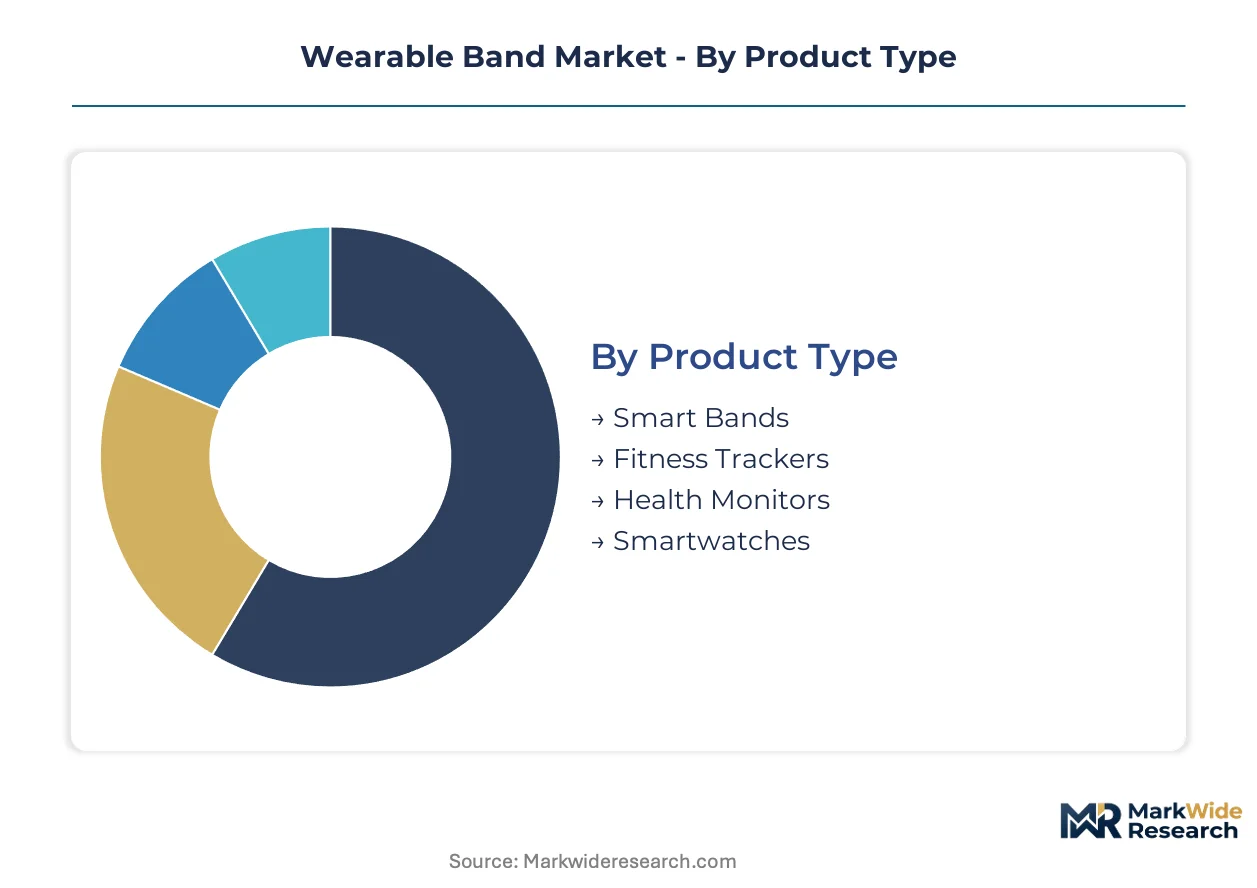
Wearable band segmentation reveals how hardware integration depth determines pricing power and customer lifetime value. Product architecture choices between standalone operation and smartphone-tethered functionality split the addressable market into distinct procurement channels and margin profiles.
Product Type:
Integration depth separates segments between fully autonomous systems with embedded cellular modems and accessory-class devices dependent on paired smartphones for data processing and display.
- Smartwatches:Autonomous wrist-worn computers integrating application processors, cellular basebands, and AMOLED displays within 40-60 gram enclosures. Demand concentrates among US and Chinese urban professionals where standalone calling and payment functionality justifies premium positioning against smartphone dependency.
- Health Monitors:Clinical-grade sensor arrays combining photoplethysmography with electrocardiography electrodes and pulse oximetry LEDs, designed for FDA 510(k) or NMPA Class II clearance pathways. German and Dutch hospital systems are piloting these for post-surgical remote monitoring where reimbursement codes now cover prescribed deployment.
- Smart Bands:Mid-tier devices bridging fitness tracking with limited smart features—notification mirroring, NFC payments, and basic app ecosystems—typically operating 5-7 days between charges.
- Fitness Trackers:Entry-level accelerometer-based units delivering step counting, sleep staging, and calorie estimation through simplified OLED or memory-in-pixel displays.
Smartwatches lead volumes today; health monitors are gaining share fastest.
Usage Scenario:
Application specificity determines sensor fusion requirements and algorithm validation burden, with medical-adjacent use cases demanding clinical-grade accuracy certification.
- Heart Rate Monitoring:Continuous photoplethysmography signal processing for resting, active, and recovery phase cardiovascular assessment. US corporate wellness programs specify this capability as baseline for employee subsidy eligibility.
- Fitness Tracking:Multi-axis accelerometer and gyroscope integration for activity classification, rep counting, and energy expenditure modeling. India's fast-growing consumer base drives volume in this entry segment where basic step and calorie metrics suffice.
- Sleep Monitoring:Overnight accelerometry and optical heart rate variability analysis for sleep stage classification and respiratory disturbance detection.
- GPS Navigation:Multi-constellation satellite receiver integration enabling pace, distance, and elevation tracking without smartphone pairing.
Fitness tracking anchors volume across price-sensitive geographies; heart rate monitoring commands the steepest expansion trajectory as clinical credibility deepens.
Connectivity:
Wireless architecture choices trade battery endurance against functional autonomy, with cellular integration enabling prescribed medical use cases beyond smartphone range.
- Bluetooth:Low Energy 5.3 transceivers dominating accessory-class devices with sub-10mW power draw enabling week-long operation.
- Cellular:Embedded LTE-M or NB-IoT modems for standalone emergency response and continuous remote patient monitoring data transmission.
- Wi-Fi:High-bandwidth local connectivity for firmware updates and media sync in premium smartwatch configurations.
- NFC:Secure element integration for contactless payment tokenization and access control credential storage.
Bluetooth dominates shipment volumes; cellular is climbing the fastest as reimbursement eligibility expands for prescribed health monitors.
Target User:
Demographic targeting shapes industrial design priorities—durability and simplicity for aging populations versus performance metrics and social features for athletic cohorts.
- Seniors:Fall detection, medication reminders, and emergency SOS functionality with large-format displays and simplified interaction paradigms.
- Health-Conscious Users:Preventive wellness focus combining activity goals with stress and recovery metrics for lifestyle optimization.
- Fitness Enthusiasts:Training load, VO2 max estimation, and structured workout guidance for amateur and competitive athletes.
- Tech Savvy Consumers:Early adopter segment prioritizing novel sensors, third-party application ecosystems, and aesthetic customization.
Fitness enthusiasts anchor current volume; seniors represent the fastest-expanding addressable demographic as aging populations digitize health management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing clusters supply hardware to India's fast-growing consumer base, while US reimbursement codes pull clinical-grade devices toward prescribed medical use. Germany and the Netherlands pilot remote monitoring programs that validate European demand for health-certified bands.
United States
Corporate wellness programs at Fortune 500 employers drive bulk procurement of fitness-tracking wearables as preventive benefits replace gym reimbursements. FDA 510(k) clearance pathways govern clinical-grade health monitors seeking reimbursement eligibility under expanded CMS remote patient monitoring codes. Silicon Valley and Boston corridors concentrate health-tech startups developing photoplethysmography algorithms for arrhythmia detection.
China
Domestic consumer demand and export manufacturing capacity anchor global supply for entry-level fitness trackers and premium smart bands. NMPA Class II device regulations and GB electromagnetic compatibility standards shape both domestic specifications and export eligibility. Guangdong and Jiangsu provinces cluster lithium polymer cell production and final assembly operations for thin-form-factor wearable devices.
Germany
Hospital systems pilot pulse oximetry-enabled bands for post-surgical remote monitoring where statutory health insurance evaluates reimbursement. EU Medical Device Regulation Class IIa reclassification imposes notified body scrutiny equivalent to implantable devices on diagnostic-claim wearables. Baden-Württemberg and Bavaria host precision sensor manufacturers supplying photoplethysmography-electrocardiography fusion arrays.
India
Price-sensitive consumers drive volume demand for basic step-counting and sleep-tracking fitness bands in tier-2 and tier-3 cities. Ayushman Bharat digital health mission contemplates government-subsidized wearable distribution to rural primary health centers lacking qualified suppliers. Karnataka and Maharashtra states concentrate electronics manufacturing zones assembling wearable devices for domestic consumption and regional export.
Netherlands
Health insurers experiment with prescribed wearable deployments for chronic condition management using continuous data streams to satisfy evidence requirements. EMA-aligned regulations and national health technology assessment processes evaluate clinical validity before reimbursement approval. Eindhoven's high-tech corridor hosts sensor miniaturization specialists supplying photoplethysmography modules to European wearable manufacturers.
Wearable Band Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-integrated players capturing premium pricing while scale-oriented fabricators dominate volume tiers. The vendor base concentrates around three strategic archetypes: integrated technology platforms leveraging services revenue, component specialists defending GPS precision or sleep analytics niches, and manufacturing-scale operators undercutting on hardware margins. M&A activity targets sensor fusion capabilities and FDA-cleared algorithm portfolios, while strategic partnerships with health systems accelerate reimbursement pathway navigation.
Within the ecosystem-integrated tier, Apple and Samsung Electronics exemplify platform players converting hardware sales into recurring services revenue through fitness and health subscriptions. Xiaomi occupies a position among scale-driven operators leveraging manufacturing concentration to undercut premium rivals across emerging markets. Garmin anchors the specialization vector, representing GPS precision and outdoor durability defenders targeting athletic professionals with defensible technical differentiation.
| Leading Market Players |
|---|
| Fitbit |
| Xiaomi |
| Amazfit |
| Garmin |
| Apple |
| Samsung Electronics |
| Huawei Technologies |
| Boat |
| Oura |
| Others |
Value Chain & Pricing Dynamics
Optical sensor engineering talent concentrated in Shenzhen and Eindhoven feeds labor-cost differentials that widen pricing-tier spreads between clinical-grade health monitors and entry-level fitness trackers.
Pricing Analysis
Capacity additions in Guangdong Province are reshaping price floors for entry-level fitness trackers while premium smartwatches defend positioning through ecosystem lock-in. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared health monitors from mid-tier smart bands and basic accelerometer units. Price differentiation rests on certification grade and volume scale, with clinical-grade devices commanding substantial premiums over consumer accessories. Cost compression in the economy tier is intensifying because manufacturing scale operators from China are flooding price-sensitive geographies. India's rural primary health centers exhibit the highest price sensitivity, while US self-insured employers above five thousand lives demonstrate the lowest.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and warranty replacement concentrate in Dongguan and Shenzhen, where dedicated facilities process returned devices for component recovery and resale into secondary markets. Geographic supply concentration centers on China, South Korea, and Taiwan for lithium polymer cells, AMOLED displays, and photoplethysmography sensor modules. Raw material dependencies draw from rare earth processing for magnetometers, gallium arsenide for optical emitters, and cobalt compounds for battery cathodes. Single-source vulnerability in Guangdong and Jiangsu provinces for thin-form-factor lithium polymer cells creates structural supply risk. Distribution runs through enterprise procurement channels for corporate wellness programs and retail electronics chains for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where demand is shifting toward clinical-grade specifications that satisfy FDA 510(k) clearance and reimbursement eligibility requirements.
For Market Incumbents: Anchor defensive positioning through ISO 13485 quality management infrastructure investments that compress startup viability timelines under EU Medical Device Regulation Class IIa reclassification. Pursue backward integration into photoplethysmography-electrocardiography sensor fusion arrays to defend margin position against modular component suppliers. Control direct-to-employer channels bypassing retail intermediaries for Fortune 500 wellness program procurement.
For New Entrants and Emerging Players: Rural primary health centers under India's Ayushman Bharat digital health mission represent the most penetrable buyer archetype, as government-subsidized wearable distribution lacks qualified suppliers. Target post-surgical remote monitoring applications in German and Dutch hospital systems where statutory health insurance evaluates reimbursement for pulse oximetry-enabled bands. Pursue white-label manufacturing partnerships with established electronics assembly operators in Karnataka and Maharashtra to accelerate market entry without captive production investment.
For Investors and Strategic Acquirers: Health systems and self-insured employers are the most active acquirer categories in this space, consolidating purchasing decisions away from individual consumers toward benefits administrators negotiating enterprise licenses. The long-term viability window favors FDA-cleared algorithm portfolios and sensor fusion capabilities over pure hardware fabrication. Target acquisition profiles center on photoplethysmography signal processing specialists with existing 510(k) predicates. Monitor CMS reimbursement code expansions for remote patient monitoring as the critical inflection signal determining whether health-monitor bands transition from consumer gadgets to prescribed medical devices.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks CMS reimbursement eligibility for prescribed health monitor deployments in US health systems. |
| Sensor Fusion Development | Combined PPG-ECG arrays enable arrhythmia detection without chest-worn electrodes, deepening clinical credibility. |
| Enterprise Channel Partnership | Direct-to-employer contracts with Fortune 500 benefits administrators replace retail procurement friction. |
| EU MDR Quality System Build | ISO 13485 infrastructure satisfies notified body scrutiny equivalent to implantable devices for diagnostic claims. |
| Bluetooth Low Energy 5.3 Integration | Extended range and reduced power draw enable continuous glucose monitoring without daily charging cycles. |
Study Parameters
Bottom-up corporate wellness and remote patient monitoring modeling reconciled against top-down component shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and benefits administrators at self-insured employers combined with secondary validation against FDA 510(k) filings, CMS reimbursement code databases, NMPA Class II device registrations, and EU MDR notified body certifications. Triangulation between demand-side procurement data and supply-side manufacturing cluster output ensures cross-verification of volume and value estimates.
Input-output matrices map photoplethysmography sensor module production through final assembly to end-use consumption across smartwatch, health monitor, smart band, and fitness tracker categories. Segmentation dimensions modeled include product integration depth, usage scenario specificity, wireless architecture choice, and target demographic profile. CAGRs were derived from fitted growth curves applied to historical shipment data and forward-projected reimbursement code expansion scenarios. Industry-specific forecast inputs incorporate lithium polymer cell supply constraints and evolving Bluetooth Low Energy standard adoption curves.
Underlying measurement precision varies by segment; FDA-cleared health monitors carry tighter precision than entry-level fitness trackers due to regulatory filing transparency. Forecasts reflect assumptions around CMS reimbursement code permanence, EU MDR enforcement consistency, and lithium polymer supply chain stability. Practitioners should monitor NMPA export certification changes, OSHA heat-illness prevention guideline updates, and photoplethysmography algorithm predicate device availability for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Wearable Equipment Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
GPS Watches for Kids Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
Smart Sports Wearables Market
Wearable Fitness Technology
Global Weight Management Devices Market
Wearable Fitness Technology
Wearable Devices Market
Wearable Fitness Technology
Flexible Wearable Device Market
Wearable Fitness Technology
Pocket Pedometers Market
Wearable Fitness Technology
Stress Tracking Devices Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Fitness Tracker Market