
 Gaming Peripheral Market | 2026-2036
Gaming Peripheral Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Peripheral Market Intelligence
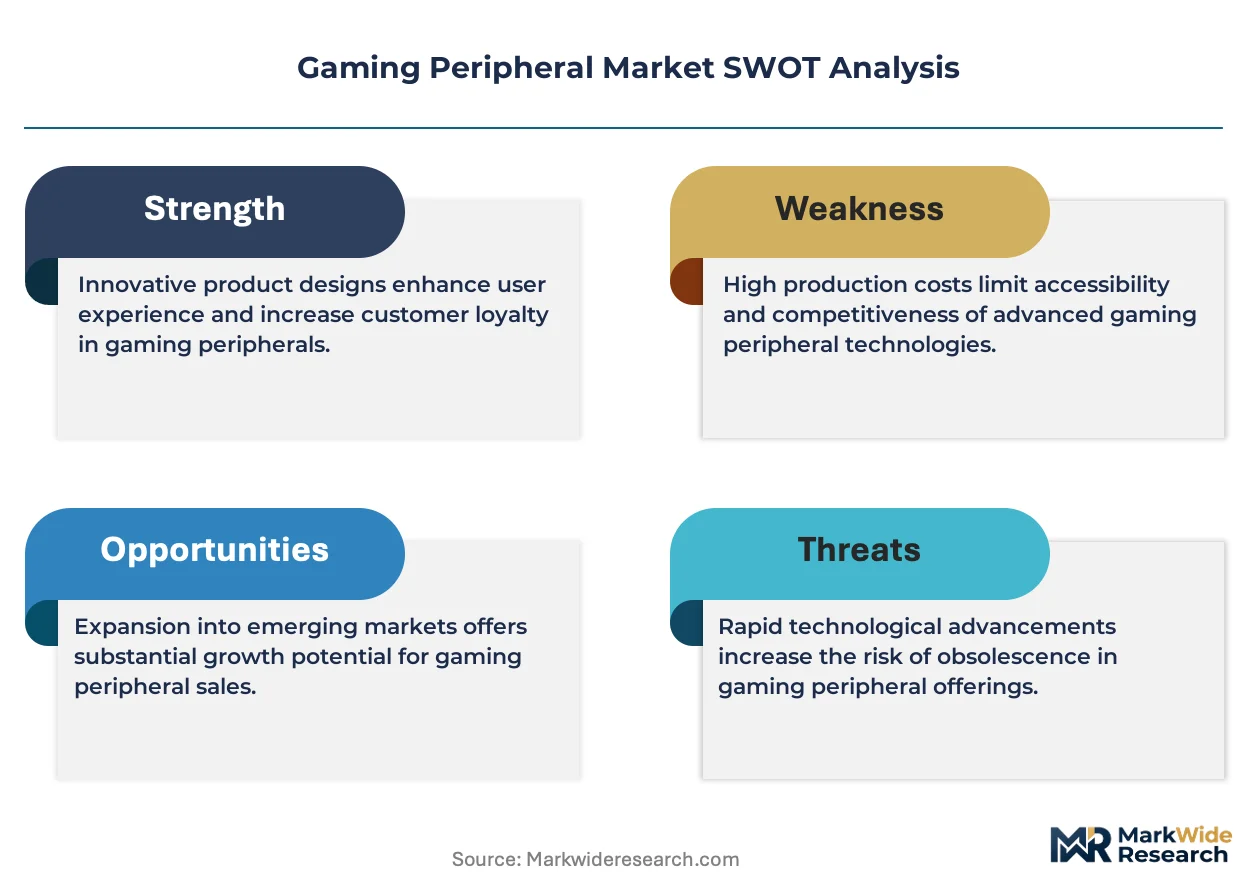
Aftermarket service revenue from firmware subscriptions and extended warranties is narrowing as hardware margins compress across the sector. Logitech leverages its vertical integration in sensor manufacturing to sustain cost advantages in premium mice. Razer Inc. differentiates through RGB ecosystem lock-in, while Corsair anchors its position in mechanical keyboard switches through captive supply arrangements.
Gaming peripherals encompass input and output devices engineered for interactive entertainment, typically featuring sub-1ms polling rates, mechanical actuation forces between 45-60g, and audio drivers tuned to 20Hz-20kHz frequency response for spatial positioning. These devices serve competitive gamers, content creators, and casual users requiring precision and ergonomic endurance. Headsets and mechanical keyboards command the deepest margin pools due to upgrade frequency and customization demand, while haptic feedback technology represents the fastest-expanding capability layer across controllers and mice. PC gaming applications generate the highest per-user spend, though mobile gaming peripherals are gaining structural importance as smartphone esports formalize.
FCC certification governs wireless transmission protocols in the United States, while the EU RoHS directive and REACH framework restrict hazardous substances in plastics and solder compositions. CE marking requirements enforce electrical safety and electromagnetic compatibility standards for market access across European member states. Stakeholders must monitor evolving battery transportation regulations and right-to-repair legislation that could reshape warranty structures and component modularity requirements.
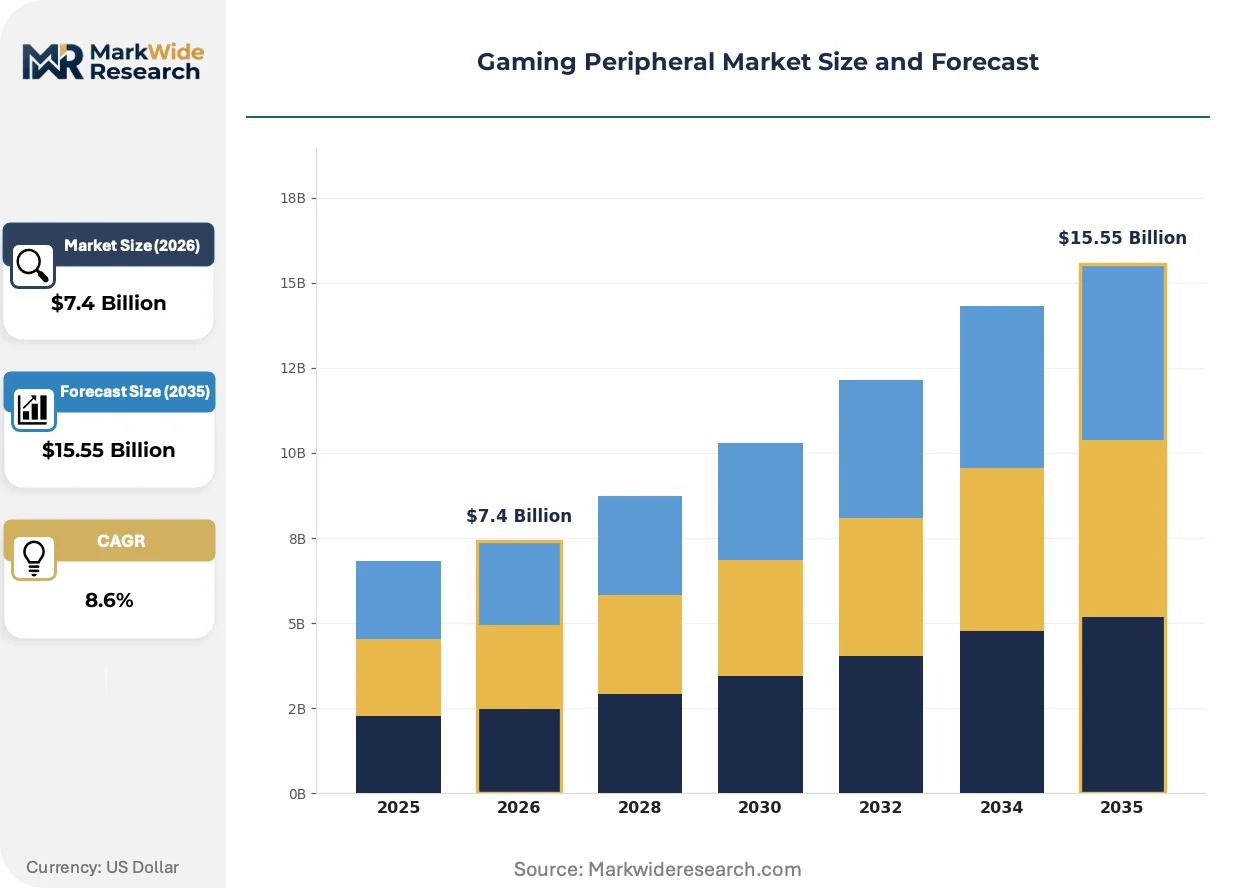
Market Dynamics
The gaming peripheral sector is experiencing margin compression as firmware subscriptions and extended warranties lose traction, forcing manufacturers to recapture profitability through sensor verticalization and ecosystem lock-in strategies.
Growth Catalysts
- Esports Formalization:Professional gaming leagues in China, South Korea, and the United States are mandating standardized peripheral specifications. Tournament organizers now require sub-1ms polling rates and mechanical switches with certified actuation forces.
- REACH Compliance Innovation:EU RoHS directive constraints on hazardous solder compositions are accelerating lead-free PCB manufacturing. German and Dutch component suppliers are capturing premium positioning through certified green material streams.
- Haptic Feedback Diffusion:Force-feedback actuators are migrating from controllers into premium mice and flight sticks. Japanese semiconductor foundries are scaling MEMS production to serve this cross-category demand.
Market Restraints
- Optical Sensor Supply Concentration:PixArt Imaging and Avago control over 70% of high-DPI sensor supply. Taiwan-based packaging facilities face recurring water shortage risks during drought cycles.
- Key Switch Input Volatility:POM and PBT polymer prices fluctuate with crude oil derivatives. Cherry MX and Gateron production schedules remain exposed to German and Chinese petrochemical feedstock swings.
- Wireless Interference Limitations:FCC Part 15 rules constrain 2.4GHz transmission power for low-latency mice. Urban environments with dense Wi-Fi saturation degrade signal stability beyond advertised ranges.
Strategic Opportunities
- India Mobile Gaming Peripheral Gap:Smartphone esports tournaments in Mumbai and Bangalore lack certified controller and audio peripheral supply. Local distributors report 18-month replacement cycles versus 36-month PC averages.
- Right-to-Repair Legislative Tailwind:EU and US state-level repairability mandates are creating modular keyboard and mouse architectures. Swappable switches and battery packs extend product lifecycles while opening replacement component revenue.
- Spatial Audio Convergence:Head-related transfer function algorithms are merging with head-tracking gyroscopes. Content creators in Los Angeles and Seoul are adopting integrated audio-visual capture peripherals for streaming workflows.
Industry Challenges
- Firmware Engineering Talent Scarcity:Embedded systems developers with USB HID and wireless stack expertise command 40% salary premiums. Shenzhen and Taipei hiring markets show sustained vacancy rates for low-latency protocol specialists.
- CE Marking Timeline Compression:Electromagnetic compatibility testing queues at notified bodies extend 14-22 weeks. Smaller manufacturers miss seasonal launch windows waiting for EMC certification clearance.
- RGB Ecosystem Patent Thickets:Razer, Corsair, and Logitech hold overlapping lighting synchronization IP. New entrants face licensing costs or workaround engineering that degrades interoperability performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Peripheral Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Keyboards, Mice, Headsets, Controllers End User: Casual Gamers, Professional Gamers, Esports Teams, Streamers Technology: Wired, Wireless, RGB Lighting, Haptic Feedback Application: PC Gaming, Console Gaming, Mobile Gaming, VR Gaming |
| Companies Covered | Logitech, Razer Inc., Corsair, SteelSeries, Alienware, Turtle Beach, Cooler Master, HyperX, ASUSTeK Computer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Peripheral Market Strategic Shifts & Innovations
Peripheral architecture is pivoting from hardware-centric margin models toward software-defined feature delivery, with sensor fusion and cloud-based configuration layers displacing fixed-function devices.
Optical-mechanical hybrid switches are migrating from proprietary keyboard implementations toward standardized open specifications. Gaming laptop OEMs in Taiwan and California are adopting these for integrated input modules. The technology is migrating from enthusiast DIY markets into mainstream retail SKUs, compressing traditional Cherry MX dominance in the $80-120 price band.
The EU CSRD disclosure requirements are forcing peripheral manufacturers to document supply chain carbon intensity across Scope 3 categories. German distributors now reject uncertified plastic housings. Assembly partners in Poland and Hungary are capturing volume as brands relocate final integration to meet nearshoring compliance thresholds.
Direct-to-consumer configuration platforms are displacing retail assortment models for high-ASP peripherals. Enthusiast buyers in Texas and Bavaria now expect 48-hour custom switch and keycap fulfillment. Amazon and specialist etailers are responding with micro-fulfillment partnerships that bypass traditional distributor markups in North American and Western European markets.
Gaming Peripheral Market Segmentation
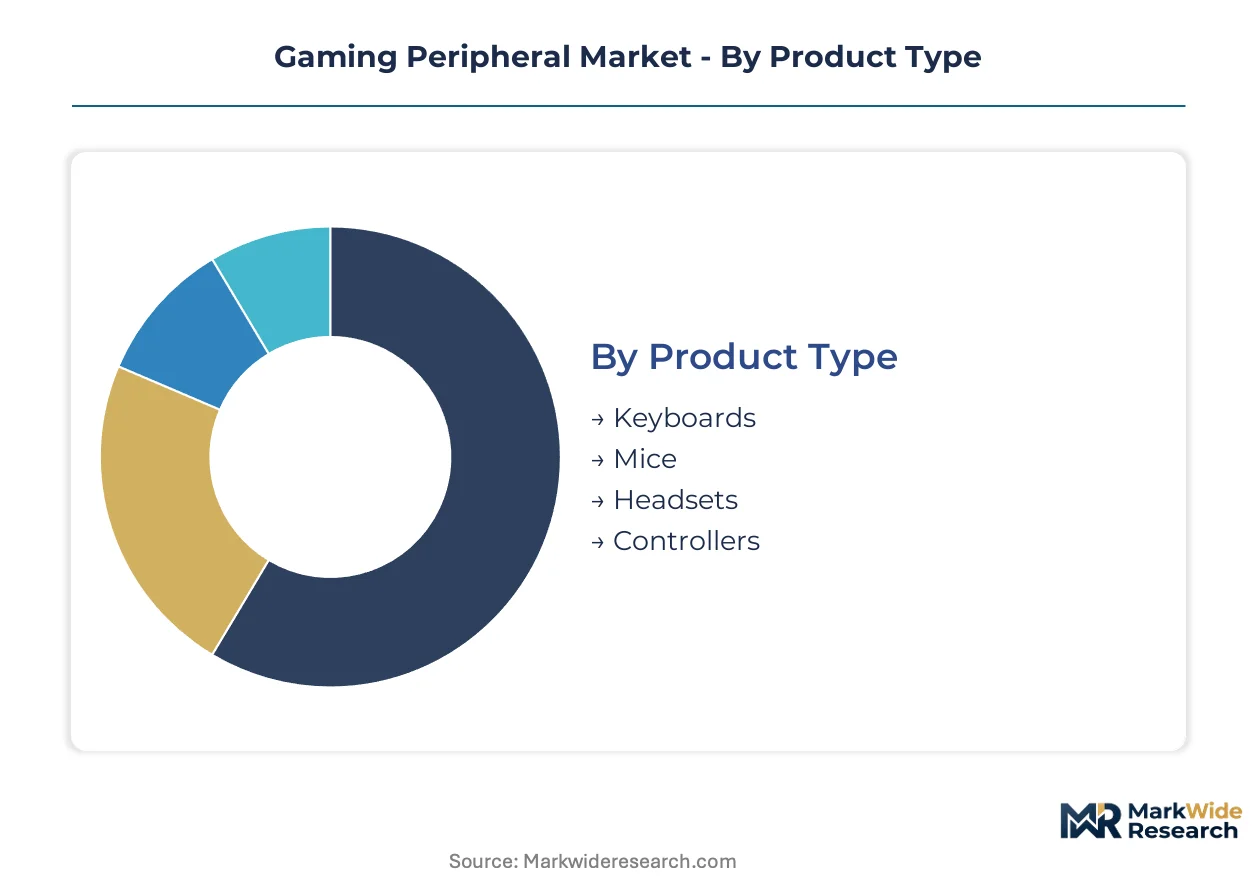
Gaming peripheral segmentation reveals divergent service intensity patterns across hardware categories. Keyboard and mouse vendors face compressed firmware subscription renewals, while headset manufacturers capture recurring revenue through spatial audio software licensing. Understanding these segment-specific margin mechanics guides portfolio allocation decisions.
Product Type:
After-sales service intensity varies sharply across input device categories, with mechanical keyboards demanding the highest switch replacement frequency and mice generating premium sensor calibration support tickets.
- Keyboards:Mechanical actuation mechanisms with 45-60g force tolerances require periodic switch replacement. Esports venues in Shanghai and Los Angeles budget quarterly maintenance cycles for tournament-grade units. Custom keycap fulfillment platforms now compress replacement part margins.
- Mice:Sub-1ms polling rate sensors need firmware recalibration as surface materials evolve. PixArt and Avago sensor supply concentration forces manufacturers to maintain dedicated technical support teams for DPI drift complaints.
- Headsets:20Hz-20kHz spatial audio drivers paired with head-tracking gyroscopes.
- Controllers:Force-feedback actuators and analog stick modules with haptic migration from console to PC peripherals.
By volume, Mice leads. By growth pace, Headsets is ahead.
End User:
Cost tier stratification separates disposable-income casual purchasers from institutional procurement budgets with multi-year replacement schedules.
- Casual Gamers:Price-sensitive segment prioritizing plug-and-play reliability over customization. Retail channels in Texas and Bavaria report 18-month replacement cycles versus professional-grade 36-month averages. RGB feature penetration remains lowest in this cohort.
- Professional Gamers:Sub-1ms latency requirements and certified mechanical switch specifications. Tournament organizers in Seoul and Los Angeles mandate standardized peripheral pools for competitive integrity.
- Esports Teams:Bulk procurement with standardized specifications and fleet management contracts.
- Streamers:Integrated audio-visual capture peripherals with head-tracking spatial audio for content production workflows.
Casual Gamers dominate unit shipments. Professional Gamers command the steepest expansion trajectory in per-user spend.
Technology:
Supply concentration in wireless protocol stacks and MEMS actuator foundries shapes component availability across connectivity and feedback categories.
- Wired:USB HID protocol implementation with zero-latency signal transmission. FCC Part 15 exemption eliminates wireless certification queues. German and Polish assembly partners prioritize wired SKUs for CE marking timeline predictability.
- Wireless:2.4GHz transmission protocols constrained by FCC power limits and urban Wi-Fi saturation. Japanese semiconductor foundries scaling Bluetooth Low Energy chip production for cross-platform pairing.
- RGB Lighting:Synchronization IP thickets across Razer, Corsair, and Logitech patent portfolios.
- Haptic Feedback:MEMS force-feedback actuators migrating from controllers into premium mice and flight sticks.
Wired maintains volume leadership. Wireless is expanding most quickly as smartphone esports formalize.
Application:
Customer type differentiation separates high-ASP PC enthusiasts from mobile-first entrants with compressed accessory budgets and shorter replacement horizons.
- PC Gaming:Highest per-user spend with modular upgrade paths. Custom switch and keycap direct-to-consumer platforms in Texas and Bavaria bypass traditional distributor markups. Steam hardware survey data informs sensor DPI specification roadmaps.
- Console Gaming:Proprietary controller ecosystems with limited third-party penetration. Sony and Microsoft certification programs gate aftermarket peripheral compatibility.
- Mobile Gaming:Smartphone controller and audio peripheral gap in Mumbai and Bangalore tournament circuits.
- VR Gaming:Inside-out tracking compatibility requirements and motion sickness mitigation through haptic grounding.
PC Gaming leads by installed base value. Mobile Gaming is gaining share fastest as smartphone esports infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers prioritize aggressive feature-to-price ratios while German and US purchasers absorb premium positioning for certified tournament-grade specifications. This elasticity divergence fragments go-to-market strategies across major demand centers.
China
Domestic brands dominate procurement volumes through aggressive pricing on mechanical keyboards and high-DPI mice. MIIT certification requirements for wireless transmission equipment add compliance layers for foreign entrants. Shenzhen and Dongguan manufacturing clusters concentrate final assembly for export-bound peripherals serving North American and European markets.
United States
Esports tournament organizers in Los Angeles mandate sub-1ms polling rates and certified switch specifications for competitive integrity. FCC Part 15 rules constrain 2.4GHz transmission power for wireless mice, degrading signal stability in dense urban Wi-Fi environments. Austin and Seattle tech corridors anchor peripheral R&D operations focused on low-latency protocol development.
Germany
Industrial buyers and enthusiast consumers absorb premium pricing for REACH-compliant green material streams. ECHA enforcement of RoHS solder composition restrictions accelerates lead-free PCB manufacturing transitions. Hamburg and Munich distribution hubs reject uncertified plastic housings, filtering supply chain access for Asian manufacturers.
South Korea
Professional gaming leagues in Seoul enforce standardized peripheral pools with certified actuation force tolerances. KCC electromagnetic compatibility certification parallels CE marking requirements for wireless device market access. Busan semiconductor foundries scale MEMS production for force-feedback actuator demand migrating across controller and mouse categories.
India
Smartphone esports tournaments in Mumbai and Bangalore expose certified controller and audio peripheral supply gaps with 18-month replacement cycles. BIS quality certification requirements for electronic goods create entry barriers for uncertified imports. Delhi-NCR distributors report structural undersupply of tournament-grade mobile gaming peripherals relative to formalizing competitive infrastructure.
Gaming Peripheral Market Key Industry Players
Vertically integrated specialists and ecosystem-platform players split the market between cost-engineered sensor control and software-defined feature lock-in. Three archetypes dominate: sensor-integrated hardware manufacturers, RGB ecosystem platform operators, and modular component specialists. Competitive intensity concentrates on backward integration into MEMS foundry capacity and strategic patent positioning around lighting synchronization protocols.
Within the ecosystem-platform tier, Razer Inc. exemplifies RGB lock-in strategies, while Logitech anchors sensor-verticalized positioning. Corsair occupies the modular component specialist archetype through captive keyboard switch supply arrangements. These three companies represent divergent margin defense mechanisms as hardware pricing compresses and firmware subscription traction narrows across the sector.
| Leading Market Players |
|---|
| Logitech |
| Razer Inc. |
| Corsair |
| SteelSeries |
| Alienware |
| Turtle Beach |
| Cooler Master |
| HyperX |
| ASUSTeK Computer Inc. |
| Others |
Cost & Logistics Intelligence
PixArt Imaging and Avago sensor supply concentration in Taiwan and China directly determines where premium margin pools accumulate downstream. Tournament-grade mice with certified sub-1ms polling rates command pricing premiums because sensor calibration expertise sits with a handful of packaging facilities facing recurring water shortage risks.
Pricing Analysis
After-sales service tiers including switch replacement programs and extended firmware calibration contracts drive lifetime value capture. Three-tier pricing structure across premium, standard, and economy levels separates certified tournament-grade peripherals with REACH-compliant material streams from mass-market SKUs. Cost compression in the mid-tier is intensifying because domestic Chinese brands compete aggressively on feature-to-price ratios. Casual gamers in Texas and Bavaria exhibit highest price sensitivity, while esports teams in Seoul and Los Angeles absorb premium positioning for standardized fleet procurement.
Supply Chain Analysis
Extended payment terms from German and Dutch component suppliers are tightening working capital requirements for assembly partners. Manufacturing gravity centers on China, Taiwan, and Vietnam for PCB fabrication and final integration. POM and PBT polymer feedstocks draw from German and Chinese petrochemical complexes. Single-source vulnerability in MEMS actuator foundries exposes force-feedback controller production to Japanese semiconductor capacity constraints. Distribution runs through Hamburg and Munich hubs filtering REACH-certified green material streams before EU market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through esports team fleet procurement contracts and direct-to-consumer platform disintermediation. Tournament organizers now mandate standardized peripheral pools, compressing vendor choice sets.
For Market Incumbents: Entrench sensor verticalization advantages by deepening captive supply arrangements with Taiwan-based packaging facilities. Defend against RGB ecosystem lock-in erosion by investing in optical-mechanical hybrid switch certification for integrated laptop modules. CE marking timeline compression at notified bodies threatens seasonal launch windows. For New Entrants and Emerging Players: Mid-market mobile gaming peripherals in Mumbai and Bangalore represent the most penetrable entry point given 18-month replacement cycles and structural undersupply of tournament-grade controllers. Local BIS certification partnerships with Delhi-NCR distributors provide regulatory pathway acceleration. Direct-to-consumer configuration platforms bypass traditional Amazon and specialist etailer markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular component specialists holding captive keyboard switch supply arrangements. Long-term viability hinges on right-to-repair legislative tailwinds extending product lifecycles and opening replacement component revenue. Watch EU CSRD disclosure enforcement as signal for carbon intensity documentation requirements reshaping supply chain access.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Japanese semiconductor foundries scaling production for force-feedback actuator demand across controller and mouse categories. |
| REACH-Compliant Material Transition | German distributors rejecting uncertified plastic housings filters supply chain access for Asian manufacturers. |
| Direct-to-Consumer Platform Launch | Texas and Bavaria enthusiast buyers now expect 48-hour custom switch and keycap fulfillment bypassing traditional markups. |
| Optical-Mechanical Hybrid Certification | Taiwan and California gaming laptop OEMs adopting standardized open specifications compressing Cherry MX dominance. |
| Spatial Audio Software Licensing | Head-related transfer function algorithms merging with head-tracking gyroscopes capture recurring revenue from Los Angeles and Seoul content creators. |
Research Approach
Desk research of FCC Part 15 filings, EU REACH substance restriction databases, and Steam hardware survey data preceded structured interviews with esports tournament organizers, OEM procurement leads at Taiwanese laptop manufacturers, and firmware engineering directors at sensor suppliers. Primary fieldwork with mechanical switch production schedulers and German distribution channel partners combined with secondary validation from customs records and ECHA enforcement disclosures. Bottom-up unit shipment modeling triangulated against top-down category spend analysis.
Assumptions held fixed include REACH RoHS solder composition restrictions and FCC wireless transmission power limits, while esports formalization pace and right-to-repair legislative adoption were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, end user tier, connectivity technology, and application platform across the analysis window. CAGRs derived from installed base replacement cycles and per-user spend trajectory analysis. Forecast inputs incorporated BIS certification queue lengths and MEMS foundry capacity expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil derivative pricing affecting POM and PBT polymer costs or drought cycles impacting Taiwan packaging facility operations would shift the trajectory. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
United Kingdom Online Gambling Market
Gaming
FPS Game Market
Gaming
Serious Games Market
Gaming
Arcade Cabinet Market
Gaming
Puzzle Video Game Market
Gaming
Lottery Market
Gaming
Global Battle Royale Games Market
Gaming
Animation, VFX & Game Market
Gaming
SLG Game Market
Gaming
Arcade Games Market
Gaming
Australia Casino Tourism Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Global Esports Market
Gaming
Traditional Casual Games Market
Gaming
Social Gaming Market
Gaming
H5 Games Market