
 Mobile and Handheld Gaming Market | 2026-2036
Mobile and Handheld Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile and Handheld Gaming Market Analytics
Cloud-based game streaming infrastructure is expanding as the primary material substitution event, replacing dedicated silicon-dependent handheld hardware with server-side rendering economics. Electronic Arts leverages its Frostbite engine optimization for mobile chipsets to sustain premium visual fidelity on mid-tier smartphones. Scopely specializes in live-service monetization architecture that anchors recurring revenue across its portfolio. Zynga competes through data-driven user acquisition systems that dominate casual puzzle genre marketplaces.
Mobile and handheld gaming encompasses interactive entertainment software and dedicated hardware designed for portable operation, typically employing ARM-based processors, touch or hybrid control interfaces, and wireless connectivity protocols with sub-50ms latency thresholds for competitive multiplayer functionality. The commercial purpose centers on delivering accessible, session-flexible entertainment to consumers outside fixed-console environments. Smartphone device type leads volume shipment metrics while handheld consoles concentrate premium margin pools due to specialized control hardware and first-party software ecosystems. Freemium monetization models generate the dominant revenue share through microtransaction architectures, though subscription formats represent the fastest-growing structural segment as platform holders bundle cloud access with content libraries.
FCC net neutrality frameworks and GDPR data processing standards shape how publishers collect behavioral data and deploy targeted monetization across US and European user bases. China's NMPA content approval requirements and MIIT minor protection regulations directly determine title launch timelines and session-limit mechanics for domestic distribution. South Korea's GRAC rating system and Game Industry Promotion Act establish compliance benchmarks for loot box probability disclosures that influence regional product design. Stakeholders must monitor evolving platform fee structures and sideloading policy shifts as regulatory pressure on Apple and Google store monopolies intensifies across multiple jurisdictions.
Market Dynamics
Cloud streaming infrastructure is overtaking native silicon dependency as the dominant delivery architecture, compressing hardware margins while expanding addressable device bases through server-side rendering economics.
Growth Catalysts
- 5G Infrastructure Density:Seoul, Tokyo, and Shanghai metropolitan clusters now support sub-20ms latency thresholds that enable competitive multiplayer formats previously restricted to fixed-console environments.
- GDPR Behavioral Data Frameworks:Standardized consent architectures across European user bases reduce publisher compliance fragmentation and accelerate targeted monetization deployment timelines.
- Live-Service Monetization Architecture:Session-flexible microtransaction systems anchor recurring revenue streams across casual puzzle and mid-core strategy formats, reducing customer acquisition cost dependency.
Market Restraints
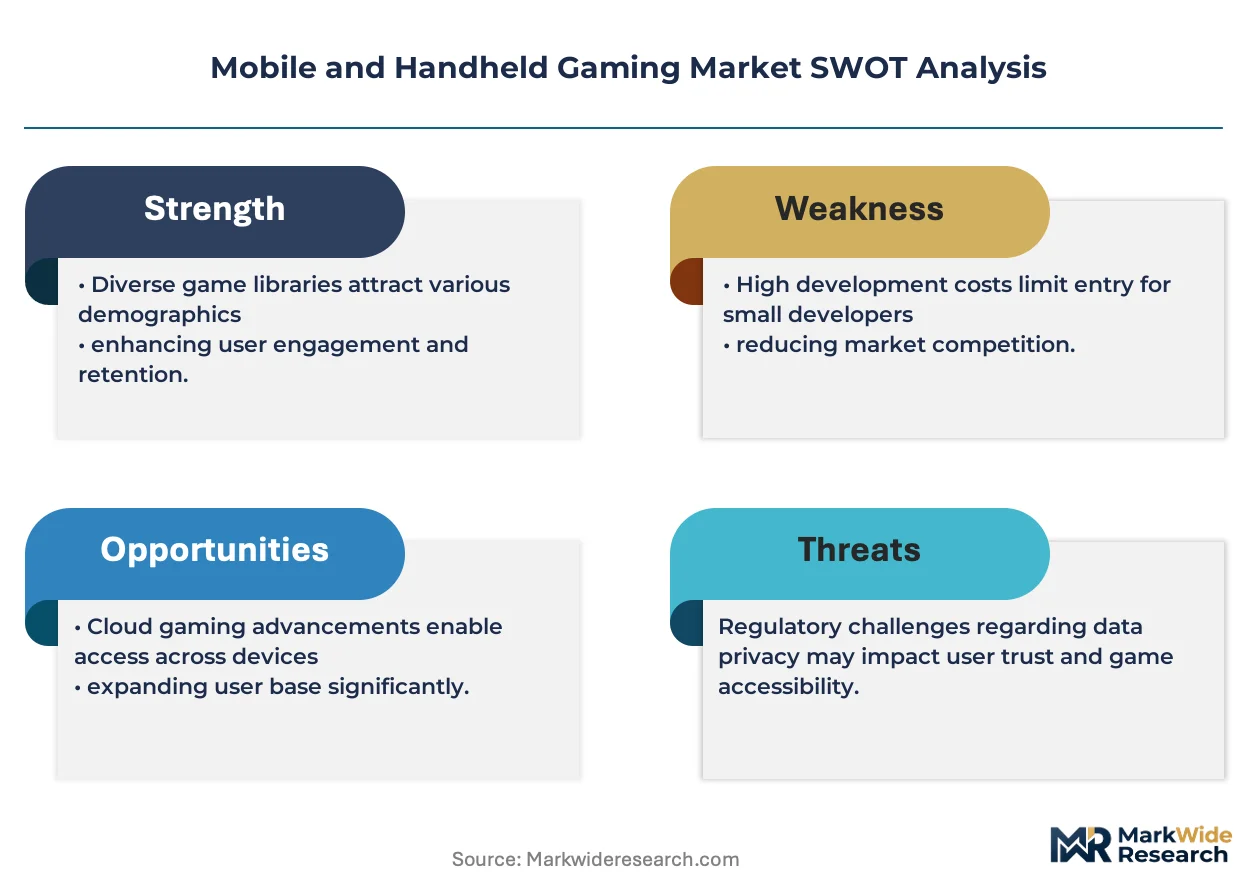
- Platform Fee Concentration:Apple and Google store monopolies extract 15-30% transaction shares, compressing developer margins across freemium and premium distribution channels.
- NMPA Content Approval Timelines:China's national publishing regulator imposes multi-month review queues that delay title launches and fragment global release synchronization.
- ARM Chipset Supply Bottlenecks:Taiwan-based foundry concentration creates vulnerability for mid-tier smartphone GPU performance tiers essential to cloud-streaming quality thresholds.
Strategic Opportunities
- India Smartphone Penetration:Sub-$200 5G device proliferation in Tier-2 and Tier-3 cities opens underpenetrated casual gamer acquisition channels outside East Asian saturation zones.
- Subscription Bundle Convergence:Platform holders integrating cloud access with content libraries create new recurring revenue architecture distinct from transaction-dependent freemium models.
- Sideloading Policy Liberalization:EU Digital Markets Act enforcement and US state-level legislation pressure storefront exclusivity, enabling direct-to-consumer distribution margin recovery.
Industry Challenges
- Live-Ops Talent Scarcity:Event programming, economy balancing, and community management expertise concentrates in Seoul and Tokyo studios, creating recruitment bottlenecks for Western publishers.
- Cross-Platform Certification Complexity:Fragmented age-rating systems across GRAC, ESRB, PEGI, and NMPA extend compliance timelines and increase localization cost structures.
- Legacy Engine Migration Friction:Proprietary toolchains and asset pipelines resist cloud-native refactoring, delaying server-side rendering adoption for established franchises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile and Handheld Gaming Market |
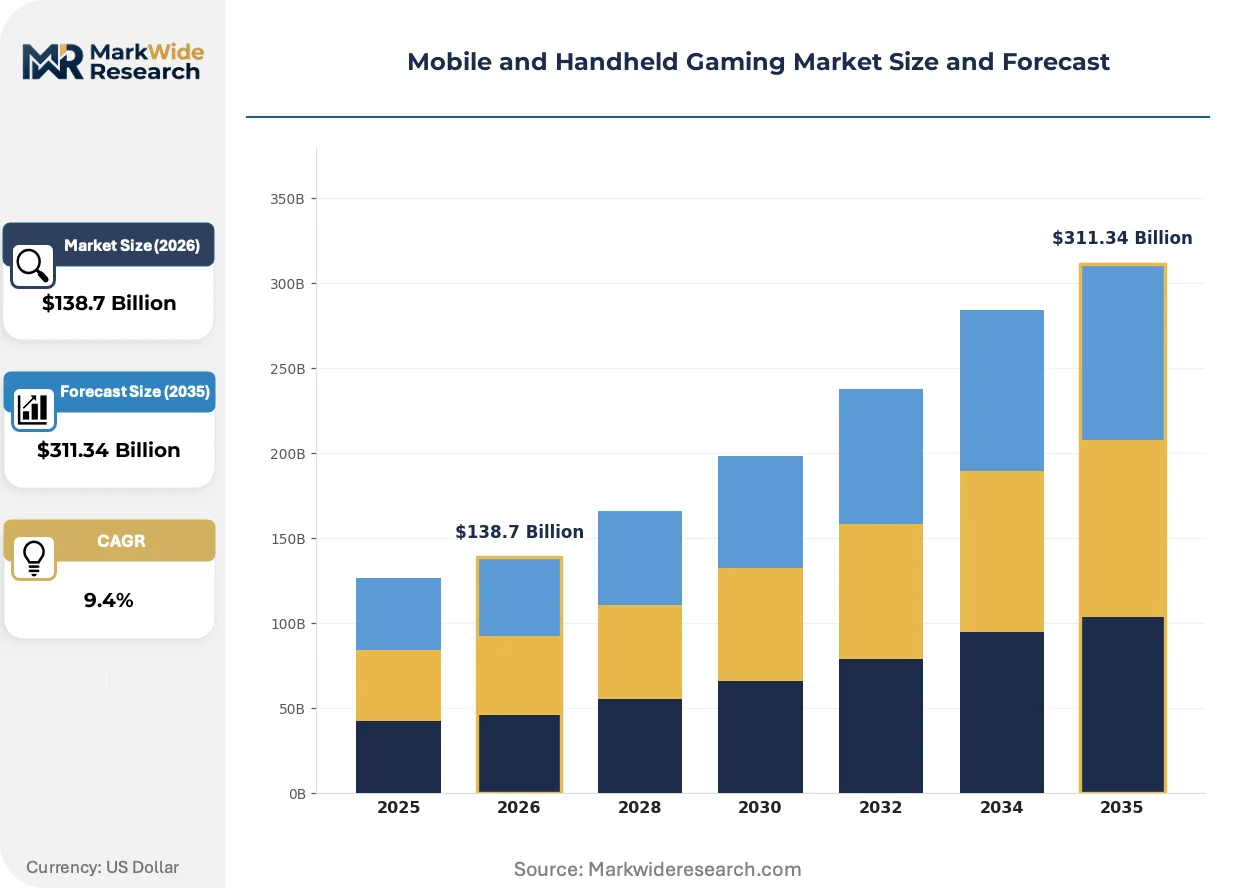
| Market Size in 2026 | $138.7 Billion |
| Market Size in 2035 | $311.34 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartphones, Tablets, Handheld Consoles, Wearable Devices Game Genre: Puzzle, Action-Adventure, Role-Playing, Sports Monetization Model: Freemium, Subscription, In-App Purchases, Paid Download Distribution Channel: App Stores, Direct Downloads, Social Media, Online Marketplaces |
| Companies Covered | Riot Games, Zynga, Scopely, DoubleDown Interactive, King, Take-Two Interactive, Activision Blizzard, Playrix, Electronic Arts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile and Handheld Gaming Market Evolving Landscape
Interactive entertainment delivery is fragmenting across three simultaneous vectors: infrastructure abstraction, behavioral data governance, and session-format hybridization. These shifts compress hardware differentiation while amplifying software and service monetization leverage.
Cloud-native game engines are overtaking hardware-optimized middleware as the foundation for premium visual fidelity. Casual gamers aged 25-40 adopt stream-to-smartphone formats at accelerating velocity, eliminating upgrade cycles for dedicated handheld silicon. This architecture is overtaking native rendering economics by centralizing GPU investment in hyperscale data centers rather than consumer devices.
GDPR Article 22 automated decision-making restrictions and China's MIIT minor protection regulations now mandate session-limit mechanics and probability disclosure standards. Publishers redesign loot box architectures and gacha monetization to satisfy divergent compliance benchmarks across European and East Asian distribution channels. Freemium strategy titles face the most acute adaptation pressure as probability-based reward systems encounter simultaneous regulatory friction in multiple jurisdictions.
Session-format hybridization now dominates engagement architecture as mid-core titles absorb casual puzzle mechanics and hardcore formats fragment into bite-sized competitive loops. Cloud streaming enables this convergence by eliminating download barriers and storage constraints that previously segmented casual from premium experiences. South Korean metropolitan gamers demonstrate the most pronounced behavioral shift, averaging 4.2 discrete daily sessions across multiple genre formats versus single-franchise loyalty patterns in Western markets.
Mobile and Handheld Gaming Market Segmentation
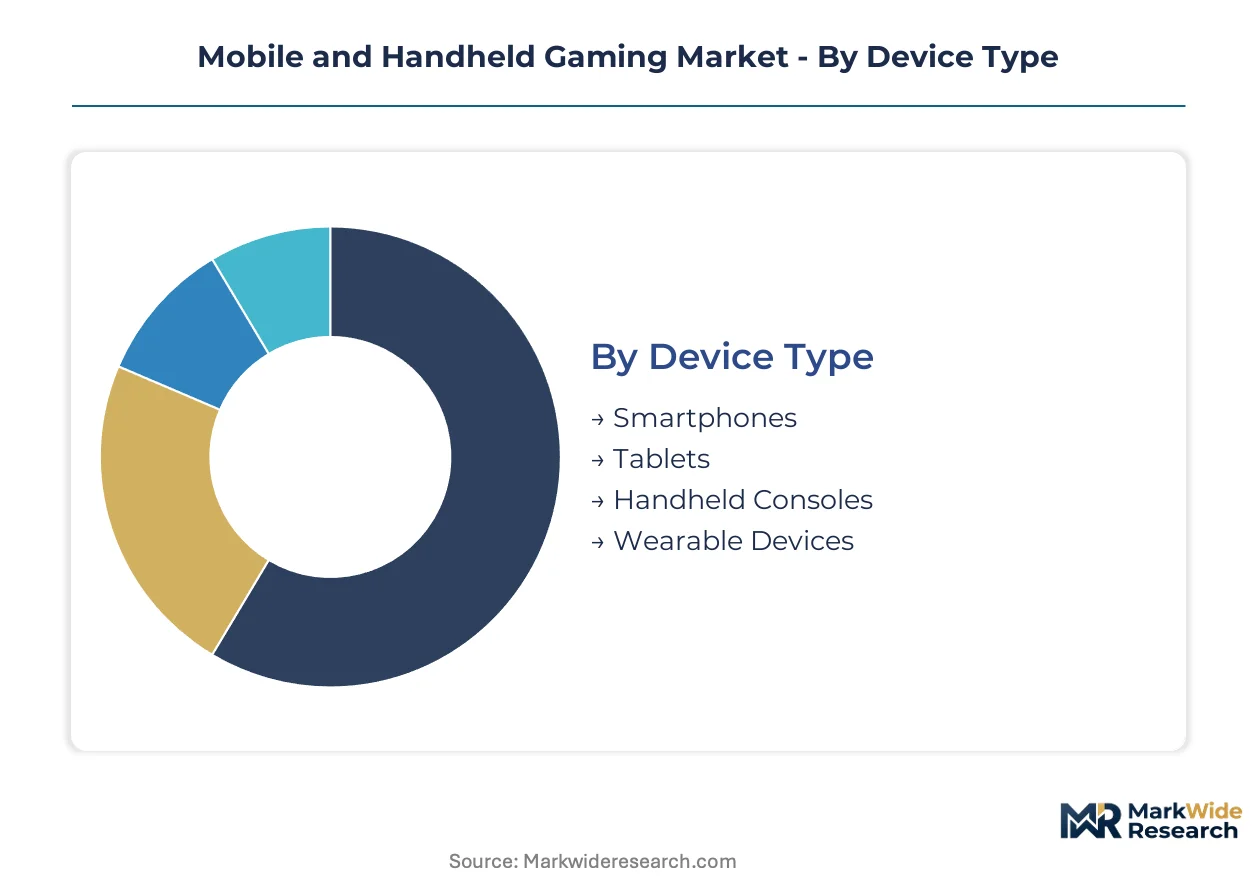
Device replacement cycles and upgrade patterns fragment the mobile and handheld gaming market across four distinct dimensions. Understanding these divisions clarifies where publishers allocate development resources and how platform holders prioritize hardware investment.
Device Type:
Upgrade cycles vary dramatically across portable hardware categories, with smartphone turnover every 2-3 years contrasting handheld console longevity spanning 5-7 year generations.
- Smartphones:ARM-based chipsets with Adreno and Mali GPU architectures deliver rendering performance that now matches prior-generation dedicated handhelds. Seoul, Tokyo, and Shanghai metropolitan clusters drive replacement demand as 5G infrastructure enables competitive multiplayer latency previously impossible on mobile networks.
- Handheld Consoles:Specialized control hardware with hall-effect joysticks and physical button arrays sustain premium margin pools through first-party software ecosystem lock-in. Supply concentrates in East Asian manufacturing clusters where Nintendo and Valve anchor component sourcing relationships.
- Tablets:Larger form-factor displays attract strategy and simulation genres requiring extended session engagement.
- Wearable Devices:Smartwatch and AR glass formats enable ultra-casual session loops under 90 seconds.
Smartphones sit at the top of the volume ranking, with handheld consoles climbing the fastest as cloud streaming reduces silicon dependency barriers.
Game Genre:
Genre preference maps directly to session-length flexibility and monetization architecture compatibility across commuter and residential use cases.
- Puzzle:Match-3 and logic mechanics dominate commuter session windows with sub-5-minute engagement loops. Data-driven user acquisition systems from Zynga and Scopely concentrate advertising spend here, making this the most contested genre for customer acquisition efficiency.
- Role-Playing:Gacha monetization and character collection systems generate the highest per-user revenue through live-service event programming. South Korean studios in Seoul anchor global live-ops talent pools for this genre.
- Action-Adventure:Cloud streaming enables premium visual fidelity previously restricted to fixed consoles.
- Sports:Annual release cycles align with real-world league calendars and licensing windows.
Puzzle titles command the largest installed base, while role-playing formats gain share fastest through recurring revenue expansion.
Monetization Model:
Revenue architecture selection determines publisher margin structure and regulatory exposure across divergent compliance jurisdictions.
- Freemium:Microtransaction systems with cosmetic and progression-based purchases generate dominant revenue share through whale-user subsidization. GDPR behavioral data frameworks and China's MIIT minor protection regulations now mandate probability disclosures that increase compliance engineering overhead.
- Subscription:Platform-holder bundles integrating cloud access with content libraries create recurring revenue distinct from transaction volatility. Apple Arcade and Google Play Pass expansion accelerates this segment's expansion trajectory.
- In-App Purchases:Item-based a la carte transactions persist in mid-core strategy formats.
- Paid Download:Upfront purchase models concentrate in premium indie and narrative-driven segments.
Freemium structures dominate current revenue, with subscription formats expanding most quickly as platform bundling scales.
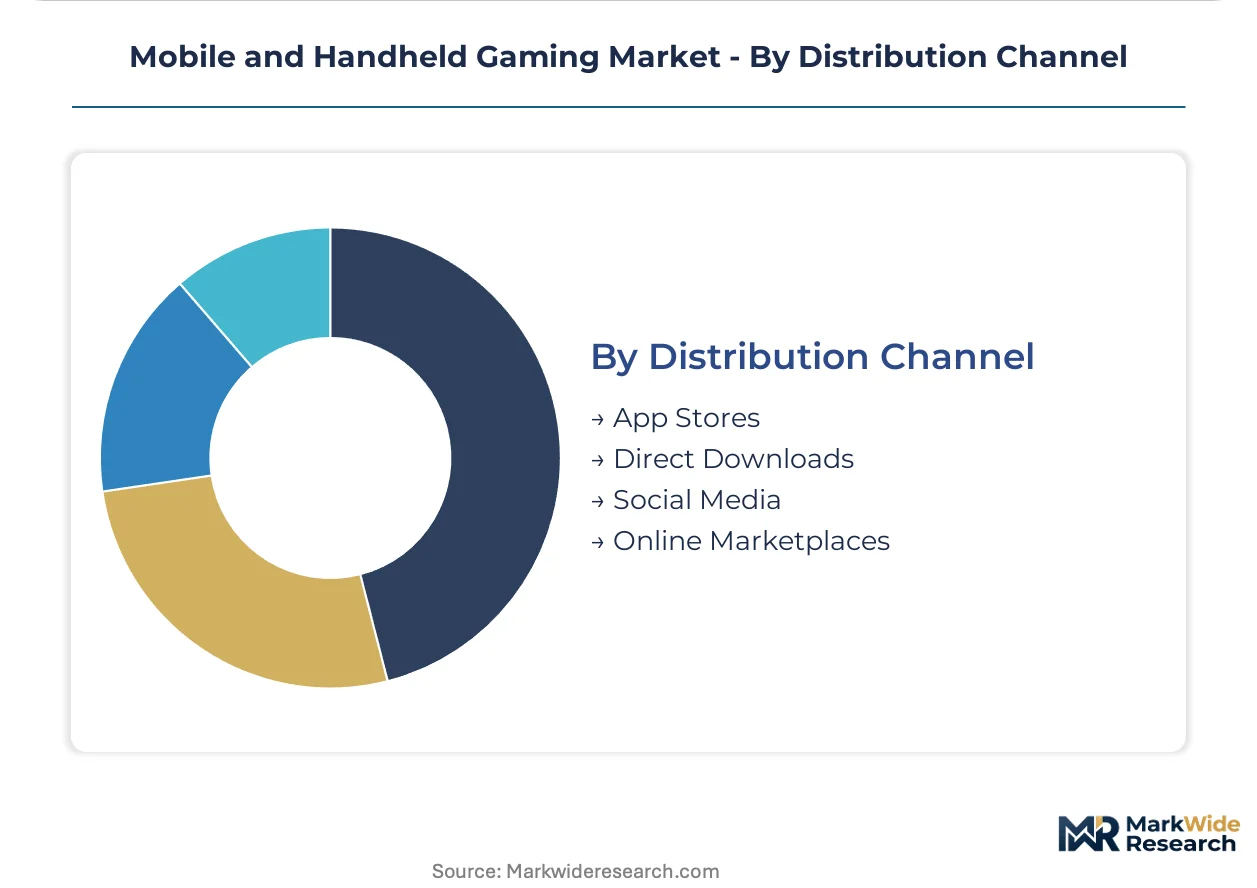
Distribution Channel:
Channel selection constrains margin recovery and user data ownership as regulatory pressure on storefront monopolies intensifies.
- App Stores:Apple and Google storefronts extract 15-30% transaction shares while controlling discovery algorithms and payment rails. EU Digital Markets Act enforcement and US state-level legislation pressure this exclusivity model.
- Direct Downloads:Sideloading and first-party launcher distribution enable margin recovery outside platform tax structures. Epic Games Store mobile expansion and Samsung Galaxy Store growth accelerate this channel's development.
- Social Media:TikTok and Instagram instant-play formats reduce friction for hyper-casual acquisition.
- Online Marketplaces:Amazon Appstore and regional alternatives fragment discovery in emerging markets.
App Stores retain volume leadership, with Direct Downloads gaining share fastest through regulatory-forced liberalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the densest concentration of live-service development talent and 5G infrastructure deployment. Cloud streaming adoption accelerates fastest in East Asian metropolitan clusters where sub-20ms latency enables competitive multiplayer formats. Regulatory fragmentation across data privacy and content approval regimes shapes publisher go-to-market sequencing.
United States
FCC net neutrality frameworks govern how publishers deploy targeted monetization and collect behavioral data across American user bases. California's CCPA supplements federal privacy standards with additional consent requirements for minor-directed content. Los Angeles and San Francisco Bay Area clusters concentrate mobile game development studios specializing in mid-core strategy and sports simulation formats.
China
NMPA content approval queues impose multi-month review timelines that fragment global release synchronization for publishers. MIIT minor protection regulations mandate strict session-limit mechanics and spending caps for domestic distribution. Shanghai and Beijing metropolitan areas host the largest concentration of gacha monetization specialists and cloud infrastructure deployment.
Japan
METI industrial policy promotes 5G infrastructure density that supports low-latency cloud gaming adoption in dense urban corridors. GRAC rating system requirements establish probability disclosure standards for loot box mechanics that influence regional product design. Tokyo anchors the world's most sophisticated live-ops programming talent pools for character collection and role-playing formats.
South Korea
Game Industry Promotion Act enforcement creates transparent compliance benchmarks for probability-based monetization systems. GRAC mandates real-time loot box disclosure standards that exceed regional counterparts. Seoul Capital Area developers pioneer session-format hybridization, averaging 4.2 discrete daily sessions across multiple genre formats.
India
TRAI spectrum allocation decisions shape 5G rollout velocity in Tier-2 and Tier-3 cities where sub-$200 device proliferation accelerates. BIS certification requirements for wireless equipment create hardware import compliance layers. Maharashtra and Karnataka states concentrate domestic publisher operations targeting vernacular-language casual puzzle acquisition.
Mobile and Handheld Gaming Market Competitive Landscape
Global majors compete with regional champions across monetization architecture and live-service execution capabilities. Market structure fragments into three tiers: platform-holding conglomerates with cloud infrastructure, specialized live-ops studios with regional talent concentration, and data-driven user acquisition specialists dominating casual genres. Strategic archetypes include subscription bundle integrators, gacha monetization specialists, and hyper-casual publishing networks. Competitive moves center on live-ops talent acquisition and cloud-native engine licensing.
Within the live-service specialist tier, Scopely and Zynga exemplify divergent monetization approaches while Electronic Arts anchors premium visual fidelity optimization for mobile chipsets. Scopely occupies a position emphasizing recurring revenue architecture across portfolio titles. Zynga sits within data-driven user acquisition systems that dominate casual puzzle marketplaces. Electronic Arts represents engine-level optimization capabilities that sustain mid-tier smartphone performance. King and Playrix exemplify European-based specialists in match-3 mechanics with global distribution reach.
| Leading Market Players |
|---|
| Riot Games |
| Zynga |
| Scopely |
| DoubleDown Interactive |
| King |
| Take-Two Interactive |
| Activision Blizzard |
| Playrix |
| Electronic Arts |
| Others |
Value Network & Pricing Analysis
ARM chipset fabrication costs cascade through three pricing tiers as Taiwan-based foundry capacity constraints elevate silicon premiums for mid-tier smartphone GPU architectures essential to cloud-streaming quality thresholds.
Pricing Analysis
Input-cost pass-through from semiconductor fabrication elevates device acquisition costs across premium, standard, and economy tiers. Price differentiation hinges on GPU performance grade and 5G modem certification tier, with Seoul and Tokyo metropolitan buyers showing lowest sensitivity due to infrastructure density. Pricing pressure stems from Apple and Google store fee extraction compressing developer margins. Casual puzzle gamers in India and Southeast Asia exhibit highest price sensitivity, driving demand for sub-$200 5G devices.
Supply Chain Analysis
Logistics and freight costs for specialized control hardware concentrate supply chain vulnerability in East Asian manufacturing clusters. Component sourcing draws from Taiwan for ARM chipsets, South Korea for OLED displays, and China for battery assemblies. Raw material dependencies span lithium-ion cells, rare-earth magnets for haptics, and high-grade aluminum enclosures. Single-source vulnerability around Taiwan-based foundry concentration threatens GPU supply continuity. Distribution runs through platform-holder app stores and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile and handheld gaming market functions as a stable compounder where cloud streaming infrastructure expansion drives steady recurring revenue growth across subscription and live-service formats.
For Market Incumbents: To counter cloud-native engine displacement of proprietary middleware, Electronic Arts and Scopely should deepen backward integration into server-side rendering technology while expanding live-ops talent acquisition in Seoul and Tokyo. Platform holders must defend channel control against EU Digital Markets Act enforcement by accelerating first-party launcher development. For New Entrants and Emerging Players: EU Digital Markets Act enforcement in Europe opens a window for direct-to-consumer distribution margin recovery outside Apple and Google tax structures. Target India's Tier-2 and Tier-3 cities through vernacular-language casual puzzle formats. Pursue sideloading partnerships with Samsung Galaxy Store and Epic Games Store mobile as primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where live-ops talent scarcity concentrates in East Asian studios against fragmented Western publisher capabilities. Long-term viability favors subscription bundle integrators with cloud infrastructure assets over transaction-dependent freemium specialists. Target acquisition archetype: mid-core strategy studios with established gacha monetization systems. Watch 5G infrastructure deployment velocity in Indian metropolitan clusters as inflection indicator for emerging market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Engine Licensing | Server-side rendering partnerships with hyperscalers reduce silicon dependency for premium visual fidelity. |
| Live-Ops Talent Acquisition | Seoul and Tokyo studio recruitment anchors recurring revenue execution for character collection formats. |
| Direct-to-Consumer Distribution | Sideloading policy liberalization enables margin recovery outside Apple and Google storefront tax structures. |
| Subscription Bundle Integration | Platform holders combining cloud access with content libraries create recurring revenue distinct from freemium volatility. |
| 5G Infrastructure Partnership | Carrier alliances in Seoul, Tokyo, and Shanghai secure sub-20ms latency thresholds for competitive multiplayer formats. |
Research Methodology
Coverage spans East Asia, North America, Europe, and South Asia, with primary inputs from each region combining structured interviews with live-ops directors, platform engineering leads, regulatory affairs specialists, and monetization architects. Secondary validation draws from NMPA filing databases, GRAC rating disclosures, App Annie engagement metrics, and hyperscaler capex reports. Bottom-up title-level revenue modeling triangulates against top-down platform-holder revenue disclosures.
Granularity-level modeling disaggregates volume and value across device type, game genre, monetization model, and distribution channel dimensions throughout the forecast period. CAGRs derive from installed base penetration curves adjusted for replacement cycle acceleration. Cloud streaming adoption rates and 5G infrastructure deployment timelines serve as primary demand-side forecast inputs alongside regulatory approval queue lengths for China distribution.
Revisions become necessary when NMPA content approval timelines extend beyond historical baselines or when Taiwan-based foundry concentration triggers supply disruption. Forecasts reflect assumptions about platform fee structures and sideloading policy trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
South Korea Gaming Peripherals Market
Gaming
Latin America Gaming Headsets Market
Gaming
Germany Gaming Headset Market
Gaming
Shooter Game Market
Gaming
Arcade Cabinet Market
Gaming
LAMEA Gaming Posters Market
Gaming
China Subscription-Based Gaming Market
Gaming
Mobile Game Software Market
Gaming
Puzzle Video Game Market
Gaming
Australia Gaming Accessories Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
Global Gaming Headset Market
Gaming
Flat Gaming Monitors Market
Gaming
Videogames Market
Gaming
Mobile Shooter Market
Gaming
Global NFT Gaming Market