
 United States Gaming Market | 2026-2036
United States Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gaming Market Outlook
The Children's Online Privacy Protection Act enforcement is hardening, pushing platforms toward verifiable parental consent systems and transparent data practices. Microsoft Corporation leverages its Azure cloud backbone to sustain cross-platform streaming infrastructure. Sony Interactive Entertainment LLC anchors premium console exclusivity through captive studio networks. Epic Games Inc. competes on storefront commission rates and developer revenue splits.
United States Gaming comprises interactive software and hardware systems enabling real-time player engagement across dedicated consoles, personal computers, mobile devices, and remote-streamed servers. Core technical specifications include sub-50 millisecond latency thresholds for competitive multiplayer, 4K/120Hz rendering pipelines, and procedural content generation algorithms. The mobile platform category leads by user volume but carries thinner monetization yields per player. Freemium and in-app purchase models dominate revenue generation, while subscription services concentrate high-engagement users into predictable recurring revenue pools. Console and PC segments retain premium pricing power through hardware-software bundling and exclusive intellectual property control.
The Federal Trade Commission, Entertainment Software Rating Board, and state-level attorneys general shape compliance burdens around microtransaction transparency, age-gating, and deceptive marketing claims. The FTC's ongoing rulemaking on click-to-cancel subscription mechanics directly impacts recurring revenue architecture across platforms. Stakeholders must monitor emerging state legislation on digital asset ownership and transferable virtual goods, as patchwork regulation threatens unified national service design.
Market Dynamics
The FTC's click-to-cancel rulemaking is compressing subscription revenue architecture while cloud infrastructure concentration in Northern Virginia and Oregon data centers creates latency arbitrage opportunities for edge computing deployments.
Growth Catalysts
- Generative AI Integration:Procedural content generation algorithms reduce development cycles for open-world environments. Mid-tier studios adopt NVIDIA's neural rendering pipelines to compete with AAA production values.
- California Cluster Density:San Francisco Bay Area and Los Angeles corridor concentrate venture capital, streaming infrastructure, and captive talent pools. Geographic proximity accelerates cross-platform engine development.
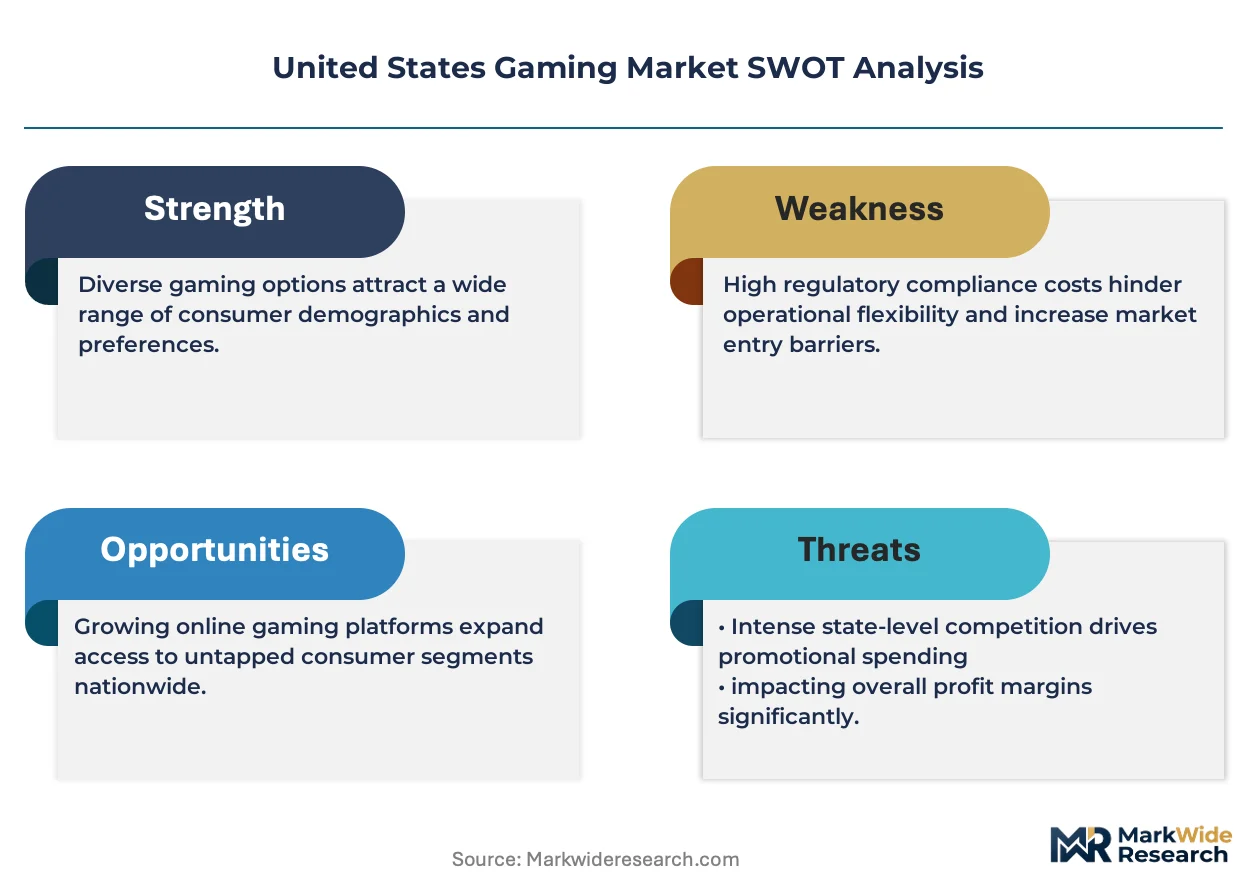
- FTC Disclosure Mandates:Transparent loot box probability requirements build consumer trust frameworks. Compliant platforms capture wallet share from non-compliant offshore competitors.
Market Restraints
- Silicon Supply Concentration:Advanced GPU fabrication depends on TSMC's Taiwan facilities and Samsung's Pyeongtaek foundries. Geopolitical friction threatens hardware-software bundling economics.
- Latency Physics:Sub-50 millisecond competitive multiplayer thresholds require fiber backhaul density unavailable in Mountain West and Great Plains states. Rural player bases remain underserved.
- State-Level Patchwork:Emerging legislation on transferable virtual goods in Utah and Illinois creates compliance fragmentation. National service design faces conflicting digital asset ownership definitions.
Strategic Opportunities
- Texas Infrastructure Expansion:Austin and Dallas-Fort Worth metros offer tax incentives and lower operational costs for data center buildouts. Secondary talent markets reduce California compensation inflation.
- Cross-Reality Convergence:Mixed reality headsets and haptic peripherals merge mobile and console engagement patterns. Hardware-agnostic middleware layers capture platform-agnostic development spend.
- Parental Consent Automation:COPPA-compliant verification APIs create B2B licensing revenue streams. Third-party age-gating services monetize regulatory complexity for smaller publishers.
Industry Challenges
- Live Operations Talent Scarcity:Games-as-a-service model demands data science and behavioral economics expertise. Traditional narrative design pipelines fail to retain high-engagement player cohorts.
- Antitrust Scrutiny:Exclusive IP control and storefront commission disputes trigger state attorney general investigations. Vertical integration strategies face pre-emptive regulatory challenge.
- Legacy Engine Migration:Proprietary toolchains from the 2010s lack cloud-native multiplayer scaling. Technical debt impedes real-time service architecture adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gaming Market |
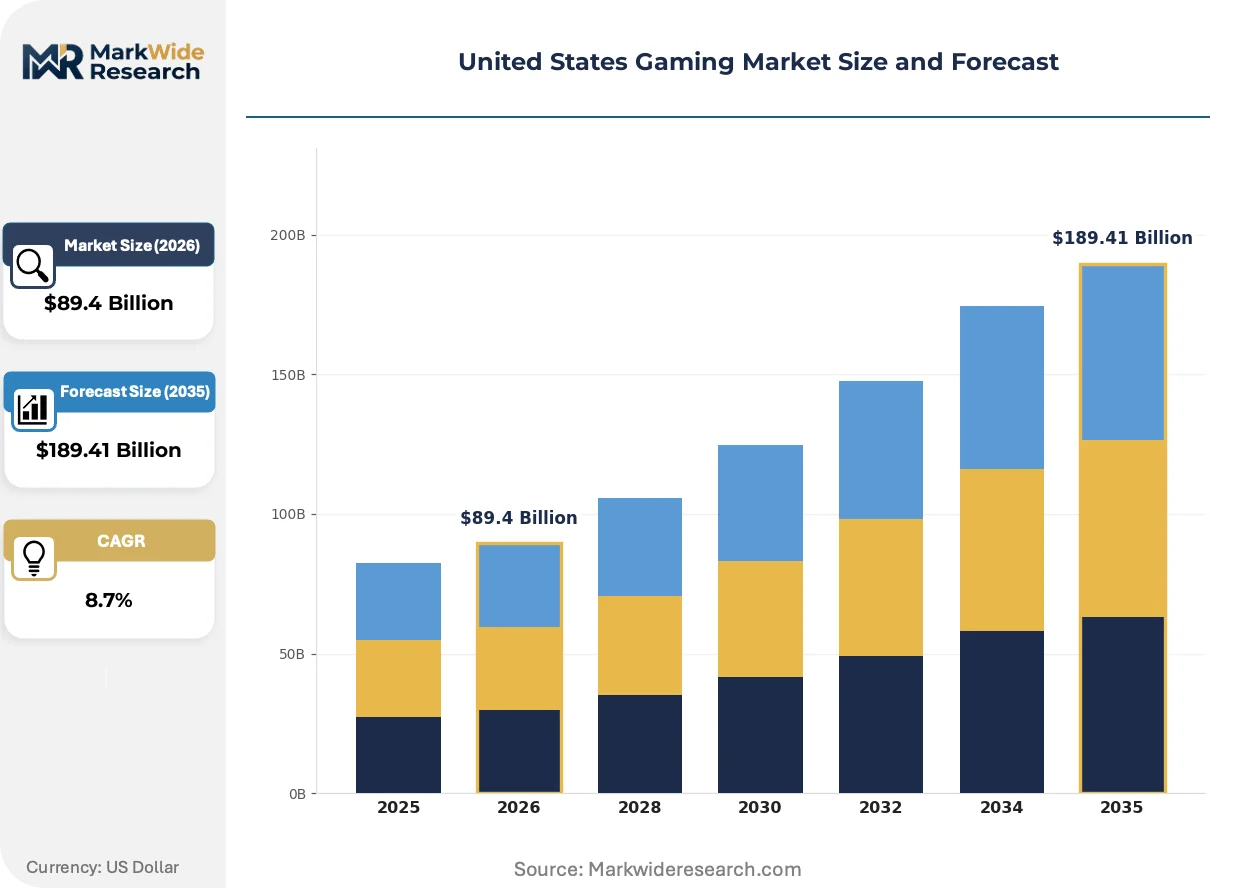
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $189.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Console, PC, Mobile, Cloud Gaming Game Genre: Action, Adventure, Sports, Puzzle Monetization Model: Freemium, Subscription, Pay-to-Play, In-App Purchases Player Demographics: Teens, Young Adults, Adults, Seniors |
| Companies Covered | Microsoft Corporation, Sony Interactive Entertainment LLC, Electronic Arts Inc., Take-Two Interactive Software Inc., Activision Blizzard Inc., Epic Games Inc., Roblox Corporation, Valve Corporation, Riot Games Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gaming Market Strategic Shifts
Real-time streaming infrastructure and AI-assisted production tools are compressing development timelines while fragmenting distribution control away from platform gatekeepers toward direct-to-consumer channels.
Neural inference accelerators embedded in consumer GPUs are electrifying dynamic NPC behavior and real-time voice synthesis. Indie studios with limited animation budgets deploy these tools to match AAA narrative immersion. The technology is electrifying competitive positioning for mid-market publishers previously constrained by asset production costs.
The FTC's evolving rulemaking on subscription cancellation mechanics imposes friction-reduction mandates on recurring revenue architecture. Platforms must implement one-click termination flows that compress customer lifetime value calculations. Mobile and PC subscription services face the steepest compliance redesign timelines.
Young adult demographics are migrating discovery and purchase behavior toward creator-led channels on TikTok and Twitch, bypassing traditional storefront algorithms. Influencer-driven wishlist velocity now determines indie title visibility more than platform curation. This shift concentrates marketing spend in Southern California and New York City creator economy hubs.
United States Gaming Market Segmentation
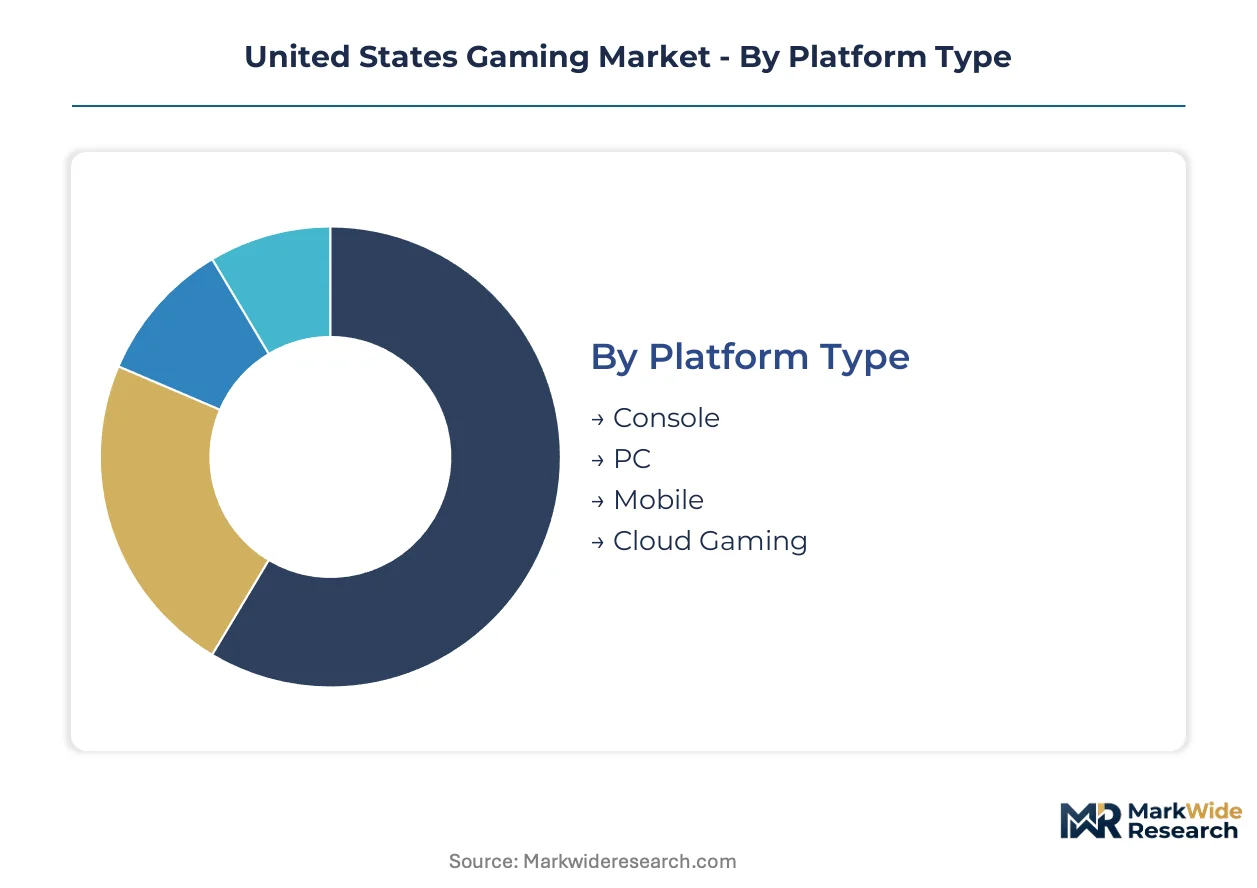
Platform architecture and monetization mechanics fragment the United States gaming landscape into distinct operational ecosystems. Each segment demands specialized compliance frameworks, infrastructure investments, and talent acquisition strategies that reshape competitive positioning.
Platform Type:
Hardware ownership patterns and connectivity requirements differentiate player investment levels and lifetime value calculations across platform ecosystems.
- Console:Dedicated hardware-software bundling sustains premium pricing power through exclusive intellectual property control. Sony Interactive Entertainment and Microsoft anchor demand in California's Los Angeles corridor and Washington state's Redmond cluster, leveraging captive studio networks to defend market position.
- PC:Open architecture enables modular upgrade cycles and storefront competition outside platform gatekeepers. Steam and Epic Games Store commission disputes concentrate developer attention in Texas and Washington state, where engine licensing and distribution infrastructure density accelerates.
- Mobile:Ubiquitous device penetration drives volume leadership with thinner per-player monetization yields.
- Cloud Gaming:Remote-streamed server architectures eliminate hardware barriers while demanding sub-50 millisecond latency thresholds.
Mobile leads volumes today; cloud gaming is gaining share fastest.
Game Genre:
Engagement duration and content production economics separate genres by development budget requirements and live operations intensity.
- Action:High-fidelity combat systems and multiplayer infrastructure dominate development resource allocation. California's San Francisco Bay Area studios concentrate talent for competitive shooter and battle royale formats, where real-time service architecture demands data science expertise.
- Adventure:Narrative-driven open worlds leverage procedural content generation to compress production timelines. NVIDIA's neural rendering pipelines enable mid-tier studios in Austin and Raleigh to match AAA environmental density.
- Sports:Annual release cycles and licensed intellectual property create predictable revenue streams with limited innovation differentiation.
- Puzzle:Lower asset requirements attract indie developers with compressed development timelines and mobile-first distribution.
Action commands the largest development spend; adventure titles are expanding most quickly.
Monetization Model:
Revenue predictability and regulatory exposure distinguish models by FTC compliance burden and customer lifetime value stability.
- Freemium:Zero-entry pricing maximizes user acquisition while in-app purchase mechanics drive conversion. The FTC's evolving scrutiny of loot box disclosures and click-to-cancel rulemaking reshapes California and New York-based platform compliance investments.
- Subscription:Recurring revenue pools concentrate high-engagement users into predictable income streams. Microsoft's Game Pass and Sony's PlayStation Plus anchor demand through exclusive content windows, though FTC friction-reduction mandates compress customer lifetime value calculations.
- Pay-to-Play:Upfront purchase models retain premium positioning for narrative-driven single-player experiences.
- In-App Purchases:Microtransaction architectures dominate mobile monetization with thinner margins per transaction.
Freemium leads user volumes; subscription models are climbing the fastest.
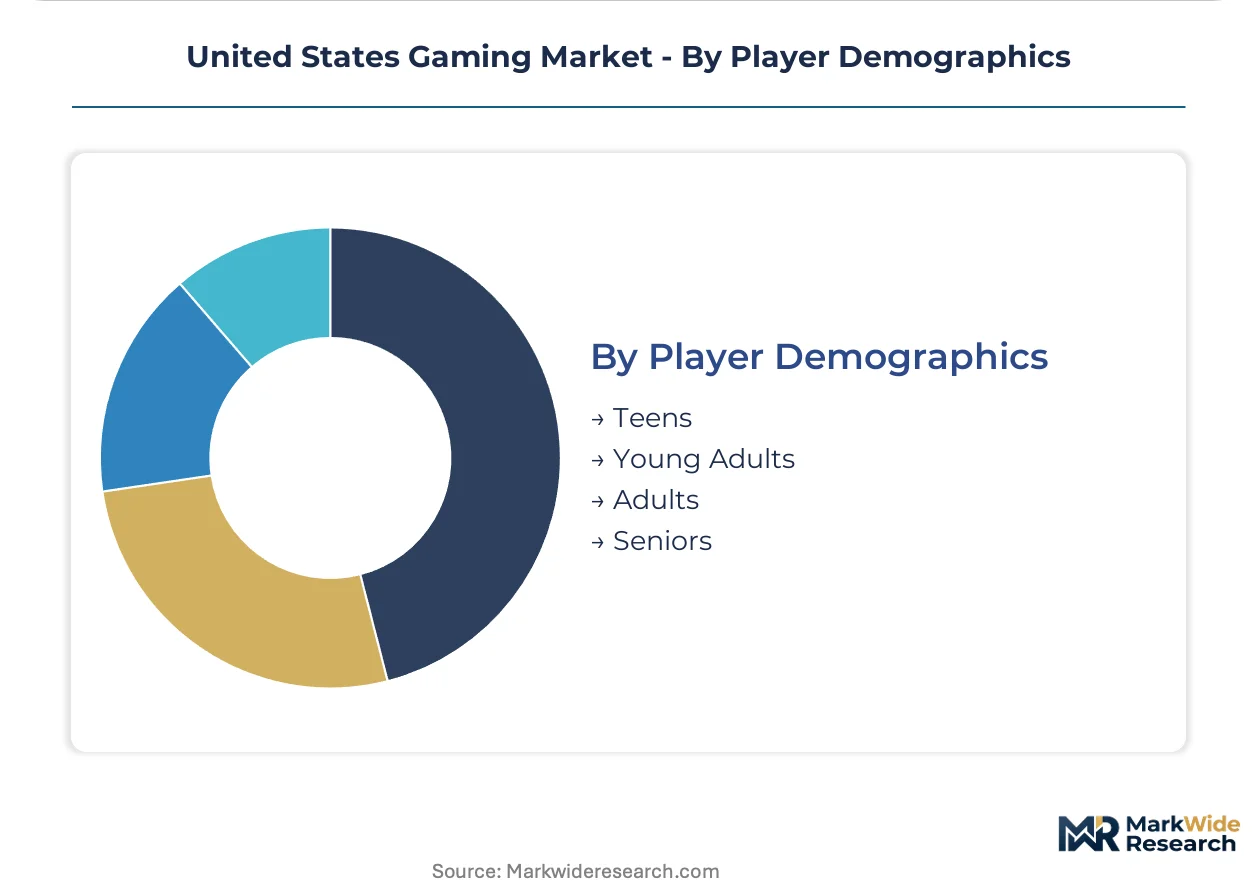
Player Demographics:
Disposable income levels and platform preference maturity shape monetization yield and content rating requirements.
- Young Adults:Peak gaming expenditure coincides with streaming discovery migration toward TikTok and Twitch creator channels. Southern California and New York City influencer economy hubs concentrate marketing spend for this cohort, bypassing traditional storefront algorithms.
- Adults:Established platform loyalty and subscription stacking sustain premium service adoption. Texas and Florida metropolitan areas concentrate this demographic for PC and console hardware-software bundling.
- Teens:COPPA enforcement hardens compliance requirements around verifiable parental consent systems.
- Seniors:Casual puzzle and mobile formats attract emerging participation with lower complexity barriers.
Young adults lead engagement intensity; adults sustain the highest monetization yields.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States gaming industry traces its commercial origins to California's Silicon Valley garage startups and Massachusetts Route 128 minicomputer labs during the 1970s semiconductor revolution.
California
San Francisco Bay Area and Los Angeles corridor concentrate venture capital deployment and streaming infrastructure density. The California Consumer Privacy Act enforcement hardens data practice requirements for platforms serving young adult demographics. Santa Monica and Irvine studio clusters anchor exclusive intellectual property development through captive talent pools.
Washington State
Redmond and Seattle metropolitan areas sustain cloud infrastructure engineering and console hardware-software bundling operations. Washington's state-level privacy legislation complements federal COPPA frameworks for parental consent verification. Kirkland-based server farms power cross-platform multiplayer latency thresholds.
Texas
Austin and Dallas-Fort Worth metros attract data center buildouts through tax incentive programs and lower operational costs relative to coastal markets. The Texas Data Privacy and Security Act imposes transparency requirements on biometric data collection in gaming peripherals. Round Rock and Plano technology corridors expand secondary talent markets beyond California compensation inflation.
New York
New York City and Albany corridor concentrate influencer economy marketing spend for creator-led discovery channels. The Stop Addictive Feeds Exploitation for Kids Act proposes algorithmic recommendation restrictions for minor-aged users. Brooklyn and Manhattan media production clusters service TikTok and Twitch content velocity requirements.
United States Gaming Market Competitive Environment
Premium-margin players sit above commodity-margin players across exclusive intellectual property control and subscription service bundling. The United States gaming market structures around three tiers: platform gatekeepers with captive cloud infrastructure, mid-tier publishers licensing third-party engines, and indie studios leveraging generative AI production tools. Dominant competitive moves include exclusive content windowing for subscription retention and strategic studio acquisitions to secure development talent pipelines.
Within the platform gatekeeper tier, Microsoft Corporation and Sony Interactive Entertainment LLC exemplify infrastructure-integrated competitive positioning. Epic Games Inc. occupies a distinct position between storefront commission competition and engine licensing standardization. These three entities represent divergent strategic archetypes: cloud-backbone vertical integration, hardware-software bundling exclusivity, and developer revenue split disruption.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Sony Interactive Entertainment LLC |
| Electronic Arts Inc. |
| Take-Two Interactive Software Inc. |
| Activision Blizzard Inc. |
| Epic Games Inc. |
| Roblox Corporation |
| Valve Corporation |
| Riot Games Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive studio networks and exclusive intellectual property control anchor both supply positioning and pricing power across the United States gaming market. Hardware-software bundling economics sustain premium tier margins while cloud infrastructure concentration in Northern Virginia and Oregon data centers shapes downstream cost structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments player willingness-to-pay by hardware investment and content exclusivity. Price differentiation hinges on exclusive IP windows and subscription bundling depth. Cost compression in the freemium mobile tier intensifies because of FTC disclosure mandate compliance investments. Young adult demographics on mobile platforms exhibit highest price sensitivity; adults stacking console and PC subscriptions show lowest elasticity.
Supply Chain Analysis
Domestic-content mandates around data sovereignty and COPPA-compliant server architecture reshape sourcing toward US-based cloud infrastructure. Advanced GPU fabrication draws from Taiwan, South Korea, and domestic Intel foundry investments. Supply chain risk centers on single-source vulnerability at TSMC's Taiwan facilities for neural rendering accelerators. Distribution runs through direct-to-consumer storefronts, bypassing traditional retail channel markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States gaming market reads as a late-cycle quality story. Demand is consolidating toward premium subscription tiers with exclusive content windows and sub-50 millisecond latency guarantees.
For Market Incumbents: Deploy exclusive IP windowing to lock high-engagement cohorts into recurring revenue pools. Deepen backward integration into cloud infrastructure through edge computing deployments in Texas and Washington state. Consolidation of live operations talent in California's San Francisco Bay Area defends against emerging generative AI-enabled mid-tier competitors. For New Entrants and Emerging Players: Launch via creator-led discovery channels on TikTok and Twitch to bypass platform gatekeeper algorithms. Target underserved rural player bases in Mountain West and Great Plains states where fiber backhaul density gaps persist. White-space exists in COPPA-compliant parental consent automation APIs for smaller publishers. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier studios with proprietary procedural content generation pipelines because generative AI is compressing AAA production value gaps. Long-term viability favors targets with cloud-native multiplayer architecture and established live operations expertise. Watch FTC rulemaking velocity on click-to-cancel mechanics as subscription revenue compression signal.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Content Windowing | Sony Interactive Entertainment and Microsoft anchor subscriber retention through captive studio IP control. |
| Edge Computing Infrastructure Expansion | Texas tax incentives attract data center buildouts reducing latency for underserved Mountain West player bases. |
| Generative AI Production Integration | NVIDIA's neural rendering pipelines enable mid-tier Austin studios to match AAA environmental density. |
| COPPA Compliance API Licensing | Third-party age-gating services monetize regulatory complexity for mobile publishers in New York and California. |
| Cross-Platform Engine Standardization | Epic Games Store commission competition concentrates developer attention in Washington and Texas corridors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged game development executives, platform engineering leads, live operations directors, and FTC regulatory affairs specialists. Secondary validation drew from SEC 10-K filings, Entertainment Software Rating Board disclosure databases, App Annie mobile monetization metrics, and hyperscaler capex disclosures. Bottom-up title-level revenue modeling and top-down platform aggregate tracking triangulated market sizing.
Comparable-period anchoring calibrated the projection horizon against historical console cycle transitions and cloud infrastructure deployment waves. Segmentation dimensions spanned platform type, monetization model, player demographic cohort, and regional data center density. CAGRs derived from trend extrapolation of subscription attach rates and in-app purchase conversion curves. Forecast inputs incorporated FTC rulemaking timelines and TSMC fab capacity allocation patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical friction scenarios affecting Taiwan semiconductor supply. Model assumptions reflect current regulatory trajectories around loot box transparency and click-to-cancel mechanics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Gaming Chair Market
Gaming
Global Game Testing Service Market
Gaming
Gaming Accessories Market
Gaming
FPS Game Market
Gaming
Gaming Peripheral Market
Gaming
VR Gaming Accessories Market
Gaming
Gaming Simulator Market
Gaming
North America in-Game Advertising Market
Gaming
Russia in-Game Advertising Market
Gaming
Advanced Digital Gaming Market
Gaming
Europe Casino Gambling Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Game Engine Management Market
Gaming
Gaming Controller Market
Gaming
Global Online Gambling and Betting Market
Gaming
RPG Games Market