
 North America Gaming Hardware and Accessories Market | 2026-2036
North America Gaming Hardware and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gaming Hardware and Accessories Market Insights
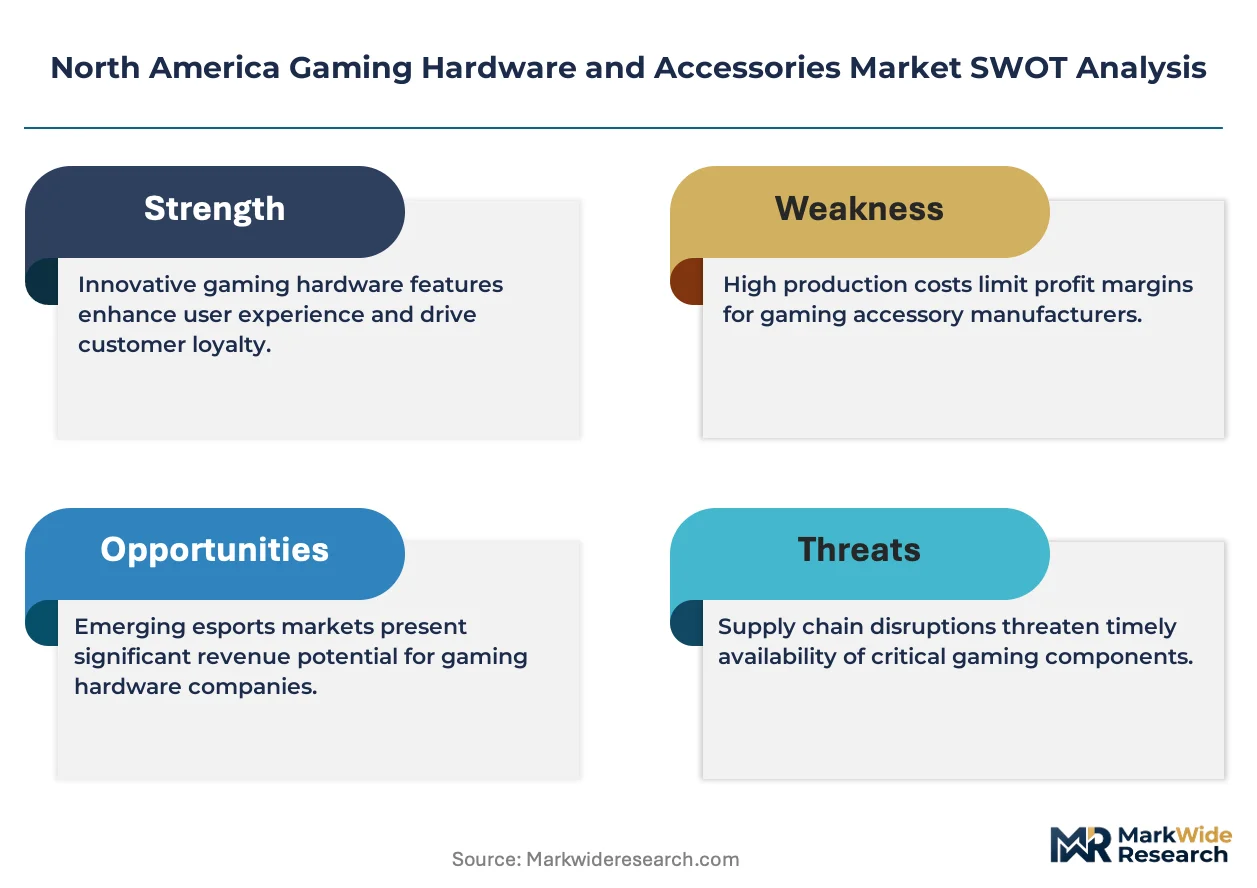
FCC Part 15 certification for unintentional radiators is rotating supplier eligibility, forcing smaller peripheral makers to redesign RF shielding or exit the North American channel. NVIDIA Corporation leverages its CUDA ecosystem to dominate discrete GPU supply for enthusiast PC builds. Razer Inc. anchors its position through deep specialization in esports-grade peripherals with sub-1ms polling rates. Corsair Gaming Inc. sustains component loyalty via integrated iCUE software control across memory, cooling, and input devices.
Gaming hardware and accessories comprise the physical computing and interface equipment purpose-built for interactive entertainment, spanning custom silicon with ray-tracing cores, mechanical switch actuation points between 1.2-4.0mm, and haptic feedback systems with sub-20ms latency budgets engineered for competitive response fidelity. PC Components command the dominant value pool as GPU and CPU upgrades cycle faster than console generations, while VR Headsets represent the fastest-expanding product type as pancake lens optics and eye-tracked foveated rendering reduce hardware costs. The Premium price tier captures disproportionate margin as streamers and professional gamers prioritize zero-latency specifications over budget alternatives.
The FCC governs wireless transmission protocols for controllers and headsets, while EPA energy efficiency standards shape console standby power budgets and California's Title 20 appliance regulations extend to gaming system power draw. These frameworks elevate compliance costs for entrants but protect incumbents with established testing infrastructure. Stakeholders must monitor how NHTSA distracted-driving precedents could extend to haptic VR peripherals and whether Health Canada aligns with FDA guidance on extended VR session duration warnings.
Market Dynamics
GPU supply concentration among foundry partners in Taiwan and Korea is reshaping inventory cycles for North American system builders, compressing lead times during peak demand windows while amplifying vulnerability to single-node disruptions.
Growth Catalysts
- Esports tournament formalization:Competitive gaming leagues in California and Texas now mandate standardized peripheral specifications, creating pull-through demand for certified low-latency controllers and headsets.
- FCC Part 15 Subpart C:Unlicensed 2.4 GHz and 5 GHz spectrum access for wireless peripherals eliminates licensing friction, accelerating controller and headset adoption across console and PC platforms.
- Cloud gaming infrastructure buildout:Microsoft Azure and Amazon Web Services edge nodes in Virginia and Oregon reduce input lag thresholds, expanding addressable hardware markets to thin-client endpoints.
Market Restraints
- Advanced packaging substrate scarcity:ABF substrate lead times from Japanese suppliers extend GPU and CPU delivery schedules, constraining North American retail channel fill rates.
- FCC equipment authorization costs:RF testing laboratory fees and SAR measurement requirements for wireless headsets exceed $50,000 per SKU, filtering smaller peripheral entrants from the US market.
- Mobile gaming substitution:Snapdragon-powered smartphones with attachable controllers capture casual gaming sessions, reducing attach rates for dedicated handheld consoles in price-sensitive segments.
Strategic Opportunities
- Canadian esports venue buildout:Toronto and Vancouver tournament halls lack purpose-built spectator infrastructure, creating first-mover advantage for seating and broadcast hardware specialists.
- Eye-tracked foveated rendering convergence:Integration of Tobii and pupil-tracking silicon with pancake lens optics halves GPU rendering loads, enabling standalone VR headsets at console price points.
- California Title 20 standby power mandates:Sub-0.5-watt console idle requirements favor power-supply redesign contracts for efficiency-optimized component vendors.
Industry Challenges
- RF shielding engineering talent scarcity:FCC Part 15 Class B unintentional radiator compliance requires specialized electromagnetic simulation expertise concentrated in Austin and Boston metro areas.
- PCIe 5.0 signal integrity validation:High-speed motherboard trace routing demands capital-intensive TDR and VNA equipment, elevating R&D fixed costs for mid-tier component vendors.
- Health Canada VR session duration guidance alignment:Divergent pediatric usage warning standards from FDA recommendations complicate North American packaging and firmware localization workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gaming Hardware and Accessories Market |
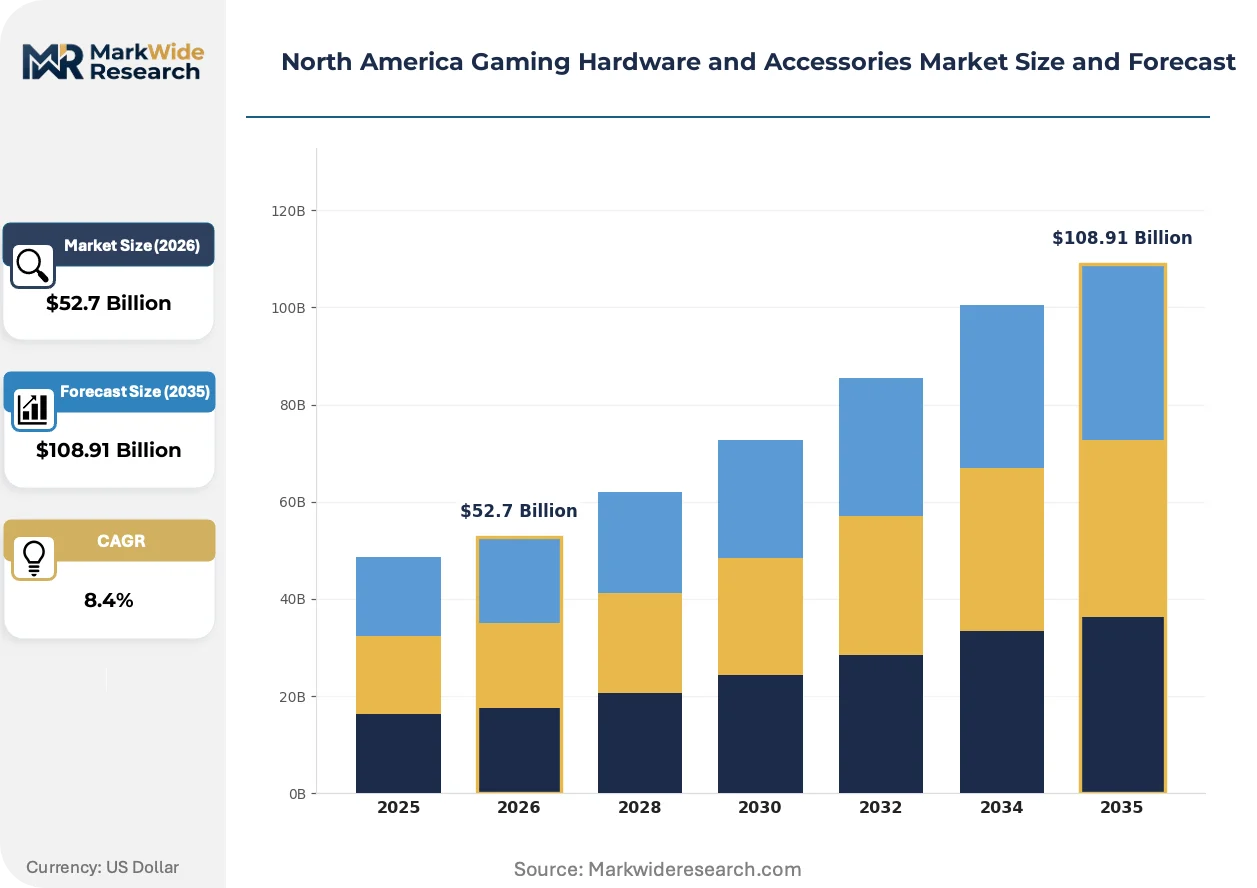
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consoles, PC Components, Gaming Mice, VR Headsets End User: Casual Gamers, Professional Gamers, Streamers, PC Builders Distribution Channel: Online Retail, Electronics Stores, Specialty Shops, Wholesale Price Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | Logitech International S.A., Razer Inc., Corsair Gaming Inc., NVIDIA Corporation, Microsoft Corporation, Sony Interactive Entertainment, Alienware (Dell Technologies Inc.), HyperX (HP Inc.), Turtle Beach Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gaming Hardware and Accessories Market Trends and Innovations
Silicon specialization and optical stack miniaturization are compressing form factors while elevating thermal and signal integrity constraints across the hardware stack. These forces are redrawing competitive boundaries between integrated system vendors and modular component suppliers.
Pancake lens optics is decomposing the traditional bulky VR headset architecture by folding optical paths through polarization-preserving films. Meta and Sony have adopted this stack for their 2024 flagship releases, shrinking headset depth by 40 percent while maintaining field-of-view specifications. This compression is decomposing the premium tethered VR segment into standalone wireless units, collapsing the external sensor and PC-link cable accessory markets.
EPA Energy Star Version 8.0 standby power requirements are tightening console idle consumption limits to sub-0.5-watt thresholds. Microsoft's Xbox Series X redesign and Sony's PlayStation 5 hardware revision both incorporate GaN power supplies to meet these specifications. The compliance burden falls heaviest on power-supply subsystem vendors without established 80 Plus Titanium certification pipelines, forcing partnership pivots toward tier-one ODMs.
Content creator procurement patterns are fragmenting across direct-to-consumer brand storefronts and Amazon influencer affiliate channels. Streamers in Los Angeles and Austin now source peripherals through creator-specific discount codes rather than traditional retail, compressing distributor margins while elevating manufacturer customer acquisition costs. This shift is most visible in mechanical keyboard and microphone categories, where audience-driven purchase intent outpaces specification-based comparison shopping.
North America Gaming Hardware and Accessories Market Segmentation
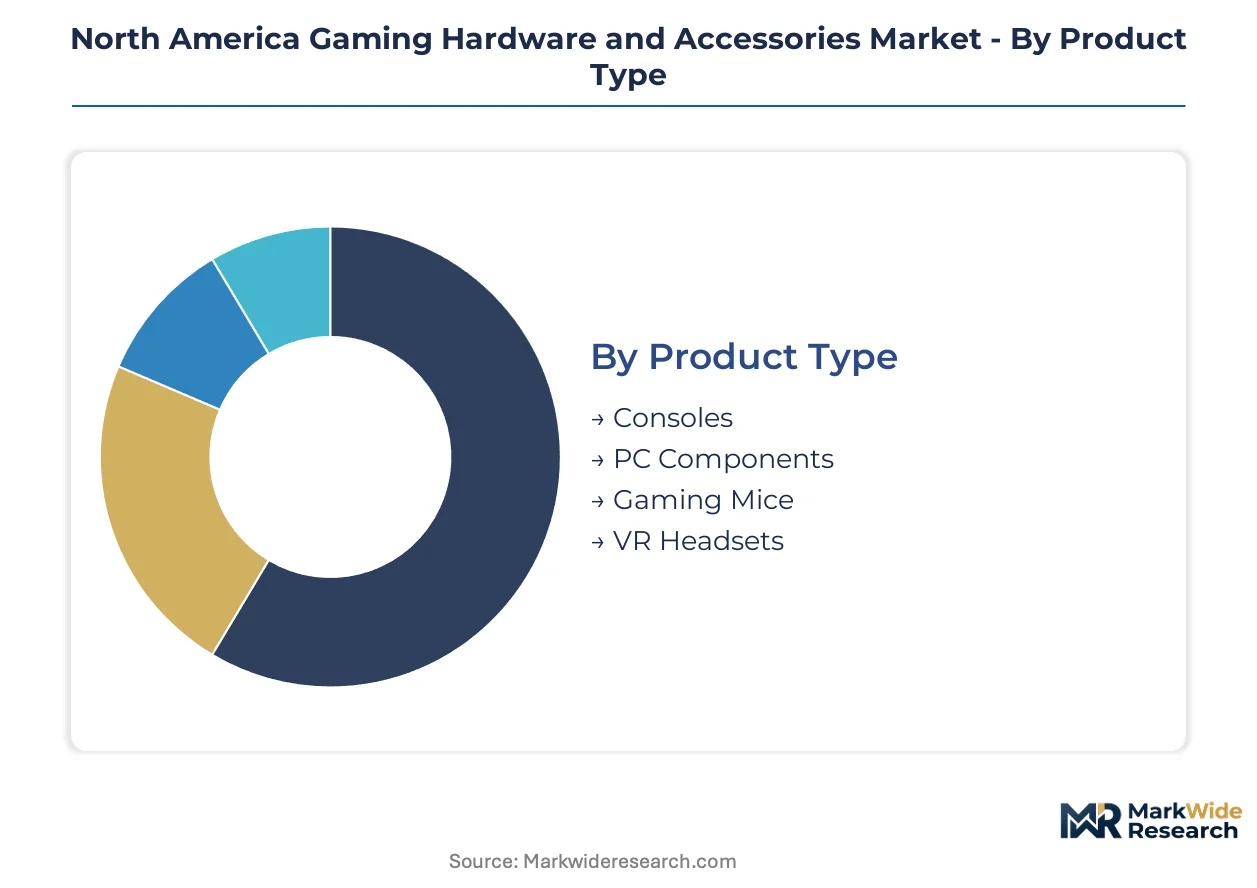
Segmentation in North American gaming hardware reveals how substitution pressures and purchasing contexts fragment demand across technical specifications, use cases, and channel preferences. Each dimension exposes distinct margin structures and regulatory exposure that shape supplier positioning strategies.
Product Type:
Mobile gaming peripherals and cloud streaming endpoints exert the strongest substitution pressure on dedicated hardware categories, forcing incumbent segments to defend through latency differentiation and ecosystem lock-in.
- Consoles:Closed-system entertainment hardware integrating custom AMD silicon with unified memory architectures. Demand clusters in suburban Texas and Florida households where shared-screen multiplayer retains dominance. FCC equipment authorization for wireless controllers adds compliance overhead that favors established platform holders with dedicated testing labs.
- PC Components:Discrete GPUs, CPUs, and motherboards assembled into custom configurations. California's Silicon Valley and Austin's tech corridor concentrate enthusiast build activity where CUDA ecosystem familiarity and PCIe 5.0 forward-compatibility drive component selection. GPU supply volatility from Taiwan foundry partners compresses inventory planning windows for North American system integrators.
- Gaming Mice:Optical and laser sensor peripherals with adjustable DPI and mechanical switch configurations. Tournament organizers in Los Angeles now mandate sub-1ms polling rate certification for competitive play.
- VR Headsets:Pancake lens optics with eye-tracked foveated rendering capability. Standalone wireless units are displacing tethered PC-dependent systems as Meta and Sony shrink optical stack depth.
PC Components anchors the volume base while VR Headsets gains share at the steepest rate.
End User:
Professional and commercial use cases command pricing power through specification sensitivity that casual consumption cannot match, creating a bifurcated margin structure across the user base.
- Casual Gamers:Infrequent players prioritizing accessibility over technical performance. Mobile controller attachments and cloud streaming subscriptions capture this segment in price-sensitive geographies like the US Southeast and Midwest.
- Professional Gamers:Esports competitors with zero-tolerance latency requirements. Texas and California tournament circuits mandate standardized peripheral specifications that create certified equipment pull-through.
- Streamers:Content creators requiring broadcast-grade audio and video capture hardware. Los Angeles and Austin procurement runs through creator affiliate codes rather than traditional retail, elevating manufacturer customer acquisition costs.
- PC Builders:Enthusiast assemblers sourcing components across memory, cooling, and input categories. Integrated software control platforms like Corsair's iCUE sustain loyalty across upgrade cycles.
Professional Gamers extract the highest per-unit margins while Streamers expand the addressable accessory market most rapidly.
Distribution Channel:
Channel cost structures determine which price tiers can sustain profitability, with direct-to-consumer models disrupting traditional electronics retail through inventory efficiency advantages.
- Online Retail:Amazon and manufacturer direct storefronts with algorithmic recommendation engines. Creator affiliate codes now drive peripheral discovery, compressing distributor margins while elevating brand marketing spend.
- Electronics Stores:Best Buy and regional chains with hands-on display capacity. California and New York metro locations concentrate experiential purchase decisions for high-consideration VR systems.
- Specialty Shops:Micro Center and local PC component retailers with technical staff expertise. Austin and Boston corridors retain this channel for complex build consultations.
- Wholesale:B2B procurement for esports venue operators and tournament organizers. Toronto and Vancouver venue buildouts create bulk equipment demand without established supplier relationships.
Online Retail captures the dominant transaction volume while Specialty Shops defend the highest customer lifetime value through technical service attachment.
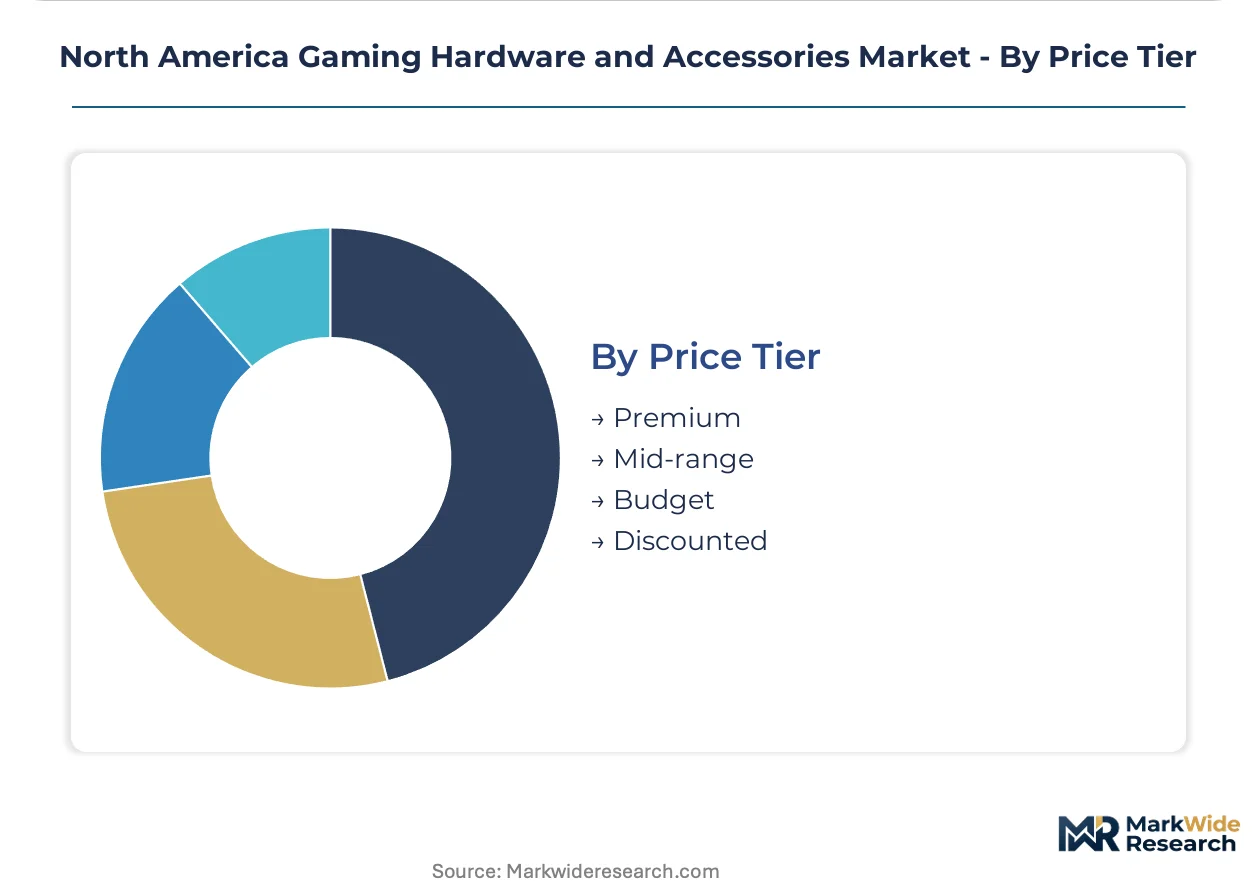
Price Tier:
Component cost transparency and review culture compress margin differentiation at the bottom of the stack while specification extremism protects premium positioning.
- Premium:Zero-latency specifications and limited-edition industrial design. Streamers and professional gamers in Los Angeles and Austin prioritize response fidelity over cost, sustaining 80 Plus Titanium power supply and optical mechanical switch premiums.
- Mid-range:Balanced performance-to-price ratios for enthusiast upgraders. This tier faces the strongest pressure from mobile gaming substitution and cloud streaming endpoint commoditization.
- Budget:Functional specifications meeting minimum competitive thresholds. Walmart and Amazon Basics private labels capture this segment in cost-conscious US regions.
- Discounted:Prior-generation clearance and refurbished equipment. Inventory liquidation from GPU generation transitions feeds this channel.
Premium commands disproportionate margin contribution while Mid-range faces the steepest share erosion from substitute technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Los Angeles-Long Beach port complex handles the bulk of Asian-manufactured gaming peripherals entering North America, while the Dallas-Fort Worth inland rail hub distributes components throughout the central corridor.
United States
California's Silicon Valley and Los Angeles corridor concentrate developer ecosystems and content creation studios driving GPU and peripheral demand. The FCC's Part 15 equipment authorization requirements for wireless peripherals continue tightening RF emission standards, elevating compliance costs. Austin and Boston metro areas host specialized electromagnetic simulation talent pools essential for RF shielding engineering.
Canada
Toronto and Vancouver esports venue buildouts generate bulk equipment procurement for tournament halls lacking purpose-built spectator infrastructure. Health Canada's pediatric VR session duration guidance diverges from FDA recommendations, complicating North American packaging localization. Montreal's gaming studios cluster drives peripheral testing and certification activity.
Mexico
Baja California and Chihuahua manufacturing zones assemble controller and headset components for re-export to US markets under USMCA tariff provisions. Mexico's telecommunications regulator IFETEL aligns equipment certification with FCC standards, streamlining cross-border product approvals. Guadalajara's emerging tech corridor attracts peripheral distribution center investments.
North America Gaming Hardware and Accessories Market Competitive Landscape
Listed leaders compete with private specialists across component integration and peripheral specialization dimensions. The vendor base fragments between semiconductor giants with foundry partnerships and focused peripheral makers with deep software ecosystems. Three archetypes dominate: integrated platform holders with console-hardware-software stacks, component specialists leveraging CUDA or equivalent ecosystems, and esports-grade peripheral purists with sub-millisecond latency specifications. Competitive moves center on strategic partnerships for foundry allocation and portfolio diversification into adjacent creator economy hardware.
Within the integrated platform tier, Microsoft Corporation and Sony Interactive Entertainment occupy positions spanning console hardware, cloud infrastructure, and first-party content. NVIDIA Corporation anchors the discrete GPU supply archetype through its CUDA ecosystem dominance in enthusiast PC builds. Razer Inc. and Corsair Gaming Inc. exemplify the esports-grade peripheral specialist model, with the former representing sub-1ms polling rate certification leadership and the latter anchoring integrated software control across component categories.
| Leading Market Players |
|---|
| Logitech International S.A. |
| Razer Inc. |
| Corsair Gaming Inc. |
| NVIDIA Corporation |
| Microsoft Corporation |
| Sony Interactive Entertainment |
| Alienware (Dell Technologies Inc.) |
| HyperX (HP Inc.) |
| Turtle Beach Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term foundry capacity reservation contracts with TSMC and Samsung lock in GPU wafer allocation while fixing cost visibility for North American system integrators facing volatile memory and substrate pricing cycles.
Pricing Analysis
Certification level creates the primary spread between FCC Part 15 Class B verified peripherals and uncertified imports, with RF testing overhead adding substantial fixed cost per SKU. Three-tier pricing structure across premium, standard, and economy levels reflects polling rate specifications and switch durability ratings. Pricing pressure stems from mobile controller attachments commoditizing entry-level peripheral demand. Casual gamers in the US Southeast exhibit highest price sensitivity, while professional esports competitors in Texas and California tolerate substantial premiums for sub-1ms latency specifications.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for discrete GPUs and high-performance DRAM, while Japan supplies ABF substrates essential for advanced packaging. Component sourcing draws from Chinese contract manufacturers for controller assembly and Mexican maquiladora operations for final headset integration. Single-source vulnerability concentrates in Taiwan foundry partners, where geopolitical friction threatens wafer allocation continuity. Distribution runs through the Los Angeles-Long Beach port complex for Asian imports, with Dallas-Fort Worth rail distribution penetrating central US markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as content creator procurement fragments across direct storefronts and affiliate channels, creating niche positioning space for specialized peripheral vendors.
For Market Incumbents: Consolidate software ecosystem control to defend against modular component challengers. Corsair's iCUE integration model demonstrates how cross-category control sustains upgrade cycle loyalty. Deepen backward integration into GaN power supply design to capture EPA Energy Star compliance margins. Prioritize RF engineering talent acquisition in Austin and Boston metro areas where electromagnetic simulation expertise concentrates.
For New Entrants and Emerging Players: Tournament-grade peripheral certification services represent an underserved layer where incumbent testing infrastructure creates bottlenecks for smaller vendors. Canadian esports venue buildouts in Toronto and Vancouver offer penetrable bulk procurement without established supplier relationships. Creator economy affiliate platforms provide direct audience access that bypasses traditional distributor margin compression.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors peripheral specialists with embedded software platforms over pure hardware assemblers. Long-term viability centers on recurring revenue attachment through firmware and control software ecosystems. Acquisition targets should demonstrate eye-tracked foveated rendering integration capability or established FCC testing infrastructure. Watch for divergence between FDA and Health Canada VR session guidance as a signal for North American packaging complexity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Supply Redesign | Captures EPA Energy Star Version 8.0 compliance contracts from Microsoft and Sony console revisions. |
| Eye-Tracking Silicon Integration | Enables standalone VR headsets at console price points through foveated rendering load reduction. |
| RF Shielding Engineering Acquisition | Secures scarce electromagnetic simulation talent concentrated in Austin and Boston corridors. |
| Creator Affiliate Platform Launch | Bypasses distributor margin compression by accessing Los Angeles and Austin streamer procurement directly. |
| Canadian Venue Partnership | Establishes first-mover presence in Toronto and Vancouver tournament hall buildouts lacking supplier relationships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, EPA Energy Star certification filings, and foundry partner capacity disclosures. Conversations with esports tournament organizers, peripheral procurement leads at content creation studios, RF compliance engineers, and cloud gaming infrastructure architects informed demand-side assumptions. SEC 10-K filings from listed component vendors and customs import records through Los Angeles-Long Beach provided supply-side validation. Bottom-up SKU-level modeling triangulated against top-down category spend estimates.
Segmentation dimensions modeled include product type hierarchy, end-user professionalization tier, distribution channel cost structure, and price tier specification intensity. Volume and value outputs were derived through installed base growth projection and replacement cycle analysis across the projection horizon. GPU foundry allocation schedules, FCC certification queue lengths, and esports tournament formalization trajectories served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FCC Part 15 emission standards and EPA standby power mandates; material policy shifts would require re-modeling. Health Canada VR guidance divergence from FDA recommendations represents a specific risk factor that could revise North American packaging and firmware localization assumptions. Recalibration cycles align with material shifts in foundry capacity allocation, tournament infrastructure investment, and wireless spectrum regulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Gaming Chair Market
Gaming
MMORPG Gaming Market
Gaming
United States Virtual Reality Gaming Market
Gaming
Global Gaming Market
Gaming
Racing Games Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
Gaming Hardware Market
Gaming
3D Gaming Technology Market
Gaming
Europe Casino Gambling Market
Gaming
Gaming Gadgets Market
Gaming
Global Tarot Cards Market
Gaming
China Subscription-Based Gaming Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
Global 3D Gaming Console Market
Gaming
Asia-Pacific Video Game Software Market