
 FPS Game Market | 2026-2036
FPS Game Market Size, Share, and Industry Trends Forecast 2026-2036
FPS Game Market Insights
Asset-light publishing and revenue-sharing partnerships is rewriting capital requirements for FPS studios, allowing mid-sized developers to compete with established publishers. Epic Games leverages its Unreal Engine ecosystem to reduce production costs for partner studios while sustaining its own battle royale operations. Valve Corporation anchors PC distribution through Steam's marketplace dominance, competing on community features and mod support rather than exclusive content.
A first-person shooter is a video game genre rendered in three-dimensional perspective where the player experiences action through the eyes of a protagonist, typically employing projectile weapons with simulated ballistics, recoil patterns, and hit-scan or projectile-based damage models against AI or human opponents. The genre serves commercial entertainment, competitive sport, and social platform functions across consumer electronics. Platform segmentation shows PC and console maintaining premium monetization through pay-to-play and DLC models, while mobile free-to-play adoption widens audience reach with compressed session design. Game type segmentation reveals battle royale and tactical shooter variants capturing the largest concurrent player bases, whereas single-player campaigns retain concentrated spending from narrative-driven consumers.
China's MIIT enforces content approval and playtime restrictions on domestic releases, directly shaping product localization timelines and monetization architecture for publishers targeting that market. The ESRB in North America and PEGI in Europe classify violent content, determining retail access and platform policy enforcement across jurisdictions. Stakeholders must monitor evolving classification standards and cross-border data governance as cloud streaming dissolves geographic distribution boundaries.
Market Dynamics
Cloud streaming infrastructure is compressing hardware requirements for entry, fragmenting platform power while concentrating distribution control among infrastructure owners who gate access to player bases.
Growth Catalysts
- MIIT content approval frameworks:China's regulatory clarity creates predictable localization pathways for foreign publishers seeking domestic release windows.
- Battle royale format retention:Sustained player engagement in 100-player elimination modes drives cosmetic monetization velocity and seasonal pass adoption.
- Esports broadcast investment:Dedicated streaming rights deals from platforms like Twitch and YouTube Gaming convert viewership into acquisition funnels for new titles.
Market Restraints
- GPU supply volatility:Discrete graphics card pricing fluctuations directly constrain PC upgrade cycles that precede premium game purchases.
- Platform store concentration:Steam's marketplace dominance in PC distribution extracts 30% revenue shares that compress indie studio margins.
- Hit-scan latency physics:Network infrastructure limitations prevent competitive integrity in sub-20ms reaction scenarios across rural broadband deployments.
Strategic Opportunities
- India's underserved mobile-first audience:Compressed-session battle royale titles face limited domestic competition despite 500 million smartphone users.
- Cross-platform progression systems:Unified account infrastructure spanning console, PC, and mobile is unlocking lifetime value from fragmented device ownership.
- Generative AI voice synthesis:Procedural dialogue generation is reducing localization costs for narrative campaigns across 12+ language markets.
Industry Challenges
- Live-service engineering talent scarcity:Backend infrastructure expertise for million-concurrent-player architectures commands premium compensation that mid-sized studios cannot match.
- Anti-cheat arms race costs:Kernel-level detection systems require continuous R&D investment to maintain competitive integrity against evolving exploit markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FPS Game Market |
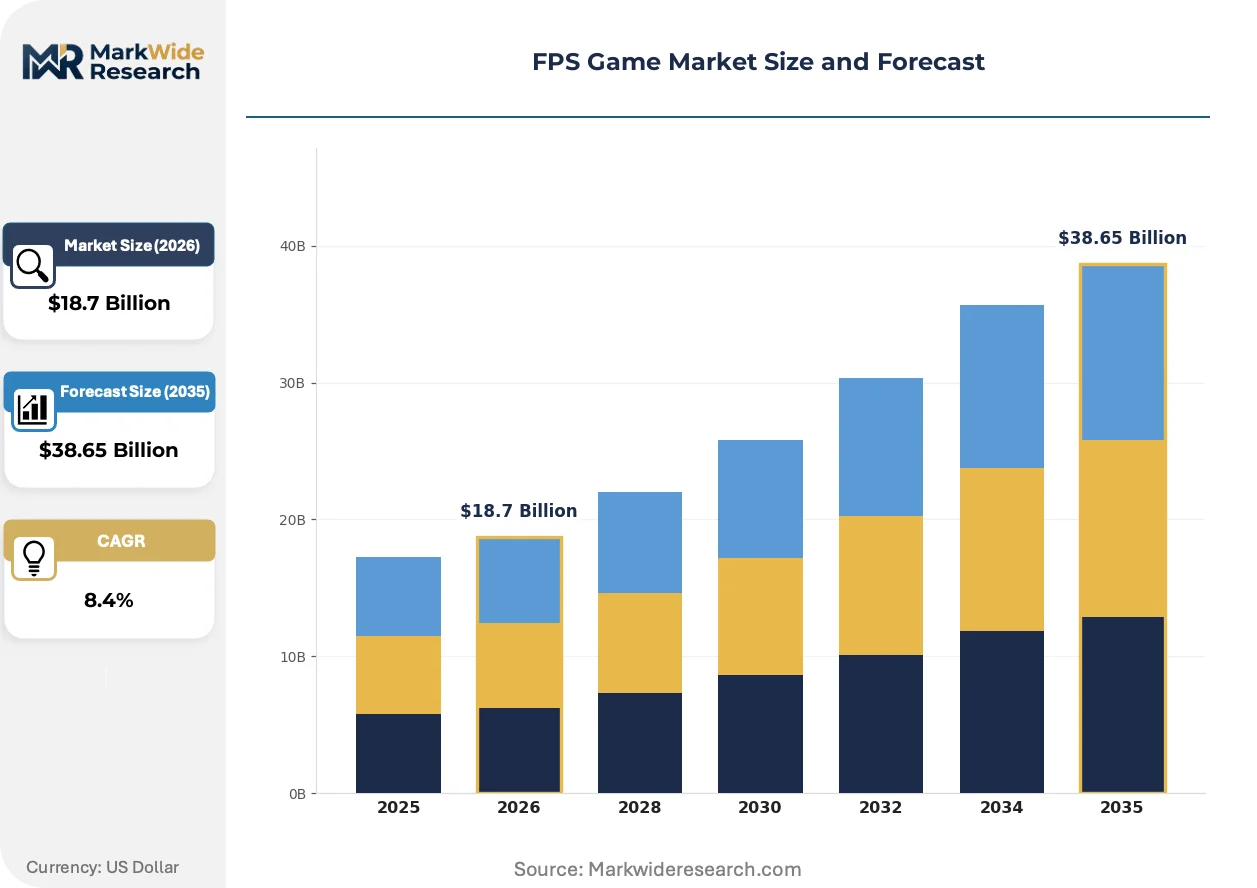
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform: PC, Console, Mobile, Cloud Gaming Game Type: Single-player, Multiplayer, Battle Royale, Tactical Shooter Distribution Model: Free-to-Play, Pay-to-Play, Subscription-based, DLC Target Audience: Casual Gamers, Competitive Players, Streamers, Esports Professionals |
| Companies Covered | Epic Games, Activision Blizzard, Valve Corporation, NetEase, Take-Two Interactive, Electronic Arts, Ubisoft Entertainment, Riot Games, Tencent Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FPS Game Market Trends and Innovations
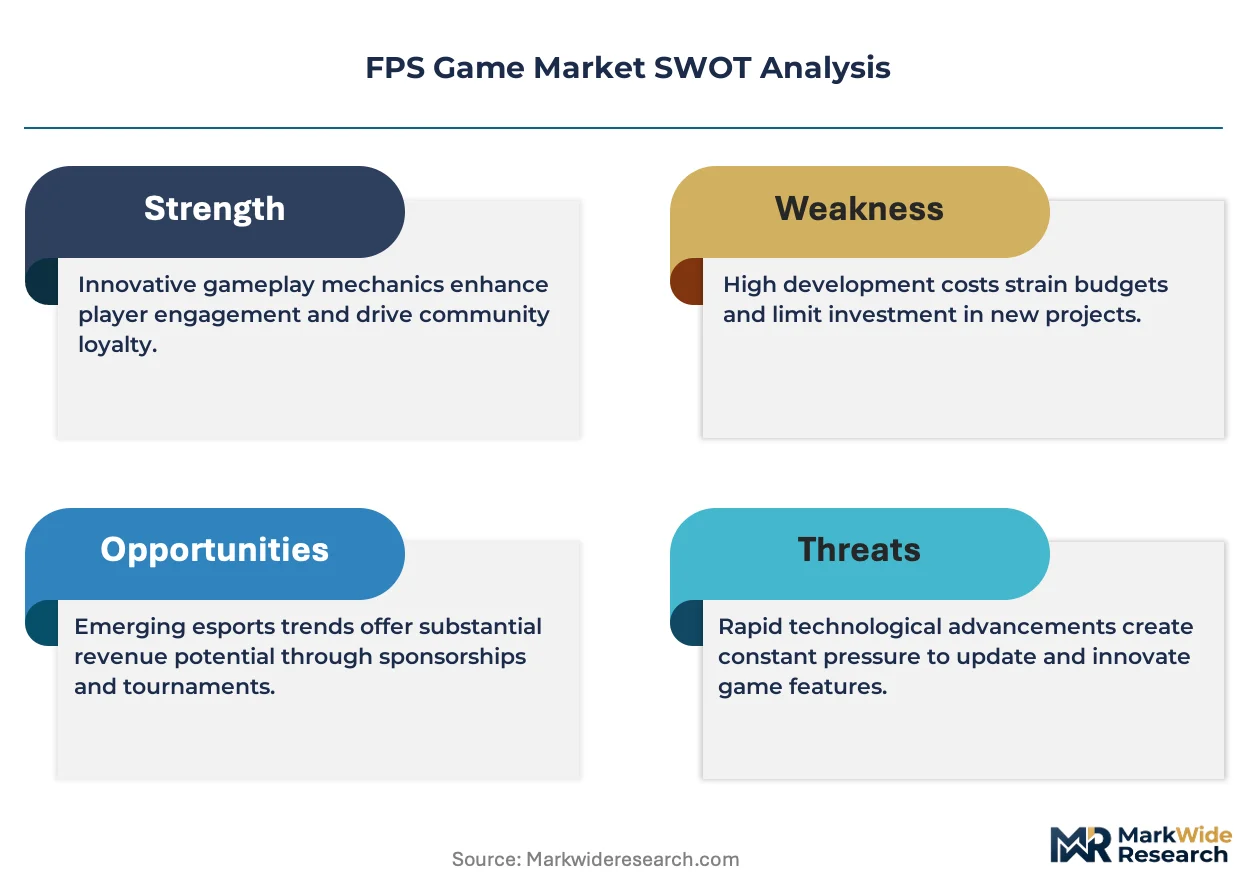
Real-time rendering pipelines and AI-assisted content generation are compressing production timelines while elevating player expectations for visual fidelity and environmental responsiveness.
Neural network-based upscaling technologies like DLSS and FSR are rendering obsolete the hardware upgrade cycles that previously gated access to high-fidelity experiences. Mid-tier GPU owners now access frame rates previously exclusive to flagship silicon. This compression is extending viable hardware lifecycles and fragmenting the premium upgrade market.
China's MIIT playtime restrictions for minors are mandating identity verification infrastructure that increases compliance costs for all publishers targeting domestic release. Titles must integrate real-name authentication and session-limiting systems. Western studios are responding by architecting separate build branches with region-locked feature sets.
Subscription bundling through services like Game Pass is displacing unit-sales forecasting as the dominant revenue model for single-player campaigns. Studios now optimize for engagement metrics that trigger platform payout thresholds rather than front-loaded purchase conversion. This shift is most visible in North American and European markets where subscription penetration exceeds 40% of console households.
FPS Game Market Segmentation
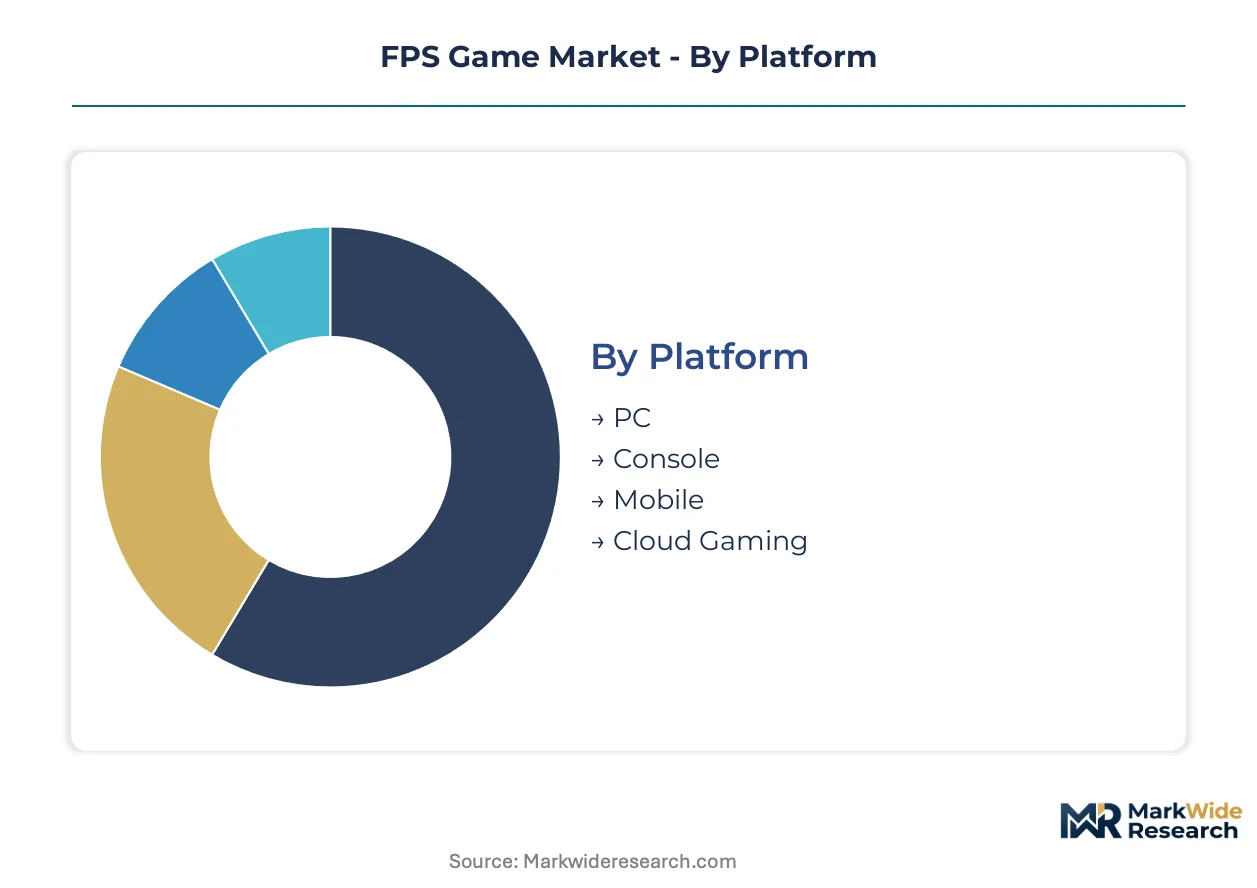
Platform fragmentation and monetization model diversity create distinct competitive arenas within the FPS landscape. Each segmentation axis reveals divergent margin structures, customer acquisition costs, and lifecycle value trajectories that shape studio resource allocation.
Platform:
Mature hardware ecosystems coexist with emerging cloud infrastructure, creating tiered entry barriers and monetization ceilings across the access spectrum.
- PC:Discrete GPU requirements sustain premium pricing power for AAA releases. Steam's marketplace dominance in distribution extracts substantial revenue shares while modding communities extend title longevity through user-generated content pipelines.
- Console:Closed hardware generations synchronize upgrade cycles with blockbuster release calendars. Sony and Microsoft platform fees compress margins but deliver standardized performance targets that reduce QA complexity for cross-platform development.
- Mobile:Touch control schemes demand interface redesigns that sacrifice precision for accessibility. China's 500 million smartphone users concentrate demand for compressed-session battle royale formats despite hardware thermal constraints.
- Cloud Gaming:Latency physics limits competitive integrity in sub-20ms reaction scenarios. Infrastructure owners gate access to player bases while dissolving geographic distribution boundaries for publishers.
PC retains volume leadership among premium spenders; Cloud Gaming holds the steepest expansion curve as fiber broadband penetration deepens.
Game Type:
Social engagement mechanics versus narrative immersion define divergent production budgets and post-launch service commitments.
- Battle Royale:Hundred-player elimination modes sustain cosmetic monetization velocity through seasonal pass architectures. Epic Games' Unreal Engine ecosystem reduces production costs for partner studios competing in this format.
- Tactical Shooter:Round-based elimination with permadeath mechanics demands precise hit registration and anti-cheat infrastructure. Kernel-level detection systems require continuous R&D investment to maintain competitive integrity against evolving exploit markets.
- Multiplayer:Persistent progression systems across team-based modes anchor daily active user metrics. Cross-platform account unification unlocks lifetime value from fragmented device ownership patterns.
- Single-player:Cinematic campaigns face displacement by subscription bundling through services like Game Pass. Studios optimize for engagement thresholds triggering platform payouts rather than front-loaded purchase conversion.
Battle Royale commands concurrent player peaks; Tactical Shooter demonstrates the most durable monetization per hour played.
Distribution Model:
Revenue recognition timing and customer relationship depth vary dramatically across upfront and recurring payment architectures.
- Free-to-Play:Zero entry price widens funnel tops while battle pass and cosmetic microtransactions fund live service operations. Mobile adoption concentrates this model in China and India where disposable income for upfront purchases remains limited.
- Subscription-based:Game Pass and comparable services displace unit-sales forecasting for narrative-driven studios. Payout thresholds tied to engagement hours reshape content design toward extended play sessions.
- Pay-to-Play:Upfront purchase models retain dominance in premium PC and console segments where $60-$70 price points signal production value. GPU supply volatility directly constrains upgrade cycles that precede these purchases.
- DLC:Post-launch content packs extend revenue windows for established player bases. Map packs and expansion campaigns require sustained server infrastructure that mid-sized studios struggle to maintain.
Free-to-Play captures the widest audience footprint; Subscription-based is climbing the fastest as platform penetration exceeds 40% of console households in North American and European markets.
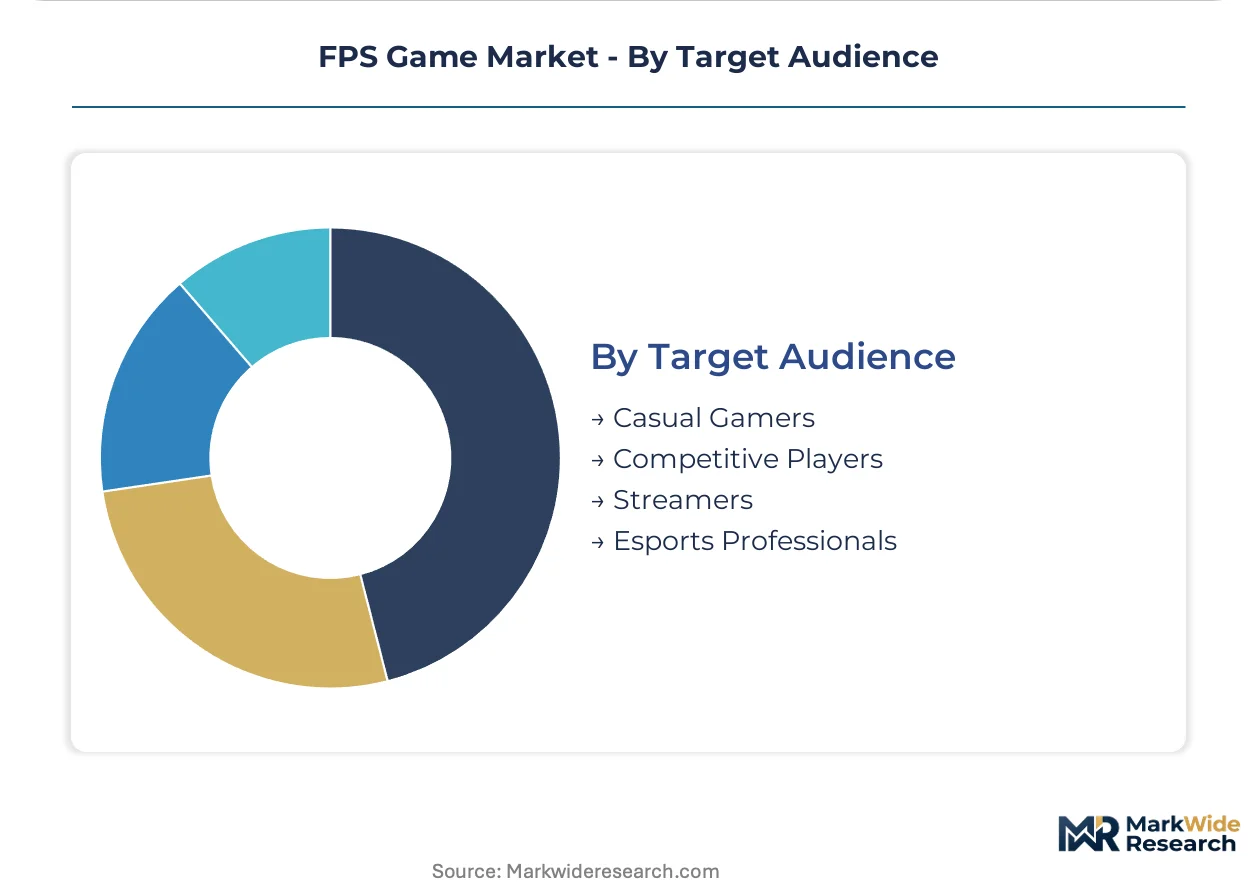
Target Audience:
Skill investment thresholds and social visibility motives segment players into distinct monetization responsiveness profiles.
- Competitive Players:Ranked ladder systems and tournament infrastructure demand sub-20ms latency guarantees. Esports broadcast investment from Twitch and YouTube Gaming converts viewership into acquisition funnels.
- Casual Gamers:Compressed session design accommodates intermittent play patterns on mobile hardware. Progression systems emphasize unlock velocity over skill mastery to sustain retention.
- Esports Professionals:Sponsored team structures and prize pool economics concentrate in China where NetEase and Tencent operate dominant distribution platforms. Career longevity depends on title stability and developer commitment to competitive balance.
- Streamers:Content creators drive organic discovery through live broadcast audiences. Cosmetic item visibility in gameplay footage generates demand velocity for limited-release skins.
Competitive Players generate the highest per-capita spending; Casual Gamers represent the largest addressable population expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT content approval frameworks in China create predictable localization pathways that foreign publishers exploit to access the world's largest gaming population. Brazil's ANVISA-equivalent content classification system and India's BIS-aligned digital infrastructure standards shape parallel entry strategies for emerging market penetration.
United States
ESRB classification standards determine retail access and platform policy enforcement for violent content across console and PC distribution. The FTC monitors loot box mechanics and youth-targeted monetization practices under consumer protection mandates. Seattle and Los Angeles anchor development clusters where Epic Games and Riot Games operate flagship studios producing Unreal Engine-powered titles.
China
NetEase and Tencent distribution platforms concentrate demand from 500 million smartphone users demanding compressed-session battle royale formats. MIIT enforces real-name authentication and session-limiting systems for minors that increase compliance costs for foreign publishers. Shanghai and Shenzhen development hubs generate region-locked build branches with localized monetization architectures.
Germany
KBA-aligned USK ratings classify violent content with stricter thresholds than PEGI neighbors, affecting title availability on Steam and console storefronts. The country's national media regulator enforces NetzDG compliance for user-generated content in multiplayer environments. Hamburg and Munich host middleware specialists supplying anti-cheat and networking infrastructure to European publishers.
South Korea
MFDS-equivalent content grading and Game Rating and Administration Committee standards govern domestic release windows for competitive shooters. The national esports association channels broadcast investment into dedicated streaming rights deals. Seoul's Pangyo Techno Valley concentrates live-service engineering talent commanding premium compensation for million-concurrent-player architectures.
Brazil
ANVISA-equivalent content classification and Receita Federal import tariffs shape console hardware pricing that precedes premium game purchases. The central bank's PIX instant payment infrastructure accelerates mobile free-to-play microtransaction velocity. São Paulo development studios localize Portuguese-language voice synthesis through generative AI partnerships reducing narrative campaign costs.
FPS Game Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented platform ecosystems where distribution ownership determines revenue capture. Steam's marketplace dominance extracts substantial shares from PC releases while console manufacturers gate access through closed hardware generations. Three archetypes populate this structure: engine-ecosystem owners leveraging tool licensing to subsidize first-party operations, platform-holding distributors competing on community features rather than exclusive content, and live-service specialists commanding premium engineering talent for anti-cheat and backend infrastructure. Competitive moves concentrate on cross-platform progression systems and subscription bundling displacing unit-sales forecasting.
Within the engine-ecosystem tier, Epic Games represents the vertically integrated model combining Unreal Engine licensing with battle royale operations. Valve Corporation exemplifies platform-holding distribution anchored through Steam's community features and mod support infrastructure. Tencent Holdings occupies a position spanning domestic distribution dominance and minority stakes in Western studios seeking China release pathways.
| Leading Market Players |
|---|
| Epic Games |
| Activision Blizzard |
| Valve Corporation |
| NetEase |
| Take-Two Interactive |
| Electronic Arts |
| Ubisoft Entertainment |
| Riot Games |
| Tencent Holdings |
| Others |
Pricing and Supply Chain Analysis
MIIT content approval bottlenecks in China constitute the dominant regulatory chokepoint determining both tiered pricing spreads and supply chain architecture for foreign publishers. This single-source dependency forces studios to maintain parallel build branches with region-locked compliance infrastructure, compressing margins on domestic releases while elevating premium pricing for uncensored international versions.
Pricing Analysis
Platform certification level creates the primary spread between premium and standard tiers, with console first-party approvals and Steam Direct compliance anchoring distinct price bands. Subscription bundling through Game Pass and comparable services is displacing unit-sales forecasting, intensifying cost compression for narrative-driven studios optimizing engagement thresholds over front-loaded purchase conversion. Mobile free-to-play adoption in India and Southeast Asia demonstrates acute price sensitivity, whereas PC discrete GPU owners retain tolerance for premium pricing.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers are restructuring working capital requirements for live-service operators. Engine licensing revenue from Unreal Engine and proprietary toolchains draws from North American and European development hubs, while anti-cheat middleware and networking stack development centers on South Korea and Germany. Single-source vulnerability concentrates in China's real-name authentication infrastructure, which all publishers targeting domestic release must integrate. Distribution runs through platform-holding gatekeepers—Steam, PlayStation Network, Xbox Live, and Tencent's WeGame—each extracting substantial revenue shares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battle royale fatigue and emerging immersive platform substitutes threaten incumbent positioning, requiring active substitution defense through format innovation and cross-platform retention mechanics.
For Market Incumbents: Pre-empt platform fragmentation by unifying progression systems across console, PC, and mobile before subscription bundling fully displaces unit-sales forecasting. Invest in kernel-level anti-cheat R&D to defend competitive integrity against exploit markets eroding player trust. Backward integration into cloud streaming infrastructure reduces dependency on third-party latency guarantees. For New Entrants and Emerging Players: India's 500 million smartphone users present the most penetrable geography for compressed-session battle royale titles facing limited domestic competition. Target Brazil's PIX-accelerated microtransaction infrastructure for mobile free-to-play velocity. License Unreal Engine ecosystem tools to compress production timelines and reduce capital requirements. For Investors and Strategic Acquirers: China's evolving MIIT enforcement posture reshapes the acquisition landscape, with foreign publishers seeking domestic distribution partners commanding premium valuations. Live-service engineering talent scarcity in million-concurrent-player architectures defines the viable target archetype. Monitor anti-cheat arms race R&D intensity as the signal for competitive sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Platform Progression Unification | Steam, PlayStation Network, and Xbox Live integration unlocks lifetime value from fragmented device ownership. |
| Cloud Streaming Infrastructure Partnership | Microsoft Azure and Amazon Web Services latency guarantees expand addressable markets beyond hardware-constrained users. |
| Generative AI Localization Pipeline | Procedural voice synthesis reduces narrative campaign costs across 12+ language markets. |
| Esports Broadcast Rights Acquisition | Twitch and YouTube Gaming streaming deals convert viewership into acquisition funnels for new titles. |
| Anti-Cheat Technology Investment | Kernel-level detection systems defend competitive integrity against evolving exploit markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, platform holder earnings disclosures, and regional regulatory filings. Interviews with live-service engineering directors, platform partnership leads, esports broadcast executives, and anti-cheat middleware specialists inform demand-side validation. Customs data on console hardware imports, Steam concurrent player statistics, and mobile app store revenue estimates provide supply-side triangulation through bottom-up and top-down reconciliation.
Forecast inputs span platform segmentation, game type classification, distribution model architecture, and target audience monetization profiles across the projection horizon. CAGRs derive from trend extrapolation of player base expansion, session frequency elasticity, and cosmetic monetization velocity. GPU supply cycles, broadband penetration curves, and MIIT approval throughput anchor industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in disposable income trajectories, semiconductor availability, or cross-border data governance would shift the trajectory. Forecasts reflect documented assumptions; regulatory enforcement intensity, platform fee restructuring, or generative AI disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Battle Royale Games Market
Gaming
United States Gaming Accessories Market
Gaming
VR Gaming Console Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Game Engine Management Market
Gaming
Connected Game Console Market
Gaming
Casino Gaming Equipment Market
Gaming
Latin America Gaming Headsets Market
Gaming
Mobile and Handheld Gaming Market
Gaming
Gaming Chair Market
Gaming
Mobile Gaming Market
Gaming
Global NFT Gaming Market
Gaming
Singapore Gaming Gadgets Market
Gaming
Russia in-Game Advertising Market
Gaming
South Korea Gaming Peripherals Market
Gaming
Latin America Mobile Gaming Market